Silicon Motion Technology Corporation
Q3 FY2026 · Earnings Call TranscriptOctober 29, 2026
Operator
Good day, and thank you for standing by. Welcome to Silicon Motion Technology Corporation's third quarter 2026 earnings conference call.
At this time, all participants are in listen-only mode. After the speakers' presentation, there will be a question-and-answer session.
At which time, if you wish to ask a question, you will need to press star 1 1 on your telephone keypad. Please be advised that today's conference is being recorded.
This conference call contains forward-looking statements within the meaning of Section 27A of the Securities Act of 1933 and Section 21E of the Securities Exchange Act of 1934, as amended. Such forward-looking statements include, without limitation, statements regarding trends in the semiconductor industry and our future results of operations, financial condition, and business prospects.
Although such statements are based on our own information and information from other sources we believe to be reliable, you should not place undue reliance on them. These statements involve risks and uncertainties, and actual market trends and our results may differ materially from those expressed or implied in this forward-looking statements for a variety of reasons.
Potential risks and uncertainties include, but are not limited to, continued competitive pressure in the semiconductor industry and the effect of such pressure on prices, unpredictable changes in technology and consumer demand for multimedia consumer electronics, the state of and any change in our relationship with our major customers, and changes in political, economic, legal, and social conditions in Taiwan. For additional discussion of these risks and uncertainties and other factors, please see the documents we file from time to time with the Securities and Exchange Commission.
We assume no obligation to update any forward-looking statements, which apply only as of the date of this conference call. With that, I'll now hand you over to Mr.
Tom Sepenzis, Vice President of Investor Relations and Strategy. Please go ahead.
Tom Sepenzis
Good morning, everyone, and welcome to Silicon Motion's third quarter 2026 financial results conference call and webcast. Joining me today is Wallace Kou, our President and CEO, and Jason Tsai, our CFO.
Wallace will first provide a review of our key business developments, and then Jason will discuss our third quarter results and outlook. Following our prepared remarks, we will conclude with a Q&A session.
Before we begin, I would like to remind you of our safe harbor policy, which was read at the start of this call. For a comprehensive overview of the risks involved in investing in our securities, please refer to our filings with the US Securities and Exchange Commission.
For more details on our financial results, please refer to our press release, which was filed on Form 6-K after the close of the market yesterday. This webcast will be available for replay in the Investor Relations section of our website for a limited time.
To enhance investors' understanding of our ongoing economic performance, we will discuss non-GAAP information during this call. We use non-GAAP financial measures internally to evaluate and manage our operations.
We have therefore chosen to provide this information to enable you to perform comparisons of our operating results in a manner consistent with how we analyze our own operating results. The reconciliation of the GAAP to non-GAAP financial data can be found in our earnings release issued yesterday.
We ask that you review it in conjunction with this call. With that, I will turn the call over to Wallace.
Wallace Kou
Thank you, Tom. Hello, thank you for joining us the call today.
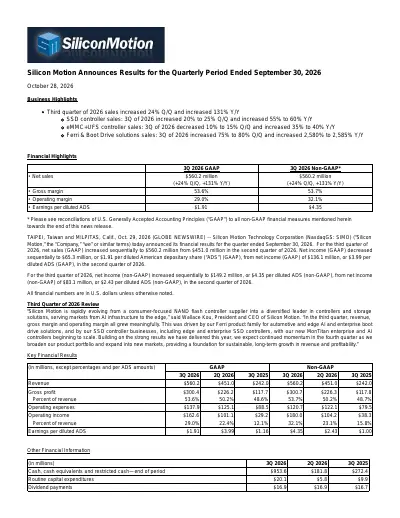
I'm pleased to report that we delivered another quarter of strong growth with revenue of $560 million and gross margin of 53.7%, driven by the growth in Ferri for automotive, edge AI, and boot drive storage, our edge SSD business, and our emerging MonTitan controller for enterprise SSD. We drove another quarter of higher operational performance, delivering the second consecutive quarter of record earning per ADS as we continue to capitalize on our product and market diversification strategy.
We are on track to deliver record revenue in 2026 with over 100% top-line growth. Our strategy is simple: deliver real value to customers and focus where we are uniquely differentiated so we can generate strong ROI for shareholders.
For our edge controllers, we have become the de facto standard for mobile, IoT, and PC controller solutions. For NAND makers and virtually every module maker is outsourcing, become a much more meaningful portion of the market.
Our unmatched controller technology and design expertise deliver solutions that are better performing, consume less power, and are more cost-efficient than either in-house or other merchant solutions. Our strong share gains are driving significant growth despite end-market weakness, and we expect this to continue.
Our MonTitan enterprise SSD controller are winning across the ecosystem with leading NAND makers, hyperscalers, and CSPs, and with module makers that supply AI server to hyperscale and enterprise customers. Our success is based on our unique combination of two decades of controller and firmware design experience and our history of managing more NAND than anyone in the industry.
This has created an incredibly solid foundation for our leading enterprise controller products, and we expect our MonTitan revenue ramp to accelerate as we introduce our next-generation PCIe Gen 6 controller next year. Lastly, for our storage solution segment, our strategy has always been to focus in areas that are underserved by NAND makers, and we are rapidly growing share in these lighter low-density, smaller-volume market that require more design and customization work.
We have spent more than a decade building one of the industry's broadest automotive-grade portfolio, supported by dedicated quality and supporting team. Today, that foundation position us to capture fast-growing compute and storage demand across cars, drones, and increasingly robotics.
For our enterprise boot drive solution, our unique combination of broad controller platforms, best-in-class firmware, technical know-how, NAND supply relationship, and manufacturing capability put us in an ideal position to serve the growing need of the AI infrastructure market. As a result, we are rapidly evolving to much more balanced and profitable company as the new enterprise and AI product enhance our leading consumer controller share, strengthening our competitive position from AI infrastructure to the edge to deliver long-term sustainable revenue and earning growth.
I would like to take a moment to address the current market environment. The AI supercycle has driven robust demand of HBM, DRAMs, NAND, HDDs for the past several quarters with no sign of slowing down.
Prices have risen sharply over the past year, and the strained substrate supply across memory and storage. Enterprise market remains relatively insensitive to price, but the PC, smartphone, and other consumer device OEMs are struggling to bring affordable product to market given today's memory and storage cost, and consumer unit volume are declining as a result.
We expect condition to stay difficult until bit supply come back into balance with demand. New NAND fabs are planned for 2028, and NAND makers continue to add bit through higher layer count, but we do not see this changing the current supply-demand imbalance to any great degree.
Flash makers continue to prioritize enterprise and high-capacity solution, creating new and expanding opportunity for Silicon Motion. Our growth is benefiting from more outsourcing and larger opportunity in enterprise and the storage solution market that we are uniquely positioned to win.
We are at the beginning of the journey in the enterprise and AI market, and our early success will drive accelerating demand for our next-generation storage technologies. Let me now detail our embedded eMMC and UFS business, which include controller for smartphone, IoT connected devices.
Our eMMC UFS business was up over 100% year-over-year in the first half of 2026 as the NAND makers are shifting their resources toward DRAM and HBM solutions, allowing module makers to take share in the mobile market. This has helped drive our market share gains as module makers look to third-party controller partner to make their mobile solution.
In the third quarter, eMMC and UFS revenue declined modestly from the prior quarter, reflecting customer launch timing and the challenging smartphone OEMs face in offering affordable device amid the higher NAND and DRAM prices. We expect headwind to persist in the near to mid-terms until additionally memory and storage supply comes online.
Across the markets that we sell our eMMC UFS controller, OEMs are reducing specification to try to offset the rising memory and storage cost. We expect our eMMC UFS business to remain relatively flat in the near term given the current market challenging, but do believe we can return to growth next year and beyond as our new UFS 4.1 controller and UFS 5 controller ramp and driving higher ASPs.
Now turning to our SSD controller business, which include edge and MonTitan enterprise SSD controllers. This business delivered strong sequential and year-over-year growth.
In edge SSD, our PCIe Gen 5 investment continue to pay off. With growth in both our four-channel and eight-channel controllers, PCIe Gen 5 currently represent approximately 10% of the PC market, and we expect this will grow to 20% to 25% of the market by the end of 2027, providing a strong runway for further growth.
Our leading position PCIe Gen 5 is driving greater market share gains within the PC market. As the industry transition from PCIe Gen 4 to PCIe Gen 5, we expect to see further top-line improvement given the higher ASP associated with these next-generation products.
We are currently working with all the major NAND makers and most of the leading module makers to deliver compelling SSD solution that leverage PCIe Gen 4 and PCIe Gen 5 controllers. We are tracking well ahead of expectation to achieve our market share goals of 40%, excluding Apple, by 2028, and believe we will continue to improve our position.
While PC unit headwind associated with higher memory and storage prices present challengings, we believe we will drive further top-line growth through the market share gains and ASP increases as the market shift to PCIe Gen 5 continue. I would now like to provide you with an update on our new MonTitan enterprise SSD business.
NAND remain critically important technology across enterprise and AI storage ecosystem, and MonTitan is positioned for rapid growth in the coming years. These eSSD solutions deliver high-speed, low-latency storage that target compute and data storage application for enterprise AI platforms.
Our first two customers begin shipping TLC eSSD for compute that leverage our MonTitan controller in the second quarter, and all seven of our announced customer are on track to begin commercial ramp in 2026 with both TLC-based compute and QLC-based data storage products. TLC-based compute eSSD using MonTitan are expected to grow more quickly than QLC-based data storage eSSD in the near term until greater supply of 2-terabit die become available.
Encouragingly, four of our six NAND makers have started production of 2-terabit QLC die today, and we expect all NAND maker to begin shipping 2-terabit QLC by end of the 2027, momentum will accelerate throughout next year. During the third quarter, we taped out next-generation 4-nanometer PCIe Gen 6 MonTitan controller targeting hyperscaler and CSP, expect to begin sampling in the first quarter of 2027.
We have won design with multiple Tier 1 customer including NAND flash makers, hyperscalers, and CSPs. The new controller was designed for both compute application using TLC and data storage using QLC NAND as a performance-shaping and multiple-agent server architecture extremely well-suited for agentic AI infrastructure.
We continue to see increased inbound interest in our MonTitan controllers, and expect this new enterprise controller segment will help us deliver long-term sustainable top- and bottom-line growth. Finally, I would like to provide an update on our Ferri for automotive, edge, and enterprise boot drive storage business.
Our solution business, which include Ferri and boot drives, delivered the strongest result in the third quarter with revenue up over 75% sequentially, representing over 40% of our revenue. Our automotive business has been a particularly source of strength, delivering better-than-expected top-line results and higher gross margins.
We continue to scale this business quickly as we know automotive market, its customers, and the supply chain extremely well, which has driven significant backlog for long-term growth as we accelerate our share gains. We have spent more than a decade developing our automotive products and certifications.
Today, our storage controller and firmware offer the broadest portfolio of solution to serve every part of the automotive market. Our success in automotive has drawn interest in Ferri for other fast-growing markets, including robotics, drones, and advanced networking.
In the emerging robotic market, we are actively engaged with several companies that want to use our storage products. We see multiple opportunity in humanoid robots and other physical AI systems, including vision, lidar, and compute storage.
Our early conversation suggest robotic opportunity may be larger than automotive, and we believe Ferri is ideally suited to address it. Our fast-growing boot drive business also gaining momentum.
We estimate that the market will be approximately $3 billion in 2026, growing to over $5 billion by 2030. In the third quarter, we won design with several new Tier 1 customer for networking and AI infrastructure products.
These program are expected to ramp over the next two years and will substantially improve our backlog visibility. As the average capacity of enterprise boot drives is much smaller than compute and data storage SSD drives, the NAND maker are no longer prioritize this market.
Additionally, our DRAM-less controller deliver the performance, reliability, and endurance this drive need with lower power consumption requirement, smaller form factor, and the lower cost than DRAM-based design. Boot drive handles the operation system, logging, and system management rather than heavy data workload, they don't need the expense of on-board DRAM for DPU, router, and switch products.
As AI infrastructure buildout add large numbers of servers, the networking and DPU equipment shipment are increasing rapidly, each needing reliable boot storage, driving the growing demand for DRAM-less boot drives. We have been the primary supplier for DRAM-less boot drive controllers to the NAND maker that have historically served this market, but as they are moving on the higher-density opportunity, Silicon Motion is uniquely positioned with the right technology, the right support, the leading security firmware, and proven ability to procure NAND, making us the best partner for those needing a boot drive solution.
Looking ahead, however, we are seeing significant new opportunity for boot drive with on-board DRAM. Driven the strong demand of AI inference and agentic AI, near-CPU boot drive with DRAM provide lower latency and open compute project features that are increasingly high demand.
As the NAND maker have shift the resources toward HBM, DRAM, and higher-capacity compute and data storage SSD, there is a growing shortage of near-CPU boot drives with DRAM. We estimate that this market will reach over $10 billion by 2030, making it a significant new opportunity for Silicon Motion.
We are already in discussion with multiple potential customer for boot drives that leverage our industry-leading eight-channel and PCIe Gen 5 controller that can serve the near-CPU market to further expand our market opportunity, and expect to begin ramping product for this market in the second half of 2027. Our Ferri for automotive, edge AI, and boot drive solution business are performing especially exceptional well, and these are many large and growing opportunity for our product in the segment.
Our backlog has increased significantly in just the past three months, and we expect many additional customer design wins in automotive, edge AI, and boot drive solution to deliver significant future growth. We continue to benefit from our proven ability to secure NAND in a difficult environment from multiple NAND suppliers, and this continue to be a powerful differentiator for our company.
In conclusion, Silicon Motion delivered its fourth consecutive quarter of record revenue as we executed across a rapidly diversifying business. We are fundamentally stronger company today with our strongest balance sheet, broadest range of solution and product, and more opportunity ahead than at any time in our history.
Our broad portfolio serve surging AI demand from the data center to the edge. That breadth give us balance across our market and the flexibility to seize growing opportunity while navigating challenge like those we face today in PC and smartphones.
I am extremely proud of our teams. Together, we have built a durable, diversified business powered by best-in-class technology, expanding share, and new end markets, strengthens by two decade of relationship with OEMs, module makers, and NAND makers.
I'm more confident than ever that we will continue to deliver broad-based sustainable growth long term. Now let me turn the call to Jason to go over our financial performance and outlook.
Jason Tsai
Thank you, Wallace, and good morning to everyone joining us today. I will discuss additional details of our third quarter results and then provide our outlook.
Please note that my comments today will focus primarily on our non-GAAP results unless otherwise specifically noted. A reconciliation of GAAP to non-GAAP data is included with our earnings release issued yesterday.
Before I get into the results, I'd like to comment briefly on our convertible bond issuance on August 13. We raised an aggregate $1.15 billion with net proceeds to the company of $1.127 billion.
This successful raise was increased from the initial offering of $800 million. This new CB at 0% interest and an initial conversion price of $380.50 represents a conversion premium of 65% over the last reported sale price of SIMO on August 10, the day the deal was announced.
This additional capital significantly strengthens our balance sheet and will help fuel our growth and enhance our working capital to scale our business. Now turning to our results.
We delivered an outstanding third quarter, surpassing our expectations, driven by stronger execution and demand trends. In the September quarter, sales increased 24% sequentially and 131% year-on-year to $560 million, coming in well above the high end of our guided range of $519 to $541 million, delivering our fourth consecutive quarter of record revenue.
We experienced strong growth across most of our businesses in the third quarter with standout growth in Ferri for automotive, enterprise boot drives, and SSD controllers including edge and MonTitan for enterprise. Gross margins of 53.7% was significantly better than guidance as we capitalize on new product introductions and benefited from better mix and better-than-expected margins in our Ferri automotive products.
Operating expenses slightly decreased sequentially to $120.7 million, and operating margin increased 32.1%, well exceeding our guidance, driven by higher-than-expected revenue and gross margin in the quarter. Earnings per ADS was $4.35, a 79% increase sequentially and a 333% increase compared to the same quarter last year.
Total stock-based compensation, which we exclude from non-GAAP results, was $17.3 million in the September quarter. We had $953.6 million in cash, cash equivalents, and restricted cash at the end of the third quarter compared to $181.8 million at the end of the second quarter.
Cash increased in the third quarter due to the successful $1.15 billion convertible notes offering that we executed in the quarter, offset by the increase in working capital, dividend payment, and the repayment of the short-term bank loan. Our strategy, as Wallace outlined at the start of this call, continues to drive growth and expand our opportunities.
Our experience, our customers and partners, and our unmatched technology and development of NAND controllers and solutions has driven a significant transformation of the company. While the NAND market continues to be dynamic, our investments across consumer, enterprise, data center, and AI applications are the foundation of our rapidly growing business.
As a result, we believe the momentum in our business will continue in the fourth quarter and now expect revenue to grow 5% to 10% sequentially to $588 to $616 million with growth across nearly all our product segments led by Ferri for automotive, enterprise boot drive solutions, and MonTitan enterprise SSD controllers. We believe our SSD controller business will be flat to slightly down given the current memory and storage environment and typical seasonality.
Gross margins are expected to increase sequentially to 54% to 55% in the December quarter given the continuing improvement in product mix. Operating margin is expected to grow to 36% to 37% as continued strong revenue growth and higher profitability drives leverage to the bottom line.
Our effective tax rate is expected to be 20%, and stock-based comp and dispute-related expenses are expected to be in the range of $34.6 to $35.6 million. 2026 is on track to deliver record revenue for Silicon Motion with top line expected to more than double year-over-year.
While we continue to invest heavily in R&D this year to expand our portfolio of leading-edge solutions, we are confident that along with the higher revenue and improved gross profitability, our operating margins will exceed 30% exiting this year. We expect this momentum to carry into 2027.
Our strong backlog across all of our businesses gives us confidence that we can grow revenue by at least 40% next year with gross profitability to be in the low- to mid-50% range. Our mix is improving.
With more contribution from enterprise controllers and Ferri automotive solutions, we should be able to sustain this higher margin level. It's also worth emphasizing that these new enterprise opportunities represent larger addressable markets than our consumer segments, and because they are greenfield opportunities for Silicon Motion, we can grow significantly by gaining share without depending on further market growth.
Any market expansion would only add to our potential upside. We set out to diversify beyond consumer applications into automotive and enterprise, and that strategy is now producing outsized results.
Our long-standing leadership in merchant controllers and our multi-year investments in enterprise and AI SSDs are beginning to bear fruit. The solutions we are winning in these markets offer far greater visibility, much longer product cycles, and significantly higher barriers to entry, which together underpin sustained growth in revenue and profitability.
As these wins ramp across a broad mix of end markets, consumer cycles will have less influence on our results. Our visibility is improving significantly, and our business will become meaningfully more resilient and predictable.
Our balance sheet has never been stronger, and we are well-positioned to capitalize on the fundamental drivers at our foundation of the transformation that Wallace spoke about earlier. I look forward to sharing more on our progress next quarter.
This concludes our prepared comments. I'd like to open up the questions now.
Operator? Thank you.
To ask a question now, please press star 1 1 on your telephone keypad and wait for your name to be announced. To withdraw your question, please press star 1 1 again.
That's star 1 1 for questions. A moment for our first question.
Operator
Our first question comes from the line of Neil Young of Needham & Company. Please ask your question Neil, your line is open.
Neil Young
Hey, good morning guys. First question, just given that you just gave us the expecting revenue to grow by at least 40% next year and gross margin in the low-50% range, curious if you could sort of dive into maybe the main drivers of that.
Given that gross margin, you're sort of resetting the long-term target, it sounds like now, I would expect more of the growth to be driven by sort of the higher-margin business like Ferri and MonTitan, but any comments that you can add further on to '27, thanks.
Jason Tsai
I think that's right. I think we're seeing significant traction with MonTitan.
We're seeing Ferri for automotive ramping very aggressively as well. A lot of these Ferri projects, especially in automotive, these are multi-year engagements where, once we're qualified in, we've got a really long-standing position with that socket, with that customer.
We're working with virtually every automaker in the world for a variety of solutions going into a significant amount of their portfolio, but significant room for growth still. Based upon our backlog, based upon the growth we anticipate from MonTitan, as well as other SSD controllers and Ferri for automotive, we believe that we can sustain these low- to mid-50% gross margins.
Neil Young
Great. That's helpful.
Then Ferri just in this quarter, bringing it back, looking at the Ferri and boot drive, obviously the growth continued and it was really great. Could you by any chance give us some more detail?
It sounds like Ferri might have outgrew boot drive in the quarter? Then obviously, beyond automotive in Ferri, curious to learn more about the robotics and sort of where you guys play in that.
Thanks.
Wallace Kou
I think because Ferri for automotive is being for a long time, we see that the customer base are very strong. For this year definitely it's Ferri for automotive it grows stronger.
However, our boot drive also gaining momentum with a diversified customers, more than just GPU customer and a TPU customer. We recently winning all the networking and the server customers.
We see that our enterprise boot drive will grow even much faster next year. Robotics, I think it's still very early stage, and the total volume still very small, but we try to make sure we'll be in when the market is take a boom.
Jason Tsai
Keep in mind, a lot of the features within the Ferri for automotive products are the same features that the robotics requires, right? Which is high-temp, vibration, all of the things that go into a car largely go into the robotics as well.
Having that certification already, having those products already puts us in a significant advantage to penetrate this market as it grows.
Neil Young
Thank you.
Operator
Thank you. We will now take our next question from the line of Craig Ellis of B.
Riley Securities. Please ask your question Craig, your line is open.
Craig Ellis
Thanks for taking the question. Team, congratulations on the tremendous momentum that it seems you have in the business.
I wanted to start with a question for you, Wallace. Very exciting to hear about the engagement that you've got with near-CPU boot drives because the performance gains given reduced latency with the way that can implement are really quite profound.
It seems like that could be a very significant market. The question is this: do you see this implementing on more of a custom basis across customers?
Or is JEDEC going to move super quickly and get standards out here in another quarter or two? Then can you just talk a little bit more about how you would see the early part of the ramp for Silicon Motion?
Wallace Kou
We see the opportunity come from the early third quarter because conventionally this near-CPU boot drive with DRAM belong to NAND makers because all NAND makers are busy and try to produce at least the 8-terabyte, 16-terabyte compute SSD. They have less interest of resource or NAND allocation for the low-capacity near-CPU boot drive.
The near-CPU boot drive primary density is about 1-terabyte, 2-terabyte, and some also 512-gigabyte. 4-terabyte is very, very few.
I think because we can see it will be probably very, very big gap, a shortage supply for 2027, many, many customers come to Silicon Motion. We are preparing discussion, and I think the solution definitely to have a customized some feature and tailor for individual server and leading hyperscalers.
This is not a simple work. We'll try to focus on selected NAND and make sure we follow the OCP requirement and provides firmware.
I think we will be ready for the firmware and solution by early Q1, and production ramp will be second half 2027.
Craig Ellis
That's really helpful. Then the second question is really a higher-level question for you and Jason.
The team has done a phenomenal job operationally this year, putting the business in a position to grow 100% plus year-on-year. Can you help us understand the positioning that you feel like you're in with wafer supply, packaging, etc., to support the 40% growth?
If demand is greater, given some reports that things like agentic AI CPUs could grow 47% next year, can you just help us understand if there's upside potential in the supply chain to meet greater demand than that 40%? Thank you.
Wallace Kou
As you know very well in semiconductor industry, today everything is in shortage, right? From substrate, from material, from wafer, from NAND, from memory, from even test capacity.
I think our manufacturing team did a very good job, and we secured our 2027 wafer with TSMC primarily, and also we also secure the test capacity and assembly capacity and the substrate material. We believe we are able to support our growth for 2027.
Jason mentioned we see we definitely can grow minimum 40% year-over-year. I think in next quarter earning call, we'll provide more meaningful guidance for our 2027.
Craig Ellis
Thank you.
Operator
Thank you. We will now take our next question from the line of Sebastien Naji of William Blair.
Please go ahead Sebastien, your line is open.
Sebastien Naji
Thank you and good morning. Thanks for taking the questions, and congrats on another record quarter here.
My first question is maybe a little bit higher-level and strategic. As your SSD solution business continues to grow as a share of revenue, hit over 40% in Q3, it is driving greater NAND pricing exposure into Silicon Motion's model, and that's a little bit of a shift for a company that was largely tied to volume growth historically.
Maybe just how do you think about managing this new pricing dynamic and how it could impact your growth and margins, particularly if NAND pricing starts to come down?
Wallace Kou
You ask a very good question. I think see we definitely manage a NAND price increase and negotiate with customer to pass through the cost to customer, we benefit from the sales revenue growth.
We believe the NAND price increase will come to moderate because the swap price for module maker now is become challenging. We see the Q3, Q4, NAND pricing is really similar.
For next year, we also see that although will be single-digit growth quarter, but it will be moderate. For our business, why we focus on automotive and boot drive, because the end customer want to have a long-term contract and support and supply.
Our contract with customers and price will stay at least two quarters, and we negotiate price every 6 months. We are able to manage the price and the cost, and that's why we can see through the demand, then we can manage our gross margin continually.
We see the NAND wafer price will be more stable compared to say last year.
Jason Tsai
One more thing, Sebastien, I think certainly there's a fear that if NAND flash prices begin to come down, how does that affect our growth? I think one of the things that we're seeing in automotive, even in boot drives, is that there's some de-speccing going on.
I think all things being equal, if NAND availability was better, if pricing was better, our customers would double their density or more in some cases. I think between a combination of kind of re-speccing to normal specs, as well as additional opportunities, additional customers that's coming online over the next 12, 18, 24 months, I think we're well-positioned to continue to grow even as the NAND market stabilizes over the next 2 years.
Sebastien Naji
Got it. Great.
That's helpful. Then maybe just as a related follow-up around the funding that you raised and the working capital needs.
I just wanted to get maybe a better sense for your ability to continue funding all of your working capital and inventory build with the cash that you have on hand. Can you maybe just talk a little bit about how quickly you expect inventory, particularly around NAND, to flow through the model, and what it would take to maybe potentially need further capital down the line?
Jason Tsai
For us, we're targeting about two quarters turnaround time between when we get the NAND and when we generate the cash flow. Our expectation is to be able to turn that inventory relatively quickly, and generate the cash flow to support ongoing growth of our business.
When we did the raise, we talked about the raise being sufficient to fund our working capital needs for the next couple years based upon today's expectations. Obviously, as the business continues to grow and hopefully as it exceeds expectations, we'll continue to reevaluate that, but that's at least right now for our visibility, we believe we're in a good spot.
Sebastien Naji
Great. Thank you.
Operator
Thank you. Our next question comes from the line of Suji Desilva of ROTH Capital.
Please ask your question Suji, your line is open.
Suji Desilva
Hi Wallace. Hi Jason.
Hi Tom. Congratulations on the progress here.
The MonTitan product, the higher KV cache density you're expecting, are there innovations coming from HBM and DRAM that might offset the opportunity for SSDs in KV cache? I'd love to get your thoughts there.
What's a good concept of the number of MonTitan SSDs needed per GPU for KV cache?
Wallace Kou
I think see MonTitan demand from very wide range not only from the AI server and for hyperscaler and also for the CSP, but also for NVIDIA ecosystem. I think we don't know the percentage how, but we see the demand for compute SSD this year is bigger because due to the NAND price is very expensive.
We'll also see the momentum for high-capacity QLC coming for next year. I believe from when Samsung, Hynix, a 2-terabit QLC can move to production, we'll see more QLC demand for data storage.
MonTitan itself can handle both see compute SSD and the storage SSD. For KV cache, particularly for CMX for NVIDIA structure, I think they will redefine and try because the price is very expensive, they try to reduce the minimum capacity for the each of Vera Rubin tray.
I think this will be probably they will announce at early next years, and I think the related ecosystem and we're helping provide. I think as long as the CMX or KV cache demand is growing, as well as demand additional eSSD, that's good for us, for MonTitan, because that increase our controller demand.
Suji Desilva
Okay. Thanks Wallace, very helpful.
The other question is for Jason perhaps. 40% plus revenue growth next year, you talked about an operating margin guide in the 30s.
Just how are you managing the opex and R&D growth given that you have so many different end markets and projects you're focusing on? What's the kind of a growth rate for opex versus revenue that would be kind of a framework for us to think about?
Jason Tsai
We'll get into more specific guidance around 2027 in January, but the expectation, this year we taped out a number of 6-nanometer as well as 4-nano products, we were spending a lot of money on tape-out and design this year already. We anticipate continuing to invest next year, and, again, we'll talk more about the specific opex guidance next year in January, but our expectation is that we will continue to be able to deliver operating margin leverage next year as well.
Suji Desilva
Thanks, guys. Appreciate it.
Thanks, guys.
Operator
Thank you. Our next question comes from the line of Mehdi Hosseini of Susquehanna International Group.
Please go ahead Mehdi, your line is open.
Mehdi Hosseini
Yes, thanks for taking my question. A couple of follow-ups for me.
Wallace, Jason, can you quantify what percentage of your total revenue were attributable to Ferri, boot drive, and PCIe SSD, and how each percentage would change into next year? I have a couple of follow-ups.
Wallace Kou
I will say we cannot talk about the detail, but for about 40% our total revenue is around the solution from boot drive and automotive, 60% from controller.
Mehdi Hosseini
Would those mixes change dramatically next year?
Wallace Kou
Next year, see solution boot drive, automotive might be grow to 50%, but so far we didn't accurate, but I think we see probably will be balanced next year, 50-50, between controller and solution.
Mehdi Hosseini
Okay. Given how your exposure to the consumer end market is less looking forward compared to prior years, should I assume that there is no more seasonality from Q4 to Q1?
Jason Tsai
Again, Mehdi, we'll get into more specific Q1 and 2027 guidance in January. Okay.
Mehdi Hosseini
I was hoping to get a preview. You mentioned you're more driven by enterprise, and maybe qualitatively you can help us to
Jason Tsai
No, Mehdi, I think certainly, with enterprise becoming a bigger portion of the mix, Ferri becoming a bigger portion of the mix, I think certainly normal consumer seasonality will certainly be more muted going forward as consumer business becomes a smaller percentage of our business. Okay.
Then
Mehdi Hosseini
is there any update on arbitration? As it would be great to tell us whether the key milestone and how we tracking to those.
Jason Tsai
We did the closing arguments in Singapore arbitration in March, and we are still anxiously awaiting the results. We don't have any other updates at this point, but certainly once the results come out, we'll be talking about those things quite a bit.
Right now, there's no additional comments we can make regarding the arbitration.
Mehdi Hosseini
Okay. Thank you.
Thank you. As a reminder, before we move to our next question, if you wish to ask a question now, please press star 1 1 on your telephone keypad.
Operator
Our next question comes from the line of Gokul Hariharan of J.P. Morgan.
Please go ahead, your line is open.
Gokul Hariharan
Hi. Thank you very much.
My first question is on the near-CPU boot drive opportunity. Wallace, I think you said you will start in as your solutions in second half of next year.
Could you talk a little bit about how big that opportunity can scale into, because your enterprise boot drive partnering with NVIDIA, it scaled up very rapidly. Could you talk a little bit about how the opportunity is and how fresh that opportunity is, given that there already a fair number of incumbents there?
We just wanted to understand, the TAM is big, but how quickly can you scale this business?
Wallace Kou
I think the TAM will be a minimum $10 billion by 2030, and because the density is bigger than the DRAM-less boot drive. Because NAND makers did not pay attention, but this business belong to NAND makers in the past because specially the three NAND maker have DRAM.
Because all the NAND maker they focus on high-capacity compute SSD and the data storage SSD, their lack of resource and attention in the near-CPU boot drive with DRAM. That's why the supply becomes shortage, and many, many Tier 1 customer come to Silicon Motion.
We see the great opportunity, we also work with the leading NAND maker to see how we can work together to result the issue. Whether they will support more NAND, and also we need to resolve manufacturing and also including some the DRAM supply, too.
We believe we'll start to ramp in second half this year. We also work with some module maker partner because they will use our controller and firmware, but we will have a different business model to work with them to benefit some financial results.
Anyway, this is a new opportunity, and we just really don't have enough R&D resources. This is a great opportunity for Silicon Motion to grow, and they could be grow even faster in 2028 and 2029, because we have a great ideal controller and fitting very well, and we have the firmware technology, and suddenly the controller very lucky have a certain OCP feature built-in, we don't need to redo the new ASIC.
I think all NAND maker, they don't have such a controller today. That's why we are in a great position to expand to the new market.
Gokul Hariharan
Got it. Just a follow-up there.
When you win business, do you have to win by individual server customer or you just design into a chip platform and you kind of become the de facto in that chip platform, similar to what you do for the current enterprise boot drive?
Wallace Kou
All the near-CPU boot drive today is M.2 form factor, 22 by 80. They need a low power because our controller, 6-nanometer controller, our SM8008, is ideal to fitting very well.
This controller need just a DDR4 or LPDDR4, well-positioned and to fitting this asserting. There's some NAND maker also want to work with us, but just that we have limited resources.
We just have to make sure the firmware is ready, we will support two different NAND by Q1 next year and hopefully ramping smoothly in second half next year.
Gokul Hariharan
As long as it is M.2 standard, you can start shipping, there is no additional qualification by individual server customer, etc., which takes time?
Wallace Kou
We already working with our module maker, our customer, and they will support the leading Tier 1 server maker, they may be ship earlier by Q2 next year, but it's only we support controller, but our own solution, total solution, will be probably ready shipping in second half next year.
Gokul Hariharan
Understood. Second question is for Jason.
Jason, first on gross margins, historically, we've seen Ferri and any NAND solution business operate in the probably lower than 40% or 40% kind of gross margin levels. Now, obviously, you've made a meaningful step-up in gross margins for solution business as well.
As NAND price kind of starts to stabilize or not really go up a lot, how should we think about margins? Are these the steady-state margins that you expect the solution business to earn, given it's more enterprise-related?
Secondly, could you also talk a little bit about next year it looks like, based on Wallace's comment, the SSD solutions business will grow faster than the 40%. What is the support that you need from inventory perspective, because inventory already has gone up to about $800 million or so.
Could you talk a little bit about how you think about how much working capital support you would need to kind of support that kind of additional, probably 50% plus percent growth in the solution business?
Jason Tsai
In terms of the gross margin question on the solutions business, as Wallace pointed out, we're we're negotiating 6-month pricing contracts with our customers. We expect to turn inventory, our inventory here within that period as well, maintaining very tight controls around working capital and price protection and margin protection for our products and our P&L.
We anticipate that, certainly with automotive, these are qualified products going into projects that are multi-year, 3 to 5 years in length, and so pricing as well as supply agreements are agreed upon at the beginning of these engagements, and so we're confident that we can maintain better margins, especially as the solution complexity, the design, the support becomes more onerous. Having the higher margin supports all of that.
In terms of the working capital, as I said, with the raise that we've done, we're confident that we're we're confident that we can support, the next couple years' worth of business, based upon what current forecasts look like. We'll continue to grow inventory, but obviously in in anticipation of a 40% plus year, we've grown inventory now, we'll continue to grow inventory in the next quarter, in the fourth quarter, and then, we'll start seeing, obviously the turns of that inventory come back into cash flow, as as we progress.
Gokul Hariharan
Got it. Okay.
Thank you.
Operator
Next question comes from the line of Daniel Yen of Morgan Stanley. Please ask your question Daniel, your line is open.
Daniel Yen
Thanks, Wallace and Jason, to take my question, and congratulation on a great result. I want to switch gear to a very different question.
Wallace, you just mentioned about some opportunities, for example, for your boot drive, for some of enterprise SSD. I want to ask what will be your strategy right now in China?
I think China is still a important region. I think in China we also have CSPs, we have NAND makers, we also have a lot of module house there.
At the same time, I think competition is still there. I want to consult you on Silicon Motion's strategy right now in China, both with NAND makers, with competitors, and also how should we address maybe the future demand from a CSP in China?
Wallace Kou
You ask a very good question, Daniel. I think see we really want to balance between China and also the rest of world.
China have YMTC, NAND maker, they're very strong, they grow very, very fast. We also support and collaborate with the YMTC directly or indirectly with module maker.
I think the enterprise portion we see they will become stronger in 2027. I think we will definitely work closely for China CSP, for hyperscaler.
Believe us, and I think that's why we try to grow China local R&D. Eventually, want our local R&D can support China customer, and Taiwan will support the rest of world, especially for US customers.
Secondly, I think see China they are growing enterprise controller company, but in the past, they also like to make a enterprise SSD drive, right? In the past, NAND pricing is cyclical.
They have a downside, they have upside. See some enterprise controller company, they buy the NAND in the downside, they're selling the drive in the upside.
Nowadays, there's no longer the cyclical, it's price are going up, all stable, right? Very hard for enterprise controller company convert into selling the whole solution if you don't win hyperscaler or even NAND maker of the CSP customer.
I think our strategy is very simple. We win in NAND maker business and design win directly.
We win hyperscaler customer in both US and China. We also win see CSP directly.
We don't make enterprise solution. We only sell controller and our firmware.
We enable module maker and the NAND maker, utilize our controller and the firmware, make a enterprise solution and selling to the customer. This is where we are.
We think that's why building Silicon Motion ecosystem working together and supporting the growing opportunity in both China and US.
Daniel Yen
I see, very, very clear. Wallace, if I may follow up, how should we think about the overall competitive landscape on the controller in China right now?
Just want to get your opinion.
Wallace Kou
For enterprise, even there's one or two ASIC company move to the IPO, but we don't see they are strong enough to compete in the long term, not just on technology, our business model, right? I don't really see any threat from them.
Even some also want to go overseas. Today we feel pretty comfortable for our position and with our technology.
We have a very, very strong design win pipeline for both our PCIe Gen 5 as well as Gen 6.
Daniel Yen
I see. Thanks for this.
The second question from me is that, since right now, I think you are issuing the convertible bond, I want to ask if there's any change on your dividend policy potentially in the future? Also, yeah, I think just overall how should we think about your capital structure going forward?
Do you have any ratio you are looking at? I think this question is actually coming from some of the investors who subscribed your convertible bond.
Yeah. Thank you.
Jason Tsai
Yeah. Dividend and capital allocation certainly continues to be a priority.
We increased our dividend a couple weeks ago, to $2 to $2.30 per ADS per year. We've had a history of increasing our dividend over the last 10 years or so, and our expectation is that we continue to look at that strategically over time and continue to look at opportunities to raise that.
The three priorities for us is on capital return is dividend, share buybacks opportunistically, and then M&A as it makes sense. That is unchanged.
Certainly right now, working capital needs continue to increase as well. The CB raise puts us in a much better position to drive growth in our business with better working capital as well.
Daniel Yen
Thank you, Jason. That's all my questions.
Thank you.
Operator
Thank you. We have now reached the end of the question-and-answer session.
I'll now turn the conference back to Mr. Wallace Kou for closing comments.
Wallace Kou
Thank you, everyone, for joining us today and for your continued interest in Silicon Motion. We'll be attending several investor conferences over the next few months.
The schedule of these events will be posted on the Investor Relations section of our corporate website, and we look forward speaking with you at these events. Goodbye for now.
Operator
Thank you for your participation in today's conference. This does conclude the program.
You may now disconnect your lines.