SiriusXM Holdings Inc.
Q3 FY2026 · Earnings Call TranscriptOctober 29, 2026
Operator
Greetings. Welcome to the SiriusXM third quarter 2026 earnings call.
At this time, all participants are in listen-only mode. A question and answer session will follow the formal presentation.
If anyone should require operator assistance during the conference, please press *0 on your telephone keypad. Please note that this conference is being recorded.
It is now my pleasure to introduce Jennifer DiGrazia, Senior Vice President of Investor Relations.
Jennifer DiGrazia
Thank you, and good morning, everyone. Welcome to SiriusXM's third quarter 2026 earnings call.
Today's discussion will include prepared remarks from Jennifer Witz, our Chief Executive Officer, and Zac Coughlin, our Chief Financial Officer. Following their comments, we will open the call for questions.
Joining us for the Q&A portion are Scott Greenstein, our President and Chief Content Officer, and Scott Walker, our Chief Advertising Revenue Officer. I would like to remind everyone that certain statements made during this call might be forward-looking statements, as the term is defined in the Private Securities Litigation Reform Act of 1995.
These and all forward-looking statements are based upon management's current beliefs and expectations, and necessarily depend upon assumptions, data, or methods that may be incorrect or imprecise. Such forward-looking statements are subject to risks and uncertainties that could cause actual results to differ materially.
For more information about those risks and uncertainties, please view SiriusXM's SEC filings and today's earnings release. We advise listeners to not rely unduly on forward-looking statements, and disclaim any intent or obligation to update them.
As we begin, I'd like to remind our listeners that today's call will include discussions about both actual results and adjusted results. All discussions of adjusted operating results exclude the effects of stock-based compensation.
Additionally, we have posted a supplementary earnings presentation and trending schedule on our Investor Relations website for your convenience. To provide an opportunity for as many analysts as possible to participate during the Q&A portion of the call, we ask that you please limit yourself to no more than two questions.
With that, I'll turn the call over to Jennifer.
Jennifer Witz
Good morning, everyone, and thank you for joining us today. As we enter the final quarter of 2026, SiriusXM continues to make meaningful progress against the priorities we established nearly two years ago: strengthening our subscription business through exceptional in-car listening experiences, accelerating advertising and off-platform monetization, and leveraging our scale to drive greater efficiency and long-term shareholder value.
We're seeing tangible results across all three areas. Subscriber trends remain stable, engagement is growing, and our advertising reach and inventory are expanding, while disciplined execution continues to drive stronger profitability and cash flow.
Our third quarter performance reinforces that progress. We delivered positive self-pay net additions, improved churn year-over-year, and maintained stable ARPU, reflecting continued stabilization in our subscription business.
In advertising, we delivered double-digit growth in podcasting and programmatic, underscoring the strength of our expanding digital audio business. Adjusted EBITDA grew 3% with margins expanding 1 percentage point, while free cash flow increased 14%, demonstrating the strength of our business model and our ability to drive greater profitability and cash generation.
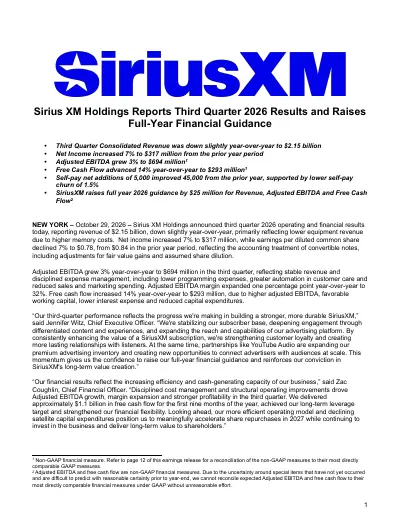
Reflecting our performance through the first nine months, we're again raising all three full-year financial guidance metrics by $25 million. We now expect approximately $8.55 billion in revenue, $2.65 billion in adjusted EBITDA, and $1.4 billion of free cash flow for 2026.
Before Zach reviews our financial results, I'd like to highlight several areas of momentum. Starting with our subscription business, we delivered 5,000 positive self-pay net additions, an improvement of nearly 45,000 year-over-year and ahead of our expectations.
Companion plans, extended duration dealer programs, and continuous service, together with improved churn, helped offset lower conversion rates and support greater subscriber stability. Central to our strategy is increasing subscription value through differentiated content, broader access, and enhanced listening experiences.
In late 2024, we expanded access to premium programming, including Howard Stern, sports play-by-play, and our artist station feature. That investment continues to deliver results, generating more than 2 million incremental monthly unique listeners in September, representing approximately 10% of subscribers who gained access.
Companion plans build on that foundation by extending SiriusXM beyond the primary vehicle to more devices and household members. Approximately half are shared with a spouse, 25% are used in a second vehicle, and the remaining 25% extend access to other family members, primarily children.
By bringing SiriusXM into more parts of our subscribers' lives, we're broadening household engagement and increasing the value of their subscriptions. Our research reinforces this opportunity.
As we shared last quarter, more than 80% of surveyed companion plan users say the offering increases their subscription's value, while approximately three-quarters indicate they're more likely to remain subscribers. As a result, we're seeing encouraging retention benefits, and we continue to optimize the program to maximize incremental value and manage cannibalization and ARPU dilution.
While we look for opportunities to thoughtfully expand the companion subscription program, this fall we also broadened our sports offering to include local sports programming from 24 markets, now available to tens of millions of subscribers nationwide. Early engagement is encouraging, with approximately 22% of our 360L sports audience already tuning in, and more than 80% of listeners outside the channels' home markets.
I'll touch more on this later, but it is clear that our differentiated sports offering, including newly added local content, is contributing meaningfully to enhancing our subscription value. Extended duration dealer programs are also gaining traction, with sales increasing more than 80% year-over-year, supported by two new automotive partners in 2026.
These programs generate more twice as many monthly active listeners per car sold as our traditional trial funnel, demonstrating the power of extended access to deepen listening habits. Together, these initiatives are broadening subscription access, strengthening retention, and supporting customer lifetime value and our ability to implement price increases over time.
Looking ahead, we anticipate a more challenging fourth quarter for self-pay subscriber trends, as we anniversary the initial benefits of continuous service, navigate ongoing conversion pressures, and increase discipline around promotional acquisition. However, stronger-than-expected performance through September supports our improved full-year subscriber outlook, with self-pay net additions now expected to be approximately flat to 2025.
Our priority remains building a more engaged, loyal, and economically valuable subscriber base, rather than maximizing near-term additions. That means investing in differentiated content, particularly in the car, while deepening fandom through live events, participatory listening, and closer connections to the artists and personalities our subscribers love.
We're seeing encouraging evidence this strategy is working. Third quarter average listening time increased 5% year-over-year, with growth across every subscriber tenure group, demonstrating deeper engagement among newer and long-standing customers.
Importantly, this growth reflects both content discovery and deeper engagement with familiar favorites. Among existing subscribers, 55% of incremental listening came from discovering new channels, with Morgan Wallen Radio alone contributing approximately 20% of the overall increase.
The remaining 45% came from spending more time with channels they already enjoy. Together, these trends demonstrate how we're expanding listening, while also strengthening existing habits.
We're seeing that deeper engagement across our programming lineup, including a 6% year-over-year increase in average listening time for our original news and issues content. Our technology platforms, including 360L and the SiriusXM app, are making this content easier to access and discover.
Year-to-date, SiriusXM app trends put us on pace for the highest average listening time and most active days per listener since the new app launched in late 2023. While technology enables discovery, our distinctive programming and talent relationships create the emotional connections at the heart of being a home for fandom.
We're bringing fans closer to the artists they love through distinctive programming and extraordinary experiences. Our Dolly Parton tribute channel became our most listened-to artist pop-up channel of 2026, demonstrating the power of timely, curated content to connect with passionate audiences.
From intimate performances with Shania Twain and John Mayer to special programming featuring Billy Joel and Talking Heads, we're creating moments that extend beyond listening. More than 110,000 people entered for a chance to attend John Mayer's performance at The Stephen Talkhouse, while Life with John Mayer has become our number one streamed artist channel.
These experiences transform listening into participation, deepen fan connections, and strengthen loyalty. Sports is another powerful driver of fandom, uniting passionate communities around live programming and hometown teams.
Listening to WWE Radio has grown nearly 20% since its July launch and rebrand, while monthly active sports listeners increased 4% year-over-year across our connected car and streaming platforms. Among 360L subscribers, average time spent listening to sports grew 7% year-over-year, demonstrating deeper engagement.
These third quarter gains came ahead of the NBA and NHL seasons, reinforcing the year-round appeal of our sports offering. At a time when sports viewing is increasingly fragmented, SiriusXM offers something distinctive for our subscribers: a comprehensive, curated experience connecting fans to all the games, analysis, and conversations surrounding their favorite teams together in one place.
Nearly 40% of our subscribers consider live sports play-by-play important to their decision to subscribe, reinforcing its value in driving acquisition and retention. Take Philadelphia, for example.
Whether following the Eagles, Phillies, 76ers, or Flyers, SiriusXM connects fans to their hometown teams and familiar local voices wherever they live. For out-of-market fans, that connection extends beyond gameday, with year-round, 24/7 access to local sports coverage.
The early response is encouraging. Collectively, our 24 local sports channels would rank as our third-largest sports destination by number of listeners, behind only NFL Radio and ESPN Radio.
We're making that experience accessible to even more fans with the launch of SiriusXM Sports Pass, an affordable subscription bringing together live play-by-play, national coverage, and trusted local voices across all four major professional leagues and more. This creates another entry point into SiriusXM, expands our addressable market, and opens opportunities for new partnerships.
We're also extending our content's reach beyond our own platforms. Howard Stern's expansion to HBO Max introduces his show to new audiences, while preserving the exclusive live experience for SiriusXM subscribers.
At the same time, we're strengthening our industry-leading podcast portfolio with the addition of Giggly Squad, Serialously, and The Bald and the Beautiful, joining top-ranked shows including Call Her Daddy, SmartLess, Dateline NBC, MrBallen, and Conan O'Brien Needs a Friend. Giggly Squad exemplifies our ability to attract culturally influential creators, with its rapidly growing fan base and sold-out multi-night run at Madison Square Garden demonstrating the reach of its creators beyond podcasting.
These partnerships expand our ability to monetize premium content across audio, video, and live experiences. That combination of premium content and expanding reach are central to our advertising strategy.
With YouTube audio, SiriusXM Media now reaches approximately 255 million unduplicated monthly listeners, up from 170 million a year ago, representing nearly 90% of Americans ages 13 and older. Early commercialization is encouraging.
Initial campaigns have increased advertisers' unique reach by as much as 91%, demonstrating the incremental value of combining YouTube's scale alongside our existing advertising capabilities and portfolio. As expected, most early bookings are coming from existing advertisers, expanding their commitments to include YouTube audio.
We're also strengthening the technology powering our broader advertising business. At our recent Built with Audio event, we highlighted AdsWizz, which powers 1 in 4 audio advertisements across the global open ecosystem, helping advertisers target audiences, optimize campaigns, and measure performance.
Together, our growing audience scale, premium content, and advertising technology position SiriusXM Media to deepen advertiser relationships, attract new advertising dollars, and capture more of advertisers' spend across all budgets. We expect YouTube audio and our broader off-platform strategy to become increasingly meaningful contributors to growth in the second half of 2027 and beyond.
As we look ahead, we're encouraged by stabilizing subscriber trends, broadening engagement, expanding advertising opportunities, and continued operating discipline. Our focus remains on translating that progress into sustained profitability, substantial free cash flow, and disciplined capital allocation.
With improving fundamentals, differentiated content, and a clear focus on execution, we believe SiriusXM is well-positioned to deliver meaningful long-term shareholder value. With that, I'll turn it over to Zach.
Zac Coughlin
Thanks, Jennifer, and good morning, everyone. Our third quarter results demonstrate continued financial progress, as the structural improvements to our business translate into stronger profitability, higher earnings, and substantial free cash flow.
Our subscription and advertising businesses remained resilient, while disciplined cost management drove margin expansion and strengthened our financial position and capacity to return capital to shareholders. Turning to the quarter, consolidated revenue was approximately $2.2 billion, essentially unchanged year-over-year, as stable subscription and advertising revenue offset a $7 million decline in equipment revenue attributable to higher memory costs.
Subscription revenue increased modestly to $1.6 billion, with the benefit of our February pricing actions offsetting mix dynamics. Advertising revenue edged higher to $456 million, as growth in podcasting, programmatic, and technology fees balanced softer demand across streaming music and satellite advertising.
Importantly, adjusted EBITDA increased 3% to $694 million, with margins expanding 1 percentage point to 32%, reflecting the benefits of our cost transformation and disciplined spending. Total operating expenses declined approximately $24 million, or 2%, year-over-year, with savings across programming, customer service, sales and marketing, and general and administrative expenses.
These improvements reflect favorable contract renewals, increased automation, lower call volumes, and more targeted acquisition spending, more than offsetting higher revenue-sharing expenses associated with our growing podcasting and off-platform businesses, as well as certain royalty costs. Importantly, these savings are largely structural, creating a more efficient operating model and a foundation for sustainable margin expansion.
We remain on track to deliver approximately $100 million in incremental gross cost savings in 2026, having realized $96 million through September, including $64 million in operating expenses and $32 million in capital expenditures. These efficiencies support sustainable margin improvement while providing flexibility to reinvest in growth.
Net income increased 7% to $317 million. Free cash flow grew 14% to $293 million in the quarter, bringing year-to-date free cash flow to approximately $1.1 billion, up 48% year-over-year, reflecting improved profitability, lower capital expenditures, favorable working capital, reduced cash taxes and interest expense, as well as the timing of cash flow compared to last year.
Turning to our segment results, SiriusXM revenue was approximately $1.6 billion, essentially unchanged from a year ago. Subscriber revenue was $1.5 billion, with pricing benefits offset by subscriber mix.
SiriusXM advertising revenue was approximately $37 million, down $2 million year-over-year, reflecting softer demand across news programming and direct-to-consumer advertising, partially offset by continued strength in sports. Equipment revenue declined 16% to $36 million, primarily due to elevated memory costs associated with our hardware modules.
These pressures reflect broader semiconductor industry conditions and remain a headwind to equipment revenue and margins. Despite these challenges, SiriusXM gross profit increased 1% to $963 million, with gross margin expanding 1 percentage point to 60%, supported by lower programming, customer service, and transmission costs.
Turning to subscribers, we delivered 5,000 self-pay net additions, an improvement of roughly 45,000 year-over-year. Self-pay churn improved to approximately 1.5%, while ARPU remained relatively stable at $15.18, benefiting from rate increases and improved discount mix, as we transition customers from deeply discounted promotional offers to more sustainable pricing within our modular content packages.
These gains were partially offset by the growing mix of more affordable and value-add offerings designed to broaden access and strengthen long-term retention. Our subscriber initiatives continue to support performance, including approximately 107,000 net additions from companion plans this quarter, alongside benefits from continuous service and extended duration dealer programs.
While conversion rates continue to decline gradually, the underlying trend remains unchanged. As Jennifer discussed, we anticipate a more challenging fourth quarter for self-pay net additions, reflecting tougher year-over-year comparisons as we anniversary the initial benefits of continuous service, continued conversion pressures, and a disciplined approach to promotional acquisition.
Nevertheless, stronger-than-expected performance through September supports an improved full-year outlook, with self-pay net additions now expected to be approximately in line with 2025. Turning to Pandora and off-platform, segment revenue was approximately $549 million, modestly higher year-over-year.
Advertising revenue increased 1% to $419 million, driven by 20% growth in podcasting, 21% growth in programmatic advertising, and 11% growth in technology fees, partially offset by a decline in streaming music advertising, reflecting lower listening hours. Podcasting continues to benefit from strong advertiser demand, larger deal sizes, and expanding creator and omnichannel offerings.
Strong sell-through has reduced available inventory, constraining growth in the third quarter, partially offset by improving monetization rates. We're addressing this in the fourth quarter by expanding our premium creator portfolio, including new partnerships with Giggly Squad, Serialously, and The Bald and the Beautiful, bringing additional inventory and highly engaged audiences to our network.
We're also capitalizing on the shift toward video consumption, with video and social podcast advertising sales more than doubling year-over-year for the third consecutive quarter. The launch of Apple HLS further expands our video capabilities, creating new inventory and monetization opportunities across formats.
Specifically, looking at the fourth quarter, advertising trends are encouraging, with continued strength in podcasting and programmatic supporting modest year-over-year growth, despite a tougher comparison to a strong fourth quarter last year. Our expanding advertising capabilities, including YouTube audio, create opportunities to attract new advertisers and deepen existing relationships.
As we previously communicated, we're taking a measured approach to commercialization, with a modest contribution expected in 2026 and a more meaningful impact in the second half of 2027. Pandora and off-platform gross profit increased approximately 2% to $173 million, with gross margin expanding to 32%.
Our focus remains on expanding premium inventory, capturing advertiser demand, and translating stronger monetization into sustained revenue growth and profitability. Turning to capital expenditures, total spending was $166 million during the quarter, compared with $175 million a year ago.
We're progressing toward completion of our current satellite investment cycle, with SXM-12 expected to launch in 2027. For non-satellite CapEx, we continue to expect spending of approximately $400 to $415 million this year, with targeted investments in product modernization, technology infrastructure, and advertising capabilities.
As satellite spending moderates, we expect stronger cash conversion, further enhancing free cash flow and financial flexibility. Our substantial cash generation continues to support disciplined capital allocation.
During the quarter, we reduced total debt by $100 million, while returning $124 million to shareholders through dividends and share repurchases. We ended the quarter with net leverage of 3.3 times adjusted EBITDA, within our long-term target range of low-to-mid 3 times, and approximately $1 billion remaining under our existing repurchase authorization.
Our capital allocation priorities remain focused on investing in the business to drive attractive long-term returns, maintaining a strong balance sheet, and returning excess capital to shareholders. We'll remain opportunistic in pursuing both organic and inorganic growth opportunities where we see compelling strategic and financial returns.
At the same time, we believe our current share price represents a compelling investment opportunity and see potential to meaningfully accelerate share repurchases in 2027, while maintaining our dividend and operating within our established leverage framework. Turning to our outlook, as Jennifer highlighted, our strong performance through the first nine months supports another $25 million increase across all three of our full-year financial guidance metrics.
We now expect revenue of approximately $8.55 billion, adjusted EBITDA of $2.65 billion, and free cash flow of $1.4 billion for 2026. Our increased outlook reflects improving subscriber performance, continued operating efficiencies, and strong cash generation, more than offsetting the impact of elevated memory chip costs.
Looking ahead, the resilience of our subscription business, strengthening advertising momentum, and continued operating discipline position us to sustain strong profitability, generate substantial free cash flow, and increase capital return to shareholders. We remain focused on translating our financial strength into meaningful long-term shareholder value.
With that, I'll turn it back to the operator for Q&A.
Operator
Thank you. We'll now be conducting a question and answer session.
If you'd like to ask a question at this time, you may press *1 from your telephone keypad, and a confirmation tone will indicate your line is in the question queue. You may press *2 if you'd like to remove your question from the queue.
For participants using speaker equipment, it may be necessary to pick up your handset before pressing the star keys. In the interest of time, we ask that you please limit yourself to no more than two questions, to allow as many possible to ask questions.
Thank you, and today's first question is from the line of Sebastiano Petti with J.P. Morgan.
Please proceed with your questions.
Sebastiano Petti
Hi, thank you for the question. I just wanted to ask about the strategy shift towards higher lifetime value subscribers, just trying to understand why is now the right decision or the right time to kind of make that pivot, moving away from deep discounting, full price trials.
I guess how should we think about defining success within that context? Is it a more smaller base, but more profitable?
Just help us kind of contextualize that, would be great. Just a quick follow-up.
The subscriber guidance just what is the number we should be anchoring to that you say will be similar? Is it flat subscribers year-over-year?
Is it down 300,000? It's a little bit unclear from the outside looking in and trying to listen to the messaging.
Thank you.
Jennifer Witz
Sure. Thanks, Sebastiano.
First, on customer lifetime value, the strategy we put in place two years ago is working. The core subscription business continues to improve.
Our subscriber trends are improving, and we are focused on building a higher quality and more durable overall subscription business. We're really pleased to be improving our outlook for self-pay net adds for this year.
Last year, we were down about 300,000. This year, we now are saying that we expect to be in line with that self-pay net add performance, which is better than we've been guiding previously, because we thought we might be slightly worse.
That's primarily because of the take-up we've seen in companion plans and to a certain extent our extended duration plans as well. Our primary focus over the last two years has been on improving engagement and ensuring that our core in-car customers feel that we provide them with strong value in their subscriptions.
You see that manifesting in strong customer satisfaction, retention, and low churn. We have, in addition, as launched multiple acquisition-oriented initiatives helping to build new demand outside of our traditional in-car conversion funnel.
These are things like the EDP, extended duration program, and our companion plans, which are both driving new demand through new engagement across the household and reinforcing subscription value as well. This strategy also flows through to pricing and packaging, right?
We've been more disciplined, as we've been talking about, by focusing on driving improved CLV, and we're doing this by creating more package differentiation, reducing this reliance on unpublished discounts, and opening up these new demand at lower price points, but primarily adding value to these top-tier full-price packages to improve engagement across content types and devices and household members, because this will allow us to support ongoing rate increases. You asked what is the ultimate goal.
Success is that we have stable to slightly improving subscription revenue overall, and this is the first year we will achieve that in four years.
Sebastiano Petti
Very Very helpful. Thank you, Jennifer.
Operator
Our next question comes from the line of Bryan Kraft with Deutsche Bank. Please proceed with your question.
Hi,
Bryan Kraft
thanks. I had a few on the YouTube relationship, and then I had I guess a follow-up on net adds.
Maybe just ask the net adds first. On the companion subscriptions going forward, are you continuing to assume a contribution in the fourth quarter?
It seems like maybe you're not, given the implied net adds for 4Q based on the guidance. Then on the YouTube relationship, wondering if you expect there to be a benefit to CPMs and/or fill rates for your own inventory as you roll out the YouTube partnership, just given the increase in audience size and scale.
Are you seeing the relationship as you launch it, bring new advertisers to the platform? Any interest yet from other audio streaming services in partnering with you, just given the leadership that you're showing in this area?
Thanks.
Jennifer Witz
Thanks, Bryan. I'll let Scott cover YouTube in a minute.
Just on net adds, we do still expect a contribution from companion in the fourth quarter, and into next year, by the way. There are opportunities for us to continue to expand that program.
Plus, we just see ongoing take rates among those that are eligible today. Again, we believe this is a really strong program for us, because it does open up engagement across the household and reinforce that value.
In the fourth quarter, we talked about the dynamics a little bit about continuous service. We launched it last year in the fourth quarter.
That had a meaningful contribution. This year, we're starting to stabilize in terms of the net impact of continuous service, and so it will have less of a contribution in the fourth quarter.
That's the primary dynamic. Scott, you want to address YouTube?
Scott Walker
Absolutely. Look, the basis of the question is a really interesting one, because it's exactly how we're going to market with YouTube, not as a stand-alone platform, but as an aggregated audience play that includes streaming music inventory on Pandora, SoundCloud, and the broader podcast network.
There is an opportunity, as we bring this massive incremental reach that we talked about, and in our early campaigns, we're seeing that incremental reach across our existing portfolio is up to 90-plus percent, as Jennifer mentioned in the prepared remarks. That allows us to tap into new advertisers, targeting new audiences, and aggregate that through an audience-based buy alongside our existing inventory.
That will bring more sell-through and pricing opportunity as we bring this aggregated solution to market. In terms of the advertisers that are currently investing and testing right now with YouTube, it's very early.
A lot of the advertisers are existing advertisers, as Jennifer mentioned. They're in test-and-learn mode right now.
This is exactly what we would expect. Our trusted relationships that we've established for years are those that are going to invest first.
There are a number of measures that we're paying attention to, whether that's the mix of new versus existing, repeat buys, how much they're investing against this new inventory. It will take time.
Audio is not a channel where you have a click-through to a purchase like you have on social or search or some of these other channels. You have to have patience and set up the right measurement infrastructure and the right testing methodology to see the real halo effect across these other channels, which is why we've been so focused on getting that measurement infrastructure in place and why we expect to see the ramp really in second half next year.
Bryan Kraft
Great. Thank you.
Operator
The next question is from the line of Steven Cahall with Wells Fargo. Please proceed with your questions.
Steven Cahall
Thank you. Jennifer, we're backing into SiriusXM's self-pay gross adds maybe down around double digit for the last couple of quarters, excluding companion.
Then churn is also improving really nicely year-on-year. I was wondering if you could just talk us through how you think about what you're seeing at the top of the funnel and what you're looking to drive at the top of the funnel.
Then how we should expect churn to continue on that trendline. Then just a housekeeping one: you've been talking about the auto dealer duration plans for a few quarters now.
Could you just quantify what those are contributing to 2026 self-pay net adds, and how do we think about the engagement or conversion that you're seeing with those customers? Thanks.
Jennifer Witz
We talked a little bit about the extended duration program in terms of engagement in the prepared remarks, that we look at it as a metric based on kind of a new car trial start or an enabled vehicle. At the end of a typical trial, which is usually about three months, compared to an EDP, which is three years, we see more active customers per car.
Ultimately, we're building stronger engagement across a broader set of customers through that program. It's been very helpful in terms of not just leveraging, but also building and deepening our relationships with automakers and dealers.
It's a win for all of us: the OEMs, the dealers, our customers, and the business for SiriusXM. We're very pleased with that program.
You mentioned companion. Companion shows up in both in-car adds and streaming adds, and we believe that there's still opportunities to expand that going forward.
Again, it's driving incremental demand and retention that supports ongoing rate increases as well. I think if you look at the funnel going forward, we've been developing new opportunities outside of this traditional in-car funnel and the conversion process after a three-month trial.
This is just opening up demand into new areas, and so there's a number of areas that I think we can continue to explore there. Part of it is in pricing and packaging, with things like Sports Pass, which we just launched, and so it's early days, but at a much more compelling price point of $5 for a reduced content set, but honestly the best sports package out there, whether it's audio or video, is an incredibly powerful opportunity for us to open up the addressable market, but also pursue additional bundles and partnerships.
There's been a fair amount of interest. Far, we're using it in select ways with the Rise and Shine program, in Yahoo Sports, and building more awareness for this package.
You might imagine, we've just announced a growth in our relationship with T-Mobile. We're incorporated in their new T-Mobile Experience wireless plans.
There are a lot of opportunities for us to pursue additional bundles and partnerships given that we have these new packages that will likely be more content-focused at more compelling price points. We're also continuing to remove friction.
I know, you've highlighted that our extremely low churn. I believe we have continued opportunities to improve upon this, because we're just getting started using all the data that we're getting back from 360L.
Again, the objective there is to make sure that customers feel that their subscriptions have high value because they are expanding engagement across content types, devices, and additional members of the household. I think that's incredibly important, and we're just getting started in those areas.
Again, we continue to find new ways to better serve our core in-car customers as well as opening up new channels of demand.
Steven Cahall
Great. Thank you.
Operator
Our next question is from the line of Barton Crockett with Rosenblatt Securities. Please proceed with your questions.
Barton Crockett
Great. Thanks for taking the question.
I was curious to talk a little bit about spectrum in this regard. I know that you guys are going through kind of a long-term process to evaluate options and maximize value.
I'm just wondering given that there's so much dynamism in the technology, right, with Elon Musk talking up his ambitions in satellite-to-device and carriers kind of responding, if there could be some environment where there could be some early kind of testing deals that precede kind of a broader engagement in terms of how you guys are looking at the environment, and if there's a possibility of something like that perhaps near-term and ahead of kind of the longer-term kind of technology commitment. That's one question.
Then the other question is just to look at kind of the subscriber trends, and just how to think about the fourth quarter number, which is a different trajectory than we've seen through the first three months in terms of the numbers you've reported, impacted obviously by the companion, but to what degree is the fourth quarter kind of a bogey that suggests how we should think about next year or not, just some puts and takes around that.
Jennifer Witz
I'll start on the fourth quarter, Barton. We don't see this as necessarily indicating a different trend.
We've been certainly not that focused on the quarters. We are focused on building a healthier subscriber base, and while this particular quarter may look different than prior fourth quarters, we've looked at the year in total, and we feel really good about the progress we're making.
Again, our goal is to stabilize the subscriber base, but really focused on subscription revenue and not just subscribers. Back to your question on spectrum, just to take a step back, certainly the technology innovation, including in launch capabilities and satellite designs is supporting new entrants in the last several years, and especially direct-to-device.
That combined with more recent increases in industry transactions and just commentary, as you mentioned, and regulatory developments, all help reinforce the value of spectrum, and particularly our spectrum as a scarce strategic asset. We believe that all these developments are constructive to our portfolio.
On your specific question about testing, we have done some work, of course, to understand impacts of interference from different technologies. We have a very strong understanding as to how that might manifest.
There is growing interest in different commercial applications, and those discussions are certainly informing our evaluation of potential opportunities and partners and different types of transaction structures, and we remain open to a range of alternatives, of course, and look forward to sharing more when we have more information.
Barton Crockett
Okay. All right.
That's helpful. Thank you.
Operator
The next question is from the line of Cameron Mansson-Perrone with Morgan Stanley. Please proceed with your questions.
Cameron Mansson-Perrone
Thank you. Morning.
Two if I could. First, there's obviously been a lot of development around AI-enabled agents, and it doesn't appear from the results today like there was much of an impact in 3Q, but I'd be curious, Jennifer, on your thoughts regarding as we look forward, how you see these agents becoming more sophisticated interacting with you as a subscription product, and any impact that you might foresee in the future.
Then on the expense side, there's been a nice benefit this year on the programming expense front. I'd be interested in any color there.
I know you highlighted contract renewals in the release, but just any color around kind of the sustainability or how you see programming expense trending over time. Thanks.
Jennifer Witz
Zach will take the cost piece first.
Zac Coughlin
Let me start on the cost piece. Thanks, Cam, for the question.
I think overall, we've had a good year on costs. We talked about the $100 million at the beginning of the year for gross cost savings.
We've delivered $96 million, essentially all of that through three quarters of the year. I think what makes us happy about that is there's no single silver bullet inside of there.
Obviously, you mentioned programming savings, and we saw that in the third quarter and throughout the year. We've seen it in customer service.
We've seen it in marketing. We've seen it in G&A.
I think it's a signal of the widespread work that the organization is doing to deploy a combination of tools and technology and new ways of working to engineer structural cost savings out of the business. I think that's, as we see what that is, it gives us confidence that'll build into next year as well.
To the specifics on programming, exactly, I think that I would say similar to the work we've done otherwise across the other pieces of the portfolio. Programming at its core is an investment.
We're working on making sure that we're utilizing sort of more insightful ROI, trade-offs of costs to benefits. I think that's proven successful in programming across a number of the other parts of the portfolio.
We're able to give both improved outcomes, and we're able to see the financial benefits from a cost perspective fall out the bottom as well.
Jennifer Witz
I'd say Scott and his team have done a great job at looking at the data, combined with the research on perceived value to understand exactly what we believe we get from various programming contracts and internally developed content as well. Feel really good about our opportunities there going forward, also.
Back on the AI agents, look, we're taking a broad perspective here. These AI agents obviously have the potential to change how customers are discovering and evaluating and managing their subscriptions, and we're looking at all of these areas.
The subscription management side, as you mentioned, has gotten a lot of attention lately. We don't see that as fundamentally changing the value that customers receive from SiriusXM based on our differentiated content and experiences that just can't be replicated by other providers.
If I think about it, I look at this as really having two potential impacts: there could be higher cancel demand, which is a volume impact, or there could be higher cancel rate or trade-downs, which is a rate impact more. On the former, we don't see any volume of note.
Obviously, we're watching it closely, and we believe we can identify these agents. Just overall, I might highlight that we're not even seeing an increase in customer interactions in terms of cancel demand overall.
In fact, they've continued to decline year-over-year, which is one of the things that's manifesting in our lower churn. On the latter, we've been working with Sierra, as you've been discussing, for over two years, and we have a significant percentage of our interactions today across chat and voice already handled by AI agents.
These automated interactions have higher levels of CSAT, because of lower level of effort, they have better business results, and they're generally at a lower cost. We're working closely with Sierra on their agent protocol, and I think we'll learn more as they start to release that in the coming weeks.
We keep improving our results by adding additional customer listening and engagement data to the models we use to address customers if they do call to negotiate. That's going to be important whether it's a personal agent contacting us on behalf of the customer or the customer themselves.
We're already doing this work, and I believe that AI, it's going to be obviously a potential for disruption, but it also is an opportunity for us to continue to improve customer experience, whether it's in our customer interactions or more broadly across our business.
Cameron Mansson-Perrone
Very helpful color. Thank you, both.
Operator
Our next question is from the line of Jessica Reif with Bank of America. Please proceed with your questions.
Jessica Reif Ehrlich
Thank you. Good morning.
Two questions. Engagement was up, or listening time was up 5% in the quarter, but advertising was down 5%.
Can you talk about what's going on there? Are there a feather things that we should be thinking about for Q4, because your Q4 guidance implies significant margin contraction.
Just wondering where it's coming from and what's going on with advertising. Then the second question, going back to YouTube, advertiser budgets are pretty much set for '27 at this point.
Can you give us a framework for the revenue that you guys will retain and incremental EBITDA contribution at scale from the YouTube relationship? What are the measurable milestones over the next two or three quarters that would tell us this ramp is on track for second-half scaling?
Thank you.
Jennifer Witz
Scott, you want to start on YouTube?
Scott Walker
Yes, I will. Jessica, thanks for the question.
You mentioned that the budgets are set for 2027. We actually don't see that as being the case.
We're in early discussions with all the major holding companies, locking commercial terms around the potential opportunity to expand our investment with their clients, not just existing advertisers, but net new advertisers targeting this younger demo and the incremental reach. I think that's still yet to be determined.
We see a lot of interest, like I mentioned earlier, and we're in a test-and-learn mode through the balance of the year. As we start to get to feature parity with both what we deliver on the SiriusXM Media side in terms of content filtering, targeting, measurement capabilities, but also the YouTube video side, because these advertisers are very sophisticated, they have expectations that both businesses have set, we see a real opportunity and a lot of runway heading into 2027 in the upfront, but also in the scatter market as we start to evangelize and start to demonstrate the halo effect of bringing YouTube into the fold.
That's the answer on the YouTube front.
Zac Coughlin
Maybe, Jessica, a couple of things on the advertising revenue. I think overall for the third quarter, total advertising for us was quite stable versus last year.
You mentioned the SiriusXM specific advertising revenue. I think that's a small part of the broader SiriusXM portfolio.
I think if we look forward more broadly about the fourth quarter, we commented in the scripts earlier that we feel really good about where early signals are for fourth quarter advertising revenue, and where bookings are coming in. Maybe I'll just talk a little bit about more broadly the Q4, the implied outlook.
As we don't give quarterly guidance, but obviously a lot can be implied in the fourth quarter from the guidance we've given. Maybe I'll spend a little more time talking about the quarter itself than we typically would.
For both subscription and advertising revenue, we expect to see consistent trends the first three quarters, good stability on subscription revenue, and as I just mentioned, Q4 advertising trends look encouraging. Inside of the rest of revenue, though, we do expect to see growing headwinds from equipment revenue tied to memory costs.
This is probably the most impactful element shaping that implied fourth quarter outlook. For the rest of the P&L, we've done a really good job this year of delivering on the cost efficiency target, as we talked about a moment ago.
As we transition to the fourth quarter, we are looking to lean back into some targeted investments with a focus on building momentum into 2027. Probably the most specific on that would be some marketing spending.
We've done a lot of work this year on sharpening our targeting and improving ROIs, and the spending there in the fourth quarter does give us some confidence to spend a bit more and see that impact building in to 2027. That's just a little more on the Q4 outlook.
Jessica Reif Ehrlich
That's helpful. Thank you.
Operator
Thank you. Next question is from the line of Jason Bazinet with Citi.
Please proceed with your questions.
Jason Bazinet
I just had one question on companion plans. I think in your prepared remarks, you talked about thoughtfully expanding that to sort of improve the value, but keep an eye on ARPU dilution.
Can you just describe today how you're sort of expanding companion plans and how that might change over the next few years? What could change?
Jennifer Witz
I'll pick up the program, and then Zach can touch on ARPU briefly. What we've seen is that our most loyal customers on full-price packages are taking advantage of this and providing the incremental, whether it's a car in certain cases, depending upon the package you have, or streaming login to another member of the household, right?
Whether that's an adult child or perhaps a partner. For us, it's really about how deep we should go in our customer base in terms of providing that opportunity or how broadly we might go in terms of adding incremental opportunities beyond, right now if you have an in-car subscription, you automatically get a streaming login.
We don't count the extra streaming login in that case as a subscriber, but if you add another one, that's an incremental subscriber, and we could provide another one or two to some of our most valuable households. We continue to look for those opportunities.
It has delivered beyond our expectations this year, and that's why we think that there is more to do here. Of course, we want to be mindful of any potential cannibalization of paying subscribers.
It is not material today, but that's the watch-out we're looking to manage.
Zac Coughlin
Thanks, Jason, for the question. I think speaking specifically about ARPU for a moment, remained relatively stable to last year at $15.18.
That number reflects a number of components. Obviously, it has in there the impact of the rate increases on self-pay plans earlier this year.
That's been a strong tailwind all year. It also reflects the improved discount mix, as we've transitioned customers away from those deeply discounted packages, that Jennifer talked about in the progress on that over the last couple of years.
For the third quarter, those benefits are being offset by the growing mix of sort of value-adding companion subscribers and more affordable offerings designed to broaden access, and support long-term retention. The net result of that picture is an increasingly stable subscriber base, low churn, increasing engagement, higher customer satisfaction, and strong ARPU.
We feel good about how we've been managing that balance so far this year, and I think we'd expect to continue to do so into 2027.
Jason Bazinet
That's great. Thank you.
Operator
The next question is from the line of David Joyce with Seaport Research Partners. Please proceed with your questions.
David Joyce
Thank you. I just wanted to drill down a bit more on your comment that you're taking a measured approach to driving advertising.
Is it due more to the back-end technological work that's still required, including standing up the YouTube ad rep opportunity, or is there more that you're still doing on the 360L side, or is it more that you're still working on adding to your premium inventory such as these new podcast content relationships? Thanks.
Jennifer Witz
I can start, and then I'll let Scott add on it. I think the in-car opportunity is still ahead of us, and I think that may be something that we can focus a bit more on next year.
Of course, our main priority is YouTube, but we do believe there is an opportunity for us to open up more targeted advertising in-car. I think we've talked about that before, David.
Certainly there's opportunities to work more closely with the OEMs on that as well, and I think it is something they're interested in. Scott, maybe you want to pick up on the rest?
Scott Walker
Sure. David, thanks for the question.
In terms of our measured outlook on Q4, there are a few things that stand out. I'd say we're encouraged by early bookings relative to last year, still early in the dynamic there, but programmatic continues to grow, podcasting continues to grow year-over-year, as well.
We've added podcast supply, where we've had some supply constraints, as Zach mentioned, Giggly Squad, Serialously, Bald and Beautiful. Our Apple HLS video opportunity allows us to continue to invest in omnichannel solutions, including video and social, and live events.
We've launched a new Shorts product with a really popular basketball podcast called The Deep 3, which is one example of a podcaster and creator that has more reach on the short-form content than their long-form content, and just another example of how we're diversifying our product offering there. That said, I think, of course, and I can't forget that YouTube continues to be a focus, and we're refining that offering.
One of the big learnings that we've validated early on is that these advertisers have expectations around targeting and measurement and reach frequency relative to YouTube video, relative to SiriusXM. We're systematically working through those.
That will have modest impact in Q4, but certainly growing in 2027. I would say, as far as why we're a bit cautious, there are those categories that are a bit more careful with their spending: QSR, retail.
We've talked about a few of those, given the underlying macro environment. With a political cycle around the corner that can often lead to dollars coming in and out, programmatic is something that can have some volatility to it, which is why we're being measured in our outlook there.
David Joyce
Good. Appreciate the color.
Thank you.
Operator
Thank you. Our final question is from the line of Stephen Laszczyk with Goldman Sachs.
Please proceed with your questions.
Stephen Laszczyk
Hey, great. Thanks for taking the questions.
Zach, on leverage and buybacks, I was curious if you could speak a little bit more about the opportunity to meaningfully accelerate share repurchases next year. Maybe give us your latest thoughts on leverage and some of the determining factors that will govern the pace of buybacks as we look ahead to next year.
Zac Coughlin
Thank you, Stephen, for the question. We're really happy to be able to talk about capital allocation.
Reaching our target leverage range last quarter was an important milestone, gives us a lot more flexibility to deploy that substantial free cash flow we have. I do want to pause for just a moment and talk about free cash flow, though.
We had another strong quarter: free cash flow of almost $300 million, up 14% versus last year. That brings us year-to-date to $1.1 billion, which is up almost 50%.
We have been planning all year for some different seasonality, we won't see that percent carry through to the full year, but we do expect to land cash flow with a strong number this year, reflects in our increased guidance of $1.4 billion, and really strong confidence in delivering our $1.5 billion next year. Now specifically back to capital allocation, our priorities remain consistent: first and foremost, investing in the business for attractive long-term returns, and this is through a combination of ROI-positive organic investment, which we've talked a little bit about earlier, and making sure we have the flexibility to be opportunistic around inorganic activity where it makes sense.
Beyond that, our low-to-mid 3 times leverage range remains unchanged, and we believe that's the right place to give us the flexibility, then it does land with capital to shareholders. We remain committed to the dividend, and with that being said, now we believe a little bit this quarter and then especially into next year, the chance to increasingly direct capital towards share repurchases.
I think we'll remain opportunistic in the timing and pace of that, balancing all those priorities. I do think at the end of the day, we believe that will point towards meaningful increases compared to what we've done over the last couple of years starting next year.
Stephen Laszczyk
Great. Just
Jennifer Witz
to wrap up, we are very proud of our team as we continue to make substantial progress in executing against our 2024 strategy reset, and we're excited about the prospects for our business as we see improving subscriber economics, accelerating advertising growth, expanding free cash flow and capital returns, and meaningful long-term strategic value related to our spectrum licenses. I thank you all for joining us this morning.
Operator
This will conclude today's conference. You may disconnect your lines at this time.
We thank you for your participation and have a wonderful day.