Savaria Corporation
Q3 FY2026 · Earnings Call TranscriptNovember 5, 2026
Operator
Good day, and thank you for standing by. Welcome to the Savaria Corporation's Q3 2026 investor and analyst call conference today.
At this time, all participants are in a listen-only mode. After the speakers' presentation, there will be a question-and-answer session.
To ask a question during the session, you will need to press star one one on your telephone. You will then hear an automated message advising your hand is raised.
To withdraw your question, please press star one one again. Please be advised that today's conference is being recorded.
I will now hand the call over to our first speaker today, Sebastien Bourassa, CEO and President of Savaria Corporation. Please go ahead.
Sebastien Bourassa
Thank you, Angela, and good morning, everyone. Today, I'm happy to present our Q3 results, which show that we have a good momentum across the business, and our new process and culture that we have developed during Savaria One is well established, and this is why we have realized our best EBITDA dollar so far at $52.1 million at 21.2% EBITDA margins.
First, Accessibility, with a growth of 9.1% and an EBITDA of 24.2, it showed that in our main division, we still have a lot of initiatives that are getting implemented and that we can offset some of the inflation we received this year. Our vertical strategy is paying off.
As we design, manufacture our own electronic PCB in the UK. We have good contribution from our China and Mexico factory, and we have made significant investments in machinery in the last few years in our local factory so that we can be more productive and we can make some custom product with good lead time.
Our core product line of home elevator and stairlift remained the main driver of this growth, and we continue to build our product roadmap with our 6-to-be-born R&D across all the business segment. Here's a few examples that what excite me about the future growth.
The new Luma L: we have received an enthusiast dealer response at the NAEC exhibition in September with the launch of our new larger model of Luma. We also introduced it at the Grand Designs show in UK, and we have really good interest from the designer and home elevator.
The larger cabin can accommodate many styles of mobility devices. The Luma L is now available in North America from October, and will be available in Europe in January 2027.
The through-the-floor lift category should be a strong area for coming years for growth, and it's really an elegant product that is easy to install and can be a retrofit application. Vipal: we talked a lot about Vipal in the last few months, but again, a strong product offering and code-compliant product in Europe that will really help us to develop the sales of home elevator in Europe in the coming years.
Another exciting thing: the new Precision cab for home elevator that was introduced at the NAEC also was very well received. The style and color are very trendy, which will be a big one for the contractor, designer, and customers.
The quality of those wood cab can be produced at our factory in Greenville are outstanding. They can be sold in multi-units project, custom home elevator, and really differentiate ourself on our home elevator from our competitor, and hopefully earn a higher share of project.
Regarding Greenville, we continue to manufacture approximately 50% of our home elevator, and our building expansion is on plan and should be ready by the end of Q4 of this year. Second, Patient Care: happy with the growth of 9%, but for sure, the EBITDA percentage is not where we want.
The team of Patient Care is very aware and are working on it, and as we discussed during the last conference call, we did a midyear price adjustment, which we hope to have a better results in Q4, starting from Q4. Still, I would like to highlight the performance in Europe and rest of the world, good job, Gary, and the team in UK.
Third, acquisition: as was said during the Investor Day, we have the ambition to do some acquisition in the next five years for around $200 million. Those are small, mid-sized acquisition in some areas that we underperform or can bring some new products or new dealer network to expand our product portfolio, and also the one-stop shop.
Far this year, we did Baxter elevator in Texas, where it's a booming market, and in July, we closed Vipal with a small home lift lineup and low-rise commercial elevator in Italy to help develop Europe in the coming years. With our net debt ratio of 0.85 at the end of Q3 and our liquidity that continue to go at $338 million, we are in very good position for capital allocation to continue to make investment in this business.
To conclude, I'm very happy with the first nine months of the year, and as we unveiled during the Investor Day, we have the ambition to grow the business at 12% per year in the next five years and maintain our EBITDA margins at 20-plus, which ultimately will lead us to a $1.6 billion of sales with over $320 million of EBITDA. Thanks to all the people at Savaria for their efforts in the next chapter of growth.
Steve, financials, please.
Stephen Reitknecht
Thank you, Sébastien, and good morning, everyone. I'll now provide some additional details on our third quarter results.
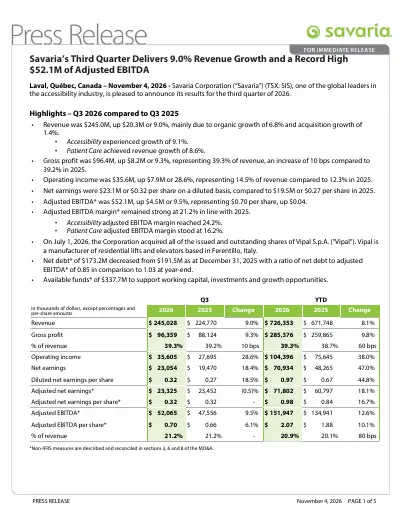
Starting with the key financial highlights for the quarter: firstly, revenue grew by 9% in Q3, including 6.8% organic, which is in line with our guidance. Year-to-date revenue is up 8.1%, reaching $726.4 million at the end of Q3.
Secondly, operating income increased by 28.6% in Q3 and has increased by 38% on a year-to-date basis, reaching $104.4 million, which was driven by improved gross margins as well as the elimination of strategic initiative expenses. Lastly, as it relates to capital allocation, we acquired Vipal, an elevator manufacturer in Italy, in July and invested in the expansion of our Greenville facility while decreasing our debt leverage ratio and ending the quarter with available funds of $337.7 million to support our future growth plans.
Now turning to consolidated revenue: we generated $245 million in the quarter, an increase of $20.3 million or 9% over last year. This includes organic growth of 6.8%, a 1.4% contribution from the acquisitions of Baxter and Vipal, as well as a positive foreign exchange impact of 0.8%, mainly driven by the strengthening of the USD versus CAD.
Looking at the segments, Accessibility revenue increased by 9.1% to $196.5 million, mainly driven by organic growth of 6.6%. Sales increased in all regions, with Europe delivering another strong quarter.
Patient Care revenue increased by 8.6% to $48.6 million, including organic growth of 7.5%. This reflects higher project sales in North America and continued growth from our UK location, which was partially offset by a softer bed market.
Now looking at gross margin and operating income: consolidated gross margin was 39.3% compared with 39.2% in Q3 2025, representing an increase of 10 basis points. Gross profit increased by $8.2 million year-over-year.
This demonstrates our ability to continue to increase gross margins under the current tariff environment. Operating income increased by $7.9 million or 28.6% to $35.6 million, representing a margin of 14.5% compared with 12.3% last year.
The drivers of the increased operating income are increased revenues, gross margin expansion, lower other expenses, and the termination of strategic initiative expenses. Adjusted EBITDA reached a record $52.1 million, representing a margin of 21.2% compared with $47.6 million and 21.2% last year.
Accessibility adjusted EBITDA margin reached 24.2% compared with 23.5% last year, an increase of 70 basis points. Again, that's driven by improvements in both of our key geographical regions.
Patient Care adjusted EBITDA margin was 16.2% compared with 18.3% in Q3 2025, reflecting higher selling and admin costs, an unfavorable product and project mix, and higher material costs. We are working towards improving the Patient Care margins in Q4 of this year.
Net finance costs were $4.4 million compared with $2.2 million last year. Interest on long-term debt continues to decrease and decreased by $0.9 million, mainly due to a lower debt balance.
However, this was more than offset by a foreign currency loss of $1.9 million compared with a gain of $1.1 million last year, the majority of which is unrealized. Net earnings increased by 18.4% to $23.1 million or 32 cents per diluted share compared with $19.5 million or 27 cents per diluted share last year.
Cash flow from operating activities was $36.8 million compared with $41.5 million last year. Cash flow before changes in non-cash operating items increased by $4 million to $41.9 million, but working capital used $5.1 million compared to an inflow of $3.6 million last year.
The largest driver of increased working capital in the quarter was inventory, which we expect to decrease substantially in the fourth quarter ahead of year-end. Cash used in investing activities was $18.8 million compared with $5.4 million last year.
We invested $9.7 million in fixed and intangible assets, including $3.1 million for Greenville on a cash basis for the Greenville building expansion and related equipment, and $9.1 million for the acquisition of Vipal. As at September 30th, the available funds were $337.7 million compared with $311.7 million at year-end, and our net debt decreased to $173.2 million from $191.5 million.
In closing, our Q3 results demonstrate good progress on achieving our long-term guidance. The underlying business is seeing strong growth, which is being helped along by strategic acquisitions.
Our EBITDA margin remains strong, and our balance sheet continues to improve. This concludes my prepared remarks.
I'll now turn the call over to JP for additional comments on our ongoing transformation efforts across the group. JP?
Jean-Philippe DeMontigny
Thank you, Steve, and good morning, everyone. As Steve mentioned, this is the third quarter since we communicated our new strategy, and we continue to make steady progress on both top line and EBITDA, which are in line with expectations.
Let me speak a bit more about how Q3 sales growth across segments and geographies links to our strategic actions. I'll start with North America.
Growth in North America was fueled mostly by home elevator sales. If you recall, our strategy is to expand home elevator sales in low-penetration regions by bringing best practices to our dealers and by engaging with national builders.
We are making great progress on all fronts. We're also continuing to grow our direct stores and professionalize them, with great results.
Also, Matot, our dumbwaiter and material lifts brand, continues to grow well thanks to our combined operational and sales efforts. In Patient Care, growth in Q3 is coming mostly from ceiling lifts sales and installation.
We are reaping the benefits today of our product innovation with the M-Series and the associated sales efforts. Furthermore, we see strong ceiling lifts and bed order intake in Q3.
Even if, Steve was mentioning, we had lower bed sales in Q3, we finished the quarter with a strong order book. Finally, Silvalea continues to be successful in growing sales and reducing costs in the UK.
In Europe, organic growth is partly driven by the success of our commercial actions in B2B, with our dealer business, as well as in our largest direct store in the UK. We are accelerating cross-selling of platform lifts, especially in the UK and NL, two markets in which we traditionally focused on stairlifts.
In Q3, we also launched the outdoor 4000 rail, which has been a big commercial success. Finally, we are accelerating growth in rest of world, and like Steve and Seb mentioned, we now have Vipal with us, which is adding to our sales in Q3.
Beyond sales growth, we're continuing to improve our value proposition, our operations, and our costs. Let me share some examples from Q3.
In Greenville, as Seb mentioned, we commissioned a new paint line so we can build precision home elevator cabs in-house. This has the dual objective, on one side to reduce our costs by bringing this activity in-house, but also to master our quality, and we had great reception from the first dealers that saw it to date.
In Huizhou, our China facility, we commissioned a new metal fabrication shop with some laser cutters, press brakes, and bending capabilities. This allows us to sustain the growth of our business with some in-house fabrication in a low-cost country.
In the stairlift business, we commonized the drawing platforms in Europe for our stairlifts, which allows us to share workload across teams, reducing our lead times and our costs in the long run. In Beamsville, we redesigned the QD1000 bed frame.
The QD1000 is our mainstream entry-level bed, it's now simpler to manufacture, the quality is better, and also we reduced our costs. We did our first batch production in Q3, and now we're ramping up production in Q4.
In St. Louis, we set up a new assembly line for the clinical M-Series lifts to be assembled in the US for us to manufacture locally a product for the US customers.
Finally, in the UK direct business, we improved the service level of our call center while reducing the reliance and the cost for external third-party support. All these are just examples of things we're continuing to do to improve our costs and our competitiveness in each market.
Now, there's also things that are still in motion and that we expect to materialize and come to fruition in Q4 and early 2027. Let me just mention a few.
Seb talked about the Luma L. This has been well received at NAEC, at Grand Designs in the UK, and REHACARE in Germany, and we're planning to launch this product shortly.
We're also planning to launch a new Otolift model, which is currently on track and going through field trials in Europe. In Patient Care, we are continuing to expand the accessories and lineup for ceiling lifts and beds.
As you heard about Vipal, Vipal has been acquired in July, and we're planning to start selling now to our European dealers in the next few months. We also have a lot of procurement initiatives that are still in flight, either to mitigate the risks of price increases or to reduce our costs.
Finally, we continue to have a number of supply chain and operational improvement initiatives across all of our factories. All this to say, in spite of the challenging external environment, we continue to show resilience and to execute our strategy successfully.
Now back over to you, Seb. Oh,
Sebastien Bourassa
thank you, JP and Steve, for those colors. First, before we pass back to Angela, I just want to say thank you to all the analysts that cover Savaria.
You do a very good job, and you're well aware of the story. Angela, I think we are ready for questions.
Operator
Thank you. At this time, we will conduct the question-and-answer session.
As a reminder, to ask a question, you will need to press star one one on your telephone and wait for your name to be announced. To withdraw your question, please press star one one again.
Please stand by while we compile the Q&A roster. First question comes from Frederic Tremblay of Desjardins Capital Markets.
Your line is now open.
Sebastien Bourassa
Hello, Fred.
Frederic Tremblay
Thank you. Good morning.
Morning, all. Just maybe starting with Patient Care, you mentioned that you're working towards improving the margin there in Q4.
Can you maybe break that down a little bit more across the key factors? What are your thoughts on how cost of materials, project mix, and pricing should evolve from Q3 to Q4?
Sebastien Bourassa
Oh, good question, Fred. For sure, Patient Care, again, we had a good growth this year, and we know again we said in April the next few years, the growth, growth, growth is our main objective.
Yes, and we are a bit tough with Patient Care today. Still, when I look at the last three years, okay, we did 19.1% of EBITDA in 2024, 19.4% in 2025, and year-to-date, we're at 18.1%.
Yes, there has been a bit more inflation in that division with the foam and aluminum, I think we are working to offset that. We did a midyear price increase, which is typically not something we do.
I'm confident the margins would come back better in the coming quarter. That would be a bit my answer, Fred, for today.
Frederic Tremblay
Okay. Thanks for that color.
Maybe sticking with margins, but Accessibility, very strong at over 24% in the quarter. I think historically margins in North America were higher than Europe, without getting into specific numbers.
Can you just provide maybe a general update on how margins are trending in each geography?
Sebastien Bourassa
I think, again, without getting too specific, I think the success a bit, as I said a bit during my remark, okay, is we are vertically integrated. We do a lot of things by ourselves, some parts.
We are always very reactive with procurement to try to improve when we do R&D, and we try to launch it at the right price, I would say. On all the legacy, all business, okay, these things continue still happen, and for sure when we make some acquisition in that division, that's a bit lower than the average.
Over time, we have enough project to be able to bring this up. No, it's very positive.
Again, it's our best margin so far. I think we go one quarter at a time.
Frederic Tremblay
Great. I'll get back in the queue.
Thanks.
Sebastien Bourassa
Thank you, Fred.
Operator
Thank you. Our next question comes from the line of Zachary Evershed of National Bank.
Your line is now open.
Sebastien Bourassa
Morning, Zach.
Zachary Evershed
Good morning. Organic growth, I think, has been accelerating for at least the last four quarters if we look at it year-over-year.
If we think about all the work you're doing with your initiatives, European dealers, timing of product launches, what are your hopes for 2027 for consolidated organic growth? Oh,
Sebastien Bourassa
good question. I think I would need to refer to the Investor Day of April.
I think we said that we had the ambition of doing 7% to 8% per year, and I think, again, we did not even finish one year since the Investor Day. No, I think that would be a nice target to continue in that.
For sure, new product is super important. I think we did a lot of work the last two years to be more efficient with our R&D, to launch product at the right time, to have a good sequence of event, and I think we're starting to see some positive out of that.
Again, we have some good action plan with the sales team or which area, part of the world where we can be better. No, I quite confident about the organic growth for the next few years.
Zachary Evershed
Gotcha. Thanks.
Flipping to the other side of the growth equation, how's the pipeline looking for M&A?
Sebastien Bourassa
Oh, pipeline, okay. Far we did two this year, okay.
We know historically we did three, four, I think we need to see over time. No, I think we still have some good opportunity, but again, we are very selective and very diligent on our approach.
Again, we want also to see what's happening with the economy, with the tariff, and so on. Definitely, we want to do 4% to 5% of acquisition per year, if we look at the five years strategy, I'm quite confident we will achieve it.
Again, it might be lumpy. For one year a bit less, the other one a bit more, but overall, if we look on a five years period, we will achieve it.
Zachary Evershed
Gotcha. Thanks.
Then just one last quick one. With the Greenville expansion wrapping up in Q4, where do you think your CapEx is going to fall for the quarter?
Sebastien Bourassa
Steve?
Stephen Reitknecht
It is Greenville's going to be the new edition's going to be opened and ready early early December, it's it's really within the next few weeks. CapEx for this year, as is trending up.
We're kind of in the three high three, 3. 3.8, I think, range right now year-to-date.
We're probably going to be ending the year at around that range, and then next year, next year, Zach, is going to be back more in the 2.5% range of of revenue, but what you're seeing year-to-date, that's going to continue for for Q4.
Zachary Evershed
Understood. Thanks.
I'll turn it over.
Stephen Reitknecht
Merci, Zach.
Operator
Thank you. Our next question comes from Jonathan Goldman of Scotiabank.
Your line is now open.
Sebastien Bourassa
Hey, Jonathan.
Jonathan Goldman
Hey, good morning, team. Good morning, guys.
Thanks for taking my questions. I was wondering if you can just talk about the trends you're seeing in home elevator sales.
It seems to be different than what we're reading about in new home starts in the US, and kind of sluggishness in Canada as well. It seems like you guys are growing and selling a lot of units.
Is that a function of something you're doing internally, whether share gains, new products, or is it maybe a market dynamic that I'm missing?
Sebastien Bourassa
Again, I think if we go back, okay, there's not enough home elevator in term of percentage that are sold into a new house. I think all the effort that we have been doing the last 10, 15 years to train people, I think people are more thinking about that.
I think even if there was less construction, doesn't mean we cannot sell more home elevator. I think also the fact that again we work hard on our options with new cab, touch screen, COP, and so on, okay.
Again, we are trying to gain also some market share. Again, Texas is a place where we bought Baxter because we saw a good opportunity to be better over there.
I think we are making some right effort, okay, with the sales distribution channel, and also with our product lineup that we can continue to grow this segment. Also again, the Luma, you could argue it fit a bit in the through-the-floor and the home elevator market.
Again, through-the-floor, it's a retrofit most of the time application, a bit maybe more cost attractive for customer. Definitely, I think all this segment of home elevator should continue to be good in the next few years for Savaria.
Jonathan Goldman
That's interesting color. Then maybe, I think you guys alluded to this in the prepared remarks, on the cross-selling in Patient Care in Europe.
Is that mainly related to NHS, or is there other sort of product lines that you're expanding beyond that and selling to different sort of channels?
Sebastien Bourassa
For sure, to have success, there's always a few different categories. Yes, NHS has been a super positive to want to help, okay, but also we look at ceiling lift, hoist, okay, this is something that we introduced a few years ago.
Now we start to have more and more traction with that. Again, we moved to a new factory a few two years ago in UK that has really helped us, okay, to be more efficient, to be better, and I think definitely I think we will continue to see some growth in the future in UK and across Europe, right.
Jonathan Goldman
That's good color. Maybe if I could just squeeze one more in.
You guys kind of gave some color on this, and you can kind of see it in the inventory bump in the quarter and kind of the CapEx comments you provided, Steve. How are backlog trends exiting the quarter?
Pretty good growth organically this quarter, and looks like comps are still pretty decent coming up in Q4. How is the backlog trending as you exited Q3?
Sebastien Bourassa
Oh, I would say backlog is quite stable, okay. Again, if we look, no, people, they know our lead time.
They place the order right on time when they will get it, when they need it, okay. I think we have teached a lot our dealer in the last few years to order on time and to get delivery when they need, because again, our production factory are very stable on early time.
It's very rare if we're late, I think it's worked as communication. Yes, the backlog is remained healthy, we're quite happy with that.
Jonathan Goldman
That's good color. Good results.
I'll get back in queue.
Sebastien Bourassa
Thank you.
Operator
Thank you. Next question comes from the line of Justin Keywood of Stifel.
Your line is now open.
Justin Keywood
Good morning. Hi.
Great to see the results. I want to ask on the services or reoccurring revenue of the business and how Savaria Link is progressing, if we're able to have an update just on the percentage of overall revenue that's reoccurring, and if there's a target in either the near or medium term.
Thank you.
Sebastien Bourassa
Oh, good question. For sure, service and maintenance is super important, okay, and right now we're at 10% to 15% of our top line is service and maintenance.
For sure, when we have our direct store, but we have a chance to have also the service with the end user, so that's good. When it is with our dealer, the dealer has the maintenance contract, and also we can have maybe some spare parts after the warranty.
I think the more units you put on the market, the better chance we have, okay, to increase this percentage. Again, Savaria Link is just, again, we're at the beginning, and I think we talk about the initiative in the next five years.
Yes, as we see a good benefit of that to have the best tools for a dealer to troubleshoot their products, to see a bit what's happening with different units. Again, installation time, service time is super important, how can we become more efficient.
I think definitely the Savaria Link will continue to help us on that aspect in the future.
Justin Keywood
Thank you. I assume there's higher implied margins within the services revenue.
Are you able to detail what that is on a gross or EBITDA basis? Oh,
Sebastien Bourassa
unfortunately, we don't go per product or margins, but definitely the service, maintenance usually is a good one, so that's really helping for the total contribution, for sure.
Justin Keywood
Understood. That could be accretive to margins as that services proportion increases overall going forward.
Is that a fair characterization?
Sebastien Bourassa
I think that's a good assumption, yes.
Justin Keywood
Great. Thank you for taking my questions.
Sebastien Bourassa
Thank you.
Operator
Thank you. Next question comes from the line of Cheryl Zhang of TD Cowen.
Your line is now open.
Sebastien Bourassa
Hi, Cheryl.
Cheryl Zhang
Hi, good morning, everyone. Thanks for taking our questions and the color so far.
Maybe I'll start with a question for JP. I think last quarter, you pointed to over 50 new initiatives implemented that help reduce costs, and sounds like there's a lot more in Q3.
Wondering if you can help us get a sense of how much cost savings these initiatives are generating.
Jean-Philippe DeMontigny
Maybe just to answer your question, first we continue to have more or less the same amount of initiatives that are implemented each quarter. In terms of how much costs are going to be saved, I prefer not to give you exact numbers on this call, if that's okay, but it's always a similar proportion, right?
It's at least a third of our impacts or our cost reductions. We continue to drive that, but I cannot give you an exact number.
Cheryl Zhang
Understood. That's helpful, and thank you.
Sounds like you're putting through pricing in Patient Care and maybe a bit in Accessibility as well as you pointed to improved pricing. Curious what you're seeing in terms of competitive activity in each market as you push through pricing.
Sebastien Bourassa
Oh, I'm sure some competitors are on the call. I will not answer for them.
Again, us, yes, it's a discipline, okay, to do some price increase every year, because again, there's inflation, we add some feature on our product, we give increase to our employees. I think it's normal to have some price increase every year.
Again, we have a job to do. We have to remain competitive.
It's up to them to do what they want to do, right.
Cheryl Zhang
Understood. Maybe just lastly, is the inflation pressure still focused just on foam and aluminum?
Are you seeing inflation in other areas as well? Do you lock in the prices for key materials, or do you always purchase at market price?
Sebastien Bourassa
Oh, that's a good question. I would say for sure that the fuel cost had an impact on many different types of material this year.
Again, why we have been able to continue to improve the margins is because we had enough positive project to offset some of the negative that we might have. Maybe this is why in Accessibility we had a bit more, and then in Patient Care, again, yes, foam is a very big part of our purchasing.
Yes, we have been impacted. Regarding annual contract or market, but I would say again, we make a different strategy in our global procurement, maybe different vendor or different product might be different strategy.
It's always depend also what the vendor are allowing to do, right.
Cheryl Zhang
Got it. Thanks very much.
Thank
Sebastien Bourassa
you.
Operator
Thank you. Next person for question comes from the line of Razi Hasan of Paradigm Capital.
Your line is now open.
Razi Hasan
Thanks. Good morning.
Thanks for taking my questions. Maybe just first one for Steve.
Just following up on the Patient Care margin, is there more operating leverage to capture with future price increases in the segment?
Stephen Reitknecht
Yes, there is. To be honest about what we saw in Q3, we were hoping for more operating leverage.
They were able to maintain the gross margins relatively flat. We were hoping that they were going to increase.
The reason why we didn't see that increase was because of the cost pressures that Sébastien alluded to on foam and aluminum. We are seeing operating leverage across all of our business, not just in Patient Care.
Razi Hasan
Fair enough. Thanks.
Then maybe a question for JP. Just in regards to Europe, are there certain countries where you're seeing stronger growth in the region at all, or is it just across the board?
Jean-Philippe DeMontigny
You mean for our business or from the market standpoint?
Razi Hasan
For your business specifically.
Jean-Philippe DeMontigny
For sure. We have different levels of growth by country, okay, I cannot get into the details of which one.
I won't say because that's competitive information. We are more successful in some countries than others, and that suggests to me that there's more potential for the future to catch up on the other places where we're maybe less growing not as fast as in some other countries.
Razi Hasan
That's helpful. Then maybe just on M&A in the region, is your focus on dealers and manufacturers or either/or?
Any thoughts there? Then maybe just valuations you're seeing there.
Sebastien Bourassa
I think the mix of both has been a bit the success so far. Again, a new product is always super, because we can improve our one-stop shop, and then we have 1,000 dealer that are excited about it.
Definitely, when there's opportunity on product or a small manufacturer, we look at it. A dealer, for us, again, we have some dealers sometimes that want to retire.
We're a very natural buyer, so that's always interesting. In term of multiple, I would say, again, we always try to pay the right price for business.
I don't think people call us because they are in distress and they need to sell at discount. I think usually we pay the fair price.
Razi Hasan
Great. Maybe just lastly, when you talk about Europe and rest of world, what percentage of that does Europe make?
I'm assuming it's the bulk of it, but do you guys break down what percentage Europe is in that segment?
Sebastien Bourassa
It's combined together, no?
Stephen Reitknecht
Europe and rest of world is combined. Sorry, was that your question, Razi, how much
Razi Hasan
Yeah, exactly.
Stephen Reitknecht
We don't get into that level of disclosure.
Razi Hasan
Fair enough. Thanks for taking my questions.
I'll leave it there. Thank you.
Operator
Thank you. The next question comes from the line of Michael Glen of Raymond James.
Your line is now open.
Sebastien Bourassa
Hi, Michael.
Michael Glen
Hey, hello. Sébastien, maybe just curious if you could provide any insight into organic within your direct network versus the dealer network in Accessibility in North America.
Sebastien Bourassa
Good question. For sure, again, it's always a balance.
What is interesting with when we have direct store, again, we can always test our marketing idea. We can test our few products to make sure things work, then we're able to teach our dealer how to improve also.
Definitely for us, again, the success is a mix combination between direct store and dealer. Unfortunately, we don't disclose the growth in one or the other, that will start to be a bit too much details, but I would say it's a combination of the two that has made the success, no.
Michael Glen
Okay. I just want to come back to the inflation question, and I just want to focus on again, Accessibility, and steel and aluminum input prices in that segment, how you are managing those costs.
Sebastien Bourassa
Again, a bit to go back over the answer earlier. Yes, there has been some inflation across the globe, okay.
I think we have done enough effort to have positive project to be able to offset some of the inflation, no. I think, yes, container price are up, transport is up, yes, some of the entrant is up, but I think at the end, we had enough positive project this year to offset the things.
Also don't forget our plant in China, okay. Again, things are relatively stable, there's less inflation than maybe we had in North America, right.
Michael Glen
Last one for me. In the past couple years, Patient Care has had a bit of a Q4 bump on its top line.
I'm just wondering if that would be expected this year, or we might see a different trend.
Sebastien Bourassa
Again, it's for sure in Patient Care, okay, there's some end of the quarter that some government fiscal year and so on, yes, I would be disappointed if they don't have a good Q4, right.
Michael Glen
Okay. Thank you.
Sebastien Bourassa
Thank you.
Operator
I am not showing any further questions at this time. I would now like to turn the call back over to Sébastien for closing remarks.
Sebastien Bourassa
Thank you, Angela, and thank you for all the analysts for your good question, okay, that it's always interesting to talk about Savaria. Again, we have a growing story with the aging population, people want to stay at home, I think definitely we're in a good segment, good business, and really can continue for the next few years.
Thank you, Angela. We'll see you next quarter in March.
Thank you.
Operator
Thank you for your participation in today's conference. This concludes the program.
You may now disconnect.