engcon AB Class B
Q3 FY2026 · Earnings Call TranscriptOctober 29, 2026
Stig Engström
Good morning, and welcome to Engcon's Q3 report presentation. My name is Stig Engström, CEO, and with me today I have our CFO, Marcus Asplund.
Let's start our report presentation for the third quarter. In some ways, the third quarter was another lost quarter.
Still war in Europe, and the conflict in the Strait of Hormuz seems to be far from resolved. Beside these military conflicts, we also struggle with trade wars.
Of course, the conflicts hits the economy, affecting interest rates and increased fuel prices. Altogether, it has a negative impact on our end customers' will for new investments.
Older excavator fleet gives more spare parts and service need. That's good business for Engcon, but now we want to increase our new product sales.
This shows in our numbers. Demand is weaker, and the order intake fell 10%.
We cannot blame everything on the world around us. I'm not satisfied with what Engcon has achieved, either before I took over or since.
Sweden, our main market, stands out as the strongest. Sales have recovered to historical high levels.
Economic uncertainty is holding back demand across the board, but France, an important market for us, has been a clear disappointment in 2026. Here we need to look ourselves in the mirror and question our priorities.
One positive thing is that we finally have an agreement with OilQuick and Steelwrist. We have put in writing a partnership that has worked well for a long time.
Now we can look ahead and take it further. More on that later.
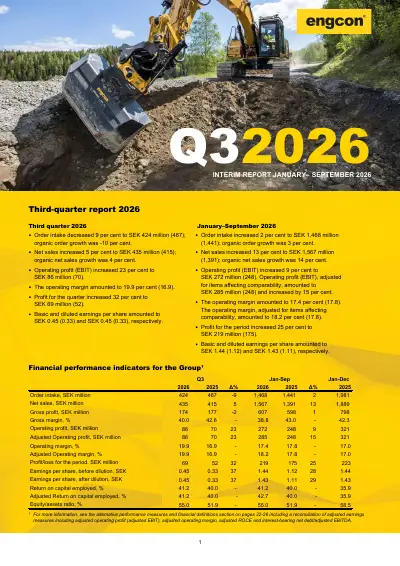
Profit improved in the quarter. The operating margin happened to reach 20%, our financial target.
Tighter cost control helped, but let me be clear, currency saved the margin. Gross margin remains a challenge.
We cannot control an uncertain world. Things do not always go our way, but our direction stays the same, and the work towards our financial targets continues.
Let's take a look at the numbers. After a good start the first half-year, it calmed down again, and the sales came out weaker than we had hoped.
Uncertainty in diesel price and interest rates lay like a heavy, wet blanket over the investment mood. We just managed to increase net sales thanks to the Nordics.
Order intake, especially parts of Europe, lower than expected. The gross margin is mainly affected by low production level and our decision to invest in personnel and production process instead of cutting cost.
As mentioned, currency saved our EBIT margin. Order intake fell with 10%, which is unusual for us.
Europe, that should be our growth engine, was weak in this quarter. Gross margin was 40%.
The new price and product packaging connecting to the Series 1, 2, and 3 is helping. We also have more production capacity than we need in Strömsund and Poland.
This puts pressure on our margin, too. This is a deliberate choice to have capacity and competence ready to day the market recovers.
The EBIT margin was 20%. Currency movements were the main reason.
We have introduced tight cost control, mainly in administration. We saw some results this quarter, but more will come.
Return on capital employed was 41%. We need to reduce our stock levels.
Do not see full effect yet. They are too high, especially in markets far away.
Marcus will talk more about the financial numbers later. The picture puts the sales in perspective.
Order intake was lower than expected after the summer holidays, and as I just said, there are several factors behind this. We may also have received more orders in the spring before the price change in conjunction with the Series 1, 2, 3 launch.
A tiltrotator pays for itself quickly, even or especially in difficult times. Jobs will be done more efficient, gives more work, and reduce fuel costs.
The tiltrotator system is here to stay, over good or bad times. Let's take a closer look at different regions.
Most of our growth this quarter comes from the Nordics, but the performance varies across the region. Sweden continued to recover.
Excavator sales have picked up in all shapes and sizes. Engcon has a strong market share, and we're growing along with it.
Large investments in road infrastructure are driving demand. Many customers have delayed buying new machines for some time, but they have now reached the point where they need to replace them.
We can see that in our spare part figures. Another positive is the launch of our Series 3 product.
Customers have responded well in our largest segment, machines of around 19 tonnes. Our unique product help us avoid competition.
Norway has now passed the bottom. Machine sales have increased after a real bad period.
We have taken market share and built our own local team, which is appreciated by dealers and customers. Normally, Norway is a little bit behind Sweden in the business cycle, and hopefully their increase will come 2027.
Finland has been slow for a long time and has the weakest economy in the Nordics. We are gradually hearing more positive views from the dealers and customers, but we can't see that in our figures yet.
Denmark is closest to Central Europe and seems to have felt the same weakness this quarter. Business did not really pick up after the summer.
The region has performed well during the year, but we want more. Europe should be our main source for growth, but we are not seeing that happen in Q3.
The Netherlands is driving growth in the region. We are well placed with a strong local team, and the tiltrotator use is growing.
Still a lot here to do, but they are best in class. France is the biggest disappointment.
The economy is weak with growing budget deficit. The political situation, as you can see in all news, makes the future hard to plan.
All this is bad news for our business. We also have ourselves to blame.
Focused on wrong priorities for a long time. A long reorganization has also kept us away from the right things.
In DACH region, we had no large orders this quarter comparing with previous years. We now have the right conditions in place with a new collaboration agreement.
I will come back to that shortly. Americas, performance was weak in this quarter, and that was expected.
We are following our plan, though we reduces our focus and cost. We have a new country manager in place with mission to build a solid organization.
We have also taken stronger steps to reduce stock levels and administration cost. The market is good in general, despite all the things going on there.
There's plenty of work, and we remain positive about the region in the long term. Asia-Oceania, we are seeing changes from a low starting point.
We have also taken stronger steps to reduce stock levels, especially Australia. We have signed a collaboration agreement with OilQuick and Steelwrist.
The Schauer family has done an impressive job over many years, developing the German market for our joint tiltrotator offering. The agreement does not fundamentally change how we work, but just have it in writing.
With the agreement in place, we can take our collaboration to the next level and start reduce our own cost. The agreement mainly say that we are appointing OilQuick and Steelwrist as the exclusive distributor of our joint tiltrotator offering.
In turn, Engcon will become the exclusive supplier of the tilting and rotating part, so-called yellow heart. Together, we have now laid the groundwork to increase market penetration in Europe's largest excavator market, and I'm convinced that this collaboration will continue success for many years to come.
In September, we made our first trade show together, GaLaBau. The Schauer family has made substantial own investment in new facilities for assembling and impressive demo area, including showrooms.
They will have the possibility to take customers from the whole region to their premises for demo, testing, and education. With this partnership in place, we are convinced that we have done the best we can in the DACH region, and now we can focus our own resources in other regions.
With that, thanks for me for now, and over to Marcus.
Marcus Asplund
Thank you, Stig. Let's take a look on how the quarter came through in the P&L.
Net sales came in at 435 million SEK, a modest 4% organic increase. The Nordics, and in particular Sweden, are driving sales at the moment.
For the first time in a while, currency actually worked in our favor. Norwegian krone strengthened, which helped just as our sales in Norway were growing.
Gross margin at 40%, that's down on last year, but an improvement from Q2. A few things here worth highlighting.
First, market mix worked against us. Most of the growth came from Nordic markets, which leaves a footprint on the margin as pricing is more competitive.
At the same time, volume reduced on high-margin markets in Europe and overseas. We also had lower fixed cost absorption in production.
As Stig mentioned, we have spare capacity in both Strömsund and Poland, lower sales leaves us with less volume to spread those costs over. On top of that, we have depreciation related to the Series 3.
On a positive note, the pricing review tied to the Series 1, 2, 3 launch began yielding results in the second half of the year. While most of the benefit were realized in Q3, additional gains are expected moving forward.
Selling expenses improved slightly, primarily driven by the timing of trade fairs, events, and reduced sponsorship costs. Administrative expenses were flat versus last year.
Lower ERP costs were offset by other initiatives, mainly development of our new e-commerce platform. We have now rolled it out in all of our markets, and we see it as an important step to enhance future growth and revenue streams.
We also had a sizable currency gain in other operating income. This mainly relates to receivables in foreign currencies.
In 2025, this worked against us. We're now seeing some of that come back.
EBIT came in at 86 million SEK with a margin of 19.9%, just below our financial target. The weaker sales is clearly showing, particularly as a smaller share of sales came from higher-margin markets outside the Nordics.
At the same time, we should be clear that favorable currency movements provided a substantial boost to this quarter's result. Putting EBIT into perspective, a 19.9% EBIT was a strong result, although we'd naturally have preferred a different mix of drivers behind it.
When sales outside the Nordics pick up again, we expect that to help margins, combined with continued cost discipline that should give us a solid foundation for profitability, growth over time. Cash flow from operating activities improved, driven primarily by higher operating profits and positive changes in net working capital, namely accounts receivables and inventory.
We are continuing to see smaller positive effects of improving net working capital management in the quarter, but as Stig mentioned earlier, there is more to do here. Higher investment activities are attributed to the estate in Poland as well as improvements in Strömsund.
Loans taken out now in October with 27 million SEK for the Poland facility and 10 million SEK for the Strömsund extension. Return on capital employed remained above our long-term sustainable target, coming in at 41.2% and 42.7% adjusted.
On that positive note, I'll pass it back to you, Stig, to summarize and give us an outlook.
Stig Engström
Thank you, Marcus. Many challenges remain in the global economy, and it's difficult to say when the market will turn.
I'm not satisfied with our performance in the quarter and how we have acted. However, this does not change my strategy.
We will continue to dig where we stand and focus on what we can influence. Continue to develop our successful collaboration with OilQuick and Steelwrist for the biggest excavator market in Europe.
Being our customers' first choice by offering the right product for the right market at the right price. Strengthen the organization to increase our focus on end customers while rolling out an e-commerce platform.
Continue to work to create the right conditions for profitable growth, with cost focus and firm action to reduce stock. On sustainability, we follow international regulation and initiatives, but we are also taking local action to reduce our use of fossil fuels.
Heating in our facilities should as far as possible be fossil-free. Global travel should be kept to minimum, and shorter journeys should be made by train.
Our own vehicles should run electricity or HVO, and our ambition is to make it easier for all our employees to choose renewable fuels. We're not doing this to improve the bottom line; it's our contribution to the survival of the planet.
Right now, we have excess capacity in our facilities. This is a choice we made.
It's hard to tell when the market is back, but I'm hopeful for the coming digging season in the Nordics. Nevertheless, we will be ready with capacity and skills to change the world of digging.
That's everything we had for today's presentation, and now we're happy to open for your questions. Please feel free...
Operator
If you wish to ask a question, please dial pound key 5 on your telephone keypad to enter the queue. If you wish to withdraw your question, please dial pound key 6 on your telephone keypad.
The next question comes from Zino Engdalen Ricciuti from Handelsbanken. Please go ahead.
Zino Engdalen Ricciuti
Yes, good day and thanks for the presentation and taking our questions. Starting off, you of course talk on the demand side about the macro factors that have impacted, but earlier in the year you've also done some reorganization measures.
How [would you?] say that those have impacted the group in this quarter?
Marcus Asplund
Was a little bit hard to hear, but I think I got it. The reorganization, yeah, that it coincided, for one market, it's French then market where we also had that, but that wasn't really in that reorganization that we did on the biggest scene.
It kind of coincided with that, and it's had taken a longer time on that. That's was particularly then for the French market, I would say.
Zino Engdalen Ricciuti
Understood. Given how much the Americas is down on a similar topic, how much of that is a change of, as you said, your regional priorities, and what should we think ahead?
Stig Engström
The big decrease is of course because we have taken away stock, we have taken away personnel, and of course, even though we may still have the personnel we need, but of course this makes some worries in the organization and so on, we need to start all over, and I'm quite sure that this decision to slow down the US market also affected on the numbers. We were ready for that, but in the total revenue of Engcon, it's quite a small numbers.
Zino Engdalen Ricciuti
Okay. Last question for me, of course, if we go back to the previous quarter, you sounded optimistic to reach your margin target at the end of the year.
Of course, the outlook sounds a bit worse now, but what's your expectations on when to reach the margin target? Hopefully,
Stig Engström
of course now we had the currency with us, but hopefully we will see bigger impact of our own things have done so far. Of course, we have just worked with this now for three or four months, but hopefully for three another three months more we can see more from the inside.
We may probably need some help from outside as well, but I think quite positive of that we can see positive things happening three months from now. If we're talking about the market will come back, normally when we now talking about coming back into the Nordic markets mainly, of course then we have to wait for the springtime normally, then we're talking about March, April before we can see a big impact.
Hopefully we'll have something in December coming in, but normally we have to wait for the digging season to come.
Zino Engdalen Ricciuti
Understood. Thank you.
I will get back in line.
Operator
The next question comes from Agnieszka Vilela from Nordea. Please go ahead.
Agnieszka Vilela
Thank you, and good morning, Stig and Marcus. I have a few questions.
Maybe coming back to the order trend in Europe, can you tell us is this 20% down organically in orders in Europe, is it because of the overall market slowing down, or is it more due to what you, Stig, mentioned, a kind of blip in your own performance given the changes in your leadership team and restructuring that you have been doing in these markets?
Stig Engström
I think it's the most will come from ourselves, that's for sure. Of course we had bigger customers earlier, and of course they were more sensitive for global change.
If we have worked the way we should work from end customers' perspective, it shouldn't be a problem. We know that France has something like 70,000 excavators working every day.
They are selling something like 20,000 machines every year. It shouldn't be a problem for us to sell 1,000 tiltrotators if we've done it the right way.
I think it unfortunately has most to do with ourselves.
Agnieszka Vilela
Understood. Maybe on that topic, do you see more stability in your own organization in Q4, and also what impact would you expect from these kind of a bit tightened with OilQuick and Steelwrist?
Stig Engström
We have done a lot internally for our organization. Even though I say I have not satisfied with the quarter, but we have done a lot of good things internally, and I think we can see the results from that coming up next quarter, that's for sure.
We're talking about Germany, I think they have done great investments down there themselves, and of course take a lot of focus from them as well, I think they also have taken a step back from the marketing for the moment just to build up the internal capacity, but they will come back, and then even stronger than before.
Agnieszka Vilela
Perfect. Then maybe a question to Marcus or to you, Stig.
Q4 usually is stronger than Q3 in terms of orders. Do you expect a similar development this year and maybe in relation also to your pricing strategy, and what have you seen so far in October when it comes to orders development?
Marcus Asplund
If I start then, yeah, usually we have a pre-ordering behavior from the Nordics into the digging season, and as Stig mentioned, we feel a little bit optimistic at least for the Nordics coming into the digging season. That is expected to follow similar patterns.
Having said that, since Europe is not really where it should be, we saw some bit of a pre-ordering from Netherlands last year, the first market outside the Nordics that actually had a little bit of a pre-ordering behavior, signifying a maturing market, if you like. It's a little bit hard to say.
Nordics, yeah, still believe that there will be a pre-ordering pattern like we have seen before every year. The question then is if we're so far in our new way of doing this that we can see that also Europe picking up.
Agnieszka Vilela
Thanks. I have two more questions, if that's possible.
For 2027, to come back to the 20% sales growth that's your target, when do we need to see a pick-up in order intake? Is it Q4 already, or do you think even if we don't see it until beginning to 2027, could still deliver on the 20% growth target?
Stig Engström
We can change quite fast because we have got the delivery capacity and it change really quickly. I think we can have good trust for that also if we have to wait a part into 2027.
I think in the end of quarter one, we need to see some sort of change.
Agnieszka Vilela
Understood. Then the last one from me.
As Stig, you mentioned that you are developing the new e-commerce platform, if you could share a bit more information about that, and don't you see any risk that you will be competing with the dealers in how you sell your products to customers?
Stig Engström
No, we're not doing that. Our idea is to have better contact with our end customers, and a good way to do so is to have the simple products we are producing, mainly buckets and things like that, on the website.
Also some spare parts and some used equipment that we use normally from our shows and also if we have some coming in for other customers, that we have a really good commerce platform to come in contact with end customers. That is the real goal with it, to come in commercial relation with other customers that we not know about.
That's the reason. All our OEMs, these knows about it, and normally they have their own brands, we are not competing.
We are already competing today, so that's not a problem.
Agnieszka Vilela
Yes. Perfect.
Thank you.
Operator
The next question comes from Emil Zaar from Danske Bank. Please go ahead.
Emil Zaar
Good morning, Stig and Marcus. I'm just curious about the price hikes that you've been doing.
You mentioned that there were sort of a pre-buying in the spring. How much do you think that will affect into Q4, but also how much did now in the order books as well as the trend?
Do you see more competition now to your competitors with a higher price?
Marcus Asplund
No, I think we are all struggling a little bit in this now, including our competitors, or at least that's what we hear. Look into specific markets here to see it is, of course, there's been certain markets there's fierce competition, but that's not something new, and we don't really see that escalating now either.
Actually we see that the launch of the 1, 2, 3 Series makes it easier also for us to get the right product to the right customer here, and also for our sales team easier to communicate in that sense. We don't really see any.
Of course, might have been some, but not to lost orders as such. Maybe to push a little bit on the margin sometimes, but otherwise we have seen it come in and the new price list being fulfilled, and of course that will continue during this quarter as well into the digging season.
Emil Zaar
All right. I also have another question regarding the high inventory levels that you had previously.
You mentioned that you have had some kind of older products that you have to phase out. Did that affect margins now, or would they margin-creep or margin-dilutive or just the same?
Marcus Asplund
There has been some in this, of course, when we're doing this, we have had some when we look into the stocks, especially in the faraway markets, done some rewrites or write-downs there for certain things, older products and so forth, but it's not that this is a big impact on the margin.
Emil Zaar
All right. Thank you very much.
Operator
There are no more questions at this time. I hand the conference back to the speakers for any closing comments.
Stig Engström
No, nothing more from me. Anything from Marcus?
Marcus Asplund
No, nothing more.
Stig Engström
Okay. Thanks again for tuning in today.
Marcus Asplund
Thank you.
Stig Engström
Thank you.