Smurfit WestRock plc
Q3 FY2026 · Earnings Call TranscriptOctober 28, 2026
Operator
Today, and thank you for standing by. Welcome to the Smurfit Westrock 2026 Q3 results webcast and conference call.
At this time, all participants are in a listen-only mode. After the speakers' presentation, there will be a question-and-answer session.
To ask a question during the session, you will need to press star one one on your telephone. You will then hear an automated message advising your hand is raised.
To withdraw your question, please press star one and one again. Please be advised that today's conference is being recorded.
I would now like to hand the conference over to Ciaran Potts, Smurfit Westrock Group VP, Investor Relations. Please go ahead.
Ciaran Potts
Thank you, Sarah. As a reminder, statements in today's press release and presentation, and the comments made by management during this call, may be considered forward-looking statements.
These statements are subject to risks and uncertainties that could cause our actual results to differ materially from our expectations and projections. These risks and uncertainties include, but are not limited to, the factors identified in the earnings release and in our SEC filings.
The company undertakes no obligation to revise any forward-looking statements. Today's remarks also refer to certain non-GAAP financial measures.
Where applicable, reconciliations to the most comparable GAAP measures are included in today's earnings release and in the appendix to the accompanying presentation, which are available at investors.smurfitwestrock.com. Before I hand you over, please note that Tony and Ken are stepping away from the board this morning and rejoining after our call.
In the interest of time, I therefore request that you ask no more than two questions. I'll stay on the line should we have any technical issues in Brazil.
I'll now hand you over to Tony Smurfit, CEO of Smurfit Westrock.
Tony Smurfit
Thank you, Ciaran. As Ciaran has just said, we're hosting today's call from our Três Barras mill in Brazil, Latin America's largest country with a population of some 213 million people.
Três Barras is a state-of-the-art kraftliner mill with an annual capacity of approximately 700,000 tonnes. This operation is a great example of successful investments of approximately $350 million over the last 5 years delivering superior returns.
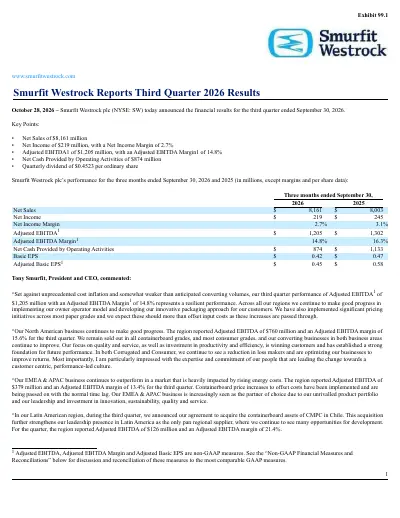
It is integrated downstream into our Latin American box system, primarily in Brazil, Argentina, and soon to be Chile, and significantly integrated upstream into our sustainably sourced forestry operations. As you will have seen, we've announced third quarter adjusted EBITDA of $1.205 million with an adjusted EBITDA margin of 14.8%.
These results show great resilience in the face of unprecedented and greater than anticipated cost inflation, predominantly, but not limited to, energy and freight. To counteract these cost increases, we have, by necessity, implemented price increases across most paper grades, which are being passed on with the normal time lag.
The period was characterized by a number of one-off events, such as extreme heat waves in Europe, earthquakes in Colombia, and a significant contamination issue in the agriculture sector in the United States, affecting our volumes both there and in Mexico. Since the formation of Smurfit Westrock, I'm incredibly proud of the many achievements we have accomplished, especially the way we have brought the two companies together and formed one culture.
Operating in 40 countries, we have unified the company under one banner, with a focus being the owner-operator model, which resonates and is well understood both internally and externally. We have developed a strategic plan, which we presented to you in February, that takes the company to a different level through our own actions and investments to improve efficiency and our offering to our customer base.
We've refocused the company at our end customer through innovation, quality, and service. Turning now to a regional overview, our North American business continues to improve in most areas, although this improvement is masked by the amount of increased costs that we have incurred.
The third quarter showed sequential improvement in our corrugated volumes, with a continued and developing strong pipeline. Our people have embraced our new Smurfit Westrock performance-led and owner-operator culture, and this is reflected by our improvements across all customer service metrics and our attention and retention of talent.
Today, our mill system across practically all grades remains sold out, allowing for us to prioritize orders and improve our business mix. The real benefits of this will be apparent as we move into 2027.
In our converting businesses, we are progressively getting better through continuous investments with teams of highly motivated people across both business areas of corrugated and consumer. As we roll out our innovation centers, we continue to benefit from our cross-selling opportunities as a major competitive advantage.
In another business area, we've seen a large structural shift towards our paper bag and sack business, where we are the largest producer in the United States. Finally, while demand in our Mexican business is as weak as I have experienced it in recent years, our footprint is continually being strengthened by significant cost takeout initiatives and rationalization measures.
Now turning to our EMEA and APAC region, where we continue to outperform our integrated peers. Our innovative offering delivers solutions to our customers that help them navigate an increasingly complex regulatory environment, especially in Europe.
By partnering with Smurfit Westrock, our customers take regulatory compliance as a given, solving a key supply chain issue for them. As in other regions, we've implemented paper price increases to recover costs, which are being progressively passed through.
These increases are primarily a consequence of the spiraling cost of energy that has shown no signs of abating during the year and is reaching levels that we have rarely seen. Over the last number of years, we have made many investments in both our mill system and conversion operations that have considerably improved our quality and service KPIs, giving us further competitive advantage.
Some of those investments are also targeted continuing to reduce our cost base and drive operating efficiency, which have helped somewhat to offset some of the cost pressures we have seen this year. We have also continued to rationalize our footprints, making our asset base more efficient, which will enhance future returns.
Our experienced management team in this region has the skill to both navigate the current difficult macro environment and continue to outperform. In Latin America, while the region faces many of the same challenges experienced in other regions, our returns, and in particular our adjusted EBITDA margin, remained at excellent levels.
We have strongs market positions, a well-invested world-class asset base, together with, again, skilled and experienced operators. We continue to look for ways to develop our offering in the region, and I was particularly happy to announce our agreement to acquire the world-class packaging assets of CMPC during the quarter.
This acquisition will strengthen our position in both Chile and the wider region, as well as adding further paper integration to our system. Also during the quarter, we started up our circa $100 million investments in our biomass boiler in Colombia, which is helping to offset energy price increases in that country.
Paper prices are rising in the region as international shortages feed into the market. For the full year 2026, we now expect adjusted EBITDA of approximately $4.7 billion.
This primarily reflects the unprecedented cost inflation we continue to experience across the business. Freight and energy costs alone are expected to represent approximately $700 million year-on-year headwind in 2026, materially above our earlier expectations.
As we move into 2027, we believe the actions we've taken during the year will more than offset these costs. What I'm most satisfied with is the great work that has been done across the organization in every region to improve efficiency, reduce our costs, further develop our innovation offering, and improve our asset base.
As a truly global paper and packaging company with an unparalleled product portfolio and the widest geographical reach, it is ultimately our customers who benefit most from our extensive offering. As we develop the company through our investment program and through our culture, I am confident of the foundation we're building for 2027 and beyond.
With that, operator, we will hand it over to questions.
Operator
Thank you. If you would like to ask a question, you will need to press star one and one on your telephone and wait for your name to be announced.
To withdraw your question, please press star one and one again. We will now take the first question.
This is from George Staphos from Bank of America. Please go ahead.
George Staphos
Good morning, everybody. Good afternoon.
Thanks for taking the question, the details. I'm here with Reinhart van der Walt in Europe.
I guess two questions, Tony. Can you talk about the progression on volumes in North America?
At one point, you expected to be up at some point in the back half. Is that still the projection?
Relatedly, I think you had a profit improvement in terms of the bridge from volume, even though volumes were down in third quarter North America. How do we reconcile that?
Then second, given that energy and freight would seem to be largely a box-related expense, certainly it's going to affect both converting and production, but does the fact you're seeing so much pressure on where you had the most or the least amount of margin headroom to begin with in converting, does that change your philosophy in terms of how you try to push pricing and improve commercial terms over time? Thank you, and good luck in the quarter.
Tony Smurfit
Thank you very much, George. With regard to progression, as I said, that we expected either in the third or the fourth quarter that we would start to be there or thereabouts with the previous year.
Obviously, the third quarter has been very heavily impacted by this [sicnospora?] Sicnospora and the E.
coli situation that affected our agricultural region very significantly. I think from the good news point of view is, and one swallow doesn't make a summer, but for October, we are line and ball with last year.
It looks like our order books are reasonably good for November at this stage. Again, as I say, one swallow doesn't make a summer, but I do think that our progress each quarter has been a bit better.
As we see the volumes that we gave up last year come out of our business and the comparisons becoming easier, we would say that we are going to be there or thereabouts in due course unless something happens with regard to the market that we don't expect. I think the progression is as we expected.
What I'm very encouraged about, honestly, George, is when I see the customer wins we're having. They're smaller in size than when you lose one of the big ones, and it takes a lot of them to replace a big one, but our quality and service levels have improved very significantly.
Our attitude because of the owner-operator model is very well liked by our customers and liked by our internal people. Our innovation offering, as we start to roll that out, is really a very big positive.
I see us going where we want to go to, maybe sometimes a little bit slower because the underlying market is not as strong as we would have liked, but overall, I think it's going exactly as we would have anticipated. With regard to your bridges, I'll hand it over to Ken.
Ken Bowles
Hey, morning, George. Morning, Reinhart.
Keep it simple, George. The net positive volume in North America is, remember, we have a lot of third-party sales.
The positive growth you've seen there is really third-party paper sales.
George Staphos
Okay. Then on the pricing and the pressure scene in converting?
Tony Smurfit
On the converting, I wouldn't say there's anything difference. We are having to go to our customers and sort of recognize the fact that we've got other costs than just paper.
Clearly, we have to recover those as we go through the year, and either through negotiation or through making sure that we have a special tie-on for certain customers. We're continuing to develop our margins in our corrugated business.
We have reduced our lossmakers very considerably. I think we're at less than 30 lossmakers.
Some of them it's a bit difficult when the paper price goes up. Obviously, there's a period of time where the corrugated operations slip backwards because they have to go into the market and get those paper prices up to see where we are right now.
Overall, I think that we are making very good commercial progress across the business, and I'm really happy with our commercial team and the customer wins they're winning and getting pricing going forward.
Ken Bowles
George, I think you can see that, George, a little bit if you look at the North American margin quarter 1, 2, and 3, you see progression on the margin build there. Equally, while we're dealing with the normal time lag, you can see progression of pricing also, right?
Sequentially, quarter 2 into quarter 3, North America pricing up about 5%, and in Europe equally, pricing up with 2% quarter 2 to quarter 3. The impact of the price increases from paper into box is beginning to take hold, and as Tony said in his prepared remarks, really setting that foundation for '27.
The actions you're doing are still on track, no change to philosophy in that sense.
Tony Smurfit
George, we would love it to be quicker, but the reality is that we're being whacked by these massive cost increases in energy that we are going to get back. As we announced a €100 a tonne increase.
The publication recognized 70 of that. Obviously, from our perspective, we would have expected to get 100, but we'll wait and see what happens going forward.
George Staphos
Understood. Enjoy the trip.
See you soon.
Tony Smurfit
Thank you.
Ken Bowles
Thanks, George.
Operator
Thank you. We'll take the next question today.
This is from Hillary Cacanando from Deutsche Bank Securities. Please go ahead.
Hillary Cacanando
Hi, thank you for taking my question. Just going back to the North American converting business, last quarter, you mentioned that corrugated converting margins were roughly 3% to 4%.
Can you update us on where that converting margin stand today?
Tony Smurfit
It's a little bit lower than that now, Hillary, because we take in the paper price into our converting business. We transfer at the market price, so, therefore, it'll be a little bit less than the 2% number now because we have to then go to the market and get that increase into our box system.
The underlying trend of margin improvement within our corrugated business is quite significant, and you'll see that as we go into Q1 and Q2 of next year as we pass through this latest paper price increase.
Hillary Cacanando
Got it. Thanks, Tony.
Then as a follow-up, with 2026 EBITDA now expected at roughly $4.7 billion, how should we think about that lower starting point relative to the medium-term plan? Is the shortfall predominantly timing around price cost recovery such that the underlying 2030 earnings opportunity is largely unchanged?
How should we think about that relative to the 2030 plan?
Ken Bowles
Hi, Hillary, it's Ken here. Essentially, it's timing.
In reality, the plan was set up to bring us from, call it, '26 to 2030. Nothing within the plan from a structured perspective has changed.
If you recall when we talked in February, that plan was largely built on internal actions and a lot of kind of internal opportunities that we had to kind of get through, like kind of working through the unprofitable contracts and getting to positive volume growth in North America, for example. Pricing wasn't necessarily part of that kind of proposition, if you like.
Clearly, the backdrop in cost for 2026 has kind of impacted the timing, but not the recovery or achievement of the targets, but only the timing in terms of when we'll get there. The 2030 target is still bang on in terms of timing.
It'll just be kind of a flex in between the years and how we get there.
Hillary Cacanando
Great. No change to 2030 plan.
Great. Thank you so much.
Ken Bowles
Thank you,
Tony Smurfit
Hillary.
Operator
Thank you. We'll now take the next question.
This is from Phil Ng from Jefferies. Please go ahead.
Phil Ng from Jefferies, your line is open. Please ask your question.
Tony Smurfit
We can go back to him there, Sarah.
Operator
Sure. Let's move on to the next question.
This is from Mike Roxland from Truist Securities. Please go ahead.
Mike Roxland
Thank you Tony, Ken, Ciaran, and team for taking my questions. First one I had, the industry's gotten about $170 per ton of price this year.
Of that amount, how much do you estimate is for cost recovery versus margin for you guys in particular?
Tony Smurfit
I would say that the first 100 is really really just basically recovering the costs. Obviously, Mike, the cost thing is a moving target, as you will have seen from our numbers, because when we were here in 3 months ago, we did not expect TTF gas to be at 97 or 98 as it is this morning, nor did we expect diesels to be where it is or some of these other energy costs.
We would have thought that the first 100 would have had some margin improvement in it, but clearly, I'd say the vast majority of that has been gone in these current high prices. As we translate the other increases through the more recent increases, that would probably be all margin enhancement, I would say, broadly speaking.
Ken Bowles
I think Tony kind of referenced it there, the July increases, the $100 a ton we put back end of July, I think up to that point, the increases to that date would have really dealt with the cost recovery piece and probably did recover a margin. That 100 would have overcome any remaining piece, but also purely margin.
As Tony just said, since then, clearly the cost backdrop has continued to be elevated and unanticipated. Still a lot of costs would have been a margin there, but probably again pushing out timing slightly in terms of '27 versus where it might have been, but still on track.
Mike Roxland
Got it. Very clear.
Just one, when you think about '27, given the lower stepping-off point, can you provide us with an initial peak at what you're expecting in terms of either demand, maybe some of the larger buckets or guideposts around what's going to drive EBITDA next year? Thanks.
Tony Smurfit
Mike, we haven't done our budgets yet, so, I just I I do know that our guys are very comfortable and confident that our our numbers will be, significantly better based upon the run rate that we're going to come out of last year, but we haven't actually got to do our budgets yet. We're doing those next week.
I would say that we still The early The The early view is that we are very comfortable and confident that next year will be a very good year for us if everything stays relatively where it is today. Clearly, there's still a lot of uncertainty in the world, and and if we have some relief on on costs, then that will be very positive to us, but equally, if we don't have relief on costs, we will have to look again as to what actions we might take to to mitigate those costs as we go into Q1, Q2 next year.
Mike Roxland
Understood. Thank you.
Tony Smurfit
Thanks, Mike.
Operator
Thank you. Next question today is from Mark Weintraub from Seaport Research Partners.
Please go ahead.
Mark Weintraub
Great, thanks thanks so much. Obviously, we're in a pretty extraordinary period from a cost standpoint.
I was just hoping if we could maybe get a little more color on some of the sensitivities and and things like hedging, as well as the timing on price recovery as you roll containerboard through into boxes in the different regions. It was kind of big picture stuff.
Wouldn't normally be asking this, but, again, we're we're in a really volatile market, and it's it's hard for us on the outside to get our arms round some of the the timing, in particular, around these items.
Tony Smurfit
We we have said that that we expect to get the full cost recovery of the latest increase, in Q1 of next year, and all of the paper the paper price increases, as we've as we deal with some of the later earlier-taken orders, as we get rid of those out of our system, those will translate into much higher export prices. We talked I mentioned in in our in our in my script that, we see very strong paper bag business that's growing very strongly because of some structural shifts.
All of that will start to feed through into later in this quarter, all the paper stuff was later in this quarter, but really, strongly into early next year. As we go through Q1, Q2, we should start to see, material increases in our on in our numbers based upon these increases that will be passed from from corrugated into into sorry, from paper into corrugated and into into export markets and into other grades of paper.
That is the normal that it would be a normal situation for us. Europe has been a little bit more volatile in up and down pricing, and so this is completely normal for the European business to have this time lag period.
Obviously, when prices go down, that is also a benefit for the company holding on to margin. We're not seeing anything different other than the the fact that if costs, as you say, Mark, it's it's a time when when all of us are dealing with these these escalating costs.
If they continue to escalate, we'll have to do something about it because, clearly clearly, they're they're affecting our numbers, and and and we need to we need to recover. Q1 will be, a a continuing benefit from from what we've seen in in the announcement of the $70, and then and then we'll keep an eye on what what we have to do based upon costs.
Ken Bowles
Hey, Mark, it's Ken here. I I think, without overcomplicating either sensitivities on energy or freight, I think when we think about energy and hedging, clearly, coming into the year and where prices were, we still had a decent bit of hedging in the tank.
Clearly, at these levels, we've we've taken a different view across the year. We've stepped into the market every now and again when when the price has come to a level where we think that it makes sense to hedge, but, but not hedging at these kind of levels because, in in reality, that can go against you if if the price drops.
The the the energy committees in both North America and Europe and indeed Latin America have been smart about how they've incrementally added small hedges along the way, but we would not be at the levels where we would normally be, and that's purely as a function of the market and and where we see costs. Clearly, that's why the price increases we've announced on paper in both regions, net 170 North America, net 140 in Europe, are are designed to kind of take account of that situation too.
Still a level of hedging, but not not at the levels we'd like, and and and the ranges would be would be quite wide in terms of the the spot prices for that. We look at the forward curves equally, you wouldn't be stepping into this market given where the forward curves for energy are.
I I think on the freight side, probably the most meaningful sensitivity for for you is is around where diesel sits with us. We we kind of estimate that, call it, every dollar on diesel probably has a direct impact to the business of something like $80 million, but then when you when you add in the downstream impact of that through the rest of the system, that's probably more like, call it, $120 to $130 million in total impact for the year for a North American system.
That's probably the most meaningful sensitivity for that region versus, say, energy for for Europe.
Mark Weintraub
Super. That's super.
Ken, just could you give us a sense of the sensitivity to, nat gas in Europe, either how much you're consuming or, similar to like the dollar translates into X million dollars, what it would be for Europe?
Ken Bowles
It's a trickier it's a trickier proposition given the the fact that we do a lot of our own internal through CHPs and our own kind of take-off. It's a much trickier What I'd do is, Mark, I think we'll deal with that one separately because it's a it's a much deeper modeling question, given you can't take the total energy piece and kind of model it out.
It It has a lot of kind of moving parts around internal energy, where we use renewables, how we step into renewables, the CHP in the corrugated systems. It's It's quite It's quite a different, more detailed answer, if that's okay.
I
Tony Smurfit
I think, Mark, it's very interesting. Like, at the current levels, just put into an American context, the the the TTF is about $30 per BTU for natural gas in Europe.
In in in North America, it's, call it, $3. It's a 10 to 1 ratio for the European industry.
Like the reason why we're getting paper price increases in Europe is not not because of the the capacity situations. There's a lot of people that actually can't afford to run the mills.
That's why the the prices are absolutely necessary. If if this continues, well, obviously there have to be other actions, either by closures or other other pricing actions, because there is just no way that at these cost levels that the the our European industry in paper, but also many European industries, will be able to continue to operate in any way profitably.
Obviously, from our perspective, we have our kraftliner mills, which don't use as much gas and generate themselves, so that's that's making them, very profitable. As we get these box paper price increases, we have to pass them onto the box system, which we're which we will be doing and are doing, and you already see the the prices moving up in Europe step by step, and we'll start to see a big benefit of that in Q1 as as we go into as we pass through the the the contractual price increases that we have.
Mark Weintraub
Appreciate the color. Thank you.
Tony Smurfit
Thanks, Mark.
Operator
Thank you. Next question comes from Anthony Pettinari from Citigroup.
Please go ahead.
Anthony Pettinari
Good morning.
Tony Smurfit
Hey,
Anthony Pettinari
Tony. Hey.
In In North America, I think you indicated you're sold out in most consumer grades, and I'm wondering if you could give any more detail on where, the consumer business is in terms of cost recovery or just sort of overall performance versus expectations. I guess we've gotten these hikes in containerboard, but in consumer, we haven't necessarily seen the same kind of pricing traction.
Just kind of wondering if you can comment on that.
Tony Smurfit
On consumer, I would say that steady she goes on the CUK market. There's there's that that's that's carrier board market.
It's there's there's not there's not there hasn't been any real decreases, nor has there been any real increases there. We try, we had a look at that way back when, and it didn't seem like the right time.
SBS, as you'll remember, went down about $100. We're in the market with increases currently, and, we're sold out in that grade, therefore we believe that there it it merits some increases to get more than back what we lost in the last quarter of last year as we move into next year, as we move into 2027.
That is a very strong grade for us. We have a very differentiated offering.
We're not in the we are a little bit in the commodity side of that business, but we tend not to try and be in all the commodity side of that business in plate stock and cupstock. We've got some specific areas which we've grown, and as we've talked about before, we've made some switches away from CRB to to SBS and indeed to CUK with with customers and giving them benefit for that.
I think, I feel good about the SBS market right now. The way that we're positioned, at least.
Then the CRB market, we don't have our our mills are not the strongest in that area, and we continue to be a an alternative supplier for customers and our own internal usage. That's an area which we don't necessarily see when I talk about most grades.
That's the one area that we don't really see any pricing momentum, and you'll know the reasons why that that that is, Anthony.
Anthony Pettinari
I think, Anthony, just to Yeah.
Ken Bowles
Hey, Ken here. I think to follow on to that, too, at the converting end in terms of consumer, we've seen reasonable progress in terms of volumes Q3 over last year.
For food and beverage, broadly flat, but most pleasingly probably in our HBHC set segment, broadly volumes up over 2% year-on-year. It's kind of aligned that kind of sold-out position on most of the consumer grades board-wise, but also seeing progress in terms of volumes on the converting side is is equally pleasing.
Anthony Pettinari
Okay. That that's very helpful.
Then just quick follow-up on Europe and kind of your response to Mark's question. Given the spike in in energy and freight, and I I'd imagine some volume pressure for the industry, I'm just are are you seeing changes in industry supply-demand in terms of supply coming off?
Has that, I guess is it surprised you that you haven't seen more supply come off? I'm just wondering if you can give any kind of general commentary on supply-demand situation in Europe and what's obviously kind of a stress stressed environment.
I
Tony Smurfit
I think it's inevitable that it will happen. I think we've seen a lot of people taking a lot of downtime because, obviously, if you're if you're going into the market and selling at the old prices, you're just you're losing you're losing a lot of money on on on every tonne.
As this price continues to rise for energy, then then you're going to see continued stress either through downtime. As Anthony, in Europe, governments don't like to see paper mills shut down, they try and keep them open as long as possible, and they give all sorts of subsidies and and help.
You'll have seen some of our competitors announce their results, and they're making zero EBITDA on brand new assets. The question is how long they can continue to do that for, and, I don't have an answer to that because, there is some there is often government support that keeps them going.
Inevitably, if if economics will trump out, then then there will be some closures at these levels.
Anthony Pettinari
That that's very helpful. I'll turn it over.
Tony Smurfit
Thanks, Anthony.
Operator
Thank you. Next question is from Andrew Jones from UBS.
Please go ahead.
Andrew Jones
Hi, gents. Thanks.
Thanks for the call. I just wanted to ask about the situation in Europe.
We've had large price hikes obviously driven by that cost pressure that you've mentioned. I'm curious what your thoughts are on as we go into the next year, some of this new capacity is coming online in Italy and obviously that Shotton mill in the UK.
Are you seeing pricing sort of holding if the current cost environment lasts, or do you think that we'll start to see some pressure as we go into 2027?
Ken Bowles
I think, morning, Andy, Ken here. I I think the reality is that, of of all the new capacity coming on, they're all people who have skin in the game already, if you like, in terms of a system in play.
You got to think about this from kind of a pure capital allocation perspective, or at least I would, in the sense that it wouldn't make any sense logically, to be kind of trying to capture volume for a new mill on lowering price, given the amount of capital that it takes either to convert these mills or the start of a new one. For like the Shotton one you mentioned there, or even the Palm mill, equally in the UK in the early part of next year, you you have to assume a kind of similar logic or pattern that we've seen in the last number of years, which is around, Tony reference, downtime, prioritizing maybe downtime in a mill system over reducing price in order to kind of make sure that the returns stay reasonable.
Because ir- irrespective of how you might want to fill a mill, the firing of the mills, the energy cost of those mills, and indeed trying to find a market in a kind of a, okay kind of demand environment will all impact the overall return. Ultimately it comes down to the ability to generate cash flow, to be successful.
I I think we've seen in Europe two things happen over the last number of years. One, a a mayor predominance to kind of take additional downtime in order to manage that kind of market better than it might have done before.
Equally, the lack of independent players means that idea of a a rogue mill trying to capture mill capture new volume on price is not really there anymore. It is a lot of systems who have a a bigger game to play in the context of how they manage overall market share.
Tony Smurfit
I think Andy Ken just made a good point. There's two very large independents have gone out of the market, one to Saica and one to Mondi in Germany, Schumacher and Schumacher and Timm Group.
The independent market per se is shrinking. Therefore, independent mills that are coming into the market, like what the the two that Ken has mentioned, have a less and less market to go for other than they go for export.
That's not that's not That's a road to perdition, really. I think you'll find that, for them to to be chopping pricing will be, as I say, a a, it will be it will be a a disaster for them.
You'll see you see that already with one of the larger competitors in free market competitors who makes nothing in their in their in their containerboard system, and that's before the recent price rises. I I think I think I worry less about that than how the energy price affects the demand outlook for our end customers.
That that's something that, we don't obviously have a crystal ball on. Far, at least because of our offering in Europe, we we've grown this year.
We continue to see in October, reasonably good growth in October. I I'm very comfortable with our own system.
The the the overall environment, how Europe energy affects Europe is is something that we have to think about, at least.
Andrew Jones
Yeah. That's that's that's very clear.
Thanks a lot.
Tony Smurfit
Thanks, Andy.
Operator
Thank you. The next question comes from Detlef Winckelmann from J.P.
Morgan. Please go ahead.
Detlef Winckelmann
Morning, everyone. Maybe my first question.
You did call out, I think you said something to the effect that, look, price increase is always lagged. Cost inflation has come first, that's fine.
Over the next, on an annualized basis, price cost is firmly positive, or price will more than offset cost inflation. Just curious, is that only on the North American side, or should we be thinking the same thing in Europe as well just after considering your your kind of kraftliner kind of mix and the and the energy efficiency that that kind of side on that as well, please?
Then I've got a follow-up, please.
Ken Bowles
Hey, Detlef, it's Ken. Good morning.
No, you should assume that for all regions. The The mechanism, if you like, in terms of of paper price increase into the index, or indeed the freely negotiated, is probably slightly quicker in North America than Europe by a couple of months, but, but ultimately, it's exactly the same pattern.
Indeed, in Latin America, you'd argue maybe even quicker again, given it's a region that generally deals with inflation quite well. No, the the pattern in terms of normal time lags that we've we've talked about very similar for North America and Europe.
Given the level of index versus non-index is probably slightly higher in North America, you tend to get it through quicker, but overall you end up in the same place.
Detlef Winckelmann
Cool. Then one more follow-up just on Europe.
We've been hearing the last couple couple company releases that there's a bit of discounting downstream at the box plant level. It does seem to be isolated to certain regions.
Just curious, are you seeing anything of that sort that, could hurt you down the line, as you pass on the price increase through to box prices?
Tony Smurfit
There there is some some one or one player, particularly, that is is is trying to get a little bit of volume, and so that that has created some noise in the marketplace. Overall, I would say, I wouldn't say it's that much difference to any other pricing environment where people are are struggling and try and get some volume.
I wouldn't say it's a particular massively different situation to what it normally is. There are there are some players that try and use these times to get some volume in the downstream market.
You have to you have to, because of your quality, service, when you look at the quality and service and that we bring to our customers and the the complexity we we deal for them and look after for them, that, we we we expect to get paid for that. Clearly, our our whole innovation offering it is making a difference, and so I I I wouldn't worry too much about that per se, Detlef.
Detlef Winckelmann
Cool. Thank you.
Tony Smurfit
Thank you.
Operator
Thank you. Next question is from Lewis Roxburgh from Goodbody.
Please go ahead.
Lewis Roxburgh
My question's on holding onto pricing. Cost and energy inflation's clearly been challenging, but it it will turn at some point.
I guess to what degree do you believe that you'll have to give pricing back? Is Europe in particular more vulnerable to that given the oversupply in containerboard and energy security, and comparatively is the the US and LatAm in a better place given, the industry consolidation, tight supply, etc.?
Tony Smurfit
I think that's a fair characterization, Lewis. If if all of a sudden energy was to fall back, I think that it would put more pressure on the European containerboard price.
I I think that, I I don't I don't think that would be the case per se in in Latin America or the United States, or the North American market. I think, the the structural change that's happened in North America has been very significant.
As I say, we've been in a sold-out position for for the last number of months, and and we have still orders to fulfill from April and May. I'm I'm not I have no idea about the others, but I assume they're in the same sort of situation.
We we we have a window into Latin America, and while Latin American customers tend to have larger supplies, prices are going up in Latin America, and that is going to feed into a better situation next year and beyond, irrespective. Unless something really bad happens in the world, I I think that that, your your your statement is correct.
Lewis Roxburgh
That's clear. Thanks.
Operator
Thanks, Lewis.
Tony Smurfit
Thank you.
Operator
Next question, we are going to retry the line for Phil Ng from Jefferies. Please go ahead, your line is open.
Phil Ng
Hey, guys. Sorry about that, I had some technical issues this morning.
Tony, if you've addressed this already, I apologize in advance. I think Ken, you were talking about, earlier to a question that in Europe, you feel pretty good that your box prices would catch up to containerboard prices, and you would offset inflation.
I guess the one variable that would be helpful to kind of give us some color is nat gas hedges just because you had some hedges. Based on what you have in place in your traction you're seeing, how do you feel about that dynamic, and how should we think about that hitting your P&L and your ability kind of be on a positive spread next year?
Ken Bowles
Hey, Phil. The the price increases we announced, that net 140 on testliner, would have ultimately taken into account a lot of what we've done on hedging.
In effect, generally the hedging would be a net incremental positive to anything you do on that paper price. There's no incremental P&L hit in that sense.
They're not They're not futured out. Ultimately, you're just contracting gas at kind of standard set prices rather than spot in that sense.
Ev- everything we've done and built around price increases around, testliner particularly in Europe takes into account where we sit in the hedging curve, generally a conservative view on where that might go, but always with the idea that the hedging plus the price increase should land you in a slightly better position overall at the end of the game. So, in in reality, not that the hedging doesn't necessarily matter in that sense, it always acts as a better moderator or better basis in terms of how you get through in terms of full margin recovery, but the price increases do take account of all the hedging we have and had in place, indeed the forward piece,
Tony Smurfit
too. I'd just add some color to that, Phil.
We We wouldn't hedge at these levels because, if the energy price falls backwards in a hurry and you're you're you're stuck at 100, you are going to be really seriously uncompetitive for a period of time. We we just think that it would be I no, and I don't we don't believe that anyone in the industry or or to any great extent is is hedging at these levels because, they're so remarkable that nobody would have actually ever anticipated that gas could get to this level.
Now, people would be very afraid, like us, that if you hedge at these levels, you could get you you could get caught with your pants down. We're not going to be in that situation, and we'll ride it.
As I say, if if it stays at these levels, either there'll be a lot of downtime, or or there'll be further increases, or there'll be there'll be closures. Because it just can't, you're a 10 to 1 ratio for for versus the United States and on gas, which is just unsustainable for European industry.
Ken Bowles
Because you you to to stay back with Phil, really what you're thinking about in the context of where hedging sits in in an integrated system like Europe, which is probably 100% integrated, it's about cost cost certainty at the mill side. You don't, as Tony says, get trapped on one side or the other of that kind of hedging curve.
If you go back to kind of, very high prices when you go back to '21, '22, equally we would have stepped out of the hedging market while while that happened and then brought back in when we needed. It's it's about, through an integrated model, it really is that cost certainty at the start and recover at the end.
Hedging tends to be a bit reflex in the middle. It's been a been a wonderful friend in the past, but and it will be in the future.
At the moment, though, as Tony says, not a place to go.
Phil Ng
Helpful color. I guess bigger picture, Tony, you've owned the Westrock assets for some time now.
In terms of your journey in terms of, some of the goalposts that you would want to call out and things that you'd still want to work on as we think about '27 and beyond, what are some of the things you want to highlight? It might be your customer mix, in terms of, the mix of regional versus national, anything to call out just because obviously profitability has been masked a bit by the inflation.
Just kind of give us some goalposts where you are, and and what are some of the next things we should look forward to as we look out to '27 and beyond?
Tony Smurfit
I think, Phil, that's a that's a really great question. I'm sitting in the Três Barras mill down in Brazil.
Just just to take our just take it by region. I take our Latin American region.
This is one of the most one of the world's great assets, and with great management team, and continuing to grow and have great ideas for the future. If I look around our Latin American business, really strong, great the the the Westrock combination between the two.
I'll give you a very good example because I was here yesterday. They used to have a huge side side rail issue in this mill that they would sell at heavily discounted prices.
Because of the combination, we now no longer have a side reel issue in this mill. We're able to run full out and get full contribution for all of the paper that we make.
It's made this mill much more profitable. That's just one small example.
In our European business, the combination, there was no corrugated assets, but the consumer business has improved radically in Europe and is really set for a very strong growth together with our corrugated business as we as we move to the owner-operator model. Has been a really successful combination.
Then when you look to the North American market, what I would say the most the most pleasing thing for me has been how the management team have really adopted what we talk about as being the owner-operator model. They are very enthusiastic.
We're seeing customer wins in the corrugated area. Our consumer business, we need to our end-market consumer margins are not where we want them to be, but we will get there because the teams that the plants are in very good shape.
The teams are very very well organized. We will progressively move that margin up without anything to do with the underlying paper pricing as we as we refocus that business in the future.
If you take our mill system, what I would say is we have some really great mills, and we have some mills that continue to need work. That's that once we fix those mills that need to have that need work, then the mill system will be, as good as any that we have anywhere else in the world.
Our mill system, is progressing. We've got a whole new management team there that it's really moving things forward in a positive way.
We've we've recruited some great people into the business. Our, our people aspect of North America has really progressed very strongly.
If you say why am I excited, because I can see the potential of this business. Of course, I'm really frustrated by the fact that, we're we're making all this progress, and it's not easy for anyone to see, because when you get $700 of unexpected cost, $700 million of unexpected cost, you sort of go you scratch your head a little bit to say, okay, we need to recover that.
How do we do, but it's pushing the it's pushing the game forward, which is, never where we want to be. We want to be we want to be winning from the front rather than trying trying to to catch up.
It we are where we are because we don't have control over the things things outside of our control. I am very, very excited about the future of this company and the combination of this company because, it it's going to be very powerful in the years ahead.
Phil Ng
Appreciate the color. Thank you so much.
Tony Smurfit
Thank you very much, Phil.
Operator
Thank you. The final question today comes from Pallav Mittal from Barclays.
Please go ahead.
Pallav Mittal
Hi. Thanks for taking my question, a couple of them.
Firstly, clearly energy and freight costs are much higher than what we were expecting 3 months ago, and you have said hedging levels are low for very obvious reasons. If we assume spot rates and things stay this way, how much of an increase are energy and freight costs expected to be in '27 versus '26?
Oh,
Ken Bowles
Pallav, haven't got there yet. Sort of back to that's back to, we haven't got near a budget yet.
I think we have to we have to kind of see that in the round around where we think all those forward curves are. I I wouldn't given given if you like, my my forecasting on energy and freight for this year has been kind of changeable as we got through the year.
I'm not sure I'd sit here yet and forecast energy and freight for next year. I think our opening assumption would be, at some point, that cost backdrop has to abate slightly.
For the moment, I couldn't give you a view on freight or energy for '27.
Pallav Mittal
Sure. Then if I could just check on CapEx, it seems that you've lowered your guidance by $150 million or so for 2026.
Can you just help us understand what has changed there, and does it mean that '27 CapEx goes up slightly?
Ken Bowles
No, no not really. We we we decided to just slow back a little bit because, the the when we took our number down for for last quarter, we said we'll we'll just get the money back in in in our CapEx.
Our plans are still the same. They'll they'll it'll probably mean that 20 2031 will have $150 million more, or 2032, but I wouldn't we we haven't stopped anything that we need to do.
It's just that we've delayed a couple of projects by a number of months. It's not there's nothing there's nothing of interest there.
Pallav Mittal
Sure. If I can just squeeze one on Europe, a quick one, you have said the growth has been good in October.
Can you just help us understand how your order books are looking for the near future?
Tony Smurfit
For the very near future, we're actually okay. As I said, in North America, this month, as in October, we will be line and ball with last year.
I don't want to predict that that's going to be the same in November and December, but November feels okay. We have a a large election happening in in November, we'll have to see how that plays out to demand in North America.
I think that Europe, we expect to have a we're we're a couple of percent up on the same-day basis during the month of October. We hope that trend continues for the rest of the quarter, but we don't expect anything for it not to.
Latin America, we have seen weakness in Brazil, actually, during during the last couple of months as a uncertainty of the election down here fed into the marketplace, and, it hasn't hurt our profitability. The the the demand levels were not where we would have expected in the last 3 months in Brazil.
Still, as I say, it hasn't affected our profitability, and we're still very well positioned in the country.
Pallav Mittal
Amazing. Thank you.
Thanks, Pallav.
Tony Smurfit
Thanks, Pallav.
Operator
Thank you. There are no further questions, I will now hand back to Tony Smurfit for any closing comments.
Tony Smurfit
Thank you, operator. As I mentioned on the call, I remain incredibly excited about the future of this company.
We've done a lot during the last couple of years, and obviously we're not happy with the fact that we've absorbed so much cost so quickly during the last 3 3 months and into the next 2 months. Obviously that that has affected our results, but, we are in the process of recovering those costs, and we look forward to 2027 with great confidence.
We appreciate your support, and we appreciate the time you've given us today. Thank you all for being with us, and we look forward to catching up with you either in person or on the next conference call.
If we don't speak to you before year end, we wish you a very happy Christmas and a new year. I know it sounds a little bit early to be saying that, but nonetheless, good luck in case I don't speak to you.
Operator
Thank you. This concludes today's conference call.
Thank you for participating, and you may now disconnect. Speakers, please stand by.