Teleflex Incorporated
Q3 FY2026 · Earnings Call TranscriptNovember 5, 2026
Operator
Good morning, ladies and gentlemen, and welcome to the Teleflex Third Quarter 2026 Earnings Conference Call. At this time, all participants have been placed in a listen-only mode.
At the end of the company's prepared remarks, we will conduct a question-and-answer session. Please note that this conference call is being recorded and will be available on the company's website for replay shortly.
Now, I will turn the call over to Mr. Lawrence Keusch, Vice President of Investor Relations and Strategy Development.
Lawrence Keusch
Good morning, everyone, and welcome to the Teleflex Incorporated Third Quarter 2026 Earnings Conference Call. The press release and slides to accompany this call are available on our website at teleflex.com.
As a reminder, a replay will be available on our website. Those wishing to access the replay can refer to our press release from this morning for details.
Joining me on today's call are Jason Weidman, President and Chief Executive Officer, and John Deren, Executive Vice President and Chief Financial Officer. Jason and John will provide prepared remarks, and then we will open the call to Q&A.
Before we begin, I'd like to remind you that some of the matters discussed in the conference call will contain forward-looking statements regarding future events as outlined in the slides posted to the Investor Relations section of the Teleflex website. We wish to caution you that such statements are in fact forward-looking in nature and are subject to risks and uncertainties, and actual events or results may differ materially.
The factors that could cause actual results or events to differ materially include, but are not limited to, factors referenced in our press release today as well as our filings with the SEC, including our Form 10-K, which can be accessed on our website. Now, I'll turn the call over to Jason for his remarks.
Jason Weidman
Thank you, Larry, and good morning, everyone. Let me start this morning with the highlights of the quarter.
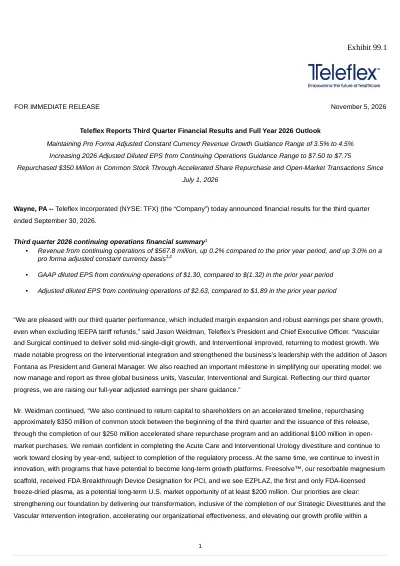
Teleflex delivered strong third quarter performance, with pro forma adjusted constant currency revenue growth of 3% and adjusted operating margin of 25%. Even excluding the benefit of the refund for IEEPA tariffs paid in 2026, adjusted margins saw modest expansion, and earnings per share grew.
Vascular and Surgical continued to deliver solid growth, while Interventional returned to positive growth, improving on its second quarter performance. We also continued our return of capital to shareholders with $350 million in additional share buybacks, $100 million more than previously announced, between the beginning of Q3 and today.
As John will discuss, we are increasing our full year adjusted EPS guidance to reflect our third quarter progress and our outlook for the remainder of the year. I've now been in the CEO role here at Teleflex for about five months.
I've continued my extensive review of the organization, spent significant time visiting sites and customers across the globe, and ensured focus on our critical executional priorities. On our last call, I said I would have more to say about my perspective on the business and our future direction by this call.
While I still consider it early in my tenure, I'd like to share some insights, particularly on our growth strategy, and then turn to our priorities and expectations for the future. As previously discussed, Teleflex is in the midst of a massive transformation, and I want to thank our employees for the tremendous effort, dedication, and extra work they have put in to continue driving the transformation forward.
Now that I have a first-hand view of what is really required, I can tell you that I'm very proud of our team. While we have always said that 2026 would be a transition year, we have made significant progress and reached tangible milestones, including combining the vascular intervention and Teleflex interventional access teams, closing the OEM divestiture, and returning significant capital to shareholders.
We expect that these efforts will enhance our financial profile in 2027 with higher adjusted margins, lower interest expense, a lower share count, and a meaningful step-up in adjusted earnings per share. While much progress has been made, we have more to do to generate the long-term growth that I am confident Teleflex can deliver.
My top priorities are threefold. First, we need to strengthen our foundation by delivering our transformation, including closing the acute care and interventional urology divestiture, and fully completing the integration of our interventional business to position it for sustainable growth.
Second, we need to accelerate our organizational effectiveness by fully implementing a global business unit structure and simplifying our operating model. Third, we need to elevate our growth profile by advancing innovation in key growth drivers within a balanced capital allocation framework.
Together, these priorities are about building a more focused, agile, and growth-oriented Teleflex, a company that is closer to its customers, faster in how it operates, and better positioned to deliver meaningful innovation and sustainable growth. Beginning with the first priority, which is clearly the most important in the near term, we need to fully execute on the foundational elements of our transformation to deliver a newly focused Teleflex that is built to grow.
Operationally, our immediate focus is successfully completing the interventional integration. While it has taken longer than we originally planned, we made notable progress in the third quarter on the three transition dynamics I outlined in August, and I'll walk through some of the details when I cover Interventional's results a bit later.
Our go-forward success with Interventional comes down to focus and execution. I believe strongly that we now have the right strategy, great products, and people to position Interventional for improving growth over the coming years.
We recently strengthened the leadership of this business with the addition of Jason Fontana, who joined as President and General Manager of Interventional effective September 14th. He brings more than 20 years of leadership experience across interventional markets, spanning global P&L responsibility, commercial strategy, market development, innovation, and business growth.
I've known and worked with Jason for about two decades, and I'm very confident in his ability to lead this business through a successful integration and beyond. Also critical to delivering on our transformation is completing the acute care and interventional urology divestiture.
I want to be clear: we're confident this transaction will be completed. As previously disclosed, the FTC issued a second request in March.
Its review is focused on a small area of product overlap with the buyer's existing portfolio, which is a defined and manageable issue. As a reminder, this is a buyer-led process, we're working closely with Intersurgical to support.
While we continue to work to close the transaction by year-end, the precise timing remains subject to the regulatory process and could extend into 2027. That said, I'll reiterate that we remain confident in completing the overall transaction and are encouraged by the progress being made.
For us to truly capitalize on the leaner, more focused Teleflex that we are building, we're going to need to change how we operate. This leads to my second priority of accelerating our organizational effectiveness.
Historically, Teleflex was organized geographically, which often led to different approaches in different parts of the world. Over time, it created a complex matrix in which accountability was spread across too many people, and objectives weren't always aligned.
Candidly, it also created a heavy process burden that at times pulled our focus away from the customer and slowed us down. To remove those barriers to execution, we're in the midst of implementing a global business unit structure and simplifying our operating model to drive sharper customer focus, clear accountability, and faster decisions.
This quarter marks an important milestone for us in this regard. We now manage and report as three global business units: Vascular, Interventional, and Surgical.
The BUs now have clear line of sight across the globe and the mandate to optimally deploy their resources to maximize growth. Each business will own its strategy, resources, and results.
Our goal is straightforward: to put customers at the center of our decisions, empower our global businesses to lead, and ensure our corporate functions help them move faster and execute more effectively. We've also simultaneously embarked on a number of initiatives to reduce process complexity and simplify our operating mechanisms.
All together, this is another big transition for our company, for our employees, and for how we operate. I'll tell you that our employees are really energized.
There's a strong belief that we can positively change so that it's easier for our teams to get things done and better serve our customers. My third priority is to elevate our growth profile by advancing innovation in our key growth drivers within a balanced capital allocation framework.
Beyond our previously committed redeployment of divestiture proceeds, which encompasses $1 billion of share repurchases and $800 million of debt reduction, our approach to capital deployment is to invest in R&D and capex to fund organic growth, maintain a strong balance sheet, and use excess capital for share buybacks or, eventually, M&A. From an organic growth standpoint, historically, the vast majority of our R&D went to sustaining products and iterations, and planning cycles tended to be shorter term.
We're changing that. We've taken R&D investment from historical levels of about 5% to 6% of revenue to close to 8%, and we're directing more of that spend towards substantive innovation.
Freezsolve, our resorbable magnesium scaffold, is one example. As we reported this summer, we completed the enrollment in the BIOMAG-II trial ahead of schedule, with the data read-out expected in late 2027, and our US pivotal trial, BIOMAG-III, is underway.
More recently, we completed the patient enrollment in the European BIOMAG-I LL clinical study, which is assessing the clinical efficacy and safety of extended length 35 and 40 Freezsolve resorbable scaffolds in long lesion lengths, which remain among the most challenging lesion subsets in PCI. Finally, we were excited to announce two weeks ago that Freezsolve received breakthrough device designation for PCI from the FDA, which signals the novelty of our approach and provides us closer interaction with the agency as we move the program forward.
EasyPlas is another substantive organic innovation example where we see meaningful future potential. Its approval in late July was a landmark for Teleflex, and on our last call, several of you asked how we think about the opportunity.
When we spoke in August, I said we had more to learn, and over the past quarter, we've learned a lot. EasyPlas is the first and only FDA-licensed freeze-dried plasma, and interest from customers has been high.
It addresses a significant unmet need. Today, the standard of care is frozen plasma, which has to be stored frozen and thawed before use.
That limits where plasma can be deployed and how quickly it can reach a patient. EasyPlas is stored at room temperature and is ready to reconstitute in minutes.
That makes plasma available on the battlefield, in air and road ambulances, and in trauma centers that want immediate access to plasma in every situation without waiting for it to thaw. Our flexible bag is also a meaningful differentiator against the glass container formats we expect from future freeze-dried competitors.
As the only licensed product with these attributes, we have a first-mover advantage, and we believe EasyPlas will set the standard against which any future entrant is measured. On market size, I told you last quarter that I wanted to thoroughly assess before putting a number on it.
Our work is not finished, but we are now confident that over the long term, the potential US market opportunity is at least $200 million and a meaningful growth driver for Teleflex. I do want to be clear about the pace.
Our first priority is the US government and military, which we expect will account for the majority of our current manufacturing capacity. We are actively engaged with the Department of War, and those conversations continue to progress.
The path from here still runs through procurement solicitation, contract negotiation, and execution before we deliver commercially. We continue to expect EasyPlas revenue to be immaterial in 2026 and to become a contributor in 2027.
Beyond that, we expect a modest revenue ramp over the first several years. We have to build the market, and scaling production of a complex biologic like this is a substantial undertaking, not a routine capacity addition.
Meaningfully increasing supply will require a significant multi-year effort, and we will be thoughtful about how we sequence those investments. This is a long-term opportunity that we are building carefully, and we are focused on positioning Teleflex to capture it over time.
Overall, going forward, we'll disproportionately deploy resources to our best growth opportunities, including through opportunistic tuck-in acquisitions that fit our three core businesses and capital allocation framework. We're improving our processes for opportunity evaluation and execution monitoring, with oversight by the growth and operating committee of our board, and we've added relevant expertise at the board level.
Sean Salmon joined our board of directors effective September 8th. Sean brings more than three decades of global leadership experience in the medical device and pharmaceutical industries, including more than 20 years at Medtronic.
He most recently served as executive vice president and president of its cardiovascular portfolio, a global business with fiscal 2025 revenue of approximately $12.5 billion, where he was instrumental in developing the growth strategy. I'm excited to work with Sean and the entire board to continue to progress our strategy, to drive execution of our priorities, and to elevate growth for Teleflex.
Now, let's move on to our third quarter continuing operations detailed results and updated financial guidance for 2026. All growth rates that I refer to are on a year-over-year pro forma adjusted constant currency basis for third quarter 2026 continuing operations, unless otherwise noted.
For the third quarter, Teleflex revenues were $567.8 million, up 0.2% year-over-year on a GAAP basis and up 3.0% on a pro forma adjusted constant currency basis. In the quarter, our revenue performance reflected continued solid growth in our Vascular and Surgical businesses and the impact on the Interventional business from the integration and restructuring activities related to the VI business.
Third quarter adjusted earnings per share was $2.63, a 39.2% increase year-over-year and ahead of our expectations. Now, let's take a deeper dive into our third quarter revenue performance.
Starting with Vascular, revenue was $243.5 million, an increase of 4.6% year-over-year, primarily driven by growth in our intraosseous portfolio, hemostatic products, and peripheral access products. As expected, growth moderated slightly from the first half as we saw some distributor inventory destocking associated with normalization following the lidocaine recall earlier in the year.
In our Surgical business, revenue was $114.0 million, an increase of 5.1%, which was primarily driven by strong performances in ligation clips and skin stapling. As expected, we also saw a moderation in growth of the Surgical business as compared to the first half, due to the challenging comparisons from the acceleration of our new instrument portfolio in mid-2025.
Moving to Interventional, revenue was $210.3 million, an increase of 0.2%. While growth continued to be impacted by the ongoing integration and restructuring activities associated with the VI acquisition, there was improvement compared to the second quarter.
Several categories, including complex catheters, hemostatic products, right heart catheters, and OnControl, outperformed. In August, I outlined several transition factors impacting the Interventional business that we expect to be temporary.
We made good headway in the third quarter, with tangible evidence of progress on the mitigation actions, and now we are on the steady march towards improvement. Let me provide some additional details.
The order-to-cash transition is now mostly behind us. In Q3, we diagnosed the causes of customer and process disruption and aggressively implemented mitigating actions.
At the end of the third quarter, approximately 90% of vascular intervention customers had been converted to the Teleflex ordering platform, and we expect substantially all customers to be transitioned in the near term. On distributors, the majority of the indirect vascular intervention business has now moved to Teleflex distributors and is now under our control, which has given us better visibility and predictability into the business.
While some distributor transition activity will continue, we now have the line of sight required to implement more comprehensive action plans to drive a steady improvement in this part of the business. On the sales force front, we've made great progress filling open territories, with openings down 63% from their peak.
It will take time for new reps to become fully productive, but I'm encouraged by the quality of our hires and the interest in joining Teleflex, which reflects the strength of our portfolio, the culture we're building, and the opportunity ahead. Under Jason Fontana's leadership, we expect to complete the remaining transition work, sharpen our focus on new product opportunities, including differentiated technologies like Freezsolve, and accelerate growth over time.
Our focus remains on positioning Interventional for long-term success, and I remain confident that we have the portfolio and the team to do so. Now, I'll turn the call over to John for a more detailed review of our financial results.
John?
John Deren
Thanks, Jason, and good morning. All results that I speak to will be on continuing operations basis for 2026.
Due to the reclassifications of discontinued operations, historical continuing operations reflect the impact of stranded costs in all periods presented. Following Jason's discussion of revenue, I'll begin with margins.
For the third quarter of 2026, adjusted gross margin was 66.8%. The 450 basis point increase year-over-year reflects the 290 basis point benefit from a refund in the quarter related to IEEPA tariff payments made in 2026 and foreign currency exchange rate fluctuations, partially offset by an increase in quality remediation charges.
Third quarter 2026 adjusted operating margin was 25%, up 300 basis points year-over-year, driven by gross margin expansion. This was partially offset by business investments and higher incentive compensation, which reflects both a lower accrual in the prior year quarter and a stronger performance this year.
Adjusted net interest expense totaled $18.9 million for the third quarter as compared to $30 million in the prior year period. The year-over-year decrease is primarily due to lower average debt outstanding, reflecting the use of a portion of the cash proceeds from the OEM divestiture to repay debt.
Our adjusted tax rate for the third quarter of 2026 was 11.1% as compared to 9.3% in the prior year. The year-over-year increase is primarily due to less favorable jurisdictional mix in the quarter and additional cost from the capitalization of certain R&D expenditures.
At the bottom line, third quarter adjusted earnings per share was $2.63, representing a 39.2% increase year-over-year. The year-over-year performance was primarily due to higher sales volume, lower interest expense, and shares outstanding, as well as the impact of tariff refunds.
At the end of the third quarter, our cash, cash equivalents, and restricted cash equivalents balance was $444.3 million as compared to $402.7 million as of year-end 2025. Net leverage at the quarter end was approximately 1.40 times, down from the second quarter leverage of 2.8 times, primarily driven by the reduction of debt following the completion of the OEM strategic divestiture.
Moving to our capital allocation strategy. We remain committed to returning cash to shareholders under our previously announced $1 billion share repurchase authorization, while reducing debt by $800 million.
Since July 1, we have repurchased approximately $350 million of our common stock, which was ahead of our expectations at the time of the second quarter earnings call. The repurchases were through a combination of our now completed $250 million accelerated share repurchase program and an additional $100 million in open market repurchases, representing approximately 2.7 million shares at an average price of $128.96 a share.
Our updated 2026 continuing operations guidance reflects the impact of these repurchases through the date of this call, but does not assume any additional share repurchases for the remainder of the year. As of November 5th, 2026, the company had $400 million remaining available under the current authorization.
During the third quarter, we paid off the $700 million term loan A-2 associated with our acquisition of the vascular intervention business and paid down a portion of our revolver. Turning now to the financial guidance framework.
As we previously indicated, 2026 results include a number of transient factors related to our strategic divestitures that will impact our near-term results, which we expect to be mitigated with the close of both transactions. Therefore, we anticipate 2027 will be more reflective of the underlying business, ultimately building a clearer financial profile with significant improvements in adjusted margins, interest expense, and adjusted earnings per share.
As previously announced, we have also launched a multi-year restructuring plan that is expected to achieve approximately $50 million in annual pre-tax cost savings upon completion in mid-2028. The restructuring activities, which are on track, began in the first quarter of 2026, and our guidance continues to assume savings from these activities.
We are also identifying further cost reduction opportunities as we remain committed to mitigating the stranded costs associated with the strategic divestitures. With that context, I will review the items that will impact our 2026 results.
First, our assumptions for 2026 continue to reflect the impact of stranded costs partially offset by transition service agreements associated with the close of the OEM strategic divestiture. Of note, the transition services and manufacturing service agreements associated with the acute care and interventional urology strategic divestiture are more expansive than those for the OEM, due to the buyer requiring more support, which will underpin our adjusted margin expansion in 2027 as we offset stranded costs.
Second, the exact timing of the closing of the acute care and interventional urology strategic divestiture will, to some extent, pace our ability to deploy additional capital during the remainder of 2026. Third, our 2026 adjusted gross margin assumption has been updated to include the receipt of IEEPA tariff refunds, which reduced third quarter adjusted cost of sales by $16.5 million.
As we look forward to 2027 and beyond, we anticipate our capital deployment actions, in combination with the impacts of the transition services and manufacturing service agreements, and our efforts to further mitigate stranded costs and right-size the organization, will result in significant increase in adjusted operating income, adjusted margins, and adjusted EPS. Moving to an update on our 2026 guidance.
Please note that our 2026 guidance is provided on a continuing operation basis and excludes acute care and interventional urology and OEM businesses. We continue to expect pro forma adjusted constant currency revenue growth for 2026 to be in the range of 3.5% to 4.5%.
Turning to adjusted earnings per share, we are increasing the range to $7.50 to $7.75 in 2026 versus our prior guidance of $6.90 to $7.20. Our guidance includes the third quarter results, our updated expectations for the remainder of the year, repurchases of common stock through the date of this conference call, and a 31 cent benefit from IEEPA tariff refunds for continuing operations associated with 2026.
Our adjusted EPS guidance does not include any benefit from the proceeds resulting from the acute care and interventional urology strategic divestiture or the anticipated positive impact from additional share repurchases. We anticipate these actions will result in meaningfully lower share count and significantly reduced interest expense in 2027 and beyond.
Taken together, we expect share repurchases and the balance sheet deleveraging activities will contribute to significantly higher adjusted EPS beginning in 2027. Additionally, for modeling purposes, you should consider the following: The impact of foreign exchange for 2026 is now expected to be approximately $9 million to $10 million benefit to our reported revenue as compared to $14 million previously.
We now expect 2026 adjusted operating margin to be approximately 20%, which includes the impact of the $16.5 million IEEPA tariff refund on gross margin. Once the acute care and interventional urology divestiture closes, we are confident that operating margin will be approximately 23% in year one as manufacturing and transition service fees offset stranded costs.
Looking forward, we see long-term opportunities to improve upon the steady-state operating margin through operating leverage associated with revenue growth and other cost-savings initiatives partially offset by continued investment in the business. Moving to assumptions below the line.
For net interest expense, we continue to expect approximately $85 million for full year 2026. We now expect our adjusted tax rate to be approximately 11.5% in 2026 as compared to approximately 12.25% previously.
Finally, we now expect our shares outstanding to approximately 42.5 million for 2026, which reflects share repurchases to date. That concludes my prepared remarks and I would now like to turn the call back to Jason for closing commentary.
Jason Weidman
Thanks, John. In closing, I will highlight our three key takeaways from the third quarter of 2026.
First, Teleflex delivered a strong third quarter, expanding adjusted margins and growing adjusted earnings per share. Vascular and Surgical remained solid, and Interventional is moving in the right direction.
Given this performance and our outlook for the remainder of the year, we are maintaining our pro forma adjusted constant currency revenue growth outlook and raising full year adjusted EPS guidance for 2026. Second, we made meaningful progress in our transformation this quarter.
The interventional integration is moving forward with new leadership in place, and we remain confident in completing the acute care and interventional urology divestiture. We are also advancing longer-term growth opportunities with innovations like EasyPlas and Freezsolve.
Third, we have a clear path forward built on three priorities: strengthening our foundation, accelerating our organizational effectiveness, and elevating our growth profile as we fund our innovation engine. Together, with our capital return and debt reduction, including the planned completion of our $1 billion share repurchase authorization following the close of the acute care and interventional urology divestiture, these priorities set us up for a meaningful step-up in adjusted operating margin and earnings per share in 2027 and sustainable growth beyond.
While there is still work ahead, we are building a more focused, agile, and growth-oriented Teleflex, and I am confident in our team's ability to deliver on the opportunity in front of us. That concludes my prepared remarks.
Now I would like to turn the call back to the operator for Q&A.
Operator
Thank you. If you would like to ask a question, please press star one on your telephone keypad.
If you're using a speakerphone, please make sure your mute function is turned off to allow your signal to reach our equipment. We ask that you limit yourself to one question and one follow-up.
If you would like to ask additional questions, we invite you to add yourself back to the queue again by pressing star one. Your first question comes from the line of Vik Chopra with BMO Capital Markets.
Your line is now open, please go ahead.
Vik Chopra
Hey, good morning. Thanks for taking the questions and congrats on a nice quarter.
I had two. The first one, Interventional returned to slightly positive growth, which was great to see, but I think you said that the integration disruption is still continuing.
I'm just curious how we should think about the quarterly growth progression for that business throughout 2027, and when you would expect that business to return to at least company average growth, and then I had a quick follow-up, please.
Jason Weidman
Sure, thanks for the question, Vik. Look, with Interventional, our goal here is to drive continuous improvement, set the business up for 2027, get it back to market growth, and to set the business up overall for success in the long term, and we did have tangible progress in this regard in Q3, we're happy about that.
Maybe I'll dive in a bit more into the specifics on what went forward, particularly with those three areas that we touched on in the prepared remarks and mentioned last time. From an OTC transition standpoint, at this point, we now have about 90% of the customers, the VI customers, onto the Teleflex ordering system.
As we talked about on the call last time, even as you transition people, if the system transitions go well, there can still be some customer disruption and some uncertainties that happen. To make this really tangible, to give you an example, in Q2, when we transitioned in Europe, we had 7% of our orders that were misdirected, and so as we go through Q3, and as we exited Q3, we had that far below 1%, we made really good progress there.
On the distributor transition front, when our indirect business was rolling through the legacy Biotronik distributors and/or with legacy Biotronik arrangements and contracts, we didn't have really close visibility to what was going on, and in particular, a lot of these guys didn't have the incentive to actually work collaboratively with us if they weren't going to be the long-term distributor, similarly, we've done a huge transition here in the quarter. So 87% of that indirect business is now over within our control, and we have now great visibility and can plan out that business much better.
We've turned a quarter and I believe that'll be on the upswing. Then finally, on the sales force front, and this was primarily a problem in the US, we had a 62, 63% reduction and quantitatively in the open positions, but qualitatively, I would say we're getting great people, and at this point, we're even starting to get reach-outs from some of the best reps in the industry in places where we don't even have open territories, feeling really great about the direction we're going.
Look, we have the right portfolio in place, the right strategy, and now we have the right leadership to drive this forward, and believe that we'll see steady improvement as we go through 2027.
Vik Chopra
Great, thanks for that comprehensive answer. If the acute care and interventional urology divestiture slips into 2027, can you just help us understand at a high level the implications for the stranded costs, interest expense, debt reduction, repurchases, and any timing of the 2027 EPS benefits?
Thank you.
John Deren
I'm happy to answer that. I think one is we're still working really hard towards closing this in Q4, and that is certainly our hope, obviously.
There is a chance that it slips into 2027. I will tell you that I don't want to speculate on if it does slip when that would be, but we're confident in the first 12 months on that 23% op margin with all the factors you just mentioned.
I don't know if I can speculate or start giving you the math. I've given you guys all the components.
I think you can think about how you'd model that with a delay, but we're still pretty confident in that 12 months post-act of disposition that we'd hit our 23% margin guidelines.
Operator
Your next question comes from the line of Patrick Wood with UBS. Your line is now open, please go ahead.
Patrick Wood
Amazing. Thanks, guys.
I might start with an incredibly nerdy one, I apologize, but Freezsolve, obviously, a lot of us back from TCT, there's so much noise around sirolimus coronary balloons, you know all the players in that space as well, but how do you think about in relation to those Freezsolve fitting into the market? Is there still a potentially better solution just given it supports the vessel during the absorption period and keeps it open, cuz obviously a lot of noise on that, I'm just curious if you see that affecting the ultimate value of Freezsolve one way or the other?
Jason Weidman
Patrick, thanks for the question. I appreciate the nerdy questions, especially in the PCI market.
Look, I think that generally with the excitement around DCB, and at this meeting, another positive result from sirolimus-eluting balloons, I kind of attribute that to the interest in not leaving a permanent implant behind. It's that general category.
The world moved towards DCBs when the first try at resorbable scaffolds didn't work, but the original plan and what people wanted was a scaffold or a stent that was in and disappeared. There was a reason why 30, 40 years ago, the world moved from plain balloons to plain stents, and there are advantages to having temporary scaffolding.
I definitely think that there's a place for Freezsolve, and I would say that I was also at TCT and there was a ton of excitement at the meeting for Freezsolve, for BIOMAG-II, and to see how the product performs versus DES, which we'll see in about a year.
Patrick Wood
Love it. Then just as a quick follow-up.
Sorry if this got dealt with earlier on the call, I was just hopping around, but the EasyPlas side of things, obviously decent opportunity for you guys there. If it were to start coming through a little faster than anticipated, what's the supply situation?
You guys able to ramp up fast for the demand, or are you supply-constrained, do you think?
Jason Weidman
Thanks, Patrick. I think that, as we said, we see this as a great long-term opportunity for us to at least $200 million in the US, but it's a new market.
It's going to take time to build. It'll take time for us to develop that market, and our first priority, as we said on the last call as well, is really serving the US government and US military, and we think that in the short term, and through the mid term actually, the first couple of years, they're probably going to take the majority of our capacity, and that's really going to be a great place for us to prove out its use and to help put in the early steps to develop that market.
Patrick Wood
Totally get it. Thanks, Jason.
Thanks, guys.
Operator
Your next question comes from the line of Jayson Bedford with Raymond James and Associates. Your line is now open, please go ahead.
Jayson Bedford
Good morning. Thanks for taking the questions.
I guess just on Interventional, there's a lot of moving parts. When will the integration be completed?
Jason, I'd love your view of end market growth in that interventional business.
Jason Weidman
Thanks for the question. I think as I said earlier in the first question, our goal here is to drive really that continuous improvement, and we're making great progress on all of those integration items.
I don't see this as a single point in time, a specific date, and all of a sudden you go from zero to one. I think that this is continuous improvement over time as we've talked about.
In terms of the end market growth, I would say in total, these are mid-single-digit markets, and so obviously the opportunity for us is to over time as well as to make sure that we're positioning ourselves in the higher-growth and more attractive subsegments of the overall interventional market.
Jayson Bedford
Thank you. Just maybe as a related follow-up, is there any way to tease out the growth profile in the VI or Biotronik business versus the legacy Teleflex interventional business?
Jason Weidman
Look, we don't guide by specific product lines, and at this point, the VI business is now fully anniversaried into our total interventional business, but it's safe to say that the VI portion has performed worse than the legacy business because this is integration disruption related.
Operator
Your next question comes from the line of Matt Taylor with Jefferies. Your line is now open, please go ahead.
Hi, good morning. Congrats on the quarter and thanks for taking the question.
This is Matthew On for Matt. My first question, I just wanted to quickly ask about tariffs and maybe the impact you're anticipating in 2027, especially given one of your peers has reached an agreement with the US government and could actually provide some relief on 232.
Is that something that you would entertain pursuing? Then I have one follow-up.
Jason Weidman
Why don't I cover that first part? Look, we're aware of the BD arrangement.
BD is a much different and a much larger company than us, they're in a different situation, we don't have anything at this time to report in terms of a similar deal to BD. In terms of thinking about 2027 in terms of tariffs—
John Deren
Yeah. Look, listen, how we've handled tariffs since liberation days, we continue to guide based on what is currently in place.
It's been very difficult, as to guess what happens next, even with these 232 investigations. Right now, what we're seeing for the current year is approximately little over $30 million in tariffs, and right at the moment I'd expect something similar for 2027, and when we know more, we'll let you know more.
Operator
Your next question comes from the line of Anthony Petrone with Mizuho Financial Group. Your line is now open, please go ahead.
Anthony Petrone
Thanks and good morning. Maybe one on Interventional, one on EasyPlas.
Just a comments on Interventional, there's still some headwinds linked to the Biotronik integration, maybe just a little bit on the details of that integration: where are you sort of behind schedule, where are you maybe ahead of schedule, and when will those integration sort of headwinds be in the rearview? Then I'll have one quick follow-up on EasyPlas.
Jason Weidman
Okay. Look, I think I mostly covered this in the first question, and that's that we reported last quarter about the integration delays that we were seeing.
Going forward, our goal here is to really make sure we show continuous improvement. We've had very tangible improvement measures in all three of those areas I identified last time.
I went through those with the first question, and so our goal is to continue to drive that improvement. We feel good about it.
We've got a lot of opportunity in this business. We've got new leadership under Jason Fontana, who knows this business like the palm of his hand, and we've got a lot of opportunities to gain share, to grow via geographic expansion and through new product introductions, we're feeling good about the direction we're going.
Anthony Petrone
Apologies for that. Just on EasyPlas, I noticed the TAM opportunities increased to at least $200 million.
I remember a few years back when that asset was brought in, it was at least $100 million. Maybe just a little bit on the increased TAM outlook for EasyPlas.
Thanks.
Jason Weidman
Thanks for the question. Look, I wasn't here when the $100 million TAM was put out several years ago, I can most confidently speak to how we're thinking about it going forward, and as we look at the market, we understand what the opportunity is, again, with the first priority being in the military and government segment here in the US, as well as limited penetration into the civilian market, with the pricing that we think is reasonable, we got to a TAM that was at least $200 million.
Again, I'll reemphasize that this is a market development play. It will take time.
This is not something that's overnight, and that our first priority here is really making sure we serve the US government and the US military and what their needs are, and that'll be the vast majority of our capacity for the first couple years.
Operator
Your next question comes from the line of Jason Bednar with Piper Sandler. Your line is now open, please go ahead.
Jason Bednar
Morning, everyone. Thanks for taking the questions.
I have a few follow-ups here on some prior topics. I'll try my hand here first on Interventional, and Jason, I know you don't want to get too specific on segment guidance, but I really want to try and put a bow on this.
You're talking about progress on the three VI integration dynamics and that's totally encouraging. With the progress you made throughout the quarter, it presumable things got better, August into September, and then that carried into the fourth quarter.
Are we safe to assume you're comfortable posting sequential improvement in constant currency growth for the fourth quarter, and then that momentum then builds into 2027?
Jason Weidman
Sure. As we look at the guidance here for 2026, let me take a step back.
From a top-line perspective, to be clear, our guidance only changed with respect to the currency effects. Our constant currency guidance for the year of 3.5% to 4.5% growth has not changed.
Q3 came in largely as expected, our outlook for Q4 has not changed, the range that we have there reflects the range of outcomes that we discussed last quarter. At the low end of the guidance, that would anticipate no improvement in Interventional, basically from that Q2 revenue number, and we have high confidence that we can achieve the low end of the guidance.
At the high end of the guidance, that would be outperformance across our portfolio. For Interventional specifically, again, we don't guide by business, but I think it's safe to say that we are targeting a modest sequential improvement in the interventional business quarter-over-quarter.
Jason Bednar
All right, very helpful. Thank you for that.
Then on EasyPlas, I'll try my hand here again on some forward guidance, but how would you have us think about this contribution? You talk about it as a material revenue contributor in 2027.
Is this a small revenue contribution? Do you want to put bands around it, 50 basis points or 100 basis points, just so we can get our models in order?
Then is this margin-accretive immediately for Teleflex, or do you need a certain scale for that margin accretion to materialize?
Jason Weidman
Okay. First thing on how to think about the revenue growth, this brand new market takes time with any new market.
It's a slow and steady growth over time. We don't guide on particular product areas, I'm not going to tighten it in on specific numbers, but I will reemphasize that we think it will be immaterial in this year 2026.
There'll be some contribution in 2027, and then modest from thereafter, after that initial kind of bolus and consistent demand that we expect from the government, which will take up the majority of our capacity. We'll start to develop that market, and then also start to build our capacity, which I think that will start to see more meaningful growth, a few years out as the market grows and capacity grows.
What was the second part of the question?
Jason Bednar
Margin-accretive immediately or do you need scale for margin accretion? Oh, margin, I'm sorry, thank you.
Jason Weidman
On margins. Look, with any product when you first launch, it typically takes a while for your margin to get to where you ultimately believe it will be, obviously.
It comes with volume. At the same time, margin is dictated by price, obviously, and our final pricing is not yet decided, and that's going to be decided largely as we work through the contract negotiation with the US government, and we're still engaged in that process right now, we don't have a final price decided on yet.
Operator
Your next question comes from the line of Mike Matson with Needham and Company. Mike, your line is now open, please go ahead.
Mike Matson
Thanks for taking my questions. I guess I wanted to start with one kind of strategy-oriented question.
I know you've still got to close the acute care and urology deal, and repay some more debt and whatnot, but it does sound like you're looking at doing some M&A in the future. Just reading the tea leaves here, it seems like that would more likely to be focused in the Interventional category, to bring in kind of higher-growth products there.
Is that a fair assessment? Just given, Jason, your background, the hiring of Jason Fontana, Sean Salmon on the board, it seems like the company kind of views its future here in Interventional, cardiology, just wanted to get your thoughts there.
Jason Weidman
Sure. The first thing I will definitely say is that we've got a lot of work to do on completing some of these foundational elements that are right in front of us, so that is by far our first priority.
We need to make sure that Interventional is fully integrated, and that that business is running as we expect. We need to complete the acute care and interventional urology divestiture, as you say.
TSAs, MSAs run beyond that. That work does not end when things close.
We've got just a lot of transformational work happening right now, I wouldn't anticipate any substantive M&A in the near term. As we move beyond, we feel more comfortable in working through that foundational work, we will certainly look at those opportunities to augment and shore up our three businesses.
We think that all three of our businesses are attractive and have attractive adjacent opportunities that we can pursue, and so we'll be looking across those. Certainly, Interventional is a big portion of that.
There are a lot of attractive adjacent markets, and so there will be opportunities there, but there are also will likely be opportunities in our other businesses.
Mike Matson
Thanks. Then just on the EasyPlas, the $200 million TAM that you talked about, are you willing to split that in terms of how much is military or government versus civilian use?
I think it used to be 50/50 when it was $100 million, but I don't know if that's still the case.
Jason Weidman
At this time, we're just not going to get into the details of that. I think that this is a long-term opportunity, right?
This is something that we're going to gradually build over time. We want to build it the right way.
We want to establish EasyPlas as the standard in the market, and ultimately, if you have deep penetration, there's probably more opportunity in the civilian market, but that's in the long term.
Operator
Your next question comes from the line of Travis Steed with Bank of America. Your line is now open, please go ahead.
Travis Steed
Hey, thanks for the question. I first want to start out kind of a higher level.
You talked about plans to elevate the growth profile, I think was the kind of the words you used, and I think there's a lot of synergies here between Biotronik and the Teleflex sales force, and you can throw things in like the Orsiro drug-eluting stent, and cross-sell that and gain share. Just trying to put together the strategy here of how you're thinking about accelerating growth, how long it takes to get this into place, can you grow in line with your mid-single-digit markets with potential to do above that over time?
Then I had a follow-up.
Jason Weidman
Travis, and are you asking specifically about Interventional then?
Travis Steed
I am, yeah. Surely.
Really just
Jason Weidman
the
Travis Steed
kind of the synergies on the Interventional.
Jason Weidman
Okay. Look, not to keep coming back to the same answer, but I think again our goal here is We're putting these things, these two parts of the interventional business together, and fully integrating them.
They do fit great together. This combined portfolio is excellent.
As you guys all know, I've been in this space for a very long time. This is a phenomenal portfolio.
We need to get it moving in the right direction. Our goal is to drive continuous improvement, set it up for a good 2027, improve it, get it to market growth, which we talked about earlier, mid single digits, set it up for long-term growth and long-term success.
We have a great pipeline, including potentially transformational products, the option equity of Freezsolve, and so that is our goal, and again, I'm highly confident in our ability to do that because we have so much opportunity. Given our current position in the market, there are a lot of people that aren't yet aware now of this combined total Teleflex, so that is on us, but as we drive that forward, we've got a lot of opportunities to gain share.
We've got a lot of opportunities to continue to expand geographically, where we have only a light presence in many parts of the world where the interventional business is quite penetrated. Again, we've got these really nice opportunities to gain growth with new product introduction, we feel good about where that's going.
Travis Steed
Great. Thanks a lot.
Kind of the follow-up question. There were calls prior where I think the $11.25, $11.50 in earnings had kind of been blessed a little bit, and I assume that us was kind of fully using full capital deployment.
I don't know with maybe the delay in the sell, is there potential that maybe that's still okay, but you need to adjust that for timing of capital deployment? On the kind of the delay, I don't know if that's something's changed there, or if it's kind of being prudent at this stage to leave yourself some room in case it does get delayed?
Jason Weidman
Why don't I answer the last part first, and then I'll pass off the question about the EPS to John. In terms of the divestiture of acute care and interventional urology, we still remain really confident that this transaction will close.
We are making progress. As we said back in the spring and have talked about since, we had a second request and it was due to a small product overlap with the buyer's portfolio.
The buyer is actively working on a remedy, and we are supporting that. We are collectively working together, and both of us, both the buyer and us, we are definitely targeting a close by the end of the year.
It's just that where we are at this stage and given, it's a regulatory process that has some things out of our control, we feel it's prudent to say that it is possible that it could move into 2027, it doesn't have to do at all with a change in confidence in our ability to get this done, just kind of where we are in the process. John.
I
John Deren
appreciate the EPS question. I think last quarter in the discussion, we're trying to communicate our optimism for the earnings potential for 2027, and I'll tell you we remain very optimistic.
I think with the leadership changes we made, the direction all three businesses are moving, we feel good about that. We've executed extremely well on our capital allocation plan so far, and we made significant progress in our planning to eliminate stranded costs resulting from both divestitures.
Let us get through Q4, let's get the ISG deal closed, and then we'll be in a good position to give you real solid guidance for 2027.
Operator
Your next question comes from the line of Lawrence Biegelsen with Wells Fargo. Your line is now open, please go ahead.
Nathan Treybeck
Good morning. This is Nathan Treybeck on for Larry.
Can you talk about the strengthening gross and operating margin in Q3 excluding the tariff refund? The guidance, it does seem to imply that operating margin will be down year-over-year in Q4 after being flat in Q3 when you exclude the tariff refund.
Can you just talk about why margins are like that in Q4? Thanks.
John Deren
Look, obviously the tariffs when you look at the EPS and margins, it was 290 basis points on margins, right? That, obviously that's a one-time item.
When we think about Q4, I will tell you there, we do have a significant step-up planned in R&D expense. We're ramping up the BIOMAG-III studies.
There's a number of significant start-up costs that take place, so that's some of the contraction we would see in Q4. That does not change our view on the long-term op margin.
Those are some start-up costs, and, frankly, that's going to be some timing in Q4. We feel pretty confident in the margins and see the one-time item in tariffs helping us in this quarter, and then a little bit of one-time costs as we ramp up the BIOMAG-III studies, and there's also some additional investments in the business that are expected to happen in Q4 across the rest of the portfolio.
Nathan Treybeck
That's helpful. You identified three transient drivers of the interventional shortfall.
Can you just rank them by revenue impact and tell us which are now fully resolved versus still open heading into 2027?
Jason Weidman
Look, I'm not going to rank them. I think that there's also kind of Venn diagram overlap of some of these, we don't get into the detail of specifically trying to calculate the exact revenue impact of each of those.
I would say that we continue to make solid progress on all of these, and there's still work to be done. For instance, on OTC transition, as I said, 90% of customers have transitioned over, we have 10% to go.
That should happen in the near term. The VI business, a large part of the VI business is a consignment business.
Consignment was new for Teleflex, we were still and are still working through our processes and getting better at consignment and how do we manage that, we still have work to be done. We're doing well, but we have work to be done to make that easier and less intensive for our teams.
From a distributor standpoint, as I said, we're about 87% there and transitioning legacy distributors over to Teleflex contracts and to become Teleflex distributors, we have a little bit of work to go there, but we're definitely on the upswing. Then on the sales force perspective, made huge strides on hiring the open positions, but of course it takes, on average, 6 months for reps to get productive, reps are going through that training and we'll have to do our final hiring, but we're in good shape, moving in the right direction.
Operator
Your final question comes from the line of Ravi Misra with Truist Securities. Your line is now open, please go ahead.
Ravi Misra
Hi, good morning. Thank you for taking the questions.
I guess I'll just ask first question just on guidance. The kind of 4Q guide is a little bit below consensus, and I appreciate you gave some of the metrics around non-operating items and just talking about a step-up in R&D here.
Is there anything else that we should be contemplating, like is the potential delay of the asset close going to lead to transition services kind of benefits that get pushed out, and we should take that out of our models? Then just relatedly, as we think about 2027, the Street has growth acceleration for you to kind of that roughly just under 5% range.
You gave a little bit of comments on the bottom line in your prepared comments. How should we think about the top line?
Is that still the place to be? Thank you.
Jason Weidman
First, I'll just comment on the 2027 and then, John, I'll let you comment on Q4 and those specific questions of the guidance. The short answer is we're not going to give guidance on 2027 in this call.
We'll do that in the next call. We're still working through everything that's going on in the business, going through our planning for next year, we're not in the position to provide numbers for next year.
We feel good about the direction we're going. We got a lot of opportunities ahead of us, and we'll update you on the next call for that.
John Deren
As far as the bottom line, I'm sorry I don't reconcile to everyone's consensus here, but at the end of the day, we've increased EPS guidance for operational items that have been very positive across the portfolio. We have not included in the past anything that we haven't entered into, there are no TSAs and MSAs that we would have in the guidance today for the ISG deal.
They are not considered in the guidance, there's no change there or no hesitation, if you will. There is some TSA and MSA income from the OEM deal, and that'll continue and that is part of our guidance that'll continue through the end of the year and well into next year.
No, there's nothing else there that you haven't heard.
Ravi Misra
Thank you.
Operator
There are no further questions at this time. I will now turn the call back to Lawrence Keusch for closing remarks.
Lawrence Keusch
Thank you, Alexandra, and thank you to everyone who joined us on the call today. This concludes the Teleflex Incorporated Third Quarter 2026 Earnings Conference Call.
Operator
This concludes today's call. Thank you for attending.
You may now disconnect.