Timken Company (The)
Q3 FY2026 · Earnings Call TranscriptNovember 4, 2026
Operator
Good morning, ladies and gentlemen, and welcome to Timken's Third Quarter Earnings Release Conference Call. All participants will be in a listen-only mode, and should you need assistance, please signal a conference specialist by pressing the star key followed by zero.
After today's presentation, there will be an opportunity to ask questions. Please note this event is being recorded.
I would now like to turn the conference over to Mr. Neil Frohnapple.
Welcome, sir. You may begin.
Neil Frohnapple
Thank you, operator, and welcome, everyone, to our third-quarter 2026 earnings conference call. This is Neil Frohnapple, Vice President of Investor Relations for The Timken Company.
We appreciate you joining us today. Before we begin our remarks this morning, I want to point out that we have posted presentation materials on the company's website that we will reference as part of today's review of the quarterly results.
You can also access this material through the download feature on the earnings call webcast link. With me today are The Timken Company's President and CEO, Lucian Boldea, and Mike Discenza, our Chief Financial Officer.
We will have opening comments this morning from both Lucian and Mike before we open up the call for your questions. During the Q&A, I would ask that you please limit your questions to one question and one follow-up at a time to allow everyone a chance to participate.
During today's call, you may hear forward-looking statements related to our future financial results, plans, and business operations. Our actual results may differ materially from those projected or implied due to a variety of factors, which we describe in greater detail in today's press release and in our reports filed with the SEC, which are available on the timken.com website.
We have included reconciliations between non-GAAP financial information and its GAAP equivalent in the press release and presentation materials. Today's call is copyrighted by The Timken Company, and without express written consent, we prohibit any use, recording, or transmission of any portion of the call.
With that, I would like to thank you for your interest in The Timken Company, and I will now turn the call over to Lucian.
Lucian Boldea
Thanks, Neil, and good morning, everyone. We appreciate you joining us today to discuss our quarterly results and outlook.
I'd like to begin by thanking our Timken team for their dedication to our customers and for the significant progress they have made in advancing our company's transformation. As I reflect on my first year at Timken, I'm proud of what we've accomplished together.
We have developed and deployed our Elevate to Outperform strategy to build upon our strong foundation and transform Timken into a leader in advanced motion technology. We've aligned our teams around our disciplined execution framework that anchors the strategy and made substantial progress towards achieving our 2028 targets, most notably in industrial motion, where we delivered high-single-digit organic sales growth and significant margin expansion so far this year.
The steps we have taken and early results reinforce my confidence in our direction and the significant opportunities ahead. Let me now turn to our third-quarter performance, including the advancements we are making in executing our strategic priorities.
In the quarter, total sales were up 4.7% versus last year, and organic revenue grew by nearly 3%, driven by positive pricing and higher volumes in the Industrial Motion segment. We saw improving demand trends across most of our industrial markets, and if we exclude the significant decline in China wind energy sales from a very strong third quarter in 2025, organic sales were up mid-single digits from last year.
We expanded EBITDA margins to 18.5%, driven by positive price-cost and higher volumes. Adjusted earnings per share increased 20% year-over-year to $1.65.
We also generated over $220 million in free cash flow. Regarding capital allocation, we repurchased more than 500,000 shares during the third quarter, substantially increasing our buyback activity from the first half of the year.
Our net leverage ratio also declined to 1.7 times EBITDA. Our strong balance sheet gives us flexibility to fuel our capital allocation priorities.
In the quarter, we delivered meaningful progress across all three pillars of our strategy as we put 80/20 and our disciplined execution framework to work across the entire enterprise. Starting with pillar one, optimizing the portfolio, we completed the divestiture of the belts business near the end of the quarter.
This is an important milestone in achieving our 2028 financial targets, and we expect this action to increase Industrial Motion EBITDA margins by more than 200 basis points in 2027. We also continue to build great momentum with 80/20.
With employee training largely complete and work streams established and underway, 80/20 teams are taking actions across our businesses and regions. A few recent examples include the implementation of minimum order values for customers to reduce our cost to serve and improve profitability without negatively impacting total revenue.
We also established our differentiated commercial service model to drive incremental growth with our 80s customers. Key account playbooks have been developed and deployed at a number of large accounts to grow our share of wallet by engaging as a One Timken solution provider.
Overall, I'm very encouraged by what we're seeing. These initiatives are well underway and generating positive early results by reducing complexity and expanding margins while increasing our focus on the fastest-growing customers and verticals.
That brings us to pillar two, where we are stepping up our resources, investments, and customer-facing efforts to drive outgrowth within our strategic verticals. Building a vertically aligned M&A pipeline is also a priority.
This organizational focus contributed to double-digit growth in automation and robotics during the quarter. We also completed a minority investment in an early-stage manufacturer of electroadhesive technology, highlighting how we're expanding our technology model to align with next-generation motion technologies.
This investment is intended to support our growth in automation and robotics. For pillar three, our One Timken operating model is fully in place to speed up decision-making and execution and to bring together commercial and operating organizations.
Our recently announced Chief Commercial Officer structure is connecting strategic marketing, sales excellence, and execution across our multinational footprint to generate greater differentiation, enhance customer value, and, most importantly, accelerate growth. This supports our One Timken commercial strategy, which is already driving greater integration across many of our platforms, including precision drives.
For example, in precision drives, Cone Drive and Spinea brought together complementary technologies and expertise to develop an integrated actuator solution for the commercial space industry. It's an exciting example of our evolution towards a system-based solution.
We're also accelerating the integration of our lubrication systems platform. Over the past decade, we have added capabilities in this space through strategic acquisitions.
Today, we are reducing portfolio complexity, aligning commercial resources with our strategic verticals, and aggressively scaling across Timken's multinational footprint beyond the business's largely European base. Our Chief Operating Officer structure, led by Steve Robatto, who joined Timken in September, is now responsible for our P&Ls.
With this structure, business leaders have greater accountability for the strategic choices that shape business performance, investments, and long-term competitiveness. Additionally, by bringing the entire supply chain footprint under a single organization and aligning individual factories with P&Ls, we will continue to benefit from rightsizing and maintaining a nimble and globally flexible footprint that is competitive on cost and lead times to support our customers' growth.
Taken together, these actions show how the Timken team is moving with speed to execute our Elevate to Outperform strategy. We are focused on finishing the year strong and delivering our 2026 outlook, and we are confident in our ability to achieve even stronger performance next year.
While it is still early, we currently expect our organic sales to increase by mid-single digits during 2027, driven by incremental growth from our strategic initiatives and further positive momentum across our industrial markets. As one example of the momentum we are seeing, the company's backlog at the end of the third quarter grew sequentially and was up mid-single digits from last year.
With that, let me turn the call over to Mike for a more detailed review of the results and outlook. Mike?
Mike Discenza
Thanks, Lucian, and good morning, everyone. For the financial review, I'm going to start on slide six of the materials with a summary of our third-quarter results.
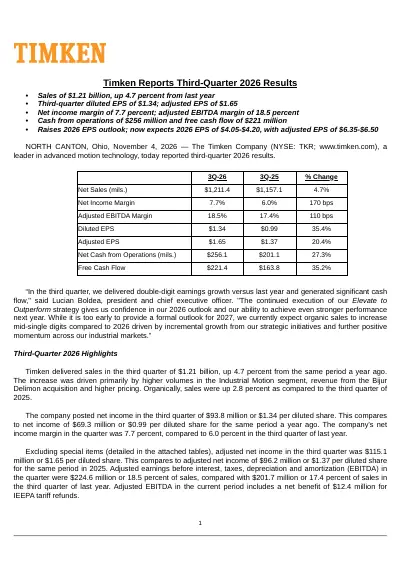
Overall, total revenue for the quarter was $1.21 billion, which was up 4.7% from last year. Adjusted EBITDA margins increased to 18.5%, and adjusted earnings per share for the quarter was $1.65.
Note that our adjusted results include a net benefit for IEEPA tariff refunds of approximately $12 million or 13 cents per share. Turning to slide seven, let's take a closer look at our third-quarter sales.
Organically, sales were up 2.8% from last year. The increase was driven by higher volumes in the Industrial Motion segment and positive pricing across both segments.
Looking at the rest of the revenue walk, the acquisition of CGI Deliman added 1.8% to sales in the quarter, while foreign currency translation had minimal impact on the top line. On the right, you can see third-quarter performance in terms of organic growth by region.
In the Americas, our largest region, we were up 6%, driven by growth across both segments and most end-market sectors. In EMEA, we were down 3% from last year, driven by lower demand in the Engineered Bearings segment, while Industrial Motion revenue was relatively flat with last year.
Finally, we were up 3% in Asia Pacific, driven primarily by strong growth across most of the region, partially offset by lower sales in China. Turning to slide eight, adjusted EBITDA was $225 million or 18.5% of sales in the third quarter, compared to 17.4% of sales last year.
Let me comment a little further on a few of the different drivers on the EBITDA bridge you can see on this slide. Starting with the impact of pricing in the quarter, it was positive $12 million and added 1% to the top line as we continued to benefit from pricing actions over the last year.
As you can see on the slide, tariffs had a $14 million net favorable impact versus last year, driven by the benefit of refunds and modestly lower tariff costs compared to the prior year. Looking at material and logistics, costs were modestly higher versus last year, driven by logistics.
With respect to the manufacturing cost line, the increase primarily reflects labor and other cost inflation, including investments we are making to strengthen our aerospace and defense operations. Moving to the SG&A and other line, expenses were up from last year, as expected, driven primarily by higher compensation expense and spending on strategic initiatives.
Finally, our CGI Deliman acquisition contributed $4 million to adjusted EBITDA in the quarter, with a high-teens margin. Now let's move to our business segment results, starting with Engineered Bearings on slide nine.
Engineered Bearings sales were $771 million in the quarter, up 0.7% from last year. Organic sales were up 0.5%, driven by higher pricing, while volumes were relatively flat.
Among market sectors, aerospace and defense achieved the strongest gain versus last year. We also posted growth across the automation and industrial solutions, infrastructure, and industrial transportation and mobility sectors.
However, we experienced a double-digit decline in power and electrification, driven by a significant decrease in China wind revenue. Note that organic sales for the segment were up more than 3% from last year when excluding the impact from China wind.
Engineered Bearings adjusted EBITDA was $156 million or 20.2% of sales in the third quarter, compared to 18.8% of sales last year. Margins in the quarter benefited from tariff refunds and favorable price-mix.
However, margins were negatively impacted by higher operating costs compared to last year. Now let's turn to Industrial Motion on slide 10.
Industrial Motion sales were $440 million in the quarter, up 12.4% from last year. Organically, sales increased 7.3%, driven by higher demand across most market sectors and higher pricing.
The CGI Deliman acquisition also added more than 5% to the segment's top line in the quarter. Among market sectors, aerospace and defense was up nearly 20% versus the prior year.
We also generated growth across automation and industrial solutions, infrastructure, and power and electrification, while industrial transportation and mobility was relatively flat with last year. The segment saw solid growth in the quarter across all product platforms and was led by double-digit gains in linear motion systems.
Industrial Motion's adjusted EBITDA margins came in at 19.8% of sales in the third quarter, up 80 basis points from last year. The increase in segment margins reflects the impact of higher volumes and favorable price-mix.
Organically, segment incremental margins were about 30%. Moving to slide 11, you can see that we generated operating cash flow of $256 million in the third quarter, and after capex, free cash flow was $221 million, up significantly from the prior year.
From a capital allocation standpoint, we returned $89 million of cash to shareholders through share buybacks and dividends in the third quarter. Note that we have approximately 9 million shares remaining on our repurchase authorization.
Looking at the balance sheet, we ended the third quarter with net debt to adjusted EBITDA at 1.7 times, which is an improvement from last quarter, driven by higher EBITDA and debt paydown. Now let's turn to the current outlook for full-year 2026, with a summary on slide 13.
Starting with the bottom line, we are increasing our adjusted earnings per share outlook to the range of $6.35 to $6.50, which represents 20% growth at the midpoint versus 2025. With respect to net sales, we expect total revenue to increase approximately 5.5%, unchanged versus the midpoint of the prior range.
Organically, we are reaffirming our outlook for revenue to be up 3.5% at the midpoint. Currency translation is estimated to contribute around 1.25% to sales for the year, up slightly from the prior guide.
M&A is expected to add 0.75% to full-year revenue on a net basis. The CGI Deliman acquisition continues to perform well, while the updated outlook now reflects the impact of the belts divestiture on the fourth quarter.
The current earnings outlook implies that our 2026 consolidated adjusted EBITDA margin will be in the mid-18% range at the midpoint, slightly higher than the prior guidance to primarily reflect the third-quarter performance. Moving to free cash flow, we expect to generate $375 to $400 million in 2026, unchanged from the prior outlook.
On slide 14, we provide an updated view on our 2026 organic sales outlook by end-market sector, which includes the impact of both volumes and pricing. Again, we are reaffirming the full-year organic sales growth rate of 3.5%.
You can see that we upgraded our outlook for the automation and industrial solutions sector, while we reduced our outlook for the power and electrification sector. Note that our outlook assumes that sales in the China wind market decline again in the fourth quarter, both sequentially and year-on-year.
Keep in mind that our China wind business is expected to be only a low-single-digit percentage of total company sales in 2026, with the run rate in the second half of this year now below prior trough levels. As a result, we would not expect this business to have a significant impact on the full-year 2027 outlook and supports the step-up in the organic sales outlook for next year that Lucian highlighted earlier.
Moving to slide 15, here we provide a bridge of the increase in our 2026 adjusted earnings per share outlook at the midpoint. Most of the increase is driven primarily by our outperformance in the third quarter, including the impact of the tariff refunds.
You can also see that we are adding 8 cents per share to reflect a lower net interest expense outlook for the year compared to our last guide. In summary, Timken delivered solid results in the third quarter, including double-digit earnings growth and strong cash flow.
We have a strong balance sheet, significant capital deployment optionality, and are well positioned to achieve strong earnings growth again in 2027. Let me turn it back over to Lucian for some final remarks before we open the line for questions.
Lucian?
Lucian Boldea
Thanks, Mike. Let me reiterate that we are focused on delivering a strong finish to the year while making continued progress on our Elevate to Outperform strategy, which is a multi-year transformation.
In 2026, we have taken significant actions to transform the core of our business, to reduce complexity and exit non-strategic underperforming businesses, refocus our resources on strategic verticals, and integrate our Timken operating system. As a leadership team, we take our commitments very seriously, and we'll continue to work relentlessly to deliver what we committed to.
Our plans are on track, and we remain confident that our strategy will accelerate growth, structurally increase margin, and drive significant shareholder value over the coming years.
Mike Discenza
Thanks, Lucian. This concludes our formal remarks.
We'll now open up the line for questions. Operator?
Operator
Gentlemen, thank you. To our phone audience joining today, at this time, we will now begin the question-and-answer session.
If you would like to ask a question, you may press star and then the digit one on your telephone. If you are using a speakerphone today, please pick up your handset prior to pressing the keys.
If you would like to withdraw your question, repeat the steps: star one will also remove you from the queue. We'll take just a moment to pause momentarily while we assemble our roster.
We'll hear first from the line of Bryan Blair with Oppenheimer.
Bryan Blair
Thank you. Good morning, guys.
Good
Lucian Boldea
morning, Bryan.
Bryan Blair
We know your Q4 organic sales outlook is unchanged, similar growth to Q3. Maybe offer a little more color on how orders trended through October and how we should think about core growth by segment in the fourth quarter.
I assume that China wind is a little bit less of a, quote unquote, bad guy on the bearing side and the comp is obviously a bit healthier for industrial motion.
Lucian Boldea
Thank you, Bryan. I think you have to look at the context of Q3 and Q4 and everything that we're doing to transform the company, you a little bit looking at the duck going across the water and not everything that's happening beneath the surface.
We're definitely focusing our resources where we said, and you look at the early wins, we alluded to that in our prepared remarks, where our pipeline sat year-over-year. Our pipeline is up in Q3 mid-single digits, but then what's more exciting is the percent increases that happen in that pipeline in our focus verticals.
Whether you're talking about automation and robotics or whether you're talking about aerospace and defense, where there are significant double-digit increases, those happened in Q3 in the pipeline. Obviously, they will continue to happen.
We expect for them to continue to happen in Q4 as well. The demand picture externally, we don't see that being dramatically different going from Q3 to Q4, but the undercurrent from all this is also, obviously, we have an automotive OE unwind that is already having a little bit of volume impact that we're offsetting with growth, and so there's a lot of churn in here that we're doing to really deliver on a number and on a commitment that we have made, and I'm proud of the team that we have done that, and we're trying to give that same kind of appropriate guidance for Q4 on what we believe we're going to do.
The pipeline, order book that we're looking at, all the indicators say that we're headed in the right direction, it is going as planned, there no big surprises, assuming the market just holds the way it is and continues to stay where it is, then we feel very good about our ability to deliver similar performance in Q4, and then we've already given a little bit of a view into 2027 without really giving a guide, but that's where we are.
Bryan Blair
I appreciate the color. You did offer a segue to the preliminary 2027 outlook there, I have to dive in a bit.
If it's fair to assume that consistent with the medium-term framework you put out there and performance through 2026, that you're contemplating high-single-digits industrial motion growth next year, more low-single on the bearing side? Then if we look across your major end markets, I think you alluded to some of these dynamics in your prior answer, but how would you rank order growth expectations given current visibility?
Lucian Boldea
Absolutely. I think if you look, I think what you said is is appropriate.
We definitely, obviously, now we focus on finishing '26 strong, but the the destiny for Q1 is pretty much set during Q4, and so we we definitely are focusing on on both. I think it's a little early to comment on 2027 with a lot of certainty, but expecting our organic sales to increase by mid-single digits is still the case.
Our strategic initiatives are starting to drive incremental growth, and those will, of course, only accelerate as we move forward. The markets that you were asking about, absolutely, automation and robotics is very much the leader in driving that growth, but right behind it is aerospace and defense.
In both of these, we're seeing increases in our pipeline of double-digit year-over-year, and it's it's not a low-double-digit number, it's a very healthy double-digit number. That gives us gives us a lot of confidence that we will be able to start benefiting more and more from pivoting that portfolio.
Obviously, there's still pricing. I'm sure there'll be other other questions on pricing later, but to tease that a little bit early on, in our price minus cost in Q3 was positive on a year-over-year basis, it was positive sequentially.
We expect the same in Q4, both year-over-year as well as sequentially from Q3. That says that our discipline around pricing is there, our track record is now there, we feel good about that being additive to our organic to our volume growth going into 2027.
There's 80/20, obviously, that's going to start being a beneficiary not only to the bottom line, but to the top line as we focus on customers, so that will that will help as well. Then on the margin side, belts, you're going to start seeing that already in Q4, and really we feel good about seeing seeing a significant impact to that in 2027.
We've committed to more than 200 basis points of Industrial Motion margin, so that's a third of the company, take a third of that number, 60 to 70 bps from from the belts. Again, all those actions that we have taken, without really providing a formal outlook, make us confident in our ability to achieve stronger performance in 2027 as we continue to build upon what we're executing today.
Bryan Blair
Understood. Thank you again.
Lucian Boldea
Thank you.
Mike Discenza
Thanks, Bryan.
Operator
Our next question will come from the line of David Raso at Evercore.
David Raso
Hi, thank you for the time. I was curious, you spoke of auto OE exits as part of the fourth-quarter comments, but when you speak of organic sales next year, mid-single-digit growth, is that including with some of the auto exits or excluding, just to level set, then I have a follow-up.
Lucian Boldea
What we've committed to is a net number. Absolutely, yes.
David Raso
The mid-single digit is even with, I'll put a number around it, $100 million of revenue backed away from an auto, even with exiting that, you still look at mid-single digit. It includes the exiting, just to be clear?
Lucian Boldea
I'll remind you that the majority of the revenue exit is not in 2027, that happens in '28, but there is a number in '27 as well. It's smaller than what you mentioned.
It's a part of the total, but the majority is in '28. Yes, the number is a net number is the answer.
David Raso
Helpful. I'm just trying to understand, I thought the China wind business, the comp gets easier in the fourth quarter to the extent where EB this quarter would have been 3.8% organic without the China wind drag.
That's why I'm just curious if that's sort of the bogey, and the wind year-over-year, if I remember correctly, it's not much of a decline. If you kept it like China wind, I guess, sequentially, are we now kind of flatlining a little bit sequentially?
Because if that's the case, I think the comp becomes almost nil. Why would EB go from 3.8% ex-wind to still sub-3 in the fourth quarter?
I'm just trying to get the confidence on EB showing any growth into '27 and why is that a credible view.
Lucian Boldea
Right. No, that's very fair, and, again, we can go into more detail on China wind, but what I would tell you is at a high level, there is another step down sequentially going from Q3 to Q4.
When you look at it at that point, it really becomes low-single-digit percentage of the total, it's no longer that significant. Having said that, if you recall first half of 2026, we had pretty strong performance.
It was also in the back half of '25, there was about a 12-month period that was pretty strong. China wind tends to be a little more cyclical, a little more lumpy, and there's nothing that says that overall demand is going away or that we're not competitive or any of that.
What the reality of that market is it does tend to be a little more cyclical, and so we're now in the down cycle. It's a little bit down, Q4 versus Q3 is another step down sequentially.
David Raso
One last thing, sorry if I missed it, when I do price-cost, I also include the mix in it, and that mix was the real drag when we look at price-cost. I'm excluding IEEPA.
The mix was very different in this quarter. It was a negative 2, and last quarter, I think it was a positive $13 million.
Did I miss that? What was the big mix change?
Mike Discenza
No, you're right, David. You didn't miss it.
It was primarily in the Industrial Motion segment where we had the larger mix impact, and it really is just the shift in where the growth was. We grew still in some of the higher-margin businesses, but grew at a slower rate in the higher-margin businesses and a little bit faster in some of the lower-margin businesses.
It really was just a mix, and think, the highest-margin businesses, lubrication, linear motion, etc., our Philadelphia Gear business, and then lower-margin businesses like chain and some of the more OE-focused markets. It really was just a shift between the markets and the growth rates between the quarters.
David Raso
Thank you. I appreciate the time.
Oh, sorry, go ahead, Lucian.
Lucian Boldea
Thank you. No, and I was also going to add regionally, I think if you look at where our slow growth was, Industrial Motion has a very heavy European footprint, Europe being down in Q3, and really almost all of that happened in the month of August, that also weighed down that mix from a regional standpoint.
David Raso
Thank you.
Lucian Boldea
Sure.
Operator
Our next question will come from Angel Castillo at Morgan Stanley.
Hey, good morning, guys. This is Oliver on for Angel today.
Good morning. When we look across, kind of organic growth across your peers, do you feel like you have the mandate to go and take more price, or maybe are we making some sort of strategic choice here in terms of price-cost?
Just hoping you could help us understand kind of confidence in re-acceleration going forward.
Lucian Boldea
Yeah. Look, really appreciate the question.
As I said, we're in the midst of a pretty significant transformation on how we're thinking about our business, and so on one hand, yes, you think of the three pillars of the strategy and how we're trying to focus on the right verticals. We're doing 80/20 to focus on our 80s customers to get more share of wallet to be a little bit less cyclical than we are today and to really be more resilient and more efficient in our growth.
What we've also started now to do is we set up a Chief Operating Officer organization and we're frankly looking at our assets differently. We are taking that sweat the assets mindset, which means leveraging that fixed cost.
It's a two-step process. We look in the mirror, we look at our cost structure, we build a competitive cost structure, and then with confidence, we go out and compete and we use the capacity that we have.
When the capacity is not competitive, then we take action and we reduce that capacity. It's our job to maintain the capacity that's competitive, and once we have it, we use it.
Aligning those P&Ls with the factories and really having that sweat the asset focus is going to get additional opportunity to do some of the things that you are talking about, especially on the Engineered Bearings side, where you're more fixed-cost intensive, and so that fixed-cost leverage does create a lot of value.
Understood. Maybe just to follow up on that.
The One Timken, it's helped you drive some early wins here. You're able to combine some different capabilities.
The question is, is the sum greater than the parts here? Is there some margin uplift or maybe some revenue uplift that's maybe we're not fully appreciating?
Lucian Boldea
Look, the sum is much greater than the parts, and the sum is greater than the parts both in how we operate, but also how we present ourselves to the market. One Timken sometimes is a big word, and people take it to the extreme that it means every product line to every customer.
Clearly, it doesn't. If you look at data in any pick the random company, what you will find is if you take one customer that does business with three or more business units inside the company, that customer is more loyal, that customer is more sticky, you have more ability to collaborate with that customer and innovation.
It's just everything gets better with a multi-business line customer. That doesn't happen if you leave it kind of to one business at a time, everybody for themselves.
If you present yourself to this customer as one company, then you can combine the appropriate value, the appropriate offerings so that the sum of the parts is greater. It also allows you to bring more of a solution in.
We used the example in the prepared remarks where we were talking to somebody in the space industry and they were an existing customer using one of our legacy solutions in their Gen 1 product. They were moving to a next-gen product where the precision of what they required was far greater.
The good news is, as we looked at our Cone Drive technology that they were using originally, we were able to shift them over to cycloidal gearbox through Spinea. That's a little higher cost technology, but much higher precision, which met their need.
That generated a higher-value opportunity for us with the same customer. In addition to that, we were able to then convince them to sell them the subsystem instead of just the gearbox, which generated really 2.5, almost 3 times more revenue than the opportunity would have otherwise.
We took something that was business at risk and turned it into a much bigger opportunity than it was before, but much more importantly, build credibility with that customer that we actually can provide a solution instead of what we would have done in the past, maybe try to negotiate the price on a technology that really didn't meet their need going forward. It's just an example.
Now when you step to the back of the store, operationally, there's even more opportunity there. You go from very simple things like why would you not buy airline tickets, hotel rooms, and rental cars and all that one single way?
Why would you buy steel two different ways? You wouldn't.
How would you manage real estate? You'd manage it all together.
That's all kind of table stakes, obvious. Some of that we've already been doing.
We're going to do more of it more deliberately. Then how do you take 100-plus operating locations and establish playbooks by archetype?
They're not all the same, but they're not all different. Are there four or five different archetypes that you can then establish unique KPIs for those, an automation strategy, and operating those and then, finally, sweating those assets?
The sum of the parts is definitely greater here as we move forward. I'm convinced of that.
I'm convinced of that both operationally, but especially in front of the customers. As we engage with these 80s customers and with our key account plans, we've done a few by now, and wherever we go, we see value.
We have to see one yet where we walk home and say, well, that was not a good idea. It's working.
The early indications are there. Obviously, this takes time.
You don't show up the first day and land a bunch of revenue that afternoon, but we do see early wins. We see pipeline.
We see orders. We see all the indications that we need to see that give us a lot of confidence that we're headed on the right track.
That's great to hear.
Mike Discenza
Thanks, Oliver.
Thanks very much.
Lucian Boldea
Thank you.
Operator
Our next question comes from Rob Wertheimer at Melius Research.
Rob Wertheimer
Hi, thanks, and good morning. I had one kind of in a similar vein Good morning.
to what David asked. As you've worked through 80/20 and opportunities and things you might cut, is there any other drag in 2027 from fading smaller products that had low volume, etc.?
Then I had a follow-up if I can. Thank you.
Lucian Boldea
Thank you for the question. The short answer is no drag from 80/20 in 2027.
We think the drag is behind us, where it was more of an investment. We're now at a point where we're at least paying for that investment through the early actions.
I gave some examples in the prepared remarks. The benefits are starting to flow in as you enter into 2027, where 80/20 is a net benefit.
I say that from a cost side, from the cost of implementing 80/20, the cost of training, the cost of all that, it's a net benefit. The bigger benefit, obviously, it's called 80/20 and not 20/80 because the benefit doesn't come from the 20s, the benefit comes from the 80s.
The benefit comes from growth. That's what's most exciting to me about 80/20 is this engagement with our key customers, key account plans, bringing more than one Timken business to bear to solving a customer problem.
That's what will change our trajectory. Frankly, that's what's already helping our Industrial Motion.
Our Industrial Motion business now has several quarters in a row where we're growing very nicely in the mid-to-high single digits, and so that's expected not only to continue, but to start accelerating that number.
Rob Wertheimer
Perfect. Thank you.
Then maybe it's small, I don't know, but the electroadhesive acquisition is not one I expected, I wonder if you could expand for a second on how that fits into current either technology or end market, and then does that significantly kind of signal an expansion of your acquisition playfield or tamp? I'll stop there.
Thank you.
Lucian Boldea
Right. No, Look, it's a great question, and I have to confess, when it was introduced to me a while back with that name, electroadhesive, I said the same thing: what is mechanical engineering or tribology or precision machining in there?
May give you a layman's explanation at least that I think of on this technology. Basically think of an e-brake that holds position without consuming electricity.
On a humanoid, if it has to pick something up and then it has to hold that position very firmly without really consuming battery life, that's what this technology does. Humanoid is a great application, but you can think of this as also in other industrial applications.
It's not a brake in the sense of a car, it doesn't slow something down. It holds position locked.
It's either on or off, but it does it in a very energy-efficient way. Where battery life is very important, we think this technology is a big enabler, again, in conjunction with actuators, in conjunction with some of the other offerings, because then we'll do the go and we'll do the stop at the same time with equal precision and in an energy-efficient manner.
That's the idea of the technology. It's part of the overall solution being more of a systems provider.
Rob Wertheimer
Thank you.
Lucian Boldea
Of course.
Operator
Our next question will come from Kyle Menges at Citigroup. Please go ahead.
Kyle Menges
Thanks. Maybe a follow-up on Rob's last question.
Lucian, I think you made comments about starting to build up an M&A pipeline and would just love to hear just anything you can share on maybe how that M&A pipeline is building, areas of focus, and are we still thinking about bolt-ons or could there be potential for anything larger?
Lucian Boldea
Let me start with the last question because that's the easiest one. Yes, still bolt-ons, not something larger.
How we think about our M&A pipeline is really way more strategically aligned with the verticals. One of the things that we tried to do at Investor Day is to really lay out very, very clearly our roadmap: how we're trying to grow, where we're trying to grow, how we're trying to win, also both the where to play and how to win.
We articulated the key verticals, and so what that means is really we expect our M&A pipeline to really be aligned with those key verticals. What I would tell you is there would be probably two two types of M&A: one, you can think a little bit in terms of the CGI Deliman being an example: how do I further the technology platforms that I have, continue to solidify my leadership, how do I add more complementary offerings in these key markets that really work with the solutions that we already provide; and then there's a smaller subset, which is similar to this investment in this technology, which is R&D make versus buy.
We might do an acquisition that maybe doesn't have a lot of revenue, but you acquire a technical capability that then you can leverage in the portfolio to bring your current solutions or pull others through the market. Would have to be pretty well aligned with our focus markets and with where we're trying to go.
The other part that we're developing and have now developed is this playbook of regionally translating our existing acquisitions. We have 22 of those that we've made in the last 10 years, depending on exactly how granular you get with the count, and most of those are regional in Industrial Motion.
How we translate those from one region to another will become a playbook for a future M&A as well, where we'll be in a great position to buy a single-region play that then we can very quickly copy-paste, translate into other regions, and so that's another avenue to create value with M&A that we now have in place.
Kyle Menges
Got it. That's helpful, Lucian.
Then it seems like since the Investor Day, you continue to talk about 80/20 initiatives and maybe some organizational changes as well that at least some of which feel somewhat incremental. Would love to just hear what you feel like you've been doing on 80/20 and any other restructuring initiatives that you would say are probably incremental from what you laid out at the Investor Day.
Lucian Boldea
Yeah. Look, I think if you polled 19,000 people today, I would bet you won't find many that say it's it's incremental.
We've we've made a lot of a lot of changes in the company. If you think how we were operating a year ago, we had an Engineered Bearings segment that was running like a vertical P&L, and then Industrial Motion running separately.
We've turned that basically 90 degrees on its on its side, and so we have a single Chief Operating Officer that runs a single customer-facing organization that's regional first, but inside those regions, it's verticalized. It's not territories, it's not product lines, it's verticals, it's industries.
The entire sales force went from you had an EB sales force, and then you had, a dozen IM sales forces, now you have a Timken sales force. If you go to Europe, you have a Timken sales force that might be focused on automation, you might have one that focused on aerospace and defense, and they're specialized in that area.
That transformation on the customer-facing side is dramatic. We have a technology organization under Chief Technology Officer that now includes the entire company.
It's not independent organizations inside the P&Ls, so that's that's pulled together. Then on the operations side, we have a single COO that includes Bearings, includes Industrial Motion.
Inside the P&Ls, we used to have the P&Ls aligned by market, they're now aligned with the factories. We would have a rail P&L in Bearings and an aerospace one.
Now, those share they'll share the factory, by the way. That's no longer the case.
I have a small bore and a large bore P&L ownership in Bearings that basically is aligned with the network of factories that then can be leveraged so they can sweat the assets. There's been very very significant changes under the surface to really operationalize this.
The more significant change, and Steve is driving even more of that, Steve Robatto, as he joined our COO, is that's the hardware, the org structure. The software, obviously, is the operating model, that discipline, that cadence.
We now have a a cadence every month, we call it business decision week. That's where it's a prescribed agenda, it happens the same day every month, it's the same system, it's the same reporting, just new numbers every month, and we refer to what did we do, what did we say we were going to do, did we get it done, what are we doing to mitigate.
All that is very transparent, very prescribed. There's a substantial amount of operationalizing the strategy that's happened, some before Investor Day, but most of it after Investor Day, and it's now really taking shape on the back of the store with Steve Robatto joining in September as COO.
Kyle Menges
Great. That's helpful.
I guess this was all kind of within that plan that you shared at the Investor Day.
Lucian Boldea
Yes, it is within the plan, but some of it at Investor Day was a plan. It is now past tense actions.
Kyle Menges
Got it. That's helpful.
Thank you.
Lucian Boldea
Sure.
Mike Discenza
Thanks, Kyle.
Operator
Our next question will come from Steve Barger at KeyBanc.
Steve Barger
Hey, thanks. Really nice to see the positive backlog trend.
How much of the mid-single-digit backlog growth is OEM versus aftermarket and distribution? Where are you seeing the most acceleration in OEM schedules?
Mike Discenza
Hey, Steve. Mike here.
Thanks for the question. Maybe I'll come at that question a slightly different way, because we don't really classify the backlog by channel.
What I would say is that our channel partners, we feel confident that the inventory levels are in a good place. The backlog is commensurate with kind of the sell-through rate, if you will.
Order intake strong there, commensurate with strong sales growth. On the OE side, Lucian referred to where we were seeing the strengths, but maybe to get one level more specific, we saw strong order book growth in our infrastructure market, which would include things like heavy industries, off-highway, etc.
Of course, aerospace has been growing strong and continued to grow strong, and that's in both segments, both Industrial Motion and Engineered Bearings, see continued backlog growth there. Then general industrial, which again cuts across a lot of the lighter, say, industrial markets.
The one place where we obviously are struggling from an order book standpoint was wind energy, which was down substantially, and we already said would be down again in the fourth quarter. Hopefully that helps give a little color.
Steve Barger
I appreciate that. Then, Lucian, you said the early minimum order and customer segmentation actions are improving profitability without affecting revenue.
Are the benefits that you're seeing so far from a better price versus cost to serve, or are you already driving incremental growth and share of wallet with the high-priority customers?
Lucian Boldea
Both are already happening, I think that we have a few examples now with larger customers where really probably September was the first month where I could really hang my hat on a significant number that made a difference to say, okay, yes, this is starting to pay off. I can identify discrete opportunities at these large customers that were directly related to opportunities we got through a different level of engagement.
I think that started really in earnest in September, and then as we expand that effort, I'm optimistic, obviously, that's going to grow not only with the customers we've already engaged, but also as we expand the customers. The minimum order value that came from when you do 80/20, you do a zero-up, and you kind of look in the mirror and say, okay, what does it actually cost me to process an order?
It's not a small number, and then you realize that maybe you were processing orders that were below the revenue that it cost you to process the order, and why on earth would you do that? Also recognizing that, by the way, the customer that places the order, it's not free for them either to place that order, and it just doesn't make any sense.
We have a minimum order value now that's going to allow us to be more efficient. For the time being, what that does in the immediate term is it frees up the resources to serve those 80s customers better, because obviously when we engage with those 80 customers and we say we need more from you, that means we will do more for them.
We will give them better service, we will give them better lead times, we will give them better visibility, and as a result, they will give us more of their share of wallet. That requires people as well.
That's that redeployment of fewer orders to process, because there's fewer smaller ones, more time for the big customers. As we continue to do this, there will be some productivity opportunities, obviously, that will be a net benefits from a margin standpoint.
Mike Discenza
Maybe, Steve, just a reminder what we've said all along, which was 80/20, the first half was a drag on the company. The second half, which we're squarely in right now, those benefits are really offsetting some of those costs.
Then we'll expect to see that drop-through on the margin really as we get into 2027. We've spent the last almost a year now, we've been doing this for a little less than a year, doing a lot of learnings.
Lucian referenced several of the tools that we've put in place. There's many tools.
Each business, as we've segmented, has different needs, and so a lot of activity going on there deploying the tools, and then looking for that to start delivering results next year, both top and bottom line, in a meaningful way.
Steve Barger
Understood. Thanks.
Operator
Next, we'll hear from the line of Tim Thein or Thein, rather, at Raymond James. I hope I said your name correctly, sir.
Please go ahead.
Tim Thein
That's good effort. A question is on kind of visibility you have for '27.
Some of your longer-cycle business or longer-cycle, larger backlog-based businesses that you called out earlier as driving a lot of the kind of order momentum, A&D and as well as automation and robotics, it's nearly 40% of revenue. Just as you kind of exit the year, I'm just curious if you could speak to where you expect to exit the year, kind of how much of that mid-single-digit growth, again, nothing's certain, but just kind of how much of that is kind of already within your control just based on what you would expect to exit the year in terms of having added in backlog.
Lucian Boldea
Tim, look, it's always a little bit difficult to link pipeline in long-cycle business to revenue in a short period of time, especially in the near term, but with that caveat, in the long run, it does all flow through and all even out. When I step back and look at the aerospace and defense business, for example, where does the pipeline sit, and again, I mentioned Q3 of '26 versus Q3 of '25, significant double-digit increase, same with automation and robotics, dramatic double-digit increase.
When I look at the revenue side of both of these verticals, whether it's Q3, whether it's Q4, again, very, very strong performance. Aerospace and defense, we've made the investments in manufacturing that have been a drag on us on cost, but I'm happy to share with you that our revenues are up, though, double digits in aerospace and defense on the bearing side.
Then as I look at Industrial Motion, it's basically a 20% year-over-year kind of trajectory, and the pipeline is growing more than that. I'm still, unfortunately or fortunately, still building past dues and backlog in spite of our best efforts.
The extra revenue, especially on the bearing side in aerospace, only came on the back of us being able to produce more because we were capacity-limited. Those investments are starting to pay off.
We have other step changes in the ability to serve that are coming in aerospace, where we've invested in more infrastructure, more material. Far, what we're getting is a bit of try harder with more people.
We've hired more people, and some of the equipment we've invested in, that's coming now and will help us. There are a number of things.
Then on the defense side, especially on the marine side, we have a number of pretty significant projects to your point on long cycle that we will have to start delivering, start working on them and have revenue recognition in 2027 from those. Those are pretty significant.
We feel very good about winning these opportunities. We're in the final stages of bidding.
We obviously have a very motivated customer who wants to move with speed, and so that will further help us on the defense side. Again, the pivot we're making, we feel very good about.
I just want everybody to recognize we're managing to a net number. It's the undercurrent of we're exiting a market, we're doing divestitures, we're doing growth at the same time.
What we said we're doing, what we said we're working on is working very well. The early indicators are very positive that we're headed on the right track, and that's why we're sitting here earlier than normal reaffirming our views on 2027 without doing a firm guide, but getting as close as we can to that.
Mike Discenza
The other thing just in our control and that we've communicated is pricing. We said we included 100 basis points of pricing in our long-term targets and expect to be able to deliver on that promise as well.
We have that in our control to help with that growth.
Tim Thein
Got it. Then, Mike, one quick one, there's an earlier question on the mix impact in the quarter.
Usually when I think of mix, I think of the distribution playing an important role in that calculation. How did just distribution fair in the quarter and what you're expecting in the fourth quarter in terms of global distribution sales?
Mike Discenza
Distribution was not a significant impact on that mix. It really was a little bit more of the as Lucian referred to, the regional impact, Europe being down, of course, some of our acquisitions, Industrial Motion heavier in Europe, mix from that.
When I think about distribution, going forward, like I said, we feel that inventory is in a good place. Our big customers that have announced their growth rates, we feel comfortable that we'll be able to match those.
We look for continued growth in those markets, and then, of course, when that grows, it does help with mix. In the quarter, it wasn't a contributor to the negative mix.
Tim Thein
Okay. All right, thank you.
Operator
Next, we'll hear from the line of Tomo Sano at J.P. Morgan.
Tomo Sano
Hi, good morning, everyone.
Lucian Boldea
Morning.
Mike Discenza
Morning, Tomo.
Tomo Sano
Thank you. It was encouraging to see a One Timken emphasized at the recent trade shows.
As you continue to implement 80/20 and One Timken, how are you positioning Timken in emerging areas like humanoid robotics? Are you bringing capabilities across the brands together to develop customized higher-margin solutions?
How does that fit with your strategic priorities?
Lucian Boldea
Yes, thank you for the question. Especially, if I start to where we sit today on the robotics side, because humanoid is more more forward-looking, but but on the humanoid side, we're already doing that.
We've we've put together a platform, Precision Drives platform. This is this constitutes our Cone Drive business, our Spinea business, and our CGI business that that we've acquired.
Those those three are kind of the tip of the spear of the One Timken. Obviously, behind them, very close behind, is our linear motion business, our automatic lubrication systems business, and then our our bearings businesses.
The tip of the spear is that platform, that Precision Drives, that really is meant to to go engage with the OEMs, because you you want to bring that credibility together to be a solution provider, and the only way you do that is you come with multiple solutions. You don't want to come with the full toolkit that maybe some of it is not relevant, you want to come with enough in your prototyping.
How it fits with the strategy both in robotics and on the humanoids is to really go to these subsystems, to where instead of selling just an actuator, and, there's plenty of revenue to be made in an in a humanoid or robot with actuators, but instead of just the actuator, you might have the gearbox, you might have the frameless motor attached to it, you might have have other subsystem, but really it's looking at that that subcomponent. It's not making the humanoid, but maybe you're looking at the wrist, maybe you're looking at an ankle, that that type of approach.
If you're thinking of a robotic arm, you might make the components in the robotic arm, but also the robot transfer unit that's comes out of our linear motion business that that is linked to that. That's that's how we we try to think about that, is really solve the unique customer problem, which is why we're more excited about industrial robotics, frankly speaking, than than humanoids.
Humanoids might be a little more mass-produced, industrial robotics, as you alluded to, is way more bespoke. There will be an in-between there, which is the industrial high-performance humanoid that is also of of great interest, or professional humanoid, that that will be interesting for us as well as an opportunity, and we're working with OEMs there in prototyping, in development already.
We have programs. I should have started with we now have a center of excellence around humanoids, we have a cross-functional team that's up and running, that's engaging with these OEMs, that's really looking at the technologies across the company and not we're not relying on one one P&L at a time to engage with customers.
Tomo Sano
Awesome. Thank you, Lucian.
Lucian Boldea
Thank you.
Mike Discenza
Thanks, Tomo.
Operator
We will hear from the line of Chris Dankert at D.A. Davidson.
Hey, good morning. Peter on for Chris today.
Lucian Boldea
Morning. Morning.
Just going back quickly to hear on 80/20. I know we've previously been given the target of, I think, 75% of initiatives being rolled out by Q3, I think.
I think by last quarter, we were at about 60%. Is it fair to say that that's been fully completed?
I just think kind of as a follow-up if there's any sort of checkpoints we should be thinking about going forward here?
Lucian Boldea
Maybe clarify. What what we said at the time, this was the percent of the revenue of the company that was covered, where we had trained everybody, brought everybody on board, and and kicked off initiatives.
We were at 75% of the revenue. We are now, I think, October 10 is was the the exact date when we significantly crossed that threshold to where now we have virtually everybody, virtually the entire revenue of the company covered in in training, and we, by the way, prioritized not only the training, but also the work stream based on where we think is the most opportunity.
We started there. We we did 80/20 with an 80/20 mindset, we started there.
Yes, it is fully underway, it is operationalized, there's a there's a operating system that goes with it, there's a review cadence that goes with it that Mike and I both personally sit in on a high level of frequency and check in with the teams across all these work streams. They all now have dashboards, KPIs, milestones, all the things that that you can imagine, and that's that is all all underway.
Everybody trained and the work stream is fully operationalized, it's all all moving forward.
Perfect. I appreciate.
I'll pass it back.
Lucian Boldea
Thank you.
Mike Discenza
Thank you.
Operator
This concludes our question-and-answer session. Mr.
Frohnapple, I'd be happy to turn the floor back to you for any additional or closing remarks that you have.
Neil Frohnapple
Thank you, operator, and thank you, everyone, for joining us today. If you have any further questions after today's call, please contact me.
Thank you, and this concludes our call.
Operator
Ladies and gentlemen, this does conclude the Timken Company Q3 2026 Earnings Release Conference Call, and we thank you all for your participation. You may now disconnect your lines.
Have a great day.