Trex Company, Inc.
Q3 FY2026 · Earnings Call TranscriptNovember 4, 2026
Operator
Ladies and gentlemen, thank you for standing by. Hello, and welcome to The Trex Company, Incorporated Third Quarter 2026 Earnings Conference Call.
All lines have been placed on mute to prevent any background noise. Thank you, and I'd like to turn the conference over to Lee Coker, Vice President, Corporate Development and Investor Relations.
Mr. Coker, please go ahead.
Lee Coker
Good morning, everyone, and thank you for joining us today to discuss our third quarter results and outlook. With us on the call are Adam Zambanini, President and Chief Executive Officer, and Prith Gandhi, Senior Vice President and Chief Financial Officer.
The company issued a press release earlier this morning containing financial results for the third quarter 2026, a copy of which is available on the company's website. This conference call is also being webcast and will be available on the Investor Relations page of the company's website for 30 days.
Before we begin, let me remind everyone that statements on this call regarding the company's expected future performance and conditions constitute forward-looking statements within the meaning of federal securities laws. These statements are subject to certain risks and uncertainties that could cause actual results to differ materially from those expressed in the forward-looking statements.
For a discussion of such risks and uncertainties, please see our most recent Form 10-K and Form 10-Q, as well as our other filings with the SEC. Additionally, non-GAAP financial measures will be referenced in this call.
A reconciliation of these measures to the comparable GAAP financial measure can be found in our earnings press release at trex.com. The company expressly disclaims any obligation to update or revise publicly any forward-looking statements, whether as a result of new information, future events or otherwise.
I will now turn the call over to Adam.
Adam Zambanini
Good morning, everyone, and thank you for joining us. Trex was founded more than 30 years ago with a simple but powerful idea: there is a better alternative to wood decking.
Since then, we have helped create and lead the composite decking category, shaped the way consumers think about outdoor living, built one of the premier brands in building products, and created a powerful combination of brand, innovation, scale, and channel reach that sets Trex apart. Today, we see an opportunity to build on that foundation and define the next chapter of Trex.
Our ambition is not simply to participate in the growth of outdoor living. It is to expand the category, make the brand accessible and aspirational for homeowners across every income level, and build a company capable of reaching $2 billion in annual revenue by 2030.
We are pursuing that ambition from a position of strength. We have an iconic brand, a leading market position, an expanded distribution network, substantial new manufacturing capacity, a growing portfolio of innovative products, and an organization aligned around a common strategy.
Those capabilities give us multiple avenues to drive growth: convert consumers from wood, take share away from tertiary brands, capture a greater share of PVC decking, which represents 20% of the wood alternative market, expand across price points and channels, grow our presence in outdoor living, and selectively extend the Trex platform through strategic opportunities. Our third quarter results show how this strategy is translating into performance.
We generated record third quarter revenue, with growth driven primarily by volume, while much of our competitors' growth in the market has been driven by price or recent acquisitions. We also successfully executed an important distribution transition, continuing ramping up production at the Arkansas manufacturing facility, and raised our full year outlook, reflecting our expectation for double-digit growth for the year.
During the quarter, we completed the initial inventory placements with our new and best-in-class distribution partners with minimal disruption. The transition remains on schedule, and the quarter-end channel inventory remained comparable with the prior year.
Approximately $30 million of our reported revenue growth came from the initial distribution load-in, with the balance reflecting underlying demand. Based on the market information available to us, we estimate that the overall decking category grew approximately 6% during the quarter.
This means our underlying growth was more than double the estimated rate of the category. We believe our performance reflects the strength of the Trex brand, continued conversion from wood, and the impact of our investments in distribution, innovation, and demand generation.
Encouragingly, growth in the quarter was broad-based across the whole product portfolio. Decking grew across premium, mid-tier, and entry-level products.
That performance reinforces the opportunity to bring more homeowners into composite decking while continuing to serve consumers across range of styles, performance needs, and budgets. We continued to grow beyond decking with railing, fasteners, and accessories, all contributing to performance and benefiting from the strong attachment rates across the Trex portfolio.
Our long-term opportunity extends beyond the deck board itself. As we convert more homeowners to Trex decking, we can provide more of the products that complete the outdoor space, including railing, fasteners, lighting, fencing, and other coordinated solutions.
That gives us an opportunity to increase our participation in each project and deepen our relationships with homeowners and contractors. We are also expanding the ways homeowners and contractors can access the portfolio.
We saw strength in both the professional and home center channels, supporting growth across multiple products rather than a single program or customer. We are seeing strong growth across national accounts, expanding Trex's reach and making our products available to more consumers and contractors across the country.
As we expand our market reach, we are also building the manufacturing capacity to support it. At our Little Rock, Arkansas facility, we began production more than six months ahead of original schedule.
During the quarter, we began training a new workforce, increasing production, and steadily improving throughput and efficiency. As we mentioned in the press release, a rare and high-impact mechanical issue affected the ramp of certain equipment and contributed to greater than expected startup costs during the quarter.
That issue has been resolved, and we remain on track to have half of the facility's decking capacity operational by year-end. Little Rock is more than an incremental source of capacity.
Its location brings production closer to the attractive Sunbelt markets, where wood continues to represent a significant portion of the decking opportunity. Over time, we expect the facility to improve the efficiency and resilience of our manufacturing and logistics network while providing flexibility to add production lines and capacity as demand grows.
This capacity will be critical to advancing the wood conversion strategy and supporting Trex's next phase of growth. We recognize that building the next generation of Trex will require continued investment and disciplined execution.
The opportunity in front of us is substantial. Our strategy is clear, and our organization is energized by what we can achieve.
We are building Trex not only to lead our category today, but to shape the future of outdoor living and create meaningful long-term value for our shareholders. With that, I will turn it over to Prith to discuss our financial results and our updated outlook.
Prith Gandhi
Thank you, Adam, and good morning, everyone. Unless otherwise noted, all comparisons are on a year-over-year basis.
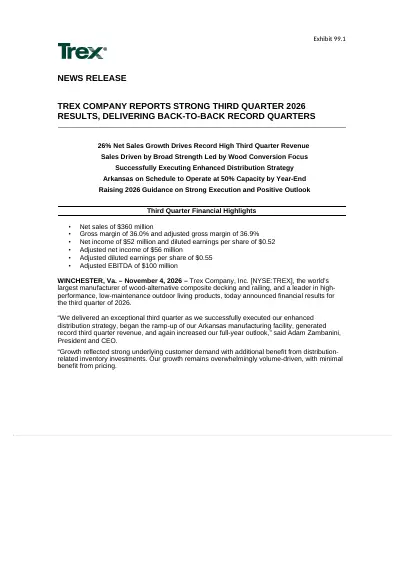
Third quarter net sales increased 26% to approximately $360 million, with growth driven primarily by volume. As Adam outlined, approximately 11 percentage points, or approximately $30 million, of our growth came from the initial distribution load-in, with the balance reflecting underlying consumer demand and continued market share growth.
Because the distribution transition temporarily affected both shipments into the channel and reported distributor sell-out, we believe the trailing 12-month view provides better context. Excluding the third quarter load-in benefit and adjusting for discounting by our former distributor, we estimate the trailing 12-month sell-in and sell-out growth were approximately 8% and 9% respectively.
Turning to profitability, gross margin was 36%. Adjusted gross margin was 36.9%, down from the levels seen in the prior year.
The decline primarily reflected labor inefficiencies, increased depreciation, higher freight costs, and rapid growth from our wood conversion strategy. Incremental inbound freight expense was over $4 million in the quarter, driven primarily by higher diesel prices, and was meaningful contributor to the year-over-year margin pressure.
Had diesel costs remained comparable to 2025 levels, adjusted gross margin for the quarter would have been 38.2%. Our freight costs include the cost of moving raw materials into our plants, transferring products across our manufacturing network, and delivering finished goods to our retail customers.
For sales through the pro channel, outbound freight is charged to our customers. We are currently in discussions about adding a temporary diesel surcharge for our home center business and are evaluating longer-term solutions to offset our exposure to fuel price volatility.
As Little Rock scales and our network becomes more balanced, we expect to improve shipping efficiency and serve key growth markets from a more favorable geographic position, thus improving both our own cost structure and the landed cost to our pro customers. Despite these pressures, adjusted gross profit dollars increased 13% versus the prior year.
GAAP SG&A expense was $56 million, representing 15.7% of net sales, in line with our expectations. SG&A increased $11 million due to an increase in personnel costs, marketing investments, and capabilities.
Excluding the impact of digital transformation and Little Rock startup costs, SG&A was $55 million. We continue to invest in capabilities and marketing programs to accelerate consumer demand and drive long-term growth, and we are already seeing the benefits through higher sales.
During the quarter, adjusted EBITDA grew 10% to approximately $100 million. Adjusted EBITDA margin was 27.7%.
Turning now to cash flow, we generated approximately $135 million of free cash flow during the quarter, giving us the ability to both pay down our revolving credit facility by $83 million while also returning $55 million to shareholders through additional share buybacks during the quarter. Through October 31st, we have repurchased $97 million of the $150 million we are targeting for the second half of 2026.
Following several years of elevated capacity investment, we expect lower capital intensity to support stronger free cash flow conversion. That improving cash generation gives us greater capacity to execute our existing capital allocation priorities.
These priorities remain unchanged: investing in the business where we see attractive returns, returning excess capital through share repurchases, and selectively pursuing acquisitions that strengthen or extend the Trex platform, while maintaining a strong balance sheet. Let me close with our updated outlook.
Based on our year-to-date performance and expectations for the fourth quarter, we are raising our full year outlook. Our wood conversion strategy is working to drive consumer demand.
We now expect full year net sales of approximately $1.296 billion to $1.306 billion, up 11% annually at the midpoint. We are also increasing our adjusted EBITDA range to $355 million to $360 million.
We now expect adjusted gross margin of 37.5% to 38% of sales, adjusted SG&A of roughly 17%, and capital expenditures of approximately $100 million for the year. For the fourth quarter, we expect net sales of approximately $175 million to $185 million.
In summary, we delivered record third quarter sales, increased adjusted EBITDA, and generated strong free cash flow through above-market growth and disciplined execution, and we are therefore raising our full year outlook while continuing to invest in long-term growth. Adam, I'll turn it back to you for a few closing comments before Q&A.
Adam Zambanini
Thank you, Prith. We see significant opportunity ahead: converting more homeowners from wood, capturing more of each outdoor living project, and leveraging our expanded distribution network.
These opportunities support our ambition to reach $2 billion in annual revenue by 2030. Our focus is on disciplined execution, translating that potential into sustained growth and long-term shareholder value.
What gives me the greatest confidence is our people. They hold themselves to high standards, they want to win, and they have the genuine desire to achieve greatness.
Trex has climbed the mountain before. Today, we're back at base camp, energized by the opportunity ahead and ready to climb even higher than ever before.
There is no group of people I would rather make that journey than with the Trex team. Operator, we're ready to take questions.
Operator
Thank you. Quick reminder before we start the Q&A: if you'd like to ask a question, please press star and the number one on your telephone keypad to raise your hand and enter the queue.
If you'd like to withdraw your question, please press star one again. We would like to kindly ask you to please limit yourself to one question and one follow-up only.
Also, we advise you to pick up your handset when asking for optimal sound quality, and if you're muted locally, please remember to unmute your device. We will take our first question from Keith Hughes from Truist.
Please go ahead.
Keith Hughes
Thank you. A couple questions on revenue.
You gave us the trailing 12-month sell-out that was 9%. Given some of the past quarters, it seems like the quarterly sell-out might have been a little bit greater than that.
Can you kind of give me your views on that? I've got one question about mix afterwards.
Prith Gandhi
Keith, it's Prith. Thanks for the question.
You're right. It is true that the sell-in sell-out numbers in the quarter were higher and, once again, once we adjust for the load-in, and we adjust for discounting and so forth, we think if they were consistent with each other, and they were in the teens.
Keith Hughes
In the teens. Okay.
On the mix of revenue, you kind of called out Transcend, and the release is being strong, one of your higher-priced goods. If you could just give within that sell-out revenue, however you do it, what is the difference between what you would see at the high end of the product offering versus Enhance and the stuff at the lower end?
Adam Zambanini
Hey, Keith. Good morning.
It's Adam. What's really encouraging about the mix is that we saw double-digit growth across all categories: good, better, best.
Very well balanced. Part of that strategy is, as we can keep converting wood, we want to keep driving consumers in, we also want to teach them how to trade up to Transcend, and we believe that there's a benefit not just with our decking business, with the fastener business, the railing business, and so on, which we saw in all categories through the quarter.
Keith Hughes
Okay. Thank you.
I'll pass it on to others.
Operator
Thank you. Thank you.
Our next question comes from the line of Collin Verron from Deutsche Bank. Please go ahead.
Collin Verron
Good morning, thank you for taking my questions. I was just hoping that you could talk about sort of the underlying composite decking growth versus maybe some contribution from things like the rollout of PVC decking, railing program, and your upgrading lighting program.
Then if you could just talk about maybe how things trended in September and October, just given the change in interest rate environment, did you see any sort of slowdown in your demand? Did things kind of hold steady?
Just any characterization of how things played out would be helpful.
Adam Zambanini
We do our own internal studies. We saw that the decking demand or decking growth for Q3 was about 6%.
Composite decking growth was about 9%. Trex grew more than double than what the category was, even when you exclude the load-in.
When it comes to PVC, it's pretty de minimis in terms of what sales are. We only introduced this year a grooved profile.
We're missing the complete line, which means we need to have grooved profiles, we need to have fascia profiles, and all that. Our plan is to extend that PVC arrangement of profiles as we move into 2027, remembering that PVC is 20% of the total market, and we have a major competitor that owns over 70% share of that market.
It's a great opportunity for Trex as we dive deeper into there, but I would say it's pretty de minimis at this point. We saw great great growth, once again, double-digit growth in the quarter for railing, and then lighting accessories.
We just launched a new lighting system this quarter, it's pretty early, but I would tell you the takeaway from that was very good in terms of the load-in on the lighting.
Prith Gandhi
Hey Collin, your question on the rate environment and has that created any change in demand. Ironically, we ran a proprietary survey through a third party where we surveyed about 2,000 homeowners across the different parts of the country and different prices of homes and so forth.
One of the things that came out of the survey is there's at least a segment of homeowners now who say, 'Well, rates have gone up so much. House prices are up so much.
I'm just going to stay put in the house I'm in, and I'm probably going to be there for a while. Now let me go look at the projects I've been deferring.'
What comes out from that work is that the outdoor living space is one of the first places they go to invest because that allows them to enjoy their existing home more. It actually provides value back when you sell the house, like a lot of listings will say we have Trex decking and so forth.
In some ways, I think that's part of we've been telling you for the last two years there's pent-up demand. I think in some cases at least, the interest rate environment is actually forcing that pent-up demand to actually become realized demand.
Collin Verron
Interesting, that's really helpful color. Then just a quick question on the fourth quarter.
Any colors if there's any initial distribution load-ins in the 4Q sales just from maybe more recent wins like Do it Best? Then just comment on how you guys are thinking about channel inventory levels maybe as you exit the year here?
Adam Zambanini
We have $30 million of load-in in Q3, and there's $5 million of load-in in Q4, and that's the end in terms of when you look at the load-in for the year. So $30 million in Q3, $5 million in Q4.
Collin Verron
Thank you, appreciate it.
Adam Zambanini
Thank you.
Operator
Thank you. Our next question comes from the line of John Lovallo from UBS.
Please go ahead.
Matt Johnson
Hey, good morning guys. You've Matt Johnson on for John.
Appreciate the time. I guess first off, if I could just clarify on that $30 million of initial distribution load-in this quarter, I think you guys also mentioned that overall channel inventory was still flat year-over-year.
I guess how should we kind of think about those factors offsetting? Presumably there's some headwind from the wind-down in Boise.
I don't know if that is an offset to the $30 million, or just how we should kind of think about the net impact there?
Adam Zambanini
When we look at the comparable year-over-year, that includes legacy distribution. When we started our transition into this year, we actually had a lower inventory position with some of our other distributors outside of our legacy distributor.
From that perspective, there was a delta there as we started that load-in at the beginning of Q3, and therefore we had to catch up throughout Q3. There was several different new distributors that we had to load in, and different and additional locations in some of the current existing distribution base.
When we looked at where the load-ins were from those locations, which there was minimal takeaway demand in Q3, the number we came up with was $30 million. The good news is, when I look at it, is to be sitting there with $30 million load-in and still have comparable inventory, and knowing that the dealers are still in a pretty good position as we exited the quarter from an inventory perspective, you saw we raised the guidance in Q4, because we feel good about where we stand moving into Q4 from the inventory position and the transition.
There was one distributor that kind of the last part of their load-in came in at the very beginning of Q4, which is the $5 million. That's kind of how I put context around that.
Matt Johnson
That's great. Appreciate all the color.
Then if I could just ask about on gross margin, I think adjusted gross margin in the quarter was down somewhere around 400 basis points from last year. You guys called out a number of headwinds with higher transportation costs, higher depreciation.
I think the implied 4Q gross margin based on the outlook is roughly flat year-over-year if you back out the warranty reserve calc from 4Q '25. I guess assuming that math is right, is there any kind of help you can give on kind of what's driving that improvement in the fourth quarter, presumably those headwinds are still in place?
Prith Gandhi
Thanks for the question. Look, yeah, based on the updated guidance, as you said, you'll end up somewhere in the 34% to 35% zone.
Then, you're right. What I do is exactly what you did, is start with a normalized base.
As you said, in Q4 last year, we took the warranty reserve of about $6 million. That's 3.7% of sales from Q4 '25.
Add that back, you'd get a Q4 '25 gross margin of about 34.4%. Directionally, look, depreciation is the biggest year-over-year headwind.
It's about 3.5%, and then we talked about some of the other things, inflation and freight, some labor inefficiencies and the like. The main driver of improvement is production.
We expect to produce double-digit growth in output across the network versus Q4 2025. That massively increases the fixed cost absorption.
Then the second piece is mix is also a tailwind in Q4 2026. It's more decking-weighted, while Q4 2025 was more railing-weighted.
Because remember we had said that at the start of the year, we would do a railing price increase. Those are some of the factors that enable us to overcome both the depreciation and the other headwinds that we talked about.
Matt Johnson
Thanks, guys.
Adam Zambanini
Thank you.
Operator
Thank you. Our next question comes from the line of Michael Rehaut from Melius Research.
Please go ahead.
Michael Rehaut
Thanks. Good morning, everyone.
Congrats on the results. Just wanted to understand a little bit with the sales upside in the quarter, obviously you highlighted the load-in, but curious kind of in two ways.
One, if that $30 million that you identified was above expectations, because I would assume you had something baked in going into the quarter, or if the upside was just more driven by a stronger underlying market growth? Secondly, with the load-in itself, $30 million this past quarter, $5 million next quarter, should we be thinking about that as a headwind, or, kind of exclude that from a base sales in '26 as we look to '27?
Adam Zambanini
I think you have to look at that as you comp the '27 numbers that load-in. We've done this historically several times.
I think that we've done a very good job identifying upfront what that load-in numbers is, and we've learned over time how to track that number. We feel very comfortable, and that's pretty much in line with where our expectations were.
When you look at the market growth, kind of going back to some of my earlier comments, the decking market grew in Q3 at about 6%, and we grew about 15% when you look at underlying demand. We more than doubled what the decking growth was for the quarter.
Now, the composite decking growth was about 9% growth. From our perspective, Trex is doing a pretty good job taking market share right now, and then the other 11% growth for the quarter was the $30 million load-in.
It's all underlying performance is really how I would look at the Q3.
Michael Rehaut
As really driving the upside then. Thanks for that, Adam.
Adam Zambanini
Yes. That's where I look at Q4, and I go, I think that as we're raising that once again, it's underlying performance.
We definitely are taking share away from wood, and we feel very comfortable with the raise in Q4 because of underlying performance. It really has nothing to do with the load-in.
Prith Gandhi
We, we see the inventory turning at distributors, and so, they continue to order. Another interesting data point just to highlight what Adam said, so, looking at, what inventory our former distributor held 9/30 versus looking at what SBP held at 9/30, which now remember SBP is SBP they used to sell to us last we used to sell to them last year, but they are now SBP plus our former distributor.
Their inventory position at September 30th was lower than our former distributor's last year on 9/30. There's a healthy market kind of trend is kind of how we read it.
Michael Rehaut
Okay. No, I appreciate that.
Then just a couple of clarification questions, if I could. You had mentioned earlier in the prepared remarks share repurchase, I think, implying some continued repurchase in October.
If you could just kind of review that, and I know that in terms of sell-in, I think you said sell-in in the most recent quarter was in the teens. I don't know if that was sell-in or sell-out, both.
If you just could clarify both of those comments?
Prith Gandhi
On the share repurchase, remember we said the second half of the year, we were planning to buy about $150 million of shares versus that goal through the end of October, we've purchased $97 million, of which we bought $55 million in Q3, in October we bought around $42 million. On the sell-in sell-out for the quarter, again, this is our best estimate, adjusting for the load-ins and all of that, we think it's in the teens for both sell-in, sell-out and pretty close to each other.
Michael Rehaut
Great. Thank you.
Adam Zambanini
Thank you.
Operator
Thank you. Our next question comes from the line of Susan Maklari from Goldman Sachs.
Please go ahead.
Susan Maklari
Thank you. Good morning, everyone.
Prith Gandhi
Good morning, Susan.
Susan Maklari
Good morning. My first question is on the branding and the marketing side of the business.
As you think about having this shift in your channel partners fairly well positioned going into 2027 and just given the macro and the recent outperformance that you've seen, can you talk about how you're positioning the business from a branding and a marketing perspective next year, and how you can perhaps leverage some of the digital and the technology investments that you've been making more recently to really make sure that you're honing in on those key points?
Adam Zambanini
Susan, that makes me feel really good considering I used to work in marketing and sales, I really appreciate that comment. When I look at it, we're going to keep putting our foot on the gas in terms of investment into the marketing program.
We've really hammered home performance engineered for your life outdoors. We believe we're the best in heat mitigation technology, we should be the best in marine, the best in fire, and the one thing is, while the story is happening on wood conversion, don't forget my comments earlier this year on innovation.
Innovation will be continuing down here, and I want game-changing innovation longer term from where Trex is. We haven't lost sight of that, and we do believe performance engineered for your life outdoors, we should be number one in each and every single category.
I will make sure, no matter whether it's a tertiary brand or a national brand in any part of this country, Trex has a number one position, and that's all investing in this iconic brand and making sure that we're hammering that home with consumers. The other thing is, we will not let a consumer on the sideline.
We do not participate in a K-shaped economy. We want everybody with every budget and every income to buy Trex, and that is what our focus is moving forward.
You're going to see once again a lot more investments with Trex in a lot of these different areas and territories, and we do believe the strategy has been working.
Susan Maklari
That's great. Thank you.
Then maybe shifting to Little Rock, sounds like that is progressing, the ramp there according to your plans. Can you just give us an update on how you're thinking about that fully coming up online next year, and what that will mean for the business?
Adam Zambanini
Starting a greenfield is not easy. We mentioned we had this mechanical issue that we worked our way through on the quarter, and so we're good in terms of where we said we're going to land: 50% capacity utilization by the end of the year, that's still unchanged.
The way I view Little Rock is, hey, through the end of Q1, there's still going to be a lot of work that goes into this thing to kind of level us up. As we move through Q2, that's where we should start to see us getting closer to where we produce in some of our other parent or sister facilities, let's say.
Then I think you'll start seeing some of the benefits of Little Rock in terms of the OEE, capacity utilization, rate yield, uptime in the back end of 2027. When you start to look at the upside of Little Rock, because it's a greenfield, it'll take us a little bit of while, but I look at this: ramping in, working on this through Q1, leveling out in Q2, and then I look at some of those benefits that we've been talking about in Little Rock to really just start hitting home in the back half of 2027.
Susan Maklari
Okay. Thank you for the color.
Good luck with the quarter.
Adam Zambanini
Thank you.
Operator
Thank you. Our next question comes from the line of Phil Ng from Jefferies.
Please go ahead.
Phil Ng
Hey guys, congrats on really strong results. I guess first a question for Prith, and maybe even you Adam, certainly you're seeing a lot of inflation whether it's diesel, freight, you talked about potentially surcharges, aluminum prices have taken off from railing as well.
How are you thinking about price as we kind of think about 2027? Is that a lever that we should think as a potential good guy to kind of help drive margins higher?
Then you talked about Little Rock, certainly there's going to be a phasing effect in the first half. When we think about '27 at large, are we back to a spot where we could get back to incremental margins on the EBITDA side in the mid-30s?
I'm just trying to get a sense how we should think about margin and operating leverage as we think about 2027.
Prith Gandhi
A lot of questions in there. Look, we always evaluate pricing as a lever, and it's in the context of inflation, in the context of competitive action and what the demand-supply balance is.
Certainly that is something that we will look at and implement when we see the opportunity. In terms of the gross margin improvement and so forth, look, we're not giving guidance on 2027 at this point, right?
If we are in a healthy demand environment as we currently are, and, as Adam said, Little Rock begins to produce and at the levels of efficiency in line with the rest of the network, all else equal, we should expect an improvement in margin next year.
Adam Zambanini
Phil, I'll add a little bit more context on it. We do have a pricing strategy in place.
There will be pricing next year. You probably will see some benefit at some time frame next year on pricing, but we're being very strategic on it.
I've been really clear that I want to build the foundation in Trex. In building the foundation is pumping volume through these factories, and you've seen that come through if you look at our performance versus everybody else.
I think we're really the only ones really driving volume through these factories. Everybody else is taking pricing.
I don't think that strategy has really worked well for Trex the last several years. When you look at us, we need to run these assets.
We've made a significant investment, and that's the idea: to get these factories rolling and then layering in pricing, which is something I've been pretty consistent with this year as we move out into 2027. We've really not communicated anything around the timing of that.
Phil Ng
Helpful. Adam, how's the transition to perhaps some of these new regional distributors?
SBP, you've done business with them for a long time, right, no change there. The education process in terms of sell-through, and how's the channel thinking about inventory as we think about 2027 with winter buys and whatnot?
Adam Zambanini
Shout-out to my team. I'm going to call it this, which is a high bar: flawless execution.
The plan and how we've identified the distributors that we were aligned with our strategy, I think what the market is missing is how much went into the preparation behind it, the research that we did amongst these people, whether they're national or regional distributors. From a regional context, we got the best ones.
When I say the best ones, they're very aligned with Trex and the strategy moving forward, and we're seeing success in several of the regional players early on. A lot of the success right now early on has definitely been through a lot of the tertiary brands.
We're seeing a good conversion right out of the gates, which, remember, I said there's a $100 million opportunity $100 million opportunity over two years away from tertiary brands moving over to Trex, and I'm kind of surprised that how immediate that impact hit as we saw some conversions even in Q3 as we move into Q4.
Phil Ng
Okay. Thank you, appreciate the color.
Adam Zambanini
Thank you.
Operator
Thank you. Our next question comes from the line of Matthew Bouley from Barclays.
Please go ahead.
Matthew Bouley
Good morning, everyone. Thank you for taking the questions.
Wanted to ask about the production benefit to margin. I think I heard you say that Q4 margin benefits from, I guess quote, "massively increased fixed cost absorption."
I think you have the load-in benefit here in Q3 and a little bit in Q4, and perhaps some share gain from tertiary competitors this year, and so I guess all of that said, when we think about production going forward, a year from now, how do you think about the level of production year-over-year and what that means for gross margin next year? Thank you.
Prith Gandhi
Again, Matt, just kind of what I said before, if we're in a healthy demand environment, we do expect production to increase again next year, and yeah, we will build some inventory here in Q4, heading into the beginning of next year, but and if that environment holds, and as you ramp up production in Little Rock, we would expect to see improvement in gross margin year-over-year.
Matthew Bouley
Thank you for that, Prith. Then, I guess secondly on the point of the share gain, your two large public competitors have been certainly putting up some fairly substantial growth as well, presumably that means that the tertiary competitors are shrinking, and correct me if I'm wrong.
How do you think about as you get into next year, what's sort of left from the tertiary competitors, and sort of your overall share positioning? Thank you.
Oh,
Adam Zambanini
I think there's still plenty of growth from the tertiary competitors, but I also think longer term when you start to think of the share gains, at some point, it can't all be pricing. We're in repair/remodeling, we're not in new construction, you can't price your way to get there forever.
You're going to get to the point where the consumer will look at the boards and say, 'I'm not going to end up paying $15, $20 a foot for a deck board.' When you look at this, and the things that Trex is really good at is driving those manufacturing efficiencies, we believe we're the low-cost manufacturer, we believe we have plenty of pipeline on continuous improvement, we have to drive down our cost structure in order to take share.
From that volume perspective, I think when you look at longer term in the Trex's opportunity there, gaining that share, leveraging that volume, lowering the cost structure is going to create greater opportunity even further for market share.
Matthew Bouley
All right. Thanks, Adam.
Good luck, guys.
Operator
Thank you. Our next question comes from the line of Anthony Pettinari from Citi.
Please go ahead.
Anthony Pettinari
Good morning. Hey, I was wondering if you could put any finer point or quantification on attachment rates in railing and fencing or fasteners in the quarter, and where you think that could go?
Adam Zambanini
We saw significant growth in railing in Q3, which has been consistent the last several years, significant double-digit growth. We also saw pretty strong growth in the fasteners as we've seen the decking sales rise.
I don't know, do we have the attachment here? Here we go.
When we look at the attachment rates, they've been increasing from mid-20s to almost around 30% as we go through the end of Q3. We've seen attachment rates rise about almost 500 basis points from the beginning of the year to the end of Q3.
Pretty good rise in attachment.
Anthony Pettinari
Got it. That's very helpful.
Then just stepping back, I think you've talked about wood-to-composite conversion kind of averaging 80 to 100 bps a year. As you kind of look back on '26 and the strong volume growth that you're having, do you think that is maybe a higher conversion year for whatever reason, or maybe too hard to tell kind of in real time?
I'm just wondering kind of perspectives on that.
Adam Zambanini
Oh, I definitely think it's a higher conversion year, and now that Trex is kind of back to basics and converting the wood, once again, 1% share away from wood is $80 million in revenue. We also see competition focusing more on that.
I think right now with these higher interest rates, more people are involved in repair/remodeling. We've definitely seen more conversion away from wood this year as a category, and I think it's definitely been higher than that 80 to 100 basis points historical average.
Anthony Pettinari
That's helpful. I'll turn it over.
Adam Zambanini
Thank you.
Operator
Our next question comes from the line of Rafe Jadrosich from Bank of America. Please go ahead.
Rafe Jadrosich
Hi, good morning. Thank you for taking my question.
Adam Zambanini
Morning.
Rafe Jadrosich
You called out on the gross margin side some one-time headwinds in '26. I was wondering if you could sort of pull it all together and then how we should think about those for '27.
The freight charges, the rare mechanical issue, I think there was some inefficiencies that you called out last quarter. How do we sort of think about as you anniversary those into next year, how much you would get back just from those?
Prith Gandhi
Hey, Rafe, it's Prith. Listen, the mechanical issue that we called out in Little Rock, we took care of that as an adjustment in the startup costs, so that shouldn't repeat next year.
In terms of freight and the inflation on that front, look, we're doing all the things we can do to mitigate, but in terms of budgetary assumptions and so forth, we're going to look at the environment we're in, and currently, with the geopolitical situation, we're still at elevated oil prices and so forth, we don't see that abating anytime soon. Remember, what we always strive to do at Trex is to have a portfolio of productivity projects and then pricing, as we talked about, to offset inflationary pressure.
That's generally how we try to manage further margin degradation year-over-year. That's kind of what I can say at this point.
Rafe Jadrosich
Then on the D&A, as we're thinking about the D&A for '27, should we think about the 4Q '26 exit rate as sort of the right level for the quarters in '27?
Prith Gandhi
Yeah. I think that's right.
Rafe Jadrosich
Okay. Great.
Thank you.
Operator
Thank you. Our next question comes from the line of Ketan Mamtora from BMO Capital Markets.
Please go ahead.
Ketan Mamtora
Thank you. Adam, first question, can you give us an update on how some of the dealer conversions are progressing and what kind of mile markers would you have us think, let's say, over the next 6, 12 months in terms of dealer conversions?
Adam Zambanini
I think the conversions have been very positive. If I just kind of pause and take a step back, my first thing that I was concerned about is interruption in service.
When I look at it, and I look at our major customers at the dealer base or at the home center, what I feel really good at is there was really no interruptions from Trex from a service level perspective. All of our major accounts and that, we were able to service throughout the quarter, and that just speaks volumes for our new distribution network.
They did a tremendous job, because to me, that's your bigger risk there. Now, to move onto the conversions, we're seeing I would say Trex has probably the largest dealers in the network who we do business with, but it's that middle to lower-tier dealer network where we can improve.
What I've liked to see, especially from a lot of the regional guys, is they've done some business with some of these tertiary brands that are out there, and they're starting to unlock those doors. Now, when I say unlock those doors, sometimes they take bundles or a couple bundles along the way.
They don't even take truckloads yet. We did start to see them start to move away or give us indications that they're moving their programs over towards Trex.
As we moved into Q4, we've seen some locations step up their purchases in terms of moving from bundles to maybe half truckloads. That makes me feel good as we move into 2027 that as we continue showing them that we're progressing, we're growing their business, then that's going to translate into truckloads as we move into 2027.
We're seeing that on the West Coast, we're seeing that in New England, and we're also seeing that in the Midwestern territories. I would say throughout the network, we're having success at those middle to lower-tier dealers, which we can do better as a company.
Ketan Mamtora
That's great color. Then just a follow-up, Adam, what is your sense of inventories at the dealer level, right?
Are you concerned at all that because of this ongoing distribution realignment that channel inventories at the dealer level are elevated at all, or is that not your sense?
Adam Zambanini
That's not my sense. We're still getting dealer orders today that are still ordering at full truckload quantities because they need inventory.
From our perspective, we're not really seeing a lot of inventory being built at that dealer level right now. Just looking at the weather, in general, it's been pretty good, pretty positive over the last several months, and so we still see pretty good takeaway right now.
Ketan Mamtora
That's very helpful. Good luck.
Operator
Thank you. Our next question comes from the line of Ryan Merkel from William Blair.
Please go ahead.
Ryan Merkel
Hey everyone, nice job this quarter. First question, Adam, can you comment any early thoughts on the winter buy and if terms will be different than in the past, or terms maybe just the same?
Adam Zambanini
I would say that we have started those discussions. We've definitely been with our distributors and had that start to be enrolled out with dealers.
I'd say they're pretty similar in nature when you look at the terms. Of course, the terms change or vary a little bit from year to year, but I don't see anything significant when I look at from a year-over-year basis.
Ryan Merkel
Got it. Okay.
Then stepping back, just a bigger picture gross margin question. Is 43%, 44% gross margin still the right long-term range?
Just talk about the big drivers. I assume volume leverage, and then Arkansas ramping are the big drivers, but anything else you'd add?
Prith Gandhi
Then yes, look, in the near term, those are the drivers for gross margin improvement. In terms of your question on what's the kind of long-term picture.
I think, again, I point to, with the current footprint and the current sort of production mix and sales mix, etc., what we communicated right in our investor materials is that about every $100 million of sales should generate about 100 basis points in gross margin improvement. I would exclude 2027 in that because we're still doing the startup of Little Rock, and we'll see really the benefits in the second half of the year.
I would say starting in 2028, that's kind of how I would think about it.
Adam Zambanini
I've also told everybody that while the margin percentages can be important, and they've been for Trex in the past, we're really focused on EBITDA dollars and return on invested capital. As you start to look at Trex, and we're trying to grow this profile, and we start to consider other ways that we want to grow the company outside of organic growth, those are also going to be major drivers in what we're paying attention to.
Prith Gandhi
Yeah.
Ryan Merkel
Got it. Thanks.
Pass it on.
Operator
Thank you. We have reached the end of the Q&A session.
I will now turn the call back over to the management for closing remarks.
Adam Zambanini
Thank you, everyone. Prith and I look forward to speaking with you at the conferences and events in the coming weeks and months.
Operator
The meeting has now concluded. Thank you all for joining, and you may now disconnect.