Transcat, Inc.
Q2 FY2027 · Earnings Call TranscriptNovember 3, 2026
Operator
Greetings and welcome to the Transcat, Inc. second quarter fiscal year 2027 financial results call.
As a reminder, this conference is being recorded. It is now my pleasure to introduce your host, John Howe, Senior Director of Financial Planning and Analysis.
John, you may begin.
John Howe
Thank you, operator, and good afternoon, everyone. We appreciate your time and your interest in Transcat.
With me here on the call today is our President and CEO, Jaime Irick, and our Chief Financial Officer, Tom Barbato. We will begin with some prepared remarks and then open the call for questions.
Our earnings release crossed the wire this afternoon after the market closed. Both the earnings release and the slides that we will reference during our prepared remarks can be found on our website, transcat.com, in the Investor Relations section.
If you would, please refer to slide 2. As you are aware, we may make forward-looking statements during the formal presentation and Q&A portion of this teleconference.
These statements apply to future events, which are subject to risks and uncertainties, as well as other factors that could cause the actual results to differ materially from where we are today. These factors are outlined in the press release, as well as in the documents filed by the company with the SEC.
You can find those on our website, where we regularly post information about the company, as well as on the SEC's website at sec.gov. We undertake no obligation to publicly update or correct any of the forward-looking statements contained in this call, whether as a result of new information, future events, or otherwise, except as required by law.
Please review our forward-looking statements in conjunction with these precautionary factors. Additionally, during today's call, we will discuss certain non-GAAP measures, which we believe will be useful in evaluating our performance.
You should not consider the presentation of this additional information in isolation or as a substitute for results prepared in accordance with GAAP. We've provided reconciliations of comparable GAAP to non-GAAP measures in the tables accompanying the earnings release.
With that, I'll turn the call over to Transcat President and CEO, Jaime Irick.
Jaime Irick
Thanks, John. Good afternoon, everyone, and thank you for joining us on today's call.
In our fiscal second quarter, the Transcat team delivered very strong results across each pillar of our core strategy: driving strong service organic growth, expanding service gross margins, executing strategic acquisitions, and growing rentals consistently. As we have said previously, by continuously improving our customer-facing business processes, applying proven lean operating principles, optimizing business mix and pricing, and utilizing technology, inclusive of AI, to improve productivity and to deliver greater value to customers, we are creating repeatable levers to expand margins and to support sustained growth.
As we move forward, our vision is for Transcat to be as well-known for operational excellence as we have historically been for growth. Our second quarter results, and doing what we said we would do, are yet another step in the right direction toward the execution of that vision.
The fiscal second quarter of 2027 marked another sequential quarter of strong financial performance, led by strength in our calibration business. We believe we are gaining share in calibration services through organic growth, disciplined M&A, and a more productive sales organization, further widening our already substantial competitive moat.
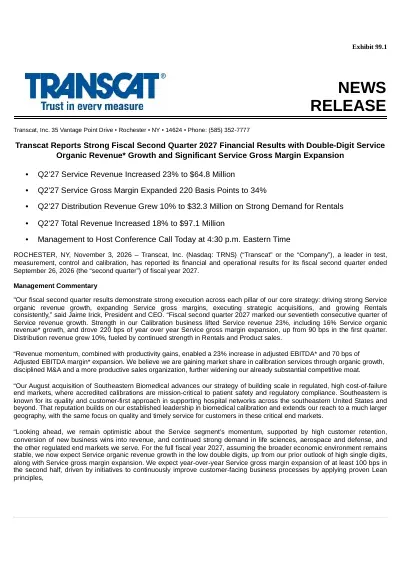
Consolidated revenue was up 18% to $97.1 million in the fiscal second quarter, driven by double-digit revenue growth in both segments. Demand in highly regulated end markets, including life sciences, aerospace and defense, and energy, remains strong, and our differentiated value proposition continues to resonate throughout Transcat's addressable end markets.
Consolidated gross profit grew 22% in the fiscal second quarter, led by 31% service gross profit growth. Adjusted EBITDA grew 23%, and adjusted EBITDA margins expanded 70 basis points to 15.4% in the quarter, driven by revenue momentum combined with productivity gains.
Now let's take a closer look at our service results. In the fiscal second quarter, service revenue increased 23%, and service organic revenue grew 16%, up from 13% in the first quarter.
The second quarter marked our 70th consecutive quarter of year-over-year growth. Service revenue growth was driven by our differentiated value proposition along with the continued successful integration and performance of our acquired companies.
We are extremely excited about our August acquisition of Southeastern Biomedical Associates. Southeastern advances our strategy of building scale in regulated, high-cost-of-failure end markets where accredited calibration is mission-critical to patient safety and regulatory compliance.
Southeastern is known for its quality and customer-first approach in supporting hospital networks across the Southeastern United States and beyond. Southeastern compliments our established leadership in biomedical calibration and extends our reach to a much larger geography, with the same focus on quality and timely service for customers in these critical end markets.
You can expect us to continue to compliment our service organic growth with strategic M&A just like Southeastern. Service gross profit increased 31% in the quarter, with service gross margins expanding 220 basis points versus prior year to 34.4%, up from 90 basis points of expansion in the first quarter.
The expansion was driven by inherent operating leverage in our service model, along with a focus on operational excellence and maturing of new customer relationships. The service segment has significant room for growth, both organically and through acquisitions.
Our pipeline positions us to pursue strategic, accretive deals that deliver meaningful synergies, and M&A will remain central to our growth strategy. Turning to distribution.
Distribution revenue grew 10% in the fiscal second quarter on strong demand from rentals and product sales. Distribution gross profit increased 6% in the quarter, and gross margins of 32% improved sequentially from 31.4% in the fiscal first quarter.
Overall, we are pleased with our performance and optimistic about the future, given the momentum building in our service segment. With that, I'll turn the call over to Tom for a more detailed look at our second quarter financial results.
Tom Barbato
Thanks, Jaime. Slide 4 of the earnings deck provides detail regarding our revenue on a consolidated basis and by segment for the second quarter of fiscal 2027.
Second quarter consolidated revenue of $97.1 million increased 18% versus the prior year, driven by compelling growth in both segments. Looking at it by segment, service revenue in the quarter grew 23% to $64.8 million, with organic revenue growth of 16%, and the balance of the growth attributable to revenue from acquisitions.
Turning to distribution, second quarter revenue grew 10% to $32.3 million, driven by strong performance in our rental channel and product sales. On slide 5, consolidated gross profit for the second quarter of $32.6 million increased 22%, driven by strength in the service segment, and consolidated gross margin expanded 110 basis points to 33.6%.
If we look at it by segment, service gross profit increased 31% in the second quarter, and service gross margins expanded 220 basis points versus the prior year to 34.4%, driven by the inherent operating leverage in our service model, along with our focus on operational excellence and maturing of new customer relationships. Distribution gross profit increased 6% in the quarter.
Gross margins of 32% improved sequentially from the first quarter, but declined year-over-year, primarily driven by lower-margin used equipment sales that enables reinvestment in our rental asset portfolio. Moving forward in fiscal 2027, 2027, we expect year-over-year distribution margin improvement driven by strength in the higher-margin rental channel.
Turning to slide 6, second quarter net income grew 90%, and diluted earnings per share increased 79% to 25 cents per share, reflecting strong profit flow-through and operating leverage. We report adjusted diluted EPS to normalize for the impact of upfront and ongoing acquisition-related costs, executive transition cost, as well as costs that are not directly tied to ongoing operations.
Second quarter adjusted EPS of 64 cents grew 46% on a year-over-year basis. A reconciliation of adjusted diluted earnings per share to diluted earnings per share can be found in the supplemental section of this presentation.
Flipping to slide 7, where we show adjusted operating income, adjusted EBITDA, and adjusted EBITDA margin, we use adjusted operating income, which is non-GAAP measure, as a measure of performance when evaluating our business segments. The company's management believes that adjusted operating income and adjusted EBITDA are important measures of operating performance because it allows management, investors, and others to evaluate and compare the performance of its core operations from period to period by excluding items that we do not believe are indicative of our core operating performance.
In addition, these metrics are also indicators of the company's ability to generate cash. Second quarter consolidated adjusted EBITDA of $14.9 million increased 23% from the same quarter in the prior year, driven by strength in the services segment, and adjusted EBITDA margin expanded 70 basis points to 15.4%.
Service adjusted operating income was $10.6 million, up 45% in the quarter, and adjusted operating margin increased 250 basis points compared to the prior year to 16.3%. Distribution adjusted operating income was $4.6 million, a decline of 9%.
A reconciliation of adjusted operating income and adjusted EBITDA to operating income and net income can be found in the supplemental section of this presentation. Moving to slide 8, operating free cash flow of $10.9 million in the first six months of fiscal 2027 grew $3.4 million, or 46%, compared to the prior-year period, driven by an increase of cash from operations and slightly lower capital expenditures, further strengthening our financial position.
First half capital expenditures of $8.1 million continue to be centered around service segment capabilities, rental pool assets, technology, and future growth projects. Turning to slide 9, at quarter end, we had total debt of $116.9 million, $33.1 million available for borrowing under the secured revolving credit facility, and a leverage ratio of 2.18x.
We believe our continued momentum with financial performance and line of sight to new large customer wins enables us to increase our full-year service organic revenue growth outlook to low double digits. With that, I'll turn it back to you, Jaime.
Jaime Irick
Thanks, Tom. In our fiscal second quarter, Transcat delivered strong results that underscored our ability to drive growth overall, to execute with operational excellence, and to energize our teammates.
We remain relentlessly focused on the execution of our proven strategy: number one, driving strong service organic revenue growth through high customer retention, realization of new business wins, and market share gains; number two, expanding service gross margins through operational excellence and our recurring revenue model; number three, continuing to pursue strategic M&A, including our recent acquisition of Southeastern Biomedical Associates as the acquirer of choice in our market; and number four, growing our higher-margin rental business. Our first half results show progress on each of those four strategic priorities.
Service organic revenue growth accelerated from 13% in the first quarter to 16% in the second, as we continue to take market share. Service gross margin expansion widened from 90 basis points in the first quarter to 220 basis points in the second, as operational excellence is taking hold in our recurring revenue model.
We added Southeastern Biomedical Associates, extending our biomedical calibration leadership to hospital networks across the Southeastern United States, and continuing to strengthen our rentals business in the high-margin space that helped to drive 10% distribution revenue growth. We remain optimistic about the service segment's momentum, supported by high customer retention, conversion of new business wins into revenue, and continued strong demand in life sciences, aerospace and defense, and the other regulated end markets we serve.
As Tom mentioned, we are raising our fiscal 2027 full-year service organic revenue growth outlook to low double digits, up from high single digits, and we continue to expect service gross margin expansion for the full year, including year-over-year expansion of at least 100 basis points in the second half. Second half margin expansion is driven by our team's focus on continuously improving customer-facing business processes, applying proven lean operating principles, optimizing business mix and pricing, and utilizing technology, including AI, to improve productivity and to deliver greater value to our customers.
While we are still in the early innings with AI, we are already seeing these initiatives begin to deliver tangible results, reinforcing our confidence in continued progress. Our large, highly fragmented market offers a path to $500 million in revenue and continued margin expansion over the next 3 to 5 years.
Consistent, strong organic growth, operational excellence, and strategic acquisitions remain the centerpiece of our strategy and continue to drive market share gains, and we expect our rentals business to grow in the low double digits over time. Before we open the line for questions, I'll close with a few thoughts.
70 consecutive quarters of service revenue growth underscores the strength of our strategy and the discipline of our execution. Our customer focus, differentiated capabilities, and recurring revenue model, supported by attractive, highly regulated end markets, give us confidence in the service segment's continued momentum, and the confidence to raise our full-year service organic revenue growth outlook to double digits.
Furthermore, this quarter showed the earnings power of our business model, as 18% revenue growth translated into 22% gross profit growth, 44% operating income growth, and 90% net income growth. Finally, I want to say thank you to our customers for their trust, our Transcat teammates for their dedication and for delivering these results, and our shareholders for their continued confidence in Transcat.
I'm energized by the opportunities ahead, and we look forward to sharing our team's progress as Transcat continues to execute and to drive profitable growth. With that, Leslie, please open up the line for questions.
Operator
Thank you. If you would like to ask a question, please press *1 on your telephone keypad now.
To leave the queue at any time, press *2. Once again, that is *1 to ask a question.
We will take our first question from Daniel Moore with CJS Securities. Please go ahead.
Your line is now open.
Daniel Moore
Thanks. Good afternoon, Jaime, Tom, John.
Thanks for all the color, and congrats on obviously tremendous quarter. Start with the growth, 16% organic service growth in the quarter.
Maybe break that down a little further in terms of pricing is usually just a couple percentage points, but price versus volume, if you had to estimate what industry growth was versus share gain, and maybe talk to some of the categories or geographies where you're growing or gaining share the fastest.
Tom Barbato
Dan, I'll start, and then Jaime could add in here. We believe that the market is performing kind of more closely aligned to historical growth averages, something in the 4% to 6% or 4% to 5% range.
We've talked historically about getting a couple points of growth from price, and I would expect that it was fairly close to that in the quarter. The rest of it would be market share gains, and we're pretty confident that we're gaining share in the market.
I think the last part of your question was what geographies or what end markets, and what we're seeing right now is pretty broad-based. It's both geographically across end markets, and we really like what we're seeing.
Jaime Irick
Dan, I'd agree. Broad-based is the headline.
As obviously Tom and I and the team spend a lot of time just analyzing where the growth is coming from. It's across geographies, it's across segments.
The biggest chunk, Dan, of that 16%, which obviously we love and the team's doing great work, is taking share. As much as the market's back to more historical growth numbers that we usually quote as 4% to 6% and we're getting some price, we're taking market share both in the regional, smaller deals that we're getting in the field in our labs, as well as we shared in the transcript, a lot more of these big customers, Dan, that will share more about as we continue to cement these wins in the positions.
Daniel Moore
Excellent. Really look forward to hearing more.
Maybe just on the margin side, great to see the 220 basis point uplift in services, obviously key focus. On distribution, it sounds like rental grew faster, which is typically higher margin.
Can you just repeat or elaborate what you mentioned in the prepared remarks in terms of what the modest headwinds were to margin or distribution gross margin in the quarter, and I think you said you expect to get back to expansion, is that Q3 or over the next few quarters? Just want to make sure I didn't miss that there.
Thank you very much.
Tom Barbato
We do expect margin expansion in the back half of the year. I think we've also said in the past that with any good rental business, you got to have an opportunity to sell off some of the underutilized assets, and we did some of that in the quarter, and that kind of weighed on distribution margins a bit.
We're confident sequentially we saw growth in margins from Q1 to Q2, and that we're confident with margin expansion in the back half of the year.
Daniel Moore
All right. It's certainly a good quarter to prune some of those.
I guess last for me, it sounds like you're really excited about SBM, just what you've learned since the acquisition and how are your relationships opening up new opportunities in that region now that we've, I think, been in there for close to six months?
Jaime Irick
Maybe Tom and I were down there a few months ago. Seems like forever ago, Tom.
In April, but maybe point on their team and culture, how they operate, and then the growth. We couldn't have brought in a group of teammates more closely aligned with our culture, Dan, which is exciting.
Just the focus on our customers, operational focus, quality commitment is incredibly high, as and you've learned about our brand. The growth for them, they're definitely benefiting from being in that trade zone.
We've already seen the green shoots that we've planted as it relates to customers that we've talked to you and others about that are large multinational companies that required a bit more investment and confidence, quite frankly, with the Transcat backstopping a company like SBM. We've seen some of that growth start as well, and we really like how that momentum is shaping up.
Tom Barbato
I think it's a classic case, Dan, too, where we're doing what we said we were going to do before the acquisition and the conversations we had with them, that they needed some capital to expand their capabilities and win more with their existing customer base, and we've done that. They're extremely appreciative of that.
Daniel Moore
All right. That's great.
I will circle back with any follow-ups, and if not, look forward to seeing you on the road in a couple weeks. Thanks very much.
Jaime Irick
Great. Thanks, Dan.
Tom Barbato
Thanks, Dan.
Operator
Thank you. We will take our next question from Max Michaelis with Lake Street Capital Markets.
Please go ahead.
Max Michaelis
Hey, Max. Hey, guys, congrats on the quarter and thanks for taking my question.
Just a few from me. First, looking at that guide for service organic growth, just 90 days ago you talked about high single digits, now double digits growth for fiscal year 2027.
Is there anything specific you can point to that gave you more confidence going forward? Was it a few of these large deals coming across the finish line, or was it just chalking it up to broad-based growth across the entire portfolio?
Tom Barbato
I think it is that broad-based growth not only in wins, but the pipeline that we're seeing, and our ability to convert that. I think we've talked in the past about things being more normalized in terms of time to closing opportunities now versus this time last year, and we're seeing that happen.
Then,
Jaime Irick
Max, the other piece, you remember us talking about how our sales team is now a lot more focused on upstream KPIs. I just think they've dialed that in a lot more: pipeline, win rates, retention.
As we do that, that gives us a bit more visibility and that much more confidence. The wins we've had in the business that we run, as that's momentum that continues in a repeatable business.
Really confident, and the team's doing great work.
Max Michaelis
Perfect. Then just last one for me.
Rental growth, I don't think you gave a specific number, but should we just expect that to be kind of in line with what you talked about, low double digits for the quarter?
Tom Barbato
Yes, that's correct, Max.
Max Michaelis
Okay. All right, guys.
Thanks for taking my questions. Take the rest of mine offline.
Tom Barbato
Thank you.
Jaime Irick
Thanks, Max.
Operator
Thank you. We will take our next question from Greg Palm with Craig-Hallum.
Please go ahead.
Jack Schroeder
Hey, this is Jack Schroeder on for Greg Palm.
Jaime Irick
Hey, Jack.
Jack Schroeder
Appreciate you guys taking the questions. Congrats on the quarter.
Wanted to just start a bit on this service gross margin uplift throughout the year. Can you talk a little bit more about what's driving that, how much of that is kind of just volume and leverage on that versus some of these operational initiatives?
Because it still kind of feels like we're early in some of that.
Jaime Irick
It's both. It's both, and thanks for the question, Jack.
As we've been saying, we just feel we're early stages on our operational excellence journey, and we think we have a long arc to drive this type of improvement. Now, specifically to your question, I'd say, as there are a litany of things that drive gross margin rate.
We did get great volume, which helps, especially in our labs. We've returned to more historical pricing power.
On the thing that we said we were going to drive with immediacy, I'd say we're operating ahead of schedule, which is how we're managing the mix of our business. Really pleased.
We've talked a lot about Mike West and the actions he and the team are driving. I'd say we've complemented that with where our sales responsibilities fall now under Roy Simmons.
That team does a great job together of making sure we're being smart about the business that we're winning in the right segments, calibration types, regions, and customers. That's ahead of schedule.
Now, the other things we've talked about in operational excellence, it's important, Jack, for you to know and the broader teams out there, it takes a longer time to really implement lean principles, that's not overnight. Technology improvements and AI take a little more time, but a lot of the immediate benefits are coming from the volume and the mix and the price.
Jack Schroeder
Perfect. Then, just kind of pivoting a little bit, we've always kind of thought like this data center build-out is kind of going to be a good opportunity for the business.
Can you talk a little bit about any opportunities you might be seeing there? Then also, you mentioned energy as a growth vertical in the prepared remarks, I believe.
Was that a part of maybe what is happening there?
Tom Barbato
It's just one part of it. We're just seeing energy in general, there's demand there, whether it's on the power generation side or the power consumption side.
We've talked in the past about data centers, and that's presented a bigger opportunity on the rental and distribution side at this point. It's certainly an opportunity on calibration services.
I would just say it hadn't had a meaningful impact at this point, but we believe that it presents an opportunity going forward and will certainly be a tailwind.
Jaime Irick
Remember, Jack, the way to think about this, obviously we want broad-based growth and market share gains. We don't want to be hinged to one specific vertical because then we're explaining things from quarter to quarter.
Energy is helping us. It's not our biggest segment, as you know.
It's one of our smaller segments, but it's definitely a tailwind now. The way you should think about energy is it's across transmission, distribution, as well as what we're seeing with EV charging stations and the like, and, of course, with AI build-out and data centers, we're getting the benefit there.
Jack Schroeder
Perfect. Appreciate it.
I'll leave it there. Thanks.
Tom Barbato
Thank you.
Jaime Irick
Thanks, Jack.
Operator
Thank you. We will take our next question from Ted Jackson with Northland Securities.
Please go ahead.
Ted Jackson
Thanks. Good evening.
Tom Barbato
Evening.
Ted Jackson
Most of my more fun questions were asked, but I have a couple maybe left. You said the line of sight for some newer, larger customers, stay tuned.
I know you said you didn't want to get into kind of verticals. Can we talk maybe with that kind of opportunity, would this be volume that's going into your labs and kind of helping you on the margin level, or are a lot of those opportunities more you taking over labs where we would see, you know what I'm saying, kind of an initial maybe pull down on margins with a longer-term lift back up as you take that in-house responsibility on?
That'd be my first question.
Tom Barbato
I would say it's a combination, Ted. I think, as we shared before, right, is, we're always focused on what's the best solution to provide the customer what they're looking for, right?
That could be kind of us doing a permanent on-site, it could be bringing equipment to our lab, and more importantly, we've got the flexibility to provide kind of a hybrid approach, right? For the stuff that makes sense for us to do at the customer site to meet specific needs they have, we'll do that, and then if there's a portion of the population that we could bring back to one of our local labs, it would provide them a more cost-effective option, it'll provide an alternative that's more attractive to us from a profitability standpoint.
It's really about meeting with the customer, developing the relationship to understand what makes most sense for both of us, and finding that common ground. I think we're good at that, and I think we get better at it every day.
Jaime Irick
This is a huge advantage we have versus some of our competitors, as Ted, because we can meet them how they want to be served. As we build out more operational excellence, it allows us to do that without taking a hit on our margins based on how we're serving them.
We've got examples, and more to come, sorry to keep you all in suspense, but we've got some examples of big customer wins where it's more of CBL-based, which is where you were going, on-site, some in our labs, and some more on-site. We'll share more of that as it comes, but it's volume that we like, and it's volume that we can manage because of the value we're delivering the customer at margins that continue to expand.
Tom Barbato
Yeah. Ted, I think you were alluding to, as we onboard these larger customers, there will be upfront costs that get incurred, right?
We've talked about that in the past, but we're always going to on the side of satisfying those customers and getting the relationship off to a good start, because the lifetime value associated with these larger opportunities is great, so.
Ted Jackson
Then, kind of the overarching conclusion with regards to these opportunities is that should give all of us some comfort that you have some decent line of sight for growth for next fiscal year, even.
Jaime Irick
Ted, this is come up. Obviously, we know the back half of this year we have tougher comps than we did the front half.
The momentum, given the guidance that we're calling and raising guidance for the full year, obviously we're confident this year, and we have a pipeline that gives us visibility and confidence that we can continue to perform as we go forward as well.
Ted Jackson
My next more fun question for you, Jaime, is
Jaime Irick
I have fun questions.
Ted Jackson
You do? I think this one you'll find fun.
Now you've got a strategy and development officer sat in his chair for a while, should be reasonably comfortable in it. Maybe a little discussion around what on the kind of the M&A and corporate dev front, what's different now than what was there before?
That would be with both you coming on board and this change.
Jaime Irick
Look, Ted, as the team has such a strong track record of M&A going back many years, but even the last 5 years, buying 14 companies, all but one of those was a proprietary process where they chose us, we chose them. We've been the acquirer of choice, we expect to continue to be the acquirer of choice, Ted, we don't want that to change.
We want to continue to look for capabilities that we can gain or geographies or consolidation opportunities, and pick up great team members like we did this year with SBM, as well as with Southeastern. I think what we're starting to feel change-wise and, some of this is now, some of this will come on the integration side, no surprise given we're adding resources and leadership, we're tightening up some of the integration process, work, and planning that we do.
That's only going to help us going forward, and we're seeing that already with these two recent deals we've done. Then going forward, we've talked about, Ted, to you and others, having a strategic game board which just gives a lot of rigor and discipline around the markets we're looking to acquire companies in, obviously our core market and having a pipeline there, and there's a lot of room to go, but also into adjacencies in the marketplace that have characteristics that we love: recurring revenue, business where it's highly regulated, sold into some of these same end markets.
I think that's one where we're starting to flesh out a lot more, and we'll continue to do that.
Ted Jackson
Okay. I'm going to leave it there.
Congrats on the quarter. Thanks for taking my questions.
Jaime Irick
Thanks, Ted.
Tom Barbato
Thank you, Ted.
Operator
Thank you. We will take our next question from Martin Yang with Oppenheimer.
Please go ahead.
Jaime Irick
Hi, Martin.
Martin Yang
Hi. Thanks for taking my question.
First on the service revenue or the incremental margins on service, it's increasingly strong in past few quarters. How much of that progression reflects a structurally better operating model you have now versus more of a recovery from customer onboarding costs?
Jaime Irick
I think on the recovery part, Tom can speak to, cuz I know we've talked about that in prior earnings calls. I think it's certainly we're getting some of that because we're past a period which we had last year where Lee and Tom called out some of that.
I would say the majority is what we're getting with the, as I mentioned earlier, Martin, the volume leverage of growing 16% organically, and then also early traction on the operational excellence-driven initiatives, especially around mix management and price.
Martin Yang
Got it. Then, on the other hand, the distribution segment seems to have worse incremental margins.
You highlighted mix as one reason this quarter. Anything else going on?
How healthy is the rental business in the past few quarters, including the fiscal second quarter?
Tom Barbato
Rentals continues to perform well, and we heard a question earlier about how should we think about that business, and low double digits is how you think about that going forward. Again, I'll repeat what I said earlier, right, is that when you have a rental business, you got to have a used business as well, right?
Because there's times when you're going to have assets that don't have the yields that we command, right, and as a result, you're going to kind of churn those out and free up some cash to reinvest in the portfolio. That's what we did a bunch of that this quarter, and it positions us well going forward.
Just part of running that business, and it'll serve us well in the future.
Martin Yang
Thanks, Tom. Just a follow-on with that, so that sales of lower margins used equipments, do you treat that as a one-time thing this quarter?
If next quarter, you see distribution overall growth, should we expect some improving incremental margins?
Tom Barbato
We said that in our prepared remarks, right, that we expect margins to expand in the second half of the year. All right.
Martin Yang
Thank you.
Tom Barbato
Yep.
Operator
Thank you. At this time, there are no further questions— All right, thanks for the questions.
Thank you. At this time, there are no further questions in the queue.
I will now turn the meeting back to John Howe.
John Howe
Thank you all for joining us for today's call. We look forward to sharing more on our story at upcoming investor events, including facility tours, institutional investor conferences, and non-deal road shows across key cities throughout the United States this fall and winter.
We will be participating in the Baird 2026 Global Industrial Conference in Chicago on November 11th, and the 2026 Stephens Annual Investment Conference in Nashville on November 18th. In December, we will join CJS Securities for investor meetings in New York on December 2nd and Boston on December 3rd, host investors for a tour of our Houston calibration laboratory on December 10th, and participate in the virtual 2026 Northland Growth Conference on December 16th.
We will also participate in CJS Securities' virtual New Ideas for the New Year investor conference on January 7th, 2027. We look forward to discussing our recent results with investors at each event.
If we were unable to answer any of your questions, please reach out to our IR firm, MZ Group, who would be more than happy to assist. Thanks again for your interest.
Operator
Thank you. This brings us to the end of today's meeting.
We appreciate your time and participation. You may now disconnect.