Power Corporation of Canada
Q3 FY2026 · Earnings Call TranscriptNovember 12, 2026
Operator
Good morning, ladies and gentlemen, and welcome to the Power Corporation third quarter 2026 earnings conference call. At this time, all lines are in a listen-only mode.
Following the presentation, we will conduct a question-and-answer session. Analysts who wish to join the question queue may press star, then one, at any point throughout the call.
If anyone has any difficulties hearing the conference, please press star, then zero, for operator assistance at any time. I would like to remind everyone that this call is being recorded on Thursday, November 12th, 2026.
I would now like to turn the conference over to Mr. Stephen Hung, Head of Investor Relations for Power Corporation.
Please go ahead, sir.
Stephen Hung
Thank you, operator. Good morning, everyone, and thank you for joining us for Power Corporation's third quarter 2026 results call.
Before we begin, a link to the audio webcast and materials for this call have been posted to our website at powercorporation.com under the Investors tab. Please turn to slide two.
I would like to draw your attention to the cautionary note regarding the use of forward-looking statements, which form part of today's remarks. Please also refer to slide three for a note on the use on non-IFRS financial measures and clarifications on adjusted net asset value.
To discuss our results today are James O'Sullivan, President and CEO of Power Corporation; and Jake Lawrence, our EVP and CFO. We will begin with opening remarks, followed by a question-and-answer session.
With that, I'll turn the call over to James.
James O'Sullivan
Okay. Thank you, Steve.
Good morning, everyone, and thank you for joining us today. Slide five summarizes how we believe Power Corporation can create shareholder value and build strong franchises.
Active ownership combined with ongoing simplification opportunities and a program of returning capital will lead to higher earnings, higher net asset value, and if positively acknowledged by the market, a reduction in Power's net asset value discount. Active ownership is how Power can support and create value at our operating companies.
The four key areas we lean into include strategy, capital allocation, key people decisions, and risk. Through our active ownership, Power can identify and support opportunities right across the group of companies.
Simplification also remains an active theme for Power Corporation. While significant progress has been achieved to date, Power still has more opportunities across the group to simplify.
These cannot be programmed or timed, but remain a focus of management. Through active ownership, ongoing simplification, and return of capital, we believe there are three key outcomes: higher earnings per share so that we can sustainably grow the dividend, Great-West and IGM continue to exceed their respective medium-term earnings per share growth objectives; higher net asset value per share as our companies grow in value; and a lower net asset value discount reflecting positive acknowledgment by the market.
Power can influence the net asset value discount by repurchasing shares, growing net asset value, and communicating the benefits of our active ownership. Turning to slide six, Q3 results reflect the continued execution of our strategy and provide further evidence of the benefits of active ownership.
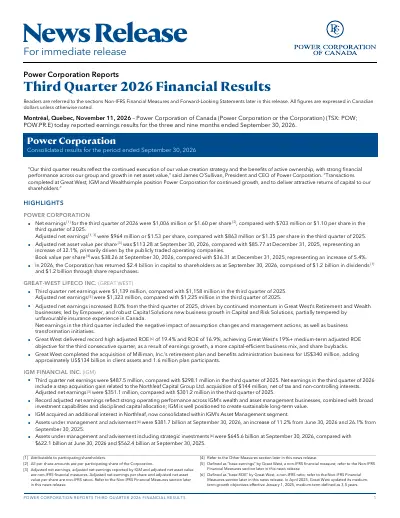
Reported adjusted EPS is $1.53. The results reflect strong business momentum from Great-West and IGM.
Great-West surpassed 19% base ROE for the third straight quarter, and IGM continued to report strong adjusted earnings and client asset growth. Recent transactions completed at Great-West, Northleaf, and Wealthsimple support the growth of our companies.
On the NAV-based investments in our portfolio, Wealthsimple posted strong AUA and client growth. Wealthsimple announced a financing round of up to $425 million on October 27th, including a primary offering of $300 million.
Net of carry, the value of the Power group of companies' interest in Wealthsimple is now $5 billion, up 13% on the quarter. Power returned $2.4 billion to shareholders through dividends and share buybacks through the first nine months of the year, and that is ahead of the $1.5 billion returned over the same period last year.
We are also seeing a similar theme across our group of companies with return of capital at Great-West, IGM, and GBL. I am particularly impressed by GBL's desire to return €1 billion to shareholders over a full year.
The quarter also reflected strong NAV growth of 57% compared to the prior year. While the NAV discount narrowed over the past quarter, we believe there is room for the gap to close further.
With that overview, I'll pass it over to Jake to walk through the financial update and business review.
Jake Lawrence
Thank you, James, and hello to everyone joining us today. Slide eight in the deck is just a reminder of all our publicly traded operating companies, which reported their quarterly results last week.
I'll begin my remarks really on slide nine. Power's adjusted net earnings were $964 million for Q3, that's up 12% year-over-year.
Our adjusted EPS of $1.53 was up 13% compared to Q3 last year. The Great-West contribution to Power's adjusted net earnings was $905 million, which is up 7% versus last year.
The results from Great-West were led by strong earnings growth at Empower as well as the capital and risk solutions business. IGM's contribution in the quarter was $227 million, and that's up 21% year-over-year, reflecting strong operating results from the wealth management business.
Turning to the NAV-based businesses, GBL and Power Sustainable reported adjusted losses in line with prior periods. The results at Sagard were impacted by lower earnings from investing activities and related to carried interest expense at Wealthsimple, reflecting the increased value that James mentioned, as well as an investment loss.
Corporate operations and other contributed a loss of $107 million, and these results included operating expenses of $61 million this quarter. The higher level of expenses quarter-over-quarter related to higher performance-based compensation given strong operating results as well as an increased share price.
Turning to slide 10, NAV per share was $113.28 at the end of Q3, and as James mentioned, our NAV per share is up an impressive 57% year-over-year. The composition of our gross asset value continues to be anchored by our earnings-based businesses.
Notably, 90% of our gross asset value is related to public companies, specifically Great-West, IGM, and GBL. When we include our cash balance, the percentage of readily observable asset value increases to 93%.
Turning to other investments, the fair value of Power's Wealthsimple position was $1.9 billion net of carried interest, and as James noted, that's up 13% from just last quarter. The increase in fair value was supported by the financing round James highlighted a moment ago.
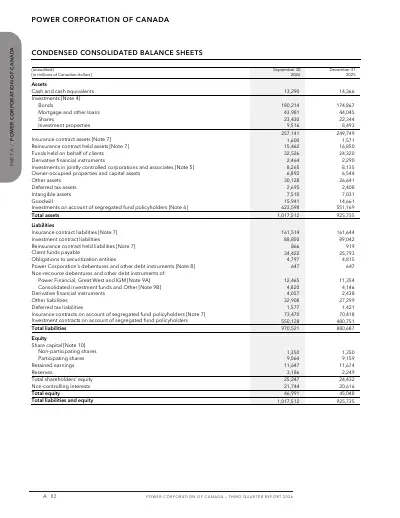
Power's cash and cash equivalents remain significant with $1.9 billion on our balance sheet as of Q3 2026, of which $1.6 billion is available after netting out some dividends to be received and some dividends to be paid. As of last night's close, NAV per share was $120.20, reflecting further appreciation in our listed holdings since quarter-end.
Next, I'll walk through the businesses starting on slide 11. Starting with Great-West, who reported base EPS of $1.48, up 11% from Q3 last year, reflecting the strong earnings I noted at Empower and Capital and Risk Solutions.
Base ROE was a record high of 19.4%, achieving the company's 19%-plus medium-term objective for the third straight quarter. Total year-to-date share repurchases were nearly $1.3 billion and continues to be supported by strong cash generation.
Great-West cash balance continued to be strong at $2.8 billion, and that's net of a planned €500 million bond repayment in Q4. This capital level continues to provide flexibility to the organization as they look to deploy into organic and inorganic strategies.
Looking closer at Empower on slide 12, year-over-year base earnings growth was strong, up 15% on a constant currency basis. In the retirement services business, client assets ended the quarter at $2.15 trillion, and base earnings grew 15% year-over-year.
In Empower Wealth, base earnings grew 28% year-over-year, and pre-tax base operating margin rose 410 basis points over the same period. Turning to IGM, I'll begin on slide 13.
IGM reported a record quarter with adjusted EPS of $1.51, up 19% year-over-year and well ahead of its 9%-plus medium-term target. The results were particularly strong in the wealth management business.
Net flows across IG Wealth and Mackenzie including Northleaf, were $3.4 billion, and AUM&A including strategic investments was $645.6 billion, up 15% year-over-year. On a year-to-date basis, IGM has returned over $1 billion in capital to shareholders through $585 million in share repurchases and $421 million in dividends paid.
As James mentioned, there were some notable transactions in the quarter. I'll highlight both we've touched on, that continue to support IGM's strategic investments.
During the quarter, IGM increased its interest in Northleaf to 61% approximately, with the results now being consolidated in the asset management segment. As we've noted, IGM also participated in the recently announced Wealthsimple fundraising, and IGM's ownership is now valued at $2.9 billion.
Moving to slide 14, on a year-over-year basis at IGM, wealth management grew 30%. Wealth management reported AUM&A of $178 billion, up 14% versus Q3 of last year.
It was also a record third quarter of new client gross inflows. Turning to asset management, investment fund net sales were $664 million, up from $407 million in Q3 of last year.
The next slide shows our strategic investments continued to see impressive client asset growth. On a year-over-year basis, Rockefeller's client assets grew 27% to $236.5 billion in U.S.
dollars, while Northleaf increased client assets by 10% to just under $38 billion. Meanwhile, China AMC assets were down 5% on a local currency basis, which reflected declines in local markets during the quarter.
Moving to slide 16, as you heard earlier, Wealthsimple's strong business momentum continues with increasing scale and another fair value increase. AUA at Wealthsimple was $170 billion, up from $155 billion from last quarter, and supported by net flows of approximately $11 billion.
Wealthsimple added another 200,000 clients in the quarter and now serves approximately 4 million Canadians. Power's collective group interest in Wealthsimple, net of carried interest, is now valued at $5 billion, up the 13% we've mentioned from last quarter.
The consolidated interest included $2.9 at IGM and the $1.9 billion value at PowerCorp. Wealthsimple recently held its latest Wealthsimple Presents event and introduced additional product-related releases for its clients and features, and we encourage you all to watch it online.
Now turning to GBL on slide 17, the business has made strong progress on its mid-term plan for portfolio simplification with disposals of more than €5 billion across listed companies and non-core assets. GBL is also expected to deploy €2.4 billion in 2026 across direct private assets through controlled or co-controlled positions.
On a year-to-date basis, GBL has returned €888 million through buybacks and dividends to shareholders. As James noted, GBL has a desire to return about €1 billion in capital to shareholders on an annual basis, and it does not need to sell assets for liquidity.
All of this is consistent with GBL's strategy of increasing direct private assets while returning capital to shareholders and achieving a double-digit total shareholder return. Turning to slide 18, our alternative asset management platforms reported total AUM of $71.4 billion at quarter-end.
The businesses remained focused on increasing scale and growing AUM. At Sagard, approximately $1.4 billion Canadian was raised during the quarter, bringing the year-to-date total close to Canadian $4 billion despite challenging market conditions.
Sagard also acquired an additional 20% economic interest in HalseyPoint, and now holds 60% in this CLO manager. Turning to Power Sustainable, the platform announced during Canada's Investment Summit held in September that it plans to invest and mobilize more than $10 billion in Canadian projects and companies over the next 5 years.
Fundraising continues to advance in its energy infrastructure, and infrastructure credit funds are progressing towards second fund closings in the near term. During the quarter, Power Sustainable completed three new financings through infrastructure credit, while energy infrastructure executed capital recycling with a wind project sale, and is advancing a pipeline of renewable energy and storage opportunities across North America.
Sagard and Power Sustainable remain focused on increasing scale and building capabilities to deliver sustainable FRE over the medium to long term. Now I'll turn the call back to James for some thoughts on value creation as well as some closing comments.
James O'Sullivan
Okay. Thanks, Jake.
Power Corporation remains focused on building its business momentum and creating value. Let's go to slide 20.
It shows the aggregate capital returned to participating shareholders since 2020: just over $13 billion in dividends and share repurchases since we began the program. On a year-to-date basis, our return of capital in 2026 is ahead of last year.
Returning capital to shareholders will remain a key priority, and the amount of buybacks will be influenced by the NAV discount levels. Moving to slide 21, it shows the strong NAV growth Power Corporation has delivered since 2020 with a 19% compound annual growth rate.
Power will continue to focus on its active ownership and increasing its communication and engagement with the investment community. Next, slide 22 tracks the discount to NAV since 2015, and the level has narrowed from last quarter to roughly 20% today.
However, we believe there is more room to narrow, and Power will remain focused on growing NAV, increasing our dividend, simplifying the company, and growing sustainable earnings from durable franchises. Moving to slide 23, Power's total shareholder returns have materially outperformed both the S&P/TSX Financials Index and the broader S&P/TSX Composite over the measured periods, including the 1, 3, 5, 10, and 30-year periods.
We believe these results reflect the successful execution of our value creation strategy, and Power will build on that strong foundation. Turning to the next slide and looking ahead, Power is well positioned to generate further attractive returns for shareholders.
The three pillars remain firmly in place. First, Great-West and IGM continue to demonstrate strong business momentum and are exceeding their respective adjusted EPS growth targets that should generate low to mid-teen returns inclusive of the dividend yield.
Second, our NAV-based businesses also offer long-term value creation. Q3 reflected another increase in Wealthsimple's valuation, and the business continues to grow assets, add retail clients, and build scale through increased product offerings.
Power's alternative investment platforms continue to scale the respective platforms and are focused on building more depth across the respective strategies at Power at Sagard and Power Sustainable. Third, our balance sheet is strong with $1.6 billion of available cash that supports the continued return of capital through dividends and buybacks across the Power group of companies, including Great-West and IGM, as well as GBL.
We are seeing increasing shareholder distributions, including GBL's €1 billion target. This quarter confirms ongoing progress for Power and its group of companies in building long-term, durable franchises.
Power is well positioned to continue growing from here. Thank you, everyone.
Operator, we are ready to take questions.
Operator
We will now begin the question-and-answer session. To join the question queue, you may press star, then one, on your telephone keypad.
You will hear a tone acknowledging your request. If you are using a speakerphone, please pick up your handset before pressing any keys.
To withdraw your question, please press star, then two. We will pause for a moment as callers join the queue.
The first question today comes from Scott Fletcher with CIBC. Please go ahead.
Scott Fletcher
Good morning. Sounds like there's a shift in discussion on active ownership and that being a primary angle of what PowerCorp is offering to the group.
On the strategy front, one of the pillars you mentioned, maybe give us an example or two of how the active ownership model is working from a strategy standpoint?
James O'Sullivan
Sure. I'm happy to.
Thank you. I think it has several components to it.
One is strong governance, and that, I suppose, is something that is easy to take for granted. I can tell you that in the Great-West board meetings, the IGM board meetings, it's a great group of directors, and it includes a subset, I suppose, of directors who have up to 40 years or longer experience with these group companies.
My point is there's a great deal of knowledge in the room, and there's a very real opportunity for the board, including the PowerCorp directors and the family, to add value and give great guidance and counsel to the CEOs of that company. The second aspect of active ownership that I'd talk about, and I spoke about this recently at a conference, is the distribution of opportunities across the group.
Now I was CEO of IGM Financial for 6 years, and so I can say this, I think, without taking anything away from IGM Financial, as I was in the chair at the time. The question I pose rhetorically is, would IGM Financial own Wealthsimple but for PowerCorp?
Would it own Rockefeller, China AMC, Northleaf? PowerCorp, through its active ownership, has generated a remarkable set of opportunities for IGM Financial, and IGM Financial's management embraced those and is running those investments extremely well as we speak.
I could go on and give examples at Great-West Life as well, but I think active ownership includes the distribution of great opportunities right across this group. The third aspect of active ownership that I'd bring to your attention is just kind of things we focus on day in and day out.
The operating companies, Great-West and IGM, for example, they have tremendous degrees of freedom and leeway, as they should. They've got their own boards, they're public companies, they've got great management teams.
From time to time, there's areas where we at PowerCorp lean in, and a great example of that right now is artificial intelligence. I've spoken in the past about how determined we are to win at AI, just as we were very determined 10 years ago to win at fintech and the digitalization of financial services generally.
Again, I point to IGM Financial, and look at the remarkable list of partners that they have established to strengthen their business, embracing the fintech ecosystem, whether it's Conquest Financial, Nesto, ClearEstate, Interval, the list goes on and on. AI is a really good, current example of how PowerCorp is leaning in with active ownership to help our operating companies for the benefit of all shareholders, so that we win, for instance, in something like AI over the next several years.
Those, Scott, would be a few examples of what we mean by active ownership. As I shared with our board yesterday, I think it's very important that every holding company be able to articulate a raison d'être, a reason for being, and ours is to engage in active ownership across a portfolio of financial services companies globally.
Scott Fletcher
Thank you. That's great color.
I'll pass the line.
Operator
The next question comes from Tom MacKinnon with BMO. Please go ahead.
Tom MacKinnon
Thanks. Good morning.
Just wondering why you participate in the Great-West buyback, but not participating in the IGM buyback? Any reasons in particular for that, and then a follow-up.
Thanks.
James O'Sullivan
The decision we've made, of course, Tom, is not necessarily a permanent decision, but I'll speak to our thinking today. I'd like to own more of IGM.
I just think it's an outstanding company. It's an outstanding group of asset management and wealth management businesses.
We own, I think, meaningfully less of IGM Financial than we do of Great-West Life. I'm inclined to own more of it because I just hold the business in such high regard.
That's not necessarily a permanent position, and if, of course, IGM came to us with a capital plan and said, "Consider this," we would consider that. For now, I'm just very happy to own a bit more of that company, and I know Jake feels the same way.
Tom MacKinnon
Yeah. Then the follow-up is with respect to Wealthsimple owned still in two places.
Is there any thinking that it needs to be only in one spot? Thoughts there?
James O'Sullivan
Thank you, Tom. It's a good question.
I would describe it as a potential simplification initiative. I'd also have to say that a whole bunch of stars have to align.
There has to be a willing buyer, a willing seller, sensible financing, and shareholder-friendly impacts. It's not something that we can program, but it's an opportunity certainly that we're aware of and one that we think about, and it's one that both the analyst community and institutional shareholders do raise with us regularly.
Tom MacKinnon
In willing buyer and willing seller, that would just be if it all went to IGM, that would be the willing buyer and you would be the willing seller. I'm not sure what you meant by or vice versa.
Were you re-answering it in that context?
James O'Sullivan
Yes. I suppose there's two potential buyers and there's two potential sellers.
Tom MacKinnon
Yeah.
Jake Lawrence
Tom, it's Jake. Just to add on, whether it's in two spots or one spot, I think how the group engages with the company wouldn't change substantially.
I think as it currently sits in two places, and if it sits in two places long term, short term, medium term, it's not going to change how we engage with the company, how we support it on its strategic initiatives, how it continues to grow well. I think from our perspective, it's a line item in two companies, but it doesn't change how we engage across the group, and it hasn't hurt in value creation to date, and we don't expect it's going to hurt in value creation moving forward for the company.
Tom MacKinnon
Appreciate the color. Thanks, Jake.
Operator
The next question comes from Graham Ryding with TD Securities. Please go ahead.
Graham Ryding
Good morning. Similar theme, what other simplification opportunities do you see potentially within the business beyond Wealthsimple?
James O'Sullivan
As I said on the last call, I'd start with businesses that are owned in more than one place. Obviously, that would include Wealthsimple.
It also includes Great-West Life. Great-West Life is owned by PowerCorp, and IGM has a stake.
It includes IGM. IGM is owned by PowerCorp and by Great-West.
I suppose there's another opportunity. Then my mind goes to kind of similar businesses that we have more than one of.
Clearly, we have more than one alternatives business in the group. I think it's fair to say that we have more than one traditional asset management business or capability within the group.
I think there's lots to think about. Look, I don't want to put too fine a point on it.
Our message really is that simplification has been a powerful force to date in reducing the historical discount at which PowerCorp trades, and I think the merger of PowerCorp and Power Financial was probably the biggest and best step in that direction. We consolidated the position of China AMC in IGM, as everyone knows.
There's potentially more to do. When Jake and I speak to shareholders, we talk about active ownership, but the shareholders say, "Okay, but let's talk a little bit about simplification as well."
Our message is that ongoing opportunities to simplify the group are opportunities that we will keep a file on our desk and see what we can do along the way here. It has been a powerful force, and we believe continues to have the potential to narrow our trading discount further.
Jake Lawrence
James, you okay if I add a thought on to that as well? Graham, thanks for the question.
I think often, and it's reasonable given the past 5, 6 years at PowerCorp and the reorganization with Power Financial, simplification is equated to transactions. I think there's another element to it.
Transactions, as James noted earlier, sometimes need several stars to align. I think simplification can also occur through our disclosure, through how we present the company, how we engage with the investment community and discuss how Power is taking an active ownership role and how we're looking to create value at the companies.
I think over the past couple of years, we've attempted to enhance disclosure, present the company in a different light, be proactive and engaging with the investment community. I think that helps the company appear hopefully simpler to the investment community at the same time, while it may not actually be a transaction occurring.
Graham Ryding
Great. Understood.
My other question would just be your proprietary investments, you flag that you target a 10% return on that. Any color on what you've been generating in the last sort of period of time, last 3, last 5 years?
Have you been generating a 10%-plus return on the investments behind your alt platform?
Jake Lawrence
I think we've got a level in the target that we disclose and maintaining it because it has been in excess of it. I think as I just noted, one of the areas we'll be looking to enhance disclosure is around what the returns have been on those investments, but they've definitely been in excess of 10% over the past 1, 3, and 5 years.
Graham Ryding
That's it for me. Thank you.
Jake Lawrence
Thanks, Graham.
Operator
The next question comes from Doug Young with Desjardins Capital Markets. Please go ahead.
Doug Young
Hi, good morning. Just back to the capital plans.
Great-West has announced its intention to buy back another $1.6 billion of stock next year. Just wanted to see or confirm, is it your intention still to proportionally participate in that buyback?
Jake Lawrence
Thanks for the question, Doug. We've participated throughout 2026, and you're correct, they are filing.
We've got a program right now in place that will expire in due course, and we would be required to file again to do that. Based off our past behavior, our intention has not changed.
Doug Young
Okay. Then, James, you talked about just discount to NAV going lower and how you think it should be lower and the plans to kind of lower that.
Then how discount to NAV does factor into buybacks. Maybe you can just elaborate in how you think about that discount to NAV.
Where do you think fair value would be, where would you potentially slow down buybacks if the discount to NAV got to a certain level? Just trying to get a little bit behind that thought.
James O'Sullivan
Yeah. I do think the discount to NAV should reflect your assessment of the quality of our active ownership.
I think it should reflect ongoing progress in simplifying the group. I think it should reflect our commitment to returning capital.
I suppose those are the three big things that I hope the discount would ultimately reflect. It's very difficult for me to say more, but I suppose I would say this.
If the discount to NAV was 10%, I'd probably be speaking about it a bit less. I really do think that north of 10, I feel obliged to really lean in on these things because shareholders choose to sell, some shareholders need to sell, and we want our shareholders to be able to sell at the best available price.
To the extent we can influence that best available price, it's incumbent on us to do what we can.
Doug Young
Then just lastly, and I don't know how to think about this, but Wealthsimple, the carried interest drag comes through, and I get how the mechanics work. I would assume that you're going to get more re-ratings on Wealthsimple, the NAV benefits, but the earnings get hit, the noise is there.
I'm just trying to kind of just think about, is there any way to smooth this so that it's not an ongoing kind of noise or drag on earnings? Just wondering what you think about that.
Jake Lawrence
I think, Doug, unfortunately, the way the carried interest is accounted for, it's an expensed item and we're not going to find a way to adjust that differently. I think looking through and us providing the numbers is probably the right way to think about it.
At some point, we've obviously took this quarter Wealthsimple share of losses, at some point they'll turn to a share of earnings and that will come through at the same time and partially offset it. At this time, I think the best we can do is the disclosure of the carried interest, the disclosure of the value bump, and people can think about how they want to attribute that in our share price at the end of the day.
Doug Young
Fair point. Okay.
Thanks for the color.
Operator
The next question comes from Jaeme Gloyn with National Bank Financial. Please go ahead.
Jaeme Gloyn
Thanks. Just wanted to dig into the asset management business a little bit.
Maybe first with the higher-level strategic comment you talked about simplification. Maybe sort of walk us through some of the areas where you're seeing potentially some duplication and maybe just sort of give us some more hints on what could be done in the alternative platform.
James O'Sullivan
Thanks for the question, Jaeme. I'm out of hints, unfortunately.
These are quintessentially people businesses with strong leaders, and were anything ever to happen, it's imperative that it happens organically and that it happens next level down if you understand me. These are just parties that would want to come together.
This is not something that would ever be or should ever be forced. I'm really pleased with kind of where these three businesses are.
I look at Sagard, and I say to you that Sagard has turned one corner, and they have their sights fixed on the next corner. The first corner was scaling assets, and they've made remarkable progress in scaling assets over the past couple of years.
The second corner now is sustainable FRE profitability and growing margin, and I can tell you that management is very focused on that. Just given the quality of the team, I expect they'll succeed and I would expect progress on that front in 2027.
If I turn then to kind of Power Sustainable, I'd say to you, look, sustainability has not been everyone's cup of tea recently, but I promise you, it will be everyone's cup of tea tomorrow or the day after. The world around us dictates that, in my opinion.
I think they've chosen a space that is medium and long-term compelling, absolutely compelling. How can it not be?
I can tell you they're making progress, they're building momentum, and I think we'll have more to report on Power Sustainable as we move through 2027. As for Northleaf, I think Northleaf is just a remarkable Canadian success story.
They have been, for some time, very, very well embraced by the pension fund community in Canada. They have very successfully globalized their business over the past 6 years of IGM's ownership, and they've got a very clear plan to kind of further scale their business and transition it for the next chapter over the next 5 years with our full support.
We've got three platforms there that we're very proud of, but yeah, we are mindful that there's more than one alts business, and if any two of them came knocking, that's obviously a call we'd take and we'd be happy to help with.
Jaeme Gloyn
You touched on the second part, which was the positive FRE in Sagard. This is the second quarter in a row.
Very small, but and maybe you don't want to call it a success at this point, but it's positive to see. You mentioned about the trajectory into next year.
Could you give us maybe a little bit more in terms of where you see that trending? Is it an opportunity to accelerate through organic opportunities, or does it really need to be coming from inorganic to drive that significantly higher?
James O'Sullivan
I think it'll be organic and inorganic. As I said, they've turned one corner, which was successfully scaling assets to their current level, but they're not done.
They have a crystal clear goal of US$100 billion in assets over the next several years, and I fully expect them to accomplish that. In terms of FRE, you're right, they've now got a couple or a few quarters of positive FRE, which is very positive.
The opportunity ahead now is to sustain that and grow the margin, and I believe they're focused on it.
Jake Lawrence
Thanks, James. Jaeme, I'd just add in, there will be volatility in that line, right?
When you think about the contributing factors to it, fundraising, it's a challenging market. The ability to monetize and deploy capital is continuing to be challenging with rate volatility.
We've been positive for two quarters. I wouldn't forecast that being the run rate moving forward positive in every single quarter.
It'll move around, but directionally, they're going to continue to grow the fee-related earnings over time, and as they scale and become more efficient in their business, we expect more of that to flow down to the bottom line.
Jaeme Gloyn
Okay. Thank you.
Operator
The next question comes from Tom MacKinnon with BMO. Please go ahead.
Tom MacKinnon
Thanks for my question here. You mentioned that the investing activities at Sagard were hurt as a result of the Wealthsimple re-rate.
I look at the asset management activities at Sagard and there was a positive 33 in net carry there. Presumably, that was benefited to some extent from the Wealthsimple re-rate.
Am I correct in that? Can you quantify that at all?
Thanks.
Jake Lawrence
It was the majority of that number, Tom, but there's also carried interest benefits flowing through other investments in the portfolio. Wealthsimple was the majority of the 33 you're highlighting.
Tom MacKinnon
Okay. How should we be thinking about that net carry number going forward?
It jumps around quite a bit.
Jake Lawrence
Depends on the value of the investments. Yeah.
Tough for to forecast on both sides, Tom, for us and for you. There you go.
Tom MacKinnon
Yeah. Okay.
Thanks.
Jake Lawrence
Thanks.
Operator
As a reminder, if you would like to ask a question, please press star, then one, to join the question queue. The next question comes from Bart Dziarski with RBC Capital Markets.
Please go ahead.
Bart Dziarski
Great, thanks. Good morning, everyone.
Wanted to ask around GBL. James, you mentioned in your prepared remarks you're pleased to see the billion-dollar euro plan.
Could you just remind us what inning they're in on their value creation plan, and should we think about that €1 billion as sort of the near term, and then it scales over time, or is there room for that €1 billion to grow over the next couple years? Thanks.
James O'Sullivan
The €1 billion is a 12-month target, and that will be both buybacks and the dividend. It's difficult to kind of look beyond that, other than to say that the company has not new management, but I'd say relatively new management, who I think have expressed a very, very clear commitment to total shareholder return.
I can't give exact numbers sort of moving forward, but TSR is something that I know that management team and the board think about very, very deeply. I am impressed.
Whenever I see €1 billion return of capital against a market cap of €9.5 billion, I think, well, there's a company that's very committed to returning capital to its shareholders. I can't really look beyond that.
I can only tell you that the management team and the board and the controlling shareholders are very committed to positive outcomes for shareholders.
Bart Dziarski
Got it. Thanks, James.
Then on the buyback, you've got $1.2 billion year-to-date, you're on pace for a record. There's available cash of $1.6.
Maybe a two-parter. If you just help us frame up how you view excess cash today, and then should we think about this year's pace of buybacks as kind of a run rate '27, '28, or maybe a dial down?
Thanks.
Jake Lawrence
It's Jake here. Thanks for the question.
We've had a couple things going on this year. Obviously, we've had our regular buyback activity, which we definitely want to do to one, offset option exercise and the dilution created from that, but also to reduce our share count.
That's kind of been the core program you've seen in recent years, which has moved around from a couple hundred million up to $400 million. I'd say what's really accelerated this year, and it's related to a couple of the earlier questions, was PowerCorp elected to participate on a pro-rata basis in the Great-West buyback.
That's returned to us over $1 billion this year, and for us, the way we look at that, as someone in the investment community said to me once, it's just math. Bart, I think in some of your earlier research, you highlighted wisely that a Power share essentially has 0.98 of a Great-West share.
As we participate in that buyback program at Great-West this year, we've been turning around and doing a larger proportion of Power buybacks to the point around in the discussion around discount to NAV. When we buy back that Power share with the proceeds from the Great-West one, we're canceling the exposure to Great-West, but we're obtaining that additional exposure to IGM, GBL, Wealthsimple, Sagard, Power Sustainable, and the cash balance.
I think it's going to depend a bit on what we do in terms of buybacks with Great-West and maybe other companies, but at this stage, I think if you run a model moving into 2026 or sorry, from '26 to '27, I'd start with the base plan of what we've done in recent years, and then take guidance from what we discuss around the Great-West program.
Bart Dziarski
Got it. That's very helpful.
Thanks, Jake.
Jake Lawrence
My pleasure.
Operator
There are no further questions. I would like to turn the conference back over to Mr.
Stephen Hung for any closing remarks.
Stephen Hung
Thank you everyone for joining us today. Following the call, a telephone replay will be available later this morning, and we look forward to our next update on Q4 results.
This concludes the call. Have a great day.
Operator
Ladies and gentlemen, this concludes your conference call for today. Thank you for participating, and you may now disconnect your line.