Propel Holdings, Inc.
Q3 FY2026 · Earnings Call TranscriptNovember 4, 2026
Operator
Good morning, everyone. Welcome to Propel Holdings third quarter 2026 financial results conference call.
As a reminder, this conference call is being recorded on November 4th, 2026. At this time, all participants are in listen-only mode.
Following the presentation, we will conduct a question-and-answer session. Instructions will be provided at that time for research analysts to queue up for questions.
I will now turn the call over to Devon Ghelani, Propel's Vice President, Capital Markets and Investor Relations. Please go ahead, sir.
Devon Ghelani
Thank you, Operator. Good morning, everyone, and thank you for joining us today.
Propel's third quarter 2026 financial results were released yesterday after market close. The press release, financial statements, and MD&A are available on SEDAR+ as well as on the company's website, propelholdings.com.
Before we begin, I would like to remind all participants that our statements and comments today may include forward-looking statements within the meaning of applicable securities laws. The risks and considerations regarding forward-looking statements can be found in our Q3 2026 MD&A and Annual Information Form for the year ended December 31st, 2025, both of which are available on SEDAR+.
Additionally, during the call, we may refer to non-IFRS measures. Participants are advised to review the section entitled Non-IFRS Financial Measures and Industry Metrics in the company's Q3 2026 MD&A for definitions of our non-IFRS measures and a reconciliation of these measures to the most comparable IFRS measures.
Lastly, all dollar amounts referenced during the call are in US dollars unless otherwise noted. I am joined on the call today by Clive Kinross, Founder and Chief Executive Officer, and Sheldon Saidakovsky, Founder and Chief Financial Officer.
Clive will provide an overview of our Q3 results and observations on our consumer segment and overall economic environment before Sheldon covers our financials in more detail. Before we open the call up to questions, Clive will provide an update on Propel's growth strategy and outlook for the remainder of 2026.
With that, I'll pass the call over to Clive.
Clive Kinross
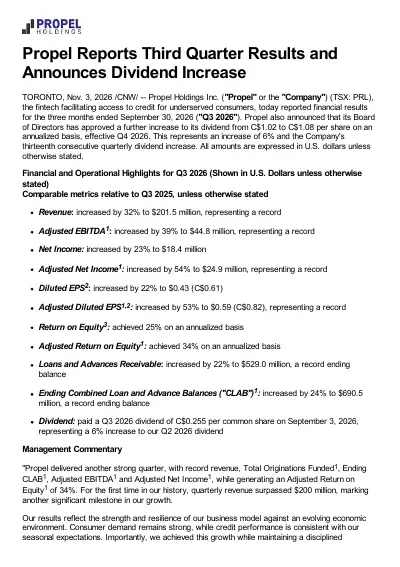
Thank you, Devon, and welcome, everyone, to our third quarter conference call. We delivered another record quarter, achieving record revenue, originations, ending CLAB, adjusted EBITDA, and adjusted net income.
Revenue increased 32% year-over-year to a record $201.5 million, surpassing $200 million in quarterly revenue for the first time in our history. This was supported by record total originations funded of $260.7 million, an increase of 27%, and record ending CLAB of $690.5 million, up 24% year-over-year.
New customer originations, including Lending-as-a-Service, increased 55% year-over-year. Importantly, we achieved this growth while maintaining disciplined credit performance.
Net charge-offs remained at approximately 12% of average CLAB, consistent with the prior quarter and our seasonal expectations. This reflects the strength of our proprietary AI-powered underwriting platform and the continued resilience of the consumers we serve.
Adjusted net income increased 54% to a record $24.9 million, outpacing revenue growth and contributing to an annualized adjusted return on equity of 34%, demonstrating our ability to generate attractive returns on equity as we scale. Our growth is also becoming increasingly diversified.
Lending-as-a-Service revenue increased 170% to a record $13.5 million, while Propel UK revenue increased 69% to a record $22 million, and Propel Bank continues to contribute to this growth through its US servicing capabilities. Together, these results demonstrate the breadth of our platform and the strength of our execution.
I'm incredibly proud of what we've accomplished. Turning to our consumers and the broader economy, as we've discussed on previous calls, the K-shaped economy continues to shape consumer behavior and the credit market.
Lower-income consumers continue to face an evolving economic environment, but they have also demonstrated considerable resilience. While inflation has moderated from its peaks, the cumulative impact of higher housing, energy, and other living costs continue to weigh on household budgets.
The critical counterbalance, particularly in the United States, is employment and wage growth. The US unemployment rate was 4.2% in September, remaining relatively low by historical standards.
The employment picture is particularly encouraging when we look at the sectors relevant to the consumers we serve, including healthcare, construction, and hospitality. The broader economy has also demonstrated resilience, with US GDP growing at an annualized rate of 3.4% in the third quarter, supported by continued strong consumer spending.
Importantly, wage growth continues to help offset inflationary pressures. According to Bank of America, after-tax wage growth amongst low-income households was 4.5% year-over-year, outpacing headline inflation of 3.7%.
Consumer spending has also remained encouraging, with Bank of America reporting that credit and debit card spending per household increased 6.2% year-over-year in September. In this environment, as we've discussed previously, traditional financial institutions continue to concentrate much of their lending at the prime and super-prime end of the credit spectrum.
This combination of resilient consumers, sustained credit demand, and limited access to mainstream lending creates opportunity for our business. Our third quarter record originations demonstrate that we can continue expanding access to credit while maintaining disciplined underwriting with our bank partners and credit performance in line with our expectations.
Turning to the United Kingdom, September inflation was 3.5%, while the unemployment rate declined to 4.7%. Against this backdrop, QuidMarket delivered its strongest quarter of year-over-year revenue growth since our acquisition in 2024, reflecting strong demand and our expanded customer acquisition capabilities.
In Canada, which represents approximately 2% of our revenue, the labor market remains softer than in the United States, with more sustained pressure on low-income households amid ongoing trade-related uncertainty. Even in this environment, we achieved record revenues with stable credit performance.
Overall, we're exceptionally proud of the third quarter performance and are continuing to realize benefits from the investments we've been making over the past several quarters. Reflecting this performance and our strong financial position, our board approved another increase to our quarterly dividend to 27 cents per share Canadian, or $1.08 on an annualized basis.
This represents a 6% increase and marks our 13th consecutive quarterly increase. I will speak more about the outlook for the rest of 2026 and our priorities heading into 2027 later in the call, but first, I will pass the call over to Sheldon.
Sheldon Saidakovsky
Thank you, Clive, and good morning, everyone. We are pleased to deliver another quarter of record results.
During Q3, we and our bank partners experienced strong demand across our operating brands, achieving record originations from both new customers and existing customers. This resulted in record total originations funded of $260.7 million, an increase of 27% compared to Q3 of last year.
New customer originations were particularly strong, increasing by 37% year-over-year, or 55% including our Lending-as-a-Service program. New customers represented 47% of total originations funded in Q3 compared to 44% last year, marking the highest proportion since Q4 of 2024.
This reflects the continued expansion of our geographic footprint, product offerings, marketing partnerships, and customer acquisition channels, together with strong consumer demand. The record quarterly originations drove ending CLAB to a record $690.5 million, an increase of 24% year-over-year, supported by broad-based growth across our operating brands and programs, further diversifying our revenue base across products, geographies, and business models.
The combination of higher average CLAB and an increase in our annualized revenue yield drove record quarterly revenue of $201.5 million, representing growth of 32% over Q3 of last year. Our annualized revenue yield increased to 121% in Q3 from 113% in Q3 of last year.
The increase was primarily driven by significant growth across our higher-yielding programs, including the MoneyKey bank service program and QuidMarket in the UK, Lending-as-a-Service, as well as a higher proportion of originations from new customers. The MoneyKey bank service program was a particularly significant contributor, with ending CLAB increasing by 87% year-over-year to $141.6 million, supported by the migration from legacy MoneyKey products, geographic expansion, and additional marketing channels and partnerships.
New customer originations were a key driver of this growth, representing approximately 60% of the program's total originations funded during the quarter. Across the entire business, the higher proportion of originations from new customers in Q3 was consistent with the trend we've seen throughout 2026, contributing to higher revenue yields both during the quarter and for the first 9 months of the year.
For the first 9 months of 2026, our annualized revenue yield increased to 117% compared to 114% in the prior year. Turning to provisioning and charge-offs, our provision for loan losses and other liabilities represented 53% of revenue in Q3 2026 compared to 52% in Q3 of last year.
The modest year-over-year increase was primarily driven by a higher proportion of originations from new customers, particularly within the MoneyKey bank service program. As a reminder, new customer originations generally carry higher upfront provisions compared to returning and existing customers, reflecting the expected credit losses recognized at origination.
With respect to net charge-offs, our net charge-offs as a percentage of average CLAB remained at approximately 12% in Q3 2026, consistent with Q3 of last year and within our targeted range for driving profitable growth. Overall, both our provision expense at 53% of revenue and net charge-offs at approximately 12% of average CLAB were consistent with our seasonal expectations for the quarter.
Maintaining net charge-offs at levels consistent with last year, despite significant growth in our loan portfolio and a higher proportion of new customer originations, reflects the effectiveness of our AI-powered underwriting technology, disciplined approach to credit risk management, and continued resilience of our consumer segment. Turning to profitability, our net income increased by 23% year-over-year to $18.4 million, while adjusted net income increased by 54% to a record $24.9 million.
On an earnings per share basis, diluted EPS increased by 22% to 43 cents, while adjusted diluted EPS increased by 53% to a record 59 cents. Our adjusted return on equity increased to 34% on an annualized basis compared to 25% in Q3 of last year, reflecting strong earnings growth and our ability to generate attractive returns on shareholders' capital.
With respect to the record adjusted EBITDA and adjusted net income, the continued growth of the MoneyKey bank service program, together with higher stage 1 provisions across our other programs, contributed to the larger non-cash adjustments to EBITDA and net income in Q3 compared to the same quarter last year. Turning to operating expenses, acquisition and data expense increased by 40% year-over-year to $25.7 million, primarily reflecting higher origination volumes, a greater proportion of new customer originations, and continued investments in marketing and customer acquisition capabilities.
Sequentially, acquisition and data expense decreased from $26.1 million in Q2, despite new customer originations increasing by 11%. This reflects continued improvement in customer acquisition efficiency, with our cost per new customer funded originations declining to approximately 20.8 cents in Q3, compared to 23.5 cents in Q2 and 26.9 cents in Q1, representing an improvement of approximately 23% since the beginning of the year.
These efficiencies reflect the investments we've been making to expand and diversify our customer acquisition channels, as we've been highlighting since Q4 of 2025. These include our AI-driven search engine optimization strategy, new marketing partnerships, and expanded advertising across digital channels, connected television, and social media.
As these initiatives continue to expand and scale, we're beginning to see the benefits through improved customer acquisition efficiency, while generating record application volume and new customer originations. We also continued to realize operating leverage across other areas of the business.
Combined salaries, wages, and benefits, and G&A expenses declined to 9.2% of revenue in Q3 compared to 9.8% in the prior year period, reflecting the continued scalability of our operating platform. Processing, technology, and program servicing expenses, which include all direct costs associated with the Lending-as-a-Service program, increased by 60% year-over-year, primarily driven by the continued significant growth of Lending-as-a-Service.
Importantly, we're also seeing improved operating leverage within Lending-as-a-Service, with servicing costs declining to 52% of Lending-as-a-Service revenue compared to 64% in Q3 of last year, resulting in an increase in Lending-as-a-Service program margins from 36% to 48% this quarter. Turning to our cost of debt, our average effective interest rate decreased to 10.2% in Q3 from 11% in the prior year period.
The improvement primarily reflects lower benchmark interest rates compared to last year, together with the benefit of the repricing of our foreign credit facility in April 2026. Overall, we are very pleased with the continued expansion in earnings, the increasing diversification of our growth drivers, and the operating efficiencies being realized across the business.
Turning to Propel's capitalization, we ended Q3 with a strong balance sheet and a debt-to-equity ratio of 1.2 times, an improvement from 1.3 times at year-end 2025, reflecting our disciplined approach to capital management. We also had approximately $71 million of undrawn credit commitment capacity under our existing credit facilities.
Together with our strong operating cash flow generation, this provides us with substantial financial flexibility to support continued growth across our operating programs and our increasing dividend. With that, I'll now turn the call back to Clive.
Clive Kinross
Thank you, Sheldon. Now, well into the fourth quarter, we continue to see strong demand and credit performance in line with our seasonal expectations.
In the United States, we have entered new states, broadened our product offerings across the credit spectrum, and expanded our customer acquisition channels. We are serving more US customers than ever.
We also continue to strengthen our marketing strategy through digital advertising, brand awareness, marketing partnerships, and AI-optimized content. Looking ahead to next year, we expect to enter 2027 with a stronger position than ever.
We see substantial opportunities as our geographic expansion, new products, and distribution investments continue to grow and scale. Lending-as-a-Service remains an important part of this strategy.
Supported by committed, long-term capital partners, Lending-as-a-Service enables us to enter additional markets and generate capital-light fee-based revenue without funding the underlying loan receivables on our balance sheet. As it scales, we expect Lending-as-a-Service to become an increasingly meaningful contributor to our business, further diversifying our revenue mix, improving capital efficiency, and supporting expanding margins and returns on equity.
In this area, we are working on additional opportunities for further geographic expansion, product development, and new partnerships. Looking beyond North America, our UK business will also continue to be a significant growth driver.
When we announced the QuidMarket acquisition nearly 2 years ago, the business was on track to generate roughly $30 million US dollars in annual revenue. Today, its revenue over the last 12 months is approximately $70 million, more than double that level.
With third quarter revenue increasing 69% year-over-year to $22 million, we expect full-year 2026 revenue to be significantly higher than the current trailing 12-month figure. That growth reflects both the strength of the underlying business and enhancements made since the acquisition.
Looking ahead, UK consumers remain underserved by traditional financial institutions, creating opportunities for further product development and new partnerships. Another important contributor to our future growth is Propel Bank.
Securing a banking license through an established regulatory structure in Puerto Rico was a deliberate, long-term investment in our US business. Propel Bank is already supporting our US operations through servicing activities and geographic expansion.
As its role expands, we expect it to help consolidate servicing and related operational activities, simplifying our licensing and operating structure, and support our long-term 50-state strategy to serve consumers across the US who face limited credit options. Finally, technology and AI remain central to how we operate and how we grow.
Our investments in automation and operating infrastructure are enabling us to support significantly higher business volumes without a corresponding increase in operating expenses. These investments are translating into meaningful productivity gains, with loans originated per customer service representative increasing approximately 24% year-over-year in Q3, while our operations labor cost as a percentage of revenue reached an all-time low in the quarter.
We are also advancing our AI-powered underwriting capabilities through our latest cash flow underwriting model, using consumer-permissioned transaction and account information to better assess recent income, expenses, and financial capacity alongside traditional credit information. This can help us better understand and ultimately underwrite consumers who are not fully served by conventional credit scoring methods.
We began rolling out our latest cash flow underwriting model towards the end of Q3 and are expanding it as we progress through Q4. Ultimately, we expect these capabilities will support higher approval rates while maintaining our and our bank partners' disciplined risk posture.
To support this initiative, we have recently integrated with Plaid, a leader in financial data connectivity. Through consumer-permissioned financial data, we can gain a more complete view of income, cash flows, and financial obligations.
Plaid was co-founded by William Hockey, who also leads Column, one of our existing banking partners. Together, these relationships reflect the broader financial technology ecosystem supporting Propel's next phase of growth.
Before closing, I want to reflect on two important milestones. In September, we celebrated Propel's 15th anniversary, and just last month, we marked 5 years since becoming a publicly traded company.
When my co-founders and I started Propel 15 years ago, with $4 million raised from friends and family and a belief that technology could change how underserved consumers access credit. Today, we have facilitated more than $3 billion in credit through over 2 million loans and lines of credit, and built an international fintech business operating in the United States, Canada, the United Kingdom, and Puerto Rico.
The numbers speak for themselves. Between 2019 and 2025, revenue grew at a compounded annual rate of approximately 43%, while adjusted EPS grew approximately 64% annually.
At the time of our IPO, trailing 12-month revenue was approximately $95 million, compared with the midpoint of our guidance of $750 million. In addition, since becoming public, we have grown revenue each and every quarter.
As a public company, we have raised our quarterly dividend 14 times, including 13 consecutive increases, representing a cumulative increase of approximately 184%. It isn't just about the numbers.
One of the things I am most proud of is that 15 years later, my co-founders and I are still building this company together. We have stayed true to the same principles: using technology to offer vastly superior products to underserved consumers otherwise locked out, delivering profitable growth, and a commitment to doing right by our consumers, shareholders, and team.
It's not just the founders. I could spend the rest of this call recognizing individuals who have built this business with integrity, commitment, and passion across Canada, the UK, and now Puerto Rico.
The list is long, and to all of you, thank you. I also want to thank the nearly 2 million consumers and growing who have placed their trust in us.
To many financial institutions, our consumers are a credit score. To us, we see the full picture.
Each step of our 15 years of growth is about being able to better serve these consumers in the US, in Canada, in the UK, and more globally in years to come. At Propel, we are not content to rest on what we've accomplished over the past 15 years.
That is what drives us: a focus on what comes next. As we enter 2027, our priorities are clear: to advance our mission of providing consumers with better credit products and greater access to credit by expanding our products and partnerships, entering new geographies, and advancing our AI technology, while continuing to deliver sustainable, profitable growth.
We've accomplished a great deal together, but as I've said many times and as we've demonstrated quarter after quarter after quarter, the best is yet to come. With that, Operator, you may open the line for questions.
Operator
Thank you. Ladies and gentlemen, we will now conduct the question-and-answer session.
If you would like to ask a question, please press star one on your telephone keypad. A confirmation tone will indicate your line is in the question queue.
You may press star two if you would like to remove your question from the queue. For participants using speaker equipment, it may be necessary to pick up your handset before pressing the star keys.
One moment, please, while we poll for questions. Your first question comes from Rob Goff with Ventum.
Please go ahead.
Rob Goff
Thank you very much, and congratulations on the quarter, and of greater importance, congratulations on the full suite of milestones that you did discuss. Incredible accomplishment in the market.
Clive Kinross
Thank you, Rob.
Sheldon Saidakovsky
Thanks, Rob.
Clive Kinross
Very much appreciated.
Rob Goff
Getting back to the day-to-day, can you talk about the level of inbounds that you are seeing and how that is allowing you to manage the filter and direct the filter, and what you're seeing both on those inbounds and how tight the filter might be or changes to the tightness of the filter as we go forward?
Clive Kinross
That's a great question. After 15 years of business to increase originations by 55% in the most recent quarter, obviously that includes Lending-as-a-Service, is pretty extraordinary, I think anyway.
We knew it was coming. We invested a ton over the past several quarters to generate that type of increase.
That notwithstanding, we don't take it for granted. We're very, very proud of it.
Your question is about what are we seeing from an inbound perspective, and we've mentioned that we're now seeing in excess of 1,000, 100,000 discrete applications every day and growing, and I can tell you the 55% growth in originations is less than the increase in inbound applications that we're seeing every day. The demand from consumers, given the part in the credit spectrum, has been very, very strong.
Our job at the end of the day is to make sure we're underwriting those consumers effectively, to manage risk effectively. Our approval rates is approximately what it's been over the course of the year.
We haven't opened up the filters at all, and as you can see, that's producing very strong credit. Provision for loan losses at around 53% is consistent with where we would expect to be in a Q3, and charge-offs at around 12% is also where we expect to be and roughly consistent with the last quarter.
If anything, Rob, our new cash flow underwriting model that as I mentioned in my prepared remarks we launched towards the end of Q3, we think is going to generate excellent results. At the end of the day, it's going to allow us to approve more consumers without taking on more credit risk.
The team's been working on this for a long time now, and I can tell you that the early results are exceptionally promising as far as that's concerned.
Rob Goff
Thank you. One more, if I may, perhaps for Sheldon.
On QuidMarket, could you update us on where you are right now with respect to the automation of the services and the service offerings in that market?
Sheldon Saidakovsky
Hi, Rob. Thanks a lot for the question.
We couldn't be more pleased with the progress in QuidMarket. As we said in the prepared remarks, we've grown it by 69% year-over-year, delivered record revenue, and what's more is just a couple years after we've acquired it, we're at a revenue run rate that's pretty much triple of where we were at the time when we did the acquisition, again as we mentioned in the prepared remarks.
Really couldn't be more pleased with the progress over there. As I've mentioned, what we focused on this year, and this has been a big investment year, where we've expanded the infrastructure, expanded the team, put the balance sheet to work, and grown new originations by record after record over there.
We've done that by applying our expertise in analytics, opening up additional marketing channels, expanding the product set a little bit. We haven't fully integrated our tech platform yet.
We've started to spec it out and work through it, and we expect that to start being integrated and rolled out in the early part of 2027, which will supercharge the growth on a go-forward basis in the years to come over there. In addition, Rob, we're looking for opportunities to extend our product suite over there.
The team in the UK is doing an absolutely outstanding job, and we're capturing more of the addressable market, and there's a lot more to come.
Clive Kinross
I'll just want to layer on a little bit to the UK. Sheldon and I were there a few weeks ago.
I can see that the team in the UK is on the call over here. They really are doing an outstanding job, and it's been a lot of hard work by that team.
You can see the growth coming through in the top line. What you will see in 2027, and this is a little bit of a preview, is that the investments that we've made in 2027 which 2026, sorry, which will lead to a record profitability in the year in the UK as well.
In 2027, that's going to lead to dramatic expansion in particular the bottom line in the UK. We're very, very excited, and that's, as well as many of the other growth drivers in the business, positioning us exceptionally well not only for continued top-line growth next year, but also with even faster bottom-line growth, none more so than in the UK.
Rob Goff
That's fantastic. Thank you very much.
Thank you.
Sheldon Saidakovsky
Thank you, Rob.
Operator
Thank you. The next question comes from Tomer Levitin with Raymond James.
Please go ahead.
Tomer Levitin
Hi, and it's Tomer Levitin on behalf of Stephen Boland at Raymond James. Congratulations on the quarter.
My first question is regarding the forward flow commitments. It's about $210 million in LaaS.
I was curious how much of that was used over the past two quarters, and if you're close to the upper end, if there's any plans to procure more forward flow funding? Thanks.
Sheldon Saidakovsky
Thanks for the question, Tomer. The forward flow, again, that's another program that's just performed remarkably well.
We're very proud of it. Frankly, as everyone can see that our revenues for the business are as diversified as ever.
What are the things that we're quite proud of, notwithstanding the fact that CreditFresh, our most mature portfolio, is growing at a very fast pace, the proportion of CreditFresh is 55% of our revenue this quarter, versus just a couple of years ago, it was about 75% of our revenue. It just shows how diversified our revenues and drivers for the business are.
With that said, Lending-as-a-Service has grown by 170% year-over-year. We've got a lot of committed capital.
We've got a lot of runway to utilize what we have. By the way, the $210 million that you mentioned is only from one institutional provider, and that is from the Column program only.
We've got obviously our other Lending-as-a-Service programs that have additional capital committed as well. We've got, as I think we've said on the last call, it took a while for us to get all the committed capital to start scaling the program.
We've got enough capital right now to hit our growth targets between the allocation of $210 million on the Column program only, and all the other capital committed on the other forward flow programs. We can continue at this pace of growth, and possibly increasing the pace of growth on a go-forward basis in 2027.
The providers of the capital are very, very happy with the returns, and frankly, we're getting a lot of inbound calls for additional capital, which frankly we're turning away at the moment. There's more than ample capital available with the existing providers and opportunity to raise more when we're ready to deploy it.
Clive Kinross
Tomer, I just want to add on to that as well. We've said it many times before, that the area where we're exceptionally prudent is how we manage our balance sheet and how we and our bank partners assess risk, and that won't change.
Where we're less prudent and where we're more aggressive is how we grow the business. How we grow the business, how we expand products, how we bring on new partners.
In the context of Lending-as-a-Service, I'm actually going to take a step back before I pivot into Lending-as-a-Service. Given our new cash flow underwriting models, we are profitable right across the spectrum in all the geographies that we operate and in all the products that we operate.
As a consequence of that, given the strong demand that we're seeing from our Lending-as-a-Service capital partners, they are pushing us to go out and expand into more products into more geographies. That means not only will we continue the exceptional growth that we're already seeing in Lending-as-a-Service, as we onboard more distribution partners, as we expand into additional geographies, but we're in in-depth discussions to broaden the product set where we provide Lending-as-a-Service to continue to fuel long-term profitable growth in that area.
Besides the growth that we're demonstrating, 170% year-over-year, I think everybody caught it in Sheldon's prepared remarks, the margins on Lending-as-a-Service increased, Sheldon just correct me if I'm wrong over here, increased from I think 34% in Q2 to 48% in the most recent quarter. It's another area where on top of top-line growth, you will also continue to see expanded margins.
Tomer Levitin
That's very helpful, thank you. Then my last question is around PCLs.
It was 53%, a slight tick-up due to upfront provisioning and the customer mix, but my question is as LaaS expands and there's no associated kind of credit risk there, and the customer cohort kind of shifts from newly acquired customers to more existing customers, can we see that structurally decline from call it the 50% we're used to seeing?
Sheldon Saidakovsky
The quick answer, Tomer, is yes, structurally, as Lending-as-a-Service, which you correctly said, does not carry a provision for loan losses. Naturally, as that grows at a faster pace than the rest of the business, you'll see the provision for loan losses as a percentage of revenue start ticking down.
Secondly, as repeat customers and our existing customers continue to graduate, and we continue to offer them better products than they can access anywhere else in the market, continues to mature, those consumers carry a much lower loss rate. They perform incredibly well, and that will lead to lower provision for loan losses as well over time.
However, with that said, as you could see, all of the investments we're making across our marketing partnerships and strategies and distribution channels are driving more new application volume than ever. We're able as a 15-year-old company to grow our new customer acquisitions, or new customer originations by 55% year-over-year.
We're nowhere near finished. There's many, many years ahead of us with all the programs and drivers we've built out to continue generating significant new customer growth across the business.
I would say, looking at that mix, I still think that the new customer volumes will continue to represent a large proportion of what we're funding. 47% in Q3 was quite high, wouldn't expect that on a normalized basis.
Certainly it continued to be high and we're going to continue originating record new customer volume on a go-forward basis. It'll take some time before the portfolio gets to maturity.
Tomer Levitin
That's all on my end. Thank you, guys.
Sheldon Saidakovsky
Thank you.
Operator
Thank you. The next question comes from Sufan Nessekoumar.
Please go ahead.
Good morning, gents, and congrats on an impressive set of results here. For my first question, I wanted to touch on the strength in revenue yields.
Obviously this past quarter's performance was ahead of what you described as your full-year outlook. Was there anything in particular that drove the upside in the quarter, and how should we be thinking about the trajectory into Q4 and beyond?
Sheldon Saidakovsky
Sufan, thanks very much for the question. It's another metric we're very proud of.
It's really, really been an outstanding quarter, and you could probably tell from the way we're coming across, we're very proud of all the milestones and what we've achieved from a growth perspective and from an earnings perspective. The revenue yield has been coming up quarter after quarter, and the primary drivers for that, to start with, were all of the investments that we made to expand all of our marketing partnerships, channels, strategies, and we've made enormous progress over there, which ultimately has led to record application volume that we're seeing across the platform, and ultimately then translating into record new customer originations.
For year-to-date, we've been in excess of 45% quarter-over-quarter of our new customer proportion funded, versus last year, it was well under 45%. If you look at that, our new customers, as start at a higher revenue yield before they get graduated over time to lower rates.
That's certainly one thing that's been driving the revenue yield up quarter-over-quarter. Secondly, our MoneyKey bank service program, as we said in our prepared remarks, has been an outstanding growth driver.
That program generally carries a higher revenue yield proportion, as well as QuidMarket, which has grown, as we mentioned, 69% year-over-year, which also carries a higher revenue yield. Finally, our Lending-as-a-Service, which we just spent quite a bit of time talking about, that's included in the revenue yield calculation, and it's reaching record revenue numbers quarter after quarter.
All of these factors are leading to quite an uptick quarter-after-quarter in our revenue yield to 121% here in Q3. With that said, I will say that in Q4 in particular, I would expect it actually to tick down slightly, primarily because Q4 is generally a period of very large graduation, and we expect significant records on the existing customer funded side.
There will be a lot of consumers that are graduating. This is, again, regular, normal course of the period that they typically graduate in, so that will probably tick down the revenue yield.
I think that the revenue yield we experienced in Q3 is probably near the high point. I would expect it to continue to be sort of, as we head into next year, between about 116% to 120% on a normalized basis.
Keep in mind that all of these programs that we've grown over the past three, four quarters that had the outsized growth have been the higher-yielding portfolios, and there's been quite a big ramp-up in those portfolios in particular. Again, we're very very proud to have reached it, and especially maintaining our net charge-off rate consistent with last year, given all this incredible growth, and a provision for loan losses right in line with where we want to be from a targeted profitability standpoint.
Great. Appreciate the color on that.
My second question, I wanted to touch on debt. I noticed your cost of capital has improved, it's lower, but your undrawn capacity is also lower and in the backdrop of a growth acceleration.
How are you thinking about your funding headroom and rates going forward?
Sheldon Saidakovsky
Firstly, the business is generating very strong operating cash flow and expanding earnings. That's number one.
Number two is, our debt-to-equity ratio, and I'll get to the capacity in a second, because you rightfully said that capacity came down or the unused capacity came down a little bit. Our debt-to-equity ratio is at 1.2 times, which has actually ticked down from the beginning of the year, which was at 1.3 times.
The balance sheet continues to be, I guess carrying light leverage, and the business is expanding its profitability quite significantly. What we always try to do with our debt providers, and much like the Lending-as-a-Service partnerships, I could tell you that we're fielding calls all the time from external parties and some tier one institutions that want to participate in our credit facilities.
It's just a matter of us balancing some fees that we pay on unused credit commitments versus having the required capital to continue funding the business. We don't want to have a lot of committed capacity, because it costs us money if we're not using it.
Obviously make sure we size it appropriately. What you should expect is, our facilities are coming into kind of a renewal period in the early part of 2027, at which point we expect to upsize our credit facilities, in addition to the external kind of calls and inbounds that we're getting all the time.
We have nine lenders across our debt facility, and each one couldn't be, I guess I'm speaking for them, but each one is very happy with the performance of the portfolio and only happy to continue funding the business.
Clive Kinross
Just to layer on, just so that this point is clear. We're certainly expecting, Sufan, that when we do renew the facility and upsize the facility, the rates and terms will be an improvement from where we are now.
Obviously, we don't control the fed funds rate. That's a component.
The areas that we do control, I absolutely expect there to be an improvement in both the rates and the terms, with a nice upsize to facilitate all the growth that we're seeing.
Gotcha, that makes sense. Awesome update, guys.
I'll pass the line.
Clive Kinross
Thanks so much, Sufan. Thank you.
Operator
Thank you. The next question comes from Andrew Scutt with ROTH Capital Partners.
Please go ahead.
Andrew Scutt
Hey, guys. Congrats on the strong results, and thank you for taking my questions.
First from me, kind of on the topic of new customers. One number that stood out to me was the cost per new customer is down 23% from the first quarter this year.
Can you guys just kind of expand on what's driving that improvement and how much room there may be for further gains as you continue to scale?
Sheldon Saidakovsky
Hey, Andrew. Thanks a lot for the question.
Another metric we're very proud of. That acquisition cost was quite a topic when it started ticking up in Q4 of 2025 last year.
At the time, we gave a lot of color on that, where we started making some very deliberate and targeted investments in our acquisition strategies, partnerships, and channels. We started investing in AI-optimized content, because consumers are using new ways of searching for loans and credit products online, we're making investments over there.
We're also investing in what we're calling mid-funnel, which is connected TV, social ads, digital channels, online videos, all of those type of things that we hadn't done before. Also this year alone, we added in excess of 20 new marketing partners.
We made these deliberate investments, and you saw the acquisition cost per funded loan tick up to just over 26 cents per new customer funded in Q1, which was the high point. As we always said, a lot of these things take a lot of upfront investments before you start seeing the efficiencies.
On the one hand, it started driving incredible increase in application volume and naturally origination volume, and over the last couple quarters, you've seen the acquisition cost coming down as we've realized on the efficiencies from those investments made. We're very proud of that, but we don't sit on our laurels.
We continue investing. I think coming into Q4, I wouldn't expect it to be at that level.
I continue to give the range of between 20 cents and 24 cents given the rate at which the business is growing at the moment. The other thing, we have to continue investing in the business and expanding.
Ultimately, over time, we will see the efficiencies, and that cost per funded loan tick below the 20 cents, but not yet. As I said, keep it between 20 and 24 cents.
For example, Clive mentioned in his prepared remarks, we're rolling out a new cash flow underwriting model, which ultimately will result in higher conversion rates, lower cost per acquisition, and a lot more originations, as we're going to be able to underwrite and approve more customers than ever before. Initially, we're very prudent and disciplined when we roll out these large transformational initiatives, expect actually, because of that, the data and underwriting costs, which form part of the cost per acquisition, to actually tick slightly up in Q4 before it starts coming down again.
Andrew Scutt
Understood. Thank you for the color there.
Second for me, Propel Bank kind of seems like a potentially underappreciated part of the story. I know some other fintechs are facing some hurdles in securing bank licenses.
Kind of while still early days, can you kind of walk us through the advantages the bank provides today and then kind of talk through some additional capabilities it could unlock over time?
Clive Kinross
It's another area. You're absolutely right.
It's one of those underappreciated areas of our business, and I think also underappreciated that we actually have a banking license. It's part of the de novo operation out of Puerto Rico.
I was actually there with Noah and Sheldon, I think a week or two ago. I see that team's also on the call over here, and they're doing quite an exceptional job down there in Puerto Rico.
We're growing that team up. We're at 30 people today, and continue to put more investments in that team.
We've mentioned geographic expansion as one of the reasons that we're driving the growth in the company, but that geographic expansion wouldn't be possible without Propel Global Bank. Our 50-state strategy ultimately is firmly intact.
That's an incredibly important driver or facilitator of that 50-state strategy, and we expect to continue to add additional states not only in this quarter, but moving into 2027 as well, and a key differentiator ultimately between us and our competitors is we have the regulatory framework with Propel Global Bank to do just that.
Andrew Scutt
Great. Thank you for taking my questions, and congrats again on the strong quarter.
Clive Kinross
Thanks so much, Andrew. Much appreciated.
Operator
Thank you. The next question comes from Michael McCue?]
with TD Securities. Please go ahead.
Michael McCue
Hi, good morning. Just wanted to check with the various strong revenue growth across different lines.
There's been previously discussed a target for LaaS of about 10% of total revenue as an exit run rate for Q4 '26. Looks like that would require a pretty healthy jump quarter-over-quarter in LaaS revenue to reach that.
Are you still targeting that 10% exit run rate?
Clive Kinross
Appreciate the acknowledgement of the growth across the business, and you're absolutely right. Every single business within the broader Propel umbrella grew by a minimum of double digits, with some programs, as Lending-as-a-Service, 170%, like the UK, just under 70% year-over-year growth.
Lending-as-a-Service specifically, at $13.5 million, approached 7% of quarterly revenues, and the guidance that we've provided for Q4, Lending-as-a-Service to be approaching 10%. I think that, relative to the 7%, we're going to be closer to the 10% than we were in Q3, but I don't suspect we will quite get to the 10%, we will obviously inch closer to it and experience, again, triple-digit growth on the Lending-as-a-Service side.
Michael McCue
Great. Thank you for that.
Then just a second one. For now still maintaining that the 2026 guidance on ending CLAB growth of 18% to 24%, it would seem like you'll be getting close to the high end of that, and just wanted to check if there's any updated commentary?
Clive Kinross
I think that's an accurate assessment in so far as we'll be getting close to the high end of that. That not only applies to CLAB, I think there's a lot of the guided numbers where we expect to be close to the top end of the range.
Just given the time of year, we're not inclined to start adjusting the guidance, but your comments that CLAB will be close to the top end of the range or even exceed the top end of the range is certainly a valid observation.
Michael McCue
Great. Thank you.
That was all for me. Appreciate it.
Clive Kinross
Thanks so much, Michael. Appreciate it.
Operator
Thank you. At this time, there are no further questions.
I will now transfer the conference over to Clive Kinross. Please go ahead.
Clive Kinross
Thank you so much, and thanks, everybody, for attending our call this morning. I'd certainly like to thank our investors and our partners for their continued support of our vision of building a new world of financial opportunity.
As always, I would like to extend a big thank you to the Propel team in Canada, the UK, and Puerto Rico for delivering these outstanding record results and achievements. On that note, have an excellent day, and Operator, you may end the call.
Operator
Thank you. Ladies and gentlemen, this concludes the conference call for today.
Thank you for your participation. You may now disconnect your lines.