Vontier Corporation
Q3 FY2026 · Earnings Call TranscriptNovember 5, 2026
Operator
Good morning, ladies and gentlemen, and welcome to the Vontier third quarter 2026 earnings call. At this time, all lines are in a listen-only mode.
Following the presentation, we will conduct a question-and-answer session. If at any time during this call you require immediate assistance, please press *0 for the operator.
This call is being recorded on Thursday, November the 5th, 2026, and a replay will be made available shortly after. I would now like to turn the conference over to Ryan Edelman, Vontier's Vice President of Investor Relations.
Please go ahead.
Ryan Edelman
Good morning, everyone, and thank you for joining us on the call this morning to discuss our third quarter results. With me on the call today are Mark Morelli, our President and Chief Executive Officer, and Anshu Naga, our Executive Vice President and Chief Financial Officer.
You can find both our press release as well as our slide presentation that we will refer to during today's call on the Investor Relations section of our website at investors.vontier.com. Please note that during today's call, we will present certain non-GAAP financial measures.
We will also make forward-looking statements within the meaning of the federal securities laws, including statements regarding events or developments that we expect or anticipate will or may occur in the future. These forward-looking statements are subject to risks and uncertainties.
Actual results might differ materially from any forward-looking statements that we make today, and we do not assume any obligation to update them. Information regarding these factors that may cause actual results to differ materially from these forward-looking statements is available on our website and in our SEC filings.
With that, please turn to slide 3, and I'll turn the call over to Mark.
Mark Morelli
Thanks, Ryan, and good morning, everyone. Thank you for joining us.
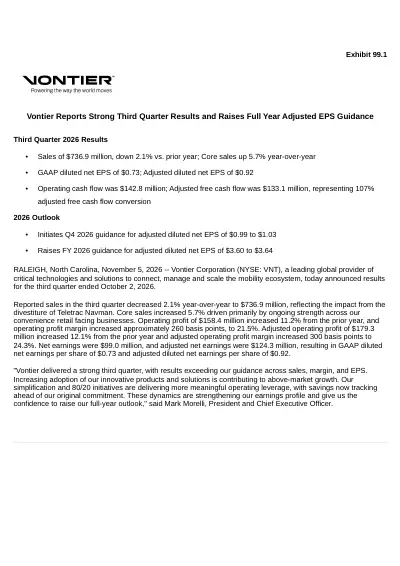
Q3 was a strong quarter and one that reflects the progress we've been making as an organization. Sales, operating margin, and EPS all exceeded our guidance ranges.
We delivered nearly 6% core growth in the quarter with underlying momentum in our core markets. Combined with meaningful margin expansion and continued progress on our strategic priorities, our results reinforce our confidence as we close out the year.
Let me give you a bit more color on what drove the quarter. Top-line performance in the quarter was driven by strength across our convenience retail-facing businesses.
Environmental & Fueling Solutions delivered 13% core growth, reflecting broad-based growth across the portfolio, led by higher dispenser demand, including ongoing upgrade activity tied to the increased adoption of our FlexPay 6 payment platform. Margin performance was a clear highlight in the quarter.
Adjusted operating margin expanded 300 basis points versus the prior year, well ahead of our guidance of approximately 110 basis points. Our results were driven by structural cost actions we've been executing through our simplification and 80/20 initiatives.
Our product line simplification programs delivered incremental savings ahead of our schedule in Q3, which contributed materially to Mobility Tech segment results. Additionally, our structural cost program is tracking closer to $20 million in savings for the year, up from $15 million originally.
I want to spend a moment on the broader demand environment because it helps frame why we're encouraged by the trajectory of the business. Within convenience retail specifically, underlying demand is constructive.
The larger national and regional chains where we are competitively advantaged are committed to their multi-year capital investment plans. Industry profitability is strong, and operators are leveraging technology to improve efficiency and attract consumers to their sites.
They're expanding their networks both organically and through acquisition, and that expansion is driving increasing complexity across their infrastructure. This is exactly where we win, as this creates an attractive end market where we have focused to establish a leadership position.
We have four competencies that are deeply embedded in our customers' operations: energy handling and dispensing, sensing and measurement, unified payment and commerce, and site automation. We have a large installed base with a strong global channel presence.
Increasingly, we are bringing our capabilities together as integrated offerings, connecting critical assets, transactions, and workflows to make our customers' footprint simpler, smarter, and more productive. A good example is our expanding relationship with Tesco, one of Europe's largest retailers.
Building on our existing fueling and payment presence across their network, Tesco will deploy our unified forecourt offering across their entire footprint of more than 700 sites, connecting our fueling hardware with their indoor point-of-sale systems to create a fully integrated payment and fuel management ecosystem. The end result is more automated site operations with improved visibility to real-time data and more seamless, secure transactions.
This is connected mobility in action: deeper integration, more value per site, and a stronger, more durable customer relationship. In our fleet end market, demand continues to be driven by the need for better visibility and control across existing infrastructure.
While some fleet operators have been more cautious about adding new capacity in the current environment, elevated diesel prices have meaningfully increased urgency around fuel monitoring, loss prevention, and operating efficiency. That backdrop plays to our strengths, and the recent acquisition of Ecos enhances our ability to address those needs with a more complete hardware and software solution.
Let me spend a couple minutes on our most recent NACS event because it captures something important about where Vontier is headed. The National Association of Convenience Stores Show brought together more than 25,000 convenience retail operators and industry leaders last month.
Following the go-to-market changes we announced at last year's event, we activated as one Vontier organization, bringing the breadth of our portfolio together across a single, customer-facing presence. The customer response was encouraging.
Operators who engaged with us noted that they could see more clearly than ever how our solutions work together to improve productivity, reduce complexity, and drive revenue growth. That kind of feedback reinforces our confidence that our connected mobility strategy is resonating with customers.
What we showed at NACS is really a live version of what I want to walk you through on slide 4: how we're connecting assets to create a differentiated growth platform for Vontier. Our mission in convenience retail is to enable operators to safely and reliably deliver energy, commerce, and services across the forecourt, inside the store, at the car wash, and at charge points.
Today, we have more than 700,000 connected assets across our installed base. That scale gives us a unique foundation not simply to connect individual products, but increasingly to connect the entire site, and that is where the real value is created.
We see value developing across three areas. The first is unified payments and commerce.
We are deploying a common architecture across multiple payment touch points, giving customers a more consistent consumer experience and a more productive site overall. The second is integrated asset management.
By connecting assets across the forecourt, we give customers greater visibility and the ability to automate more service activity, ultimately delivering higher uptime. QuickTrip, a leading convenience retail operator and adopter of our technology, is a strong example of what this looks like in practice.
They've been deploying our asset management platform across their network and have already reduced their monthly service events from roughly 600 to fewer than 100, driving service costs down by about 80% on a per-site basis. For operators managing larger, more complex networks with constrained labor resources, outcomes like these are becoming increasingly compelling.
The third is data and AI. As more assets and transactions come onto a digital foundation, we're building a richer data layer that supports better insights, faster decisions, and new value-added applications over time.
We're still in the early stages here, but the opportunity is meaningful, and we are investing deliberately. Taken together, these three areas represent how we intend to convert the scale of our installed base into a higher-value, more recurring revenue growth profile.
By adding software, payments, and intelligence on top of a foundation our customers already trust, we create more value per site and build a more durable business over time. This is the growth model we're building at Vontier.
It gives us confidence in our near-term outlook, supports a more durable and higher-quality earnings profile over time, and ultimately strengthens the long-term value we are creating for shareholders. With that, I'll turn the call over to Anshu to walk you through the quarter and our outlook in more detail.
Anshu Naga
Thanks, Mark, and good morning, everyone. Turning to our consolidated results for the quarter on slide 5.
Total sales was $737 million, with core sales growth of approximately 6%, above our guide of 5% for the quarter, led by strong performance in Environmental & Fueling Solutions. Adjusted operating profit margin was just over 24%, an increase of 300 basis points over the prior year.
The improvement was driven by strong execution in Mobility Technologies and Environmental & Fueling Solutions, along with continued progress on our VBS-led simplification efforts. 80/20 is translating into better execution, improved productivity, and a more efficient cost structure.
Adjusted free cash flow was $133 million, representing a 107% conversion to adjusted net income and 18% of sales. Turning to our segment results, beginning on slide 6.
Environmental & Fueling Solutions delivered core growth of 13%, with total dispenser sales increasing low teens in the quarter, supported by an innovative product portfolio and robust new build and replacement activity. Environmental Solutions grew low double digits, fueled by healthy equipment upgrade activity, and we saw solid growth for aftermarket parts and service.
Segment margin expanded 240 basis points, resulting from strong volume leverage and favorable mix, along with the continued benefits from our product line simplification efforts. Turning to Mobility Technologies on slide 7.
Core sales were up 2% year-over-year, supported by healthy demand across the convenience retail portfolio and improving performance in commercial and industrial fleets. Segment margin expanded 740 basis points year-over-year to 26%, reflecting accelerated product line simplification savings in Q3.
Additionally, we accelerated our structural actions, which are now tracking closer to $20 million, which disproportionately benefit Mobility Tech. Beyond the strong margin progression, we are seeing our capabilities increasingly extend across our portfolio as we bring together hardware, software, and services to deliver a more connected mobility solution for our customers.
Finally, turning to Repair Solutions on slide 8. Same-store sales were up low single digits in the quarter, reflecting a relatively stable demand environment.
Technicians spending remains constrained, with continued prioritization of products that offer a clear and relatively quick payback. The decline in revenue was primarily driven by lower interest income as a result of our more stringent underwriting standards.
Segment margin decreased 180 basis points year-over-year to just over 19%. Margins came in slightly ahead of our expectations as we are beginning to see traction on the actions already underway.
The team has made meaningful progress on our broader transformation initiatives over the last 90 days, and I am encouraged by the early results, particularly around commercial execution and improved supply chain management. Turning to the balance sheet on slide 9.
We ended the quarter with approximately $260 million of cash on the balance sheet and net leverage at 2.3 times. During the quarter, we repurchased nearly 3 million shares for $80 million, bringing the year-to-date total to approximately 9 million shares and $280 million, representing about 6% of our shares outstanding.
As we have consistently said, we remain disciplined and balanced in our approach to capital allocation. At current valuation levels, share repurchase remains one of our most attractive uses of capital.
Please turn to slide 10 for a discussion of our updated guidance. Starting with the fourth quarter, we expect sales in the range of $780 to $790 million, with core sales growth of about 3% at the midpoint.
We expect operating margin to expand approximately 280 basis points at the midpoint. Adjusted EPS is expected to be in the range of 99 cents to $1.03, representing earnings growth in the mid to high teens.
Turning to the full year, we are increasing the midpoint of our revenue guidance with sales of approximately $3.03 billion, with core growth at approximately 3%. Based on the progress we've made on self-help, we're raising our outlook for the full-year operating margin.
We now expect adjusted operating margin to expand approximately 180 basis points at the midpoint to just over 23%. Carrying through the outperformance in Q3 and increased outlook of Q4, we now expect adjusted EPS in the range of $3.60 to $3.64, representing low double-digit growth versus the prior year and above the high end of our previous guide.
As always, we've included some other modeling assumptions on the right-hand side of the slide. With that, I will pass the call back to Mark for his closing comments.
Mark Morelli
Thanks, Anshu. As we look ahead, we enter the fourth quarter with confidence and an encouraging setup for 2027.
The demand environment across our core end markets remains healthy. Our commercial pipeline is solid, bookings are strong, and the operational improvements we've been driving are showing up clearly in the numbers.
The combination of volume growth and greater traction with self-help has created a margin expansion profile that we believe is sustainable and supported by structural actions. Our margin improvement is not simply a function of volume.
Our simplification and 80/20 initiatives are driving a higher-quality revenue mix with greater operating leverage and a more durable earnings profile. We have a clear path to delivering on our full-year commitments, including double-digit EPS growth, and the underlying momentum in the business gives us confidence in how we are positioned heading into next year.
I'd like to thank the Vontier team for their focus on VBS and embracing the culture of continuous improvement. The results we reported today are a direct reflection of their dedication, and I'm proud of what this team continues to deliver for our customers and our shareholders.
With that, operator, please open the line for questions.
Operator
Thank you. We will now open the line for Q&A.
If you would like to ask a question and you've joined via the webinar, please click the raise hand icon. If you have joined via the phone line, please press *9 and to raise your hand and *6 to unmute.
In the interest of time, please limit yourself to one question and one follow-up today. When you hear your name called, you will be prompted to unmute your line and ask your question.
We will now take a moment to allow the queue to form. Our first question is from Andy Kaplowitz from Citigroup.
Andy Kaplowitz
Good morning, everyone.
Mark Morelli
Morning, Andy.
Andy Kaplowitz
Mark and Anshu, can you give more color into your simplification initiatives and how they could evolve into '27? Because as you've kind of said, they look like they're accelerating over the last few quarters, and into Q4 '26, with your predicted 280 basis points of margin improvement, I'm sure it isn't reasonable to estimate 280 or more for '27, but it seems like the incremental margin in '27 could be significantly outsized versus your normal algorithm, which is I think 30% to 35%.
Can you do that and more than absorb any memory chip cost inflation you're seeing?
Mark Morelli
Thanks for the question, Andy. Look, I think, as you've picked up here, our self-help has really gained traction.
We put in place a lot of initiatives based on VBS and 80/20. Of course, there's new headwinds that are creeping in based on supply chain constraints, but I think what's really encouraging to us, we really like the setup.
We've got a really strong runway of opportunities ahead, and I think as you can see from our results, that we're really picking them up and they're dropping through to the bottom line.
Anshu Naga
Andy, I'll just add a little more color. I think you see our guide for strong margin expansion in Q4 and raising the full year to 180 basis points.
Really a little early to give guidance for next year, but when you really start thinking about margins for next year, on our core growth, I would expect incremental margins of 30% plus our standard drop-through to flow through. Then we should obviously get some benefit from the carryforward benefit of our cost improvement program, which we started off at $15 million for the year, and it's now at run rate of $20 million for the year.
About a $10 million incremental benefit next year.
Andy Kaplowitz
Mark, I just wanted to double-click on that EFS growth. It's also been sort of accelerating over the last few quarters.
I know you mentioned the strength of your national convenience store customers, but, obviously, gas prices have been high, is it higher fuel margin that's helping the growth? We know you've had new product contribution.
Maybe just, again, durability of EFS growth as you go into '27?
Mark Morelli
The backdrop from the market is really good and constructive. When you talk to our key customers, they're planning their footprint build-outs 18 months, 2 years, sometimes almost 3 years ahead.
These folks are continuing in their new site build-outs, they're still looking at M&A in the space, and consolidation is continuing being. This theme that is under foot today, we certainly see has legs to it.
When you look at EFS growth itself, one of the things that is a little bit more difficult just to pick out from the numbers is this innovation-led growth and our payment kit technology, which is real innovation to the industry and unified payment and things that we're talking about. Sometimes it'll pull a full dispenser, which shows up in EFS growth, because instead of just buying a payment kit, they will change out the whole dispenser.
We call that a crate. You're seeing more growth there.
A little bit between EFS and Mobility Tech, it's a little bit harder for us to call exactly how that mix will play out, but I think what you see in the numbers here is that underlying growth reading through, and we think it has legs to it, and we really like the setup for 2027.
Andy Kaplowitz
Appreciate all the color.
Operator
Thank you. Our next question is from Nigel Coe from Wolfe Research.
Your line is unmuted. Please go ahead.
Nigel Coe
Thank you. Good morning, everyone.
Really nice quarter. Congratulations.
The organic growth was good, but the margins are the real highlights. Anshu, you talked about the $20 million.
Any temporary measures that were taken that might kind of reverse going forward? I've got to ask the question, any tariff refunds?
Doesn't sound like there is, but just want to just check that box off. I know there's a three parts to this question.
Mobility Tech, are we now in a mid-20% zone going forward for this business? I realize that mix can be an influence there.
Anshu Naga
Thanks, Nigel. A few things in overall margins to call out.
One, I talked about the $15 million cost-out program, which is trending or is at $20 million, so that's about a $2 million pickup per quarter versus what we previously guided. Additionally, we talked about our product line simplification program, and we actually managed to accelerate that given exceptional execution by our teams following the Vontier Business System, and that gave us about $4 million of incremental savings in the quarter, which will carry forward in the future.
We also had good volume leverage, which the beat on revenue gave us about $3 million to $4 million of volume leverage. Then finally, the piece that won't repeat itself is the mix.
We had favorable mix both from a geographic and product perspective. It was roughly $4 million, so that won't carry forward into the next quarter and the year.
Overall, strong execution from the teams, and really proud of the way the teams executed. In terms of Mobility Technology margins, we're really proud of what the team's been able to do out there and expand margins.
250 basis points of the 740 basis points was the sale of Teletrac, which is accretive to margins, obviously that continues. Also, majority of the savings are heavily weighted towards Mobility Tech from the $20 million.
Then also the product line simplification, which also leads into our new product rollout that we've seen. For example, 30% of all dispensers that shipped out of our factory in North America had the new version of FlexPay 6 on it, really the innovation is reading throughout there also.
Having said that, from a Q4 perspective, margins will be up about 600 basis points, 24% to 25% range. I think that's probably reasonable for the nearer term.
Medium to long-term, the margin trajectory remains higher, and we'll have more of this product line simplification and 80/20 benefit that over time will read through, and we'll continue to have a shift towards higher-margin recurring revenue as we provide more connected solutions and services to our customers.
Nigel Coe
Okay. Thanks, Anshu.
That was comprehensive. I'm sure someone's going to dig into the 4Q what was embedded by segment.
Just curious on Matco, in light of what Snap-on kind of talked about with diesel prices impacting some of the franchisees. Can you just talk about how you see that playing out going forward?
Mark Morelli
I'm happy to take that one. Look, the underlying fundamentals for repair are pretty decent.
Vehicle miles traveled are up, the age of car park is up, there's a lot of used cars changing hands, repair volume is certainly hanging in there. There's no question, though, that service technicians and also the franchisees who are driving with higher prices, that is an issue.
I will say, though, we are pretty encouraged that our same-store sales are up low single digits in Q3 and that the new management team is really invigorating our district manager base with new tools and capabilities. We think there's more opportunities we can leverage there.
Also, the inventory on the trucks is at a really healthy level, we don't have that to work through. What you do see is a decline in Q3, but that was really mostly entirely due to lower interest income, which is really a result of our more stringent underwriting standards.
I think there's more work to do on Matco. I wish the overall market for repair technicians was stronger than it is, and particularly as we head into next year, but I think net-net, we just have more opportunity to run this business better.
Nigel Coe
Very helpful. Thanks, guys.
Operator
Thank you. Our next question is from Andrew Obin from Bank of America.
Your line is unmuted. Please go ahead.
David Ridley-Lane
Hi, yes. Thank you.
It's David Ridley-Lane on for Andrew Obin. You have a competitor that's publicly announced capacity additions for their underground product line, and that's a vote of confidence in really the visibility of the underground tank replacement cycle.
What were the underground sales for you in the quarter, and have you been building up a backlog or a pipeline of activity?
Anshu Naga
Underground sales were up low double digits, north of 10% in the quarter. The pipeline remains very robust, and we're seeing a lot of interest, obviously, around our offerings, which is leading brand in the market.
From the automatic tank gauge perspective, we launched a couple of years back the new version of that product, which provides connected services, and there's a lot of traction around that. Also, we at the last year's National Association of Convenience Stores, we showcased the hub, which is around remote monitoring and providing visibility to our customers around their overall sites, all their sites, and that's really paying off also.
Overall, we feel pretty good about the environmental market.
David Ridley-Lane
Thank you very much.
Operator
Thank you. Our next question is from Rob Mason from Baird.
Your line is unmuted. Please go ahead.
Rob Mason
Yes, good morning. Mark, just on the fleet business, it sounded like just kind of some mixed dynamics there in the market, with connectivity doing better in infrastructure, maybe a little bit pressure.
Just how is that netting out, and how do you think that plays out into next year, and also understanding in that business there's some chunkier parts where we've seen some chunkier pieces of business flow through there. If you could just speak to how that's playing, blending all together?
Mark Morelli
Rob, you're spot on. We have definitely recognized some chunkiness, as you say, based on that.
I think the thing that I'm encouraged about is that we have real innovation that is coming to market, and we've been able to sell that at scale. The real opportunity for us is our growing backlog of US-based fleet customers that are now looking at that, piloting this technology, and we're looking for rollouts.
I think the challenge we've had is how do we get this growth, but also even that growth out so that it's not lumpy, but that's something that we're fully aware of. We're very encouraged by what we see, and we think there's lots of opportunities for fleet operators to run a better fleet operation and get better drop-through, and our Ecos acquisition is definitely accretive to this.
I am encouraged. We've got hard work going on here, but I like the setup for 2027.
Rob Mason
Very good. Just as a follow-up, maybe I'll ask the question, just how are you thinking about the 3% core growth in Q4, just spread across the different segments?
Anshu Naga
From a Q4 perspective, we should have strong growth in EFS, which should be mid-single digits plus from a core growth perspective. Mobility Tech should be flattish, as Mark mentioned during the Q&A earlier.
We're seeing a lot of traction around our payment technology, but what we're also seeing is customers buying full new dispensers versus just upgrading the payment kit, and when they buy the dispenser, obviously better economics from a Vontier perspective, but the growth shows up in EFS, with Mobility Tech just getting a smaller intercompany sale. Then for Repair Solutions, we should be down low single digits in the quarter, but as Mark also mentioned, we've consciously shrunk the size of our financing portfolio with higher or more stringent underwriting standards, and that leads to lower interest income year-on-year.
Hopefully that helps.
Rob Mason
Very helpful. Thank you.
Operator
Thank you. Our next question is from Katie Fleischer from KeyBanc Capital Markets.
Please unmute your line and ask your question.
Katie Fleischer
Hey, morning, guys. I'm using the webcast this time, can you hear me okay?
Ryan Edelman
We can.
Mark Morelli
We can, Katie. Good to hear you.
Katie Fleischer
Great. I'm interested if this increased spend that you're seeing from customers or from the large c-store chains, is this more of a share-gain story, or is it just existing customers that are investing more in their sites as they expand either organically or inorganically?
Mark Morelli
I think it's a function of the larger regional, national players that have real challenges with how do you manage their asset base, and that asset base is growing. This is the fundamental for our connected mobility strategy and this innovation-led growth, is identifying how can we do better on unified payment, site automation, and they get real drop-through benefits from that, and they also can attract more consumers to their sites.
You say is it share gain, I think it's really just picking up on a real secular driver here where the industry I think has been underserved with capabilities that have been provided for these folks, and I think it's just providing them, listening to their high-value problems and providing them better solutions to be able to do that and integrate our assets. I would also say that the very significant organizational changes we made, as we stepped into this year around focusing on our customers and deploying around that, is a real step forward for us.
We used to operate the company in siloed opcos, and now we're an integrated operating company with real focus on our customers by vertical, and I think that that really gives us enhanced benefits to bring our solutions together. It's a trend we've been seeing, we've been investing in, and I think we're really just happy that we're getting the traction that we are and seeing more opportunities to do much better.
Anshu Naga
Katie, I'll also add that as we're providing more integrated, connected solutions, we're seeing the share of the wallet or this content per site also increase, which benefits us, and that's really around our core competencies that we talked about in the prepared remarks that we're seeing the benefits of that.
Katie Fleischer
That's helpful. Then just going back to the last question on the kind of shift from Mobility Tech into stronger EFS sales, do you have any insight into why customers are increasingly going the full dispenser route, and how you're thinking about Mobility Tech growth going forward?
Just flattish for 4Q is a little lighter than what I would have expected.
Anshu Naga
As the customers are investing in their sites and to make them more modern, to really attract customers, we're seeing them not only spend money upgrading inside, adding fresh food, but also just from an outside perspective, what I'd say is the average age of the dispensers probably gone down a little bit for us, which is favoring us. A little early to give guidance for 2027, but if you think at a very high level, our convenience retail and fleet end market should be growing in the 4% to 5% range as a mid-single digits, and that's 80% of our portfolio.
Now, the split between EFS and Mobility Tech, we have to work through. We're still working our plans, working with customers, but I would expect Mobility Tech to return back to growth next year.
The percentage I think should be probably in line with the overall market for convenience stores growing 4% to 5%. Repair next year, we aren't expecting any change to the market or the macro conditions.
I expect that'll be flat to down low single digits, blended 3% to 4% range.
Katie Fleischer
All right, thanks, everyone.
Operator
Thank you. This concludes our Q&A session.
I will now turn the call back to Mark Morelli for closing remarks.
Mark Morelli
Thanks again for joining us on the call today. We really appreciate your continued interest in Vontier, and we look forward to engaging with many of you over the next several weeks.
Have a great day.