Beiersdorf AG
Q3 FY2026 · Earnings Call TranscriptOctober 27, 2026
Operator
Ladies and gentlemen, welcome to the third quarter conference call. I am Matilda, the Chorus Call operator.
I would like to remind you that all participants will be in listen-only mode and the conference is being recorded. The presentation will be followed by a question-and-answer session.
You can register for questions at any time by pressing star and 1 on your telephone. For operator assistance, please press star and 0.
The conference must not be recorded for publication or broadcast. At this time, it's my pleasure to hand over to Christopher Sheldon, Head of Investor Relations.
Please go ahead, sir.
Christopher Sheldon
Good morning, everyone, and thank you for joining us for our third quarter 2026 conference call. I'm here with our CEO, Vincent Warnery, and our CFO, Astrid Hermann.
As always, we will start with a presentation of the quarterly results, followed by a Q&A session. With that, over to you, Vincent.
Vincent Warnery
Thank you, Christopher, and good morning. Welcome to today's conference call.
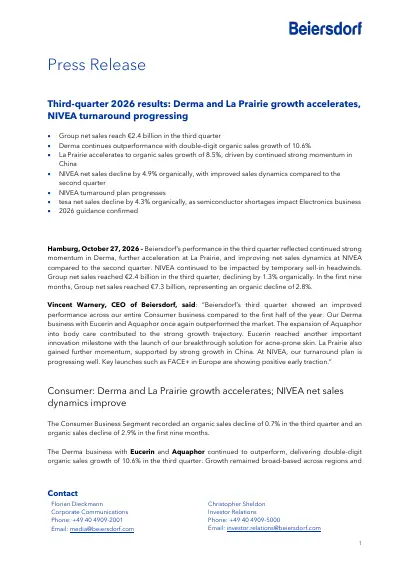
As expected, we completed the third quarter with an improved performance compared to the first half of the year across our entire consumer business. Our Derma business, with Eucerin and Aquaphor, once again outperformed the market.
The expansion of Aquaphor into body care contributed to the strong gross trajectory, and Eucerin reached another important innovation milestone with the launch of our breakthrough solution for acne-prone skin. Our luxury business, with La Prairie and Chantecaille, also accelerated in the third quarter.
La Prairie gained further momentum, with China remaining the key growth driver. In addition, Chantecaille delivered double-digit growth.
For NIVEA, our 18-month turnaround plan is progressing. Key launches such as Face+ in Europe are off to a good start, and the continued growth of NIVEA sell-out is further evidence that we are on the right track.
Our third-quarter performance reflects the strength of our business, but also the continued challenges around NIVEA. NIVEA net sales declined by 4.9% organically.
While net sales dynamics improved compared to the second quarter, several sell-in headwinds continued to weigh on performance. In addition, NIVEA's third-quarter performance was affected by a commercial dispute involving our Russian subsidiary and a local business partner in Russia.
The dispute has been resolved, and proceedings have been settled. Normal business operations have resumed.
With our H1 results, we announced our more comprehensive turnaround plan for NIVEA to restore sustainable growth. I will update you on the actions already underway later in the presentation.
Our Derma business accelerated to double-digit organic sales growth of +10.6%. Growth was broad-based across regions and categories, supported by the rollout of breakthrough innovations and expansion into white spaces.
Healthcare continued its positive trajectory with organic sales growth of +5.7%, supported by innovation in wound care. La Prairie gained further momentum, delivering organic growth of +8.5% in the third quarter.
Overall, our consumer business declined by 0.7% organically in the third quarter. Excluding Russia, consumer delivered organic sales growth of +0.6%.
As highlighted in our H1 call, tesa performance was affected by the semiconductor shortages, impacting our electronics business. This resulted in organic sales decline of 4.3% in the third quarter.
At group level, this translates into an organic sales decline of 1.3% in the third quarter. Let's now look at the performance by brand in more detail, starting with our Derma business.
Derma, with Eucerin and Aquaphor, delivered double-digit organic sales growth in the third quarter, on top of a tough comparison base in the prior year. Over the first nine months, the business grew by +8.7%.
Consumers continue to look for efficacy, scientific credibility, and dermatologists' endorsements, playing directly to our strengths. What gives us confidence is that Derma's growth is not driven by only one market or innovation.
We continue to see strong growth across regions and categories, supported by our expansion into white spaces and the rollout of breakthrough innovations. In North America, Aquaphor Body, the largest US launch in the brand's history, is off to a strong start and significantly expands the brand's potential beyond its traditional categories.
In Latin America, Mexico and Brazil continue to drive growth. In Europe, a strong sun season, as well as Thiamidol line extensions in body care, supported organic growth of +8%.
Across the AMEA region, Eucerin continued to deliver double-digit growth of +25%, with particularly strong performance in Thailand and China. During my recent visit in China, where Eucerin is a leading anti-pigmentation brand, I saw firsthand how Thiamidol is bringing our deep skincare expertise to consumers around the world.
With Thiamidol now also registered in Korea, we are opening up further opportunities in one of the world's most innovative skin care markets. In July, Aquaphor launched into body lotions and creams, thereby substantially expanding its growth potential in the category that represents 80% of the US body care market.
The launch is off to a very strong start. Within six weeks after launch, Aquaphor already secured the number-three position in the US therapeutic skin care market and the number-one derma body care position in the drugstore channel.
The launch was supported by strong activation with leading US retailers. In addition, feedback from dermatologists has been very positive.
As a result, Aquaphor accelerated to an organic sales growth of +13% in the third quarter. The launch of Eucerin DermoPure Clinical ProBIOM 8 is another strong example of how we turn our scientific expertise into clinically proven skin care solutions.
At the heart of this breakthrough innovation is our patented active ingredient, [Topic-A?] , which takes a new approach to acne-prone skin by helping to balance the skin microbiome.
It builds on more than 20 years of microbiome research and the expertise gained through our acquisition of S-Biomedic. Feedback from dermatologists and consumers has been overwhelmingly positive.
At EADV, Europe's leading dermatology congress, more than 1,400 healthcare professionals joined the largest scientific symposium in EADV's history to discuss the science behind this innovation. ProBIOM 8 was launched in September across its first markets in Europe, Mexico, and Thailand, opening new growth opportunities for Eucerin in one of the world's largest skin care categories.
Let's continue with our luxury brand, La Prairie. After temporary retail disruptions earlier in the year, the brand returned to growth in Q2 and accelerated further in the third quarter, delivering strong organic sales growth of +8.5%.
La Prairie's recent performance is a result of the strategic repositioning measures implemented over the last two years, which are paying off. China remained La Prairie's key growth driver, with net sales up +28% in the third quarter and strong sell-out growth.
Both outstanding e-commerce and impressive brick-and-mortar performance contributed to this result. Winning luxury skin care, especially in China, requires differentiated technology and science-based innovation, which plays directly to our strengths.
Our ability to succeed in such an environment is demonstrated by the exceptionally strong performance of our White Caviar line, a key growth contributor in China. Based on our hero ingredient, Thiamidol, White Caviar is the number-one luxury brightening collection in China.
We have also made good progress in expanding La Prairie's price range. In September, we launched our new entry line, Swiss Pristine, combining our scientific expertise with advanced biotechnology.
The launch enabled us to attract a new generation of consumers and selectively expand our distribution. The launch was accompanied by strong digital, influencer, and retail activations across regions.
Initial results are strong. Swiss Pristine is accelerating client recruitment, reaching significantly younger consumers, and generating strong early demand across regions.
At the same time, we are seeing increased engagement from existing clients and encouraging cross-selling into our core franchises, reinforcing its potential as an entry line into the broader La Prairie portfolio. Now let's turn to NIVEA.
Net sales declined by 4.9% organically in the third quarter. Excluding Russia, NIVEA's sales declined by 3.2% organically in the third quarter.
While net sales dynamics improved compared to the second quarter, temporary sell-in headwinds continue to weigh on performance. Retailer disputes continue to negatively affect the third quarter, but have now been largely resolved with only a few remaining that will impact Q4.
Q3 also continued to be impacted by phasing and destocking. While the fourth quarter will still be impacted, we expect this effect to gradually fade, leaving us with healthy stocks level by the end of the year.
NIVEA sell-out continued to grow globally in the third quarter, an early evidence that our rebalancing measures are starting to be effective. At the same time, our sell-out growth remains below market, which is why we started implementing the second phase of our rebalancing, a comprehensive turnaround plan for '26 and '27.
Let me remind you of key pillars of our turnaround plan before highlighting some of the actions that are already underway. First, we are unlocking the full growth potential of NIVEA's entire portfolio across all categories.
We are accelerating our innovation pipeline to respond faster to changing consumer needs and market trends. Second, we are reinforcing NIVEA's accessibility and value-for-money propositions to drive penetration and volume.
Third, we are fully leveraging NIVEA's local relevance. While NIVEA remains a global brand, we are increasing our ability to respond to local consumer needs and market dynamics.
This is already reflected in our innovation pipeline, with a stronger focus on local insights and proven regional franchises. Fourth, we are stepping up consumer-facing investments and focusing our resources on where they can have the greatest impact.
Let me now show you how we are putting these priorities into action. One example is the launch of Face+ in Europe.
Building on the success of Facial in emerging markets, we are bringing this proven consumer-relevant concept to Europe as Face+, adapted to local needs. This is where we can leverage NIVEA's global strengths and our fast-track approach to innovation: listening closely to local consumers, learning from what works in individual markets, and scaling the strongest ideas across regions.
With currently four SKUs, Face+ delivers well-known ingredients such as vitamin C, niacinamide, panthenol, and hyaluronic acid at an affordable price point of between €5 and €6. Early traction is very positive, particularly in recruiting new consumers to NIVEA.
While the initial launch focuses on moisturizing creams, our ambition is to build Face+ into a broader face care franchise over time. Another example is the launch of our Sweet Treats shower and deo limited edition in Europe, with Germany as a focus market.
Designed to engage young consumers and drive penetration, the range adds fragrance-led experiences to our core portfolio and responds directly to emerging consumer preferences. In Germany, we are supporting the launch with a fully digital media campaign and strong consumer activations with very encouraging initial consumer and market feedback.
India is already a strong market for NIVEA, with continued double-digit growth and penetration gain. Over the last 12 months, we have added 10 million new consumers to the brand.
Our ambition is to accelerate penetration through locally relevant innovation. One example is the expansion of NIVEA Soft into the fast-growing gel moisturizer segment.
The new serum-infused gel is tailored to local demand for lightweight, non-sticky hydration, while adding skincare benefits through hyaluronic acid, niacinamide, and vitamin C. Supported by accessible formats and integrated media and influencer activation, the launch is designed to drive trial, recruit new consumers, and accelerate NIVEA's growth in India.
We are also stepping up consumer-facing investments and focusing our resources on where they can have the greatest impact. Looking ahead, our recently signed five-year partnership with the Tour de France is a strong example.
Starting in 2027, NIVEA MEN will become a partner of one of the world's best-known sporting events, giving us a major platform to connect with consumers across Europe. Astrid will now give an overview on tesa, our performance by segment and region, as well as the outlook for the rest of the year.
Over to you, Astrid.
Astrid Hermann
Thank you, Vincent. tesa recorded an organic sales decline of 4.3% in the third quarter and 2.1% in the first nine months of the year, reflecting the soft performance of the electronics business.
As outlined in our half-year call, the market environment became increasingly challenging, particularly in Asia. Ongoing chip shortages have impacted production volumes across the consumer electronics industry and led to lower demand from key customers.
In addition, we faced a particularly strong comparison base in electronics in the third quarter. As a result, the segment remained below the prior-year level and more than offset the positive development across the rest of the portfolio.
The decline in electronics also weighed on profitability, given that electronics is one of tesa's higher-margin business areas. Excluding electronics, tesa delivered low-single-digit growth in both Q3 and year-to-date.
The broader industry portfolio outside electronics developed well. Electrical Systems continued its strong momentum, supported by project ramp-ups and new customer wins across regions.
Automotive delivered a strong performance, accelerating in Q3, outperforming underlying industry trends, and benefiting from new business wins in electric vehicles. Print & Packaging Solutions as well as Industrial Trade & Converting also contributed positively, supported by project-driven growth.
The Consumer business remained below the prior-year level, reflecting softer demand outside of Europe. The European business recovered over the course of the year, supported by continued momentum in e-commerce.
Let me now walk you through some further details of our sales performance in Q3 and the first nine months of the year. Beiersdorf Consumer business generated net sales of €1.94 billion in the third quarter of 2026, with an organic sales decline of 0.7%, representing a slight improvement compared to the first half of the year.
Due to favorable foreign exchange effects, nominal sales increased by 1.0%. Year to date, Consumer generated net sales of €6.052 billion, with an organic sales decline of 2.9%, while nominal sales declined by 3.2%.
Our tesa business recorded an organic net sales decline of 4.3% in the third quarter of 2026, closing the quarter with net sales of €422 million. Due to favorable foreign exchange effects, nominal sales declined by 2.0%.
As previously explained, sales development in the quarter was significantly impacted by the semiconductor shortage. Year to date, tesa generated net sales of €1.262 billion, at an organic and nominal sales decline of 2.1%.
As a result, the group generated net sales of €2.362 billion in the third quarter of 2026, at an organic sales decline of 1.3%. Due to favorable foreign exchange effects, nominal sales increased by 0.4%.
Year to date, the group generated net sales of €7.314 billion. Organic sales declined by 2.8%, while nominal sales declined by 3.0%.
Looking at our consumer business across regions, while the consumer net sales development continued to be impacted by NIVEA's softer performance in the first nine months of the year, the business showed a sequential improvement in the third quarter. At the same time, other parts of the portfolio continued to perform strongly, particularly our Derma brands and La Prairie.
North America returned to mid-single-digit growth in the third quarter, driven by continued strength in Derma, particularly due to the Aquaphor Body launch. Coppertone continued to weigh on the region's overall performance.
Latin America also returned to low-single-digit growth in the third quarter, benefiting from an improving NIVEA performance in Brazil and continued strong momentum in Derma, particularly in Brazil and Mexico. The crisis in the Middle East continued to weigh on Africa, Asia, and Australia region.
However, this impact was more than offset by continued strong growth in China, India, and Thailand. Western Europe continued to decline, however at a slower rate compared to the first half of the year, benefiting from sun care, as well as the resolution of some customer conflicts that had affected NIVEA.
Lastly, our net sales in Eastern Europe declined by 14.6%. A key factor behind this development was our remaining business in Russia, which is reported in our Eastern Europe region.
Excluding Russia, net sales in Eastern Europe declined by 1.3% in the third quarter, representing a significant improvement compared to the first half of the year. Now let us turn to our outlook for the rest of the year.
Consumer delivered an improvement in the third quarter compared to the first half of the year. Derma continued its strong performance, while La Prairie accelerated its growth.
NIVEA remains challenging, but we are seeing encouraging early signs from the turnaround plan. Taking into account an organic net sales decline of 2.9% for Consumer year to date, and a tougher prior-year comparable in the fourth quarter, we continue to expect a low-single-digit organic decline in net sales for the full year.
We expect a consumer EBIT margin excluding special factors of at least 11.0%. For tesa, we continue to expect net sales to remain flat to slightly growing organically, and an EBIT margin excluding special factors slightly below the prior year's level.
As pointed out, however, the semiconductor shortage may further negatively impact tesa's performance. Due to the corresponding negative mix effect on profitability, it also creates a risk to tesa's EBIT margin for the full year.
At group level, we continue our guidance for a low-single-digit organic sales decline and an EBIT margin excluding special factors of at least 11.8%. With that, we are happy to answer your questions.
Over to you, Christopher, for the Q&A.
Christopher Sheldon
Thank you, Astrid. Let's start with the Q&A.
Please note that we have a maximum of two questions per caller. The first question comes from Jeremy Fialko from HSBC.
Jeremy, please go ahead.
Jeremy Fialko
Yeah. Hi.
Morning. Perhaps you could just talk a bit more about the NIVEA performance in the quarter, maybe a bit more detail on kind of what the sell-out was and just if you could break down some of the sort of technical factors that led to the sell-in being below that.
Then secondly, maybe you could talk about a bit more detail about your consumer expectations for Q4 and what you think the prospects of that getting back into positive territory are. Thanks.
Vincent Warnery
Jeremy, on NIVEA, so as we said, we had the complexity with Russia, which has impacted strongly our sell-in. Now as I said, we are out of that, we are back to normal business.
What we see clearly is an improvement of the sell-out. We are growing in sell-out.
We are not yet gaining market share, which means we are not yet growing in line with the market, but we are overall growing, with some very good results in emerging market, where we are gaining market share over the last three months, which is a pretty good news. In Europe, we are still struggling because of some customer conflict, which are almost over now, but which impacted the Q3.
All in all, we are getting closer to having the same level of sell-in and sell-out. We are destocking also in order to finish the year, and that was your second question, with a strong in sell-out, with very healthy stocks in each and every country, being able to embark into a much better 2027.
Jeremy Fialko
Thank you.
Christopher Sheldon
The next question comes from Celine Pannuti of JPMorgan. Please go ahead, Celine.
Celine Pannuti
Thank you. Good morning.
Just want to come back on some of the key points you mentioned on Europe. On Russia, is this ongoing?
Do we still expect Eastern Europe to be down massively in the coming quarters, or did you say you resolved it? Then on Europe, can you talk about your sell-out data?
I presume there was a benefit from sun care in the summer, but if you look at the maybe last six weeks, how do you feel the sell-out has improved? Just trying to understand how much of a destock impact we should expect for Europe and disconnect between sell-in and sell-out in the fourth quarter.
Vincent Warnery
Thank you, Celine, for your question. On the first question, Russia, we are absolutely back to business.
We had a commercial issue with our manufacturer in Russia. We have solved this issue and we are back to business, Q4 will be a normal business for Russia, and we'll go back to what we have been doing over the last years.
It means also that overall, the Eastern Europe will be positive. We are seeing a strong improvement in Eastern Europe.
As we said, we are almost flat in Q3 in Eastern Europe excluding Russia. We are gaining market share on both NIVEA and Eucerin, we are expecting a good quarter in Q4 in Eastern Europe.
In Western Europe, this is where obviously we struggle with some customer conflict. Those customer conflicts are almost all solved.
We still have one remaining issue that should be solved. We had, in fact, a sell-out which is slightly positive.
I think over the first months of 2026 and year-to-date August, we are growing at around +1%, which is not yet at the level of the market, but which is much better than what we experienced in last year. We gain, indeed, market share in sun care.
We are by far the best performing global brand in sun care. We grew 6% the sell-out.
We are back to growth also in deodorants. Where we are struggling more is face care, and this is why the launch of Face+ that just started a few weeks ago is a good news.
I'm expecting also better news in sell-out in Europe. All in all, a Q4 in Europe which should be better, having solved the issue with retailers, having solved the problem with Russia, and having also reduce strongly the level of stocks that was coming from the launch we did last year in the Q4 2025.
Celine Pannuti
Thank you. Can I just ask a follow-up?
Super helpful what you just said on Europe and Eastern Europe. I know that Q4 has a tougher comp on the rest of the world, net-net, do you expect Q4 to be at the same level or even better than Q3 at a group level for Consumer?
Vincent Warnery
You've seen that we are maintaining the guidance, which means that we should have a Q4 which should be slightly negative. Still impacted by some customer conflict, but even more by the fact that we want absolutely to finish the year with healthy stocks on each and every product category, in each and every country.
As you remember, the Q4 '25 was strongly impacted by the launches of Derma Control and Epigenetics, that will not happen again. All in all, slightly negative quarter, by the sell-out which should be even better than what we have seen year-to-date August.
Celine Pannuti
Thank you very much.
Christopher Sheldon
The next question comes from Guillaume Delmas of UBS. Guillaume, please go ahead.
Guillaume Delmas
Thank you very much, Christopher, and good morning, Vincent and Astrid. Couple of questions for me, please.
The first one is on the tesa's guidance, because based on the first nine months performance, the guidance seems to require a very meaningful acceleration in the fourth quarter. I'm getting to 7% plus organic sales growth in Q4 to get to flat for the year.
My question here is, what visibility do you have on this potential shortage of semiconductors in the last two months of the year? In a scenario whereby, electronics would remain a drag, as in, they would not improve relative to Q3, would tesa remain negative in the fourth quarter?
Then my second question, it's a question on gross margin, mostly about the back half of '26 and maybe early days, but also on '27, because we are seeing a continued increase in commodity cost, in logistics cost. At the same time, you're making it very clear you're trying to reinforce NIVEA's value-for-money proposition, which, correct me if I'm wrong, but that seems to signal limited to very modest pricing actions going forward for NIVEA.
Question here is, would it be fair to assume that gross margin is likely to decline over the next 18 months, or are there some levers you've identified that could help you maintain your gross margin at current levels? Thank you very much.
Astrid Hermann
Guillaume, I will take both of your questions. Related to the tesa guidance, we have had quite different quarters in the prior year, comparison is quite different in the fourth quarter, with much, much lower electronics business in the prior year, and therefore a much easier comparison than, for example, in the third quarter of this year.
It's just not an apples-for-apples comparison, and we are seeing, again, the remainder of business excluding electronics really accelerating, a very, very good performance, and that's going to also contribute to in the fourth quarter. On top of that, while we do not expect the shortage to significantly ease, again, we do see that we will still have some electronics business and that should be less of a drag on the fourth quarter impact.
That said, I do want to highlight, and obviously this is why we've also spoken about a risk, there is a lot of uncertainty and it's a bit difficult completely to have complete visibility of what's to happen in the months to come. We're obviously, again, working on certain scenarios and expectations from orders from our customers.
On your gross margin question, we have talked about the fact that both the rebalancing in NIVEA is obviously putting some pressure on our gross margin, we are investing more in consumer-facing for NIVEA and beyond that, obviously the rebalancing, less face care, more personal care, is obviously having an impact here as well. The back half will be similar.
There will be pressure on gross margin downwards. Into next year, similarly, obviously less of an impact because we are already making significant changes this year, and we should start to be able to benefit obviously from some positive mix impact by our Derma business and our La Prairie luxury business growing stronger.
Guillaume Delmas
Thank you very much.
Christopher Sheldon
The next question comes from Karel Zoete at Kepler. Please go ahead, Karel.
Karel Zoete
Yes, good morning. Thanks for taking the questions.
I have two questions. Maybe a follow-up one on in relation to pricing.
Can you share what's been the volume component in the third quarter, but also how you think about pricing going into next year? What kind of price increases do you require to protect gross margins?
Particularly, of course, the situation in Europe is interesting. The second thing is, I noticed that on the slides you mentioned quite frequently growth rates excluding Russia.
Are you now considering to exit your Russian business, or is that something you like to hold on to for the time being? Thank you.
Vincent Warnery
Thank you, Karel, for your question. I will take both of them.
If you look at the performance of the quarter, the third quarter, is clearly there is no price effect. Most of the gross or the decline is volume.
Next year, we are coming with an extremely, extremely reasonable pricing policy. We are not willing to increase price because clearly the value-for-money positioning of NIVEA is essential.
This is why we are betting on the fact, as Astrid said, that we are delivering more units and that we'll be able to compensate the increased cost of goods by more units in our factories. Clearly minimizing any kind of price impact.
We'll have a price discussion, price impact on our consumers next year. On Russia, no, we are in Russia.
We stayed in Russia. In 2022, we said that we will exit La Prairie and tesa.
We did it. We said that we'll reduce our assortment by 65%.
We did it. We said that we'll not do any advertising.
We did it. We are still in the same strategy and the same mindset.
We are there to stay in Russia with our brand, protecting the brand, paying the salary of our people, but there is no change in our strategy regarding Russia.
Karel Zoete
All right. Thank you.
Christopher Sheldon
The next question comes from Tilly Eno at Morgan Stanley. Tilly, please go ahead.
Tilly Eno
Hi, good morning. Thanks for taking my question.
Just on La Prairie, clearly a very significant acceleration in the quarter. You obviously mentioned that you launched the entry-line SKU in September.
Could you just clarify if there was any sell-in benefit related to that entry-line launch? Then also on China specifically, you called out 28% growth in La Prairie there.
Could you quantify the sell-out in China La Prairie for us? Thank you.
Vincent Warnery
Swiss Pristine is really a great great event for La Prairie. We used to have in the past this kind of entry line, but we stopped it, and we came back with a line.
It's sold between €180 and €300. This is a line which is allowing us to recruit younger consumers.
They are on average 4 to 10 years younger than the La Prairie consumers. 80% of them are new to the brand.
They are people who are not buying La Prairie before. What is even more interesting is that we can also open new retail channels.
For example, we are selling La Prairie on Amazon US since last month. We have also been able to enter Sephora and Bluemercury in Canada with a Swiss Pristine line, something we could not do with a more expensive line.
Clearly an opportunity to enlarge the penetration of the brand and to be sure that we can recruit people who want to discover La Prairie, but not of course at a very high price. In China, we are benefiting from the launch of Swiss Pristine, but also from the success of White Caviar.
White Caviar is a franchise we have in China since a long time, but we decided last year to put Thiamidol, our hero ingredient, into the franchise, and we became, instantly, number-one brightening luxury franchise in China, complementing the strength of the brand by the true efficacy. It gave us over the last six quarters we have been growing in sell-out double-digit, and it's really a continuous success we have having in China, not only in e-commerce, but also in brick-and-mortar.
This is why, we had this month, this quarter, the best ever performance of La Prairie with a +28% in China. Really a combination of more efficacy with our legacy franchises, a younger target group touched by Swiss Pristine, and the fact that we are leveraging also not only the department stores, which are core to La Prairie, but also e-commerce and also new distribution channels which, until now, were not selling La Prairie.
Christopher Sheldon
The next question comes from Warren Ackerman at Barclays. Warren, please go ahead.
Warren Ackerman
Yeah. Good morning, Vincent, Astrid, Chris.
Warren here at Barclays. I've got one housekeeping and two questions.
The housekeeping is, did you confirm that the NIVEA sell-in, sell-out gap will completely close in Q4 or do you expect that gap to close at the exit of Q4? If you can just clarify that.
Then my main questions are, firstly, Vincent, how are you feeling about the NIVEA reset? Obviously you went all-in on facial skin care, you're now pivoting back to the core.
What's the organisation reaction? Does the organisation feel that you can grow the core in categories like deodorants, despite the fact that some launches have been below expectations, whilst still capturing some of the opportunity in facial skin care?
When organisations do a 180-degree pivot, there's also risks on the other side. Just interested to understand your kind of more strategic view on that and how the organisation feels about that, both good and bad.
Then secondly, on the €100 million investment that you're making in H2, now more time has elapsed, are you able to kind of give a bit more colour exactly where that spend is going and the balance of it between in-store activation, influencers, local innovation, changes, the returns that you expect to see on that? Then how that sort of feeds into kind of, yeah, next year's margins?
'Cause I think a few people are still kind of a bit unclear about the cadence of margins H1, H2 just given the kind of size of the investment that you're making. Thank you.
Vincent Warnery
Thank you for your question. I will take the first one, and Astrid will take the second one on the €100 million consumer-facing investment.
On the first one, we will exit the year with sell-in exactly in line with sell-out. That's clearly the commitment, and the commitment we have in each and every country.
We want to start 1st of January 2027 with an extremely healthy situation in terms of stock and being driven by sell-out, so that's why we are coming with a quarter which will still be slightly negative. I think your question on the NIVEA reset is a very good question.
We tried to transform, in a way, NIVEA into a premium face care brand with Luminous and Epigenetics. We succeeded to some extent, but it was done at the expense of the other categories.
This is why we are coming back to something which is much larger. We are not only focusing on face care.
This is still the number-one priority, but we are clearly seeing the other categories as an opportunity to improve penetration, and I was giving the example of the shower, which is one of the best product in terms of penetration in countries like Germany. We are also acknowledging the fact that our consumers are really attached to the value-for-money positioning of the brand.
This is why I'm extremely happy with the success of Face+, to see Face+ able to recruit 80% of people who have not used NIVEA face product in the last 12 months is something remarkable. The fact that we are also taking away market share from private label is something that we didn't have in the past, value for money is essential.
Last but not least, also this acknowledging also the fact that NIVEA has not been built in the same way in each and every country, and that in some countries we are more body/deo brand, in other countries we are actually stronger in face care. We acknowledge also the fact that there is not one single NIVEA identity across the world, and that's something which we respect, and Face+ is a good example.
How is the organisation reacting? Very positively, in the sense that nobody is regret that we tried to really push the Thiamidol and the Epigenetics option strongly, because it was an opportunity that has made the success of Eucerin and was really would have been a pity not to try.
I think everybody is very comfortable with this rebalancing, which is leveraging also local talents. I was showing the example of the Tour de France, which is coming from a strong recommendation from the French GM, but also many other things we have done in the country.
Overall, an opportunity to try new things, to be bolder, to also accept the idea that some things will work, some things will not work, more agility. I think the recent good news, the recent green shoots we see in many different countries is giving us some hope that we have found our way.
More to do, we have still some work to do, but we have found our way to make NIVEA growing again.
Astrid Hermann
Warren, your question related to the incremental spend, about a third has gone to in-store, the remainder primarily into digital marketing, including of course influencer marketing as well, particularly with some of the launches we discussed, Face+ and so on. The spend really started towards the end of the third quarter as we were also launching some of these initiatives, and we should see quite a bit of the spend also in this quarter.
In terms of next year, it will be a different pattern in that, obviously, early this year we were still spending behind some of the innovation from the prior year. That's going to look obviously quite different and much more aligned with new picture of rebalancing, to really now support all these initiatives we spoke about.
Warren Ackerman
Thank you.
Christopher Sheldon
The next question comes from Tom Sykes at Deutsche Bank. Tom, please go ahead.
Tom Sykes
Thanks, Christopher. Morning, everybody.
Just firstly, on your comments on price into next year, you obviously also gave the view that you're looking to grow volumes to grow your sales next year and that's going to be the main driver. Do you think about pricing next year as an absolute price and the value which you're going to get from that and the perception of what that's going to lead in to in terms of volume, or are you looking at relative pricing against your peers?
Do you have any feeling for where that relative pricing dynamic is going to be next year through your retailer discussions and how they're negotiating with others, because it does feel like you're kind of going to be perhaps moving that bar on price depending on where others may come out. Just any views on that.
Then just on La Prairie, you've obviously seen an improvement. How much of that improvement would have come through FX?
I think you sell in US dollars in part, and then you're calculating some of the travel retail obviously in euros. Would you be able to give the benefit of that FX to the organic growth of La Prairie at all, please?
Vincent Warnery
Take the first question, and Astrid will tell you about the FX La Prairie. On your first question, you're absolutely right to mention that pricing has two dimensions.
This is the negotiations with retailers, which is always complicated, particularly in Europe, and also the consumer, the effect on consumer prices. On the first one, obviously, we are trying to minimize any disruption next year.
This is why also some of the deals we have made this year are covering also next year, which is a good news. We are clearly willing to minimize this aspect.
On the consumer, as our competitors are not the usual suspects. We are not losing market share against the other big companies that you are following.
We are losing market share against local brands, against Korean brands, a local private labels, which are cheaper than us. It is true that every additional cent, every additional euro consumer price is impacting the value-for-money positioning of NIVEA.
This is why we are extremely cautious and we clearly see the opportunity to do price increase if and only there is a real consumer benefit that we are able to explain. It could be a new technology, could be a new claim, could be a new galenic.
Both, I would say, aspects, retailer element and consumer element, will be extremely cautiously managed next year. We clearly want to give more products to more consumers, and it means we need to have the support of retailers and we have also to offer product at the right price.
On your second question?
Astrid Hermann
Yes, Tom, in La Prairie year-to-date, the impact from the US dollar has actually been negative a couple points. Only in the third quarter, it started to obviously move into positive territory.
It's about a 1% point improvement.
Tom Sykes
Many thanks indeed.
Christopher Sheldon
The next question is from Cian Münster at Reuters. Please go ahead.
Cian Münster
Good morning. Two questions for you.
First, a general one: What are your observations in terms of customer demand? Do you see customers preferring cheaper options over premium products?
The second question about the Middle East: Are elevated oil prices and the supply chain disruptions in the Middle East still creating operational challenges with costs and deliveries? Take
Vincent Warnery
the first question, Astrid the second one. In fact, the very complicated or interesting phenomenon in the market is that you have both.
You have indeed, particularly in mass market, consumer willing to have, I would not say cheaper, but really value-for-money proposals, and this is why NIVEA has to fight, and we have to maintain what has always been a key dynamic of NIVEA: We are a value-for-money brand. In other channels, and for example drugstore, pharmacies, perfumeries, department stores, you have clearly premium skin care developing, but a premium skin care which is supported by the strong scientific efficacy.
This is why we are doing extremely well with Eucerin, and we've been able really to transform Eucerin into an extremely strong derma brand combining the R&D expertise of Beiersdorf and the equity of Eucerin towards dermatologists, but also with more recently with La Prairie, able to sell product not only at between €180 and €300, like Swiss Pristine, but also around €2,000 for the core franchises of La Prairie. We have to manage both.
We have clearly to have a differentiated approach between NIVEA, which is clearly value for money, and La Prairie, Eucerin, Aquaphor, and Chantecaille, where we are clearly offering consumers products which are more into this premium skin care category. The good news that we have the tools to do that.
We have not only the scientific expertise of Beiersdorf, but also we have been able over the last years to develop strongly the equity of the brands, and they can support these premium prices. This is why we are coming with pretty good results, especially in the third quarter.
Astrid Hermann
In terms of your question related to the Middle East, I would certainly suggest that it's caused quite a bit of headache to our teams, particularly in the supply chain. I would say, first of all, that we are not seeing significant impacts in terms of disruption of our supply chains.
We have found ways around them. This has led, though, to the most immediate impact being higher logistics costs for sure.
In terms of the remainder impact from higher oil price, we have so far been able to manage that quite well, I have to say, but obviously an oil price at above $100 for a longer period of time could cause, obviously significant pressure upwards in terms of our costs, but so far that's been managed quite well by our teams. Thank you.
Christopher Sheldon
The next question comes from Ulrike Dauer at Dow Jones. Ulrike, please go ahead.
Ulrike Dauer
Good morning. Thanks for taking my question.
Two small questions. In terms of the US import tax, I haven't heard anything whether there was a net-net effect, maybe a tax receipt or a tax burden in the sweet Q figures.
Another question on Russia, correct me if I'm wrong, Beiersdorf doesn't have any own production in Russia, it's just the import as far as I understand. The reason for staying in Russia is protecting the brand rights, is that still up to date, or what's the reason for staying in Russia at this point?
Thank you.
Astrid Hermann
Ulrike, I'll take your first question. Yes, we have received refunds of all the previously paid tariffs for all of our brands, so that's benefiting our year-to-date P&L for sure.
We are obviously paying also tariffs ongoing based on the new tariff environment, so that's happening as well. Was not all in Q3.
We even had some of those refunds happening earlier in the year. To
Vincent Warnery
your second question, we are in Russia since--
Ulrike Dauer
Could you quantify that a little bit?
Astrid Hermann
It was not a material impact to begin with, Ulrike. We had all along said because a lot of our production, to be honest, for our US business is either happening in the US or in our Mexican site, which is still part of USMCA, we've had a pretty insubstantial impact compared to many others.
Ulrike Dauer
Thank
Vincent Warnery
you. You're right.
We have no factory. We stayed in Russia to protect the brand.
We are in Russia since 1906. We know that if we had left Russia, somebody else could have produced NIVEA without us.
We are there to protect the brand and to pay the salaries of our employees, nothing more, nothing less.
Ulrike Dauer
Thank you very much.
Christopher Sheldon
Thank you. That was our last question.
This concludes our conference call. Our Q4 and full-year results 2026 will be released after market close on March 1st, 2027.
We appreciate your interest in Beiersdorf and look forward to seeing you again in early March. Thank you very much.
Operator
Ladies and gentlemen, the conference is now over. Thank you for choosing Chorus Call, and thank you for participating in the conference.
You may now disconnect your lines. Goodbye.