Xylem Inc.
Q3 FY2026 · Earnings Call TranscriptOctober 27, 2026
Operator
Welcome to Xylem's third quarter 2026 results conference call. All participants will be in listen-only mode.
Should you need assistance, please signal a conference specialist by pressing the star key followed by zero. After today's presentation, there will be an opportunity to ask questions.
To ask a question, you may press star then one on your telephone keypad. To withdraw your question, please press star then two.
Please note this event is being recorded. I would now like to turn the conference over to Mr.
Gregory Giometti, Senior Vice President, Investor Relations and FP&A. Please go ahead.
Gregory Giometti
Thank you, operator. Good morning, everyone, and welcome to Xylem's third quarter 2026 earnings call.
With me today are Chief Executive Officer, Matthew Pine, and Chief Financial Officer, Andrea Vanderberg. They will provide their perspectives on Xylem's third quarter results and discuss the fourth quarter and full-year 2026 outlook.
Following our prepared remarks, we will address questions related to the information covered on the call. I'll ask that you please keep to one question and a follow-up, and then return to the queue.
As a reminder, this call and our webcast are accompanied by a slide presentation available in the Investor section of our website. A replay of today's call will be available until midnight, November 10th, and will be available for playback via the Investor section of our website under the heading Investor Events.
Please turn to slide two. We will make some forward-looking statements on today's call, including references to future events or developments that we anticipate will or may occur in the future.
These statements are subject to future risks and uncertainties, such as those factors described in Xylem's most recent annual report on Form 10-K and its subsequent reports filed with the SEC. Please note that the company undertakes no obligation to update any forward-looking statements publicly to reflect subsequent events or circumstances.
Actual events or results could differ materially from those anticipated. Please turn to slide three.
We have provided you with a summary of our key performance metrics, including both GAAP and non-GAAP metrics. For the purposes of today's call, all references will be made on an organic and/or adjusted basis, unless otherwise indicated, and non-GAAP financials have been reconciled for you and are included in the appendix section of the presentation.
Now, please turn to slide four, and I will turn the call over to our CEO, Matthew Pine.
Matthew Pine
Thank you, Greg, and good morning, everyone. Thank you for joining us.
Before I begin, I'd like to welcome Andrea to her role as CFO of Xylem. Her deep knowledge of our business provides important continuity as we continue to execute our strategy.
The third quarter reflected a mixed operating environment. Demand for water infrastructure and technology remains strong, which was evident in our order performance during the quarter.
Across the markets we serve, the long-term drivers of water investment remain firmly in place. Near-term conditions were more challenging, with revenue coming in below our expectations, as certain projects moved more slowly than anticipated and utility customer spending decisions took longer to materialize amid a more cautious and deliberate spending environment.
While those near-term factors affected revenue, our healthy order performance and solid earnings results reflect the greater resilience we've built into Xylem. Through the operational excellence and portfolio actions we've been driving, we're better positioned to navigate short-term variability, while staying focused on long-term growth and value creation.
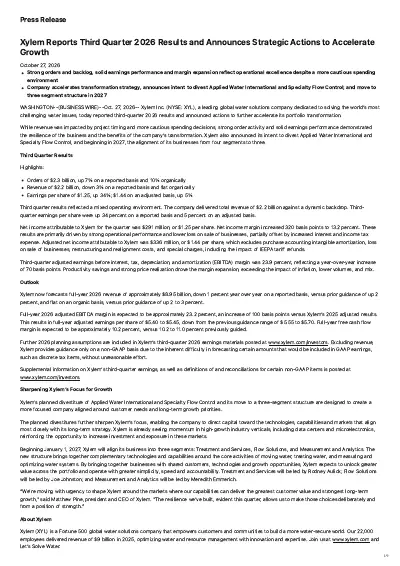
Today, we're taking another step in focusing Xylem on growth. This morning, we're announcing our intent to divest Applied Water International and Specialty Flow Control, which is our beverage and marine business, while also moving from four segments to three beginning in 2027.
These actions are rooted in a simple objective: continue applying our 80/20 principles to sharpen Xylem's focus around the businesses and end markets with the strongest growth and margin potential. The assets we intend to divest are non-core to our long-term strategy or operate in markets that are less aligned with where we see the greatest opportunities for growth.
We believe exiting these businesses strengthens the portfolio and increases our ability to invest in higher-growth, higher-margin markets that are shaping Xylem's future. At the same time, moving to three segments reflects the company we're becoming.
The four-segment structure served us well as we integrated Evoqua and executed the first phase of our transformation. However, the new structure better aligns the company around how customers move water, treat water, and measure and optimize water systems.
It enables us to accelerate value creation, capture synergies across the portfolio, and operate with greater speed and accountability. Together, these actions reflect our determination to proactively advance our transformation plan and position Xylem to accelerate growth, while continuing to expand margins over time.
Most importantly, we're rotating our exposure to higher-growth, higher-margin opportunities. Over the last few years, we've deliberately reshaped our portfolio towards markets with stronger underlying growth, more attractive economics, and compelling long-term demand drivers.
Businesses like Cornell-Roper, WaterFleet, and TriOS have historically grown at rates above our target growth rate, and their additions expand our presence in attractive, high-growth industrial verticals. As we continue rotating the portfolio, proceeds from divestitures and other capital sources will provide additional capacity to execute against our capital allocation priorities and help to further increase our exposure to these higher-growth, higher-margin markets.
We're already seeing tangible evidence of that momentum. Amazon provides a strong example.
What began with digital water replenishment efforts through Xylem Vue in Mexico is now being commercialized globally, and more recently, treatment solutions for data center infrastructure projects at scale. Today, the relationship engages multiple parts of our portfolio and demonstrates the value of our differentiated platform.
Recently, we secured a significant win with a new customer in one of the world's leading semiconductor manufacturers, providing advanced ultrapure water treatment technology for a critical US fabrication facility. This breakthrough win demonstrates our competitiveness in the high-growth microelectronics sector.
These are the types of opportunities that validate our strategy and reinforce our confidence in where we're headed. The long-term demand drivers for water remain intact.
Our portfolio is becoming more focused. Our exposure to higher-growth end markets continues to increase.
The actions we're announcing today position Xylem to accelerate organic growth, while creating additional opportunities for margin expansion and value creation in the years ahead. With that, let me turn the call over to Andrea to discuss the quarter in more detail.
Andrea van der Berg
Thanks, Matthew. Please turn to slide five.
As Matthew mentioned, revenue results fell short of our expectations, largely due to lower MCS book-and-ship volume and timing of WSS capital projects. However, the strength of our operating model enabled us to deliver earnings in line with our guide.
Despite some near-term volatility, overall demand remains healthy. Orders were strong, up 10% versus prior year, driven by water and gas metering strength in MCS and data center orders in AW.
Our ending backlog grew 13% to $5.5 billion versus prior year, sequentially up roughly $200 million, and our book-to-bill for the quarter was above one. Revenue was roughly flat to last year on an organic basis, largely driven by lower MCS metering, WI treatment, and WSS.
Together, these more than offset continued strength in North America transport and data center execution. Through productivity improvements and price, we more than offset the impact of inflation, lower sales volumes, and mix to deliver earnings in line with our guidance.
The team's operational execution delivered quarterly EBITDA margin of 23.9%, up 70 basis points versus the prior year. We also grew EPS 5% compared to last year to $1.44, excluding any benefit from my EPA tariff refund.
Year-to-date, free cash flow was $444 million, slightly below last year, mainly because of working capital and investments in outsourced water contracts. We expect working capital improvements in the fourth quarter.
Net debt to adjusted EBITDA increased to 1.1 times, driven by our opportunistic share repurchases in the quarter. Let's turn to slide six.
Across the segments, the common theme was healthy underlying demand with different revenue conversion dynamics by business. For Measurement & Control Solutions, demand remains healthy, supported by strong customer engagement, a book-to-bill of 1.16, and backlog of approximately $1.3 billion.
Orders increased 30% in the quarter, driven by large water and gas metering awards, with deployments largely scheduled for the second half of 2027 and into 2028. While these orders reinforce our confidence in the long-term growth outlook, we are seeing greater caution in shorter-cycle demand.
Affordability pressures have weighed on electric metering are now extending into water metering purchases. Although these purchases are generally funded through utility operating budgets, replacement timing is more discretionary than mission-critical repair and maintenance activity in water infrastructure.
As utilities continue to manage inflation, interest rates, and affordability concerns, some customers have slowed the pace of these purchases. We continue to believe the issue is pace rather than demand.
Customers remain committed to these investments in our strong value proposition, but are progressing more deliberately than prior periods. Revenue was down 5% on a tough compare with 11% growth last year, driven by softness in electric metering and analytics.
EBITDA margin of 24.5% was 270 basis points higher than the prior year, driven by favorable productivity, price, and the divestiture of international metrology, partially offset by inflation, volume, and mix. In Water Infrastructure, orders were down 1% in the quarter, driven by delays in treatment order intake and continued China headwind, partly offset by strength in transport orders in the Americas, where opex-funded demand remains healthy.
Revenue was down 1%, as growth in transport was more than offset by lower treatment revenue, reflecting 80/20 walk-away actions and China headwinds. EBITDA margin for Water Infrastructure of 26.2% increased 180 basis points, with productivity and price more than offsetting inflation, volume, and investments.
In Applied Water, orders grew 15% and book-to-bill was above one, lifted by data center wins and strength in Americas commercial business. Data center orders in Q3 were again up over 200%.
Revenue grew 9% versus the prior year, primarily driven by strength in US commercial buildings, including data centers. EBITDA margin declined 40 basis points against a strong prior-year quarter, as inflation, mix, and growth investments more than offset productivity, volume, and price.
Our planned divestiture of Applied Water International and Specialty Flow Control will strengthen the financial profile and durability of Xylem, as these two businesses represent roughly 9% of Xylem revenue on a run-rate basis, but less than 5% of company EBITDA, and reduces our exposure from China from approximately 2% of Xylem revenue to 1%. This divestiture supports our continued strategic portfolio rotation towards margin-accretive, high-growth industrial verticals.
In Water Solutions and Services, demand remains healthy. Orders increased 6% in the quarter, led by continued strength in capital.
Funnel activity remains strong across capital and services. Revenue declined 2% year-over-year.
Certain large capital projects ramped more slowly than anticipated, and we're comparing against a prior-year quarter that grew double digits on one-time service and capital work. We view this as an issue of timing rather than demand.
Segment EBITDA margin was 24.9%, down 140 basis points versus the prior year, driven by inflation, lower volume, and mix, partially offset by price and productivity. Now, let's turn to slide seven for our updated full-year and fourth quarter guidance.
As we've discussed, underlying demand remains healthy, as reflected in our orders and backlog. In the near term, however, demand is converting to revenue more slowly than anticipated.
In municipal markets, affordability pressures are leading some utilities to defer more discretionary purchases. We stay close with our utility customers and remain confident that federal funding is not a major factor.
In industrial markets, demand is solid, but some large capital projects are ramping more slowly than we anticipated. As a result, more of our backlog is now scheduled to ship in later periods.
With that, we're lowering our full-year revenue guidance to reflect lower revenue conversion in MCS and WSS. Based on our current visibility in both water and electric metering markets, MCS is expected to decline modestly on a sequential basis in the fourth quarter and stabilize at that level for the near term.
In WSS, we expect a return to low single-digit growth in the fourth quarter, an improvement from the third quarter, but below our prior expectations as large project timing continues to weigh on revenue. Full-year reported revenue is now expected to be down roughly 1% year-over-year at $8.95 billion, with organic revenue roughly flat to last year versus prior guidance of 2% to 3% growth.
Despite the top-line challenge, our disciplined execution is still expected to result in EBITDA margin of roughly 23.2%, or 100 basis points expansion versus the prior year, driven by productivity and price more than offsetting inflation, as well as investments for growth. As a result, we now expect full-year EPS of $5.40 to $5.45, compared to $5.55 to $5.70 previously.
The reduction reflects lower volume as we continue to hold margins, and remains within our original EPS guidance framework for the year. We now expect free cash flow margin of about 10.2%, at the low end of our prior range, driven by higher interest costs from financing the Cornell-Roper acquisition and our opportunistic share repurchases.
Now drilling down on the fourth quarter. We anticipate revenue will be down roughly 5% on a reported basis and down 1% to 2% organically.
We expect fourth quarter EBITDA margin to be roughly 24.5%, which is up 130 basis points, driven by price realization and productivity gains. We expect these results to yield fourth quarter EPS of $1.39 to $1.44.
While more of our backlog is now scheduled to ship in later periods, we exited the third quarter with strong demand indicators, and remain confident in our competitive position. With that, please turn to slide eight, and I'll turn the call back over to Matthew for closing comments.
Matthew Pine
Thanks, Andrea. The long-term demand drivers for our business remain strong.
Water challenges continue to intensify, infrastructure needs continue to grow, and customers remain focused on reliability, resilience, and sustainability. While near-term spending decisions have become more cautious, our customers continue to tell us the same thing: the need to invest in water infrastructure, resilience, and efficiency has not changed.
At the same time, Xylem is fundamentally a stronger company than it was just a few short years ago. We've strengthened operations, sharpened the portfolio, and built greater resilience across the business.
The actions we're announcing today represent the next step in that journey. They further focus Xylem on the businesses, technologies, and end markets where we see the strongest opportunities for growth and value creation.
We remain confident in our strategy, confident in our positioning, and confident in our ability to create long-term value as these opportunities continue to unfold. With that, let's open up the call for your questions.
Operator
We will now begin the question-and-answer session. To ask a question, you may press star then one on your telephone keypad.
If you are using a speakerphone, please pick up your handset before pressing the keys. To withdraw your question, please press star then two.
At this time, we will pause momentarily to assemble our roster. The first question today comes from Mike Halloran with Baird.
Please go ahead.
Mike Halloran
Hey, good morning, everyone.
Matthew Pine
Hey, good morning, Mike.
Mike Halloran
Hey, thanks, and welcome back, Andrea. A couple questions here.
First, maybe help just drill in more with the dichotomy you're seeing between what was a good order patterns, the more broad-based commentary of decent underlying strength with some of the air pockets you're seeing in the short term in terms of whether it's conversion timing or just some of the softness in the utility spend given some of the inflation and in spend challenges. How does that play out as we work into next year?
Are we going to be seeing some softness emerge in the front half versus back half? When does this type of thing normalize as far as you're concerned?
Just kind of any contrast, any context on the contrast between those two points that you've been making.
Andrea van der Berg
Thanks, Mike. We had, as you mentioned, we had really strong orders in Q3, and that was primarily driven by MCS, as well as data centers in Applied Water.
Overall, though, because of the timing that we're seeing on MCS orders, especially on the book-to-bill portion of the metering business, that tends to be more discretionary, although we won significant projects in Q3 that drove that orders growth. However, those projects are slated for the end of 2027 going into 2028.
As well with WSS, we saw great demand, we had a strong funnel, 6% orders growth in WSS, and WSS drove the biggest portion of that 200 million of sequential backlog growth. However, that WSS tends to be lumpier, and some of those projects were booked either at the end of Q3, and we still have a strong funnel going in to Q4.
In general, it's about timing of when those WSS capital projects support growth then going into next year. I'll hand it over to Matthew to give a broader view of revenue going into 2027.
Matthew Pine
Thanks for the question, Mike. Just elevating into thinking about '27 from a revenue perspective, I'd frame revenue into two buckets.
The areas where we have strong visibility to growth, and I would say the other areas is where we have timing is the main variable. On the growth side, we continue to see momentum in AI-related infrastructure and data center orders.
Still, I'd say, relatively small, but growing quickly, supported by a stronger growth profile in Applied Water than we've historically described. You can think about that in '27 as being Applied Water historically above where we typically been.
Also, we feel really good about Water Infrastructure. Transport remains very durable given the break-fix nature of the business.
In treatment, we're lapping much of the 80/20 headwind and China headwind from this year. That really disproportionately affected 2026.
The second bucket, as we think about 2027, where the watch item is and remains variable, is primarily in MCS and WSS, as Andrea was talking about in Q4. In MCS, we have strong order activity, projects were scheduled for the back half of '27 and into '28, but the shorter-cycle water metering business remains a little softer.
In WSS, the funnel and orders are strong. The pace of large project conversion will really determine the growth cadence.
We have a nice step-up from Q3 to Q4, and we expect that momentum to carry into '27 as we exit Q4 of this year. In general, I'd say we like the underlying setup for '27, but we're going to give you a more precise framework when we provide guidance in February.
Mike Halloran
Thanks for that. Then, maybe just some thoughts on where you are in terms of the portfolio journey from here.
Obviously, a couple non-core divestitures, you're re-segmenting. The re-segmentation actually makes a lot of sense.
Let's break that into two buckets. One, how much more larger-scale divestiture opportunity do you see from here?
Two, when you think about the more run-rate 80/20 revenue work that you've done, the two points of headwind this year, how does that second bucket then translate on a forward basis? Are we towards the end of the journey on either of those two different buckets?
Maybe just kind of help with the thought process from here.
Matthew Pine
Maybe on the first, just at a high level, we continue to evaluate the portfolio to make sure it aligns with our long-term strategy and the needs of our customers. I would say at the moment, we're focused on the divestitures we announced this morning around Applied Water International and Specialty Flow Control, but it's something that we obviously look at pretty consistently.
Obviously, we look at that with the board, and we'll continue to do that as good hygiene. In terms of 80/20, maybe I'll just elevate and talk about the broader transformation of Xylem first, and then get a little bit more to double-click into details.
But 80/20 is really part of a broader transformation of Xylem. Phase one has really been about executing over the past 3.5 years on improving our operating model.
I've talked a lot about that's very comprehensive. That's our culture, our processes, systems, and structure.
Maybe just a couple of things I'd like to point out that are I think really good testament to our success there is, I'll start with safety because we always start with safety and quality. Our safety injury frequency rate is down 34%, very significant, and approaching world-class.
Our on-time performance is 700 basis points of improvement. Our days of inventory outstanding has improved by 22%.
Our margins are up 600, and our SKU count is down 40%. So, 80/20 is a part of a broader operating system, but it's not all that we do to execute on our transformation.
Obviously, we'll continue to do that, but we're really focused on phase two and three of our journey, and that's about building the growth engine of the company, and that's about optimizing our portfolio. As you can see that in the actions that we announced today.
As far as 80/20 goes specifically, it's well embedded into the functions, the segments, and the divisions of our company, now going into year four. That's led centrally by Tom Pellette, our Chief Operations Officer.
We plan to be at our peak walk-away this year at 2%, and into '27, we see it as probably 50 to no more than 100 basis points of headwind. Obviously, we'll continue to see margin improvement from that.
Mike Halloran
Thank you. Appreciate it.
Mm-hmm.
Andrea van der Berg
Thanks, Mike.
Operator
The next question comes from Andy Kaplowitz with Citigroup. Please go ahead.
Andy Kaplowitz
Good morning, everyone. Morning, Andy.
Matthew Pine
Morning, Andy.
Andy Kaplowitz
Andrea, congrats on the role. Maybe just back to MCS and how to think about it as you go into '27.
I think, Andrea, you mentioned a lot of MCS projects to burn later in '27. That's fine, but, obviously, as you've talked about, have a pretty big backlog.
If we break down water versus electric metering, any more color you can give on the respective end markets and when you might see that book-and-ship start to reaccelerate? Is some of this maybe election uncertainty?
How do you think about all that?
Andrea van der Berg
Thanks, Andy. As we mentioned, we had really strong orders in MCS, up 30%, but the backlog is still down or it is down year-over-year.
When you peel that back, water metering within our backlog is up by 13% and it's sequentially increased as well. We're seeing really good strength on our water metering business, but the book-and-bill portion of that business has been softer, and it's for projects that are more later dated into 20 end of 2027 into 2028.
We'll continue to monitor the book-and-ship business portion of the business and how those projects, whether they accelerate earlier or deferred later. Which is why we said overall it's strong demand, but it's pushing out.
To look to MCS revenue is sequentially around Q3 and Q4 levels going into the first half of next year. Then it will all be about whether those projects stay on track and the book-and-ship business recovers and accelerates from there.
Andy Kaplowitz
Helpful. Then, Matthew, Andrea, maybe a similar question on WSS.
I know you've mentioned delays, but obviously a lot of that business seems to be well positioned, given the markets it serves. Why are you seeing these delays, and what's the unlock to sort of get these larger projects going to go forward?
Is it rates exposed? What's going on sort of in these industrial markets?
Because I would think you should see acceleration at some point here.
Andrea van der Berg
Thanks, Andy. We are seeing benefits from the industrial cycle.
It shows up first in our pipeline and then orders and then later in revenue. Our WSS business has a portion of capital projects that tend to be lumpier.
As I mentioned, the majority of our sequential backlog improvement was within WSS. It's just all about whether those orders get converted into revenue, as well as some of the later push-outs of some of these projects in Q3 also impact Q4.
Which is why we previously guided WSS high single digits in Q4 and now that will be low single digits because of the timing of these larger capital projects. Overall, we're still seeing very strong demand, as Matthew mentioned.
We highlighted two large customer projects, and we expect WSS over the long term or in short term, medium term to be at mid-single-digit growth rate.
Andy Kaplowitz
Helpful. Thank you.
Operator
The next question comes from Joe Giordano with TD Cowen. Please go ahead.
Joe Giordano
Hey, guys. Good morning.
Matthew Pine
Hey, good morning, Joe.
Joe Giordano
Maybe start on just the resegmentation. We've had some moves in the past.
I just want to understand from a customer standpoint versus a Xylem internal standpoint, because I thought moving the rental, like the dewatering stuff into WSS was to keep that whole segment kind of run on this service, rental-type basis. Now bringing in the treatment stuff, which is more capital sales seems a little bit against that.
I'm thinking from a utility standpoint, you were probably buying Flygt pumps and then treatment stuff, and now you're buying it from two different segments. Is it complicated in some ways as well, even though it's streamlined down to three segments from four?
Matthew Pine
No, I think it's a natural evolution, Joe, of what we've been working on. We were highly matrixed before and you'd have a lot of finger pointing and not a lot of accountability.
Into, like I said in my prepared remarks, four segments, 16 divisions with much more accountability. That's worked well for us as we integrated Evoqua.
We did, to your point, make the dewatering business integrate into WSS. That will not change.
Really, taking a step back too, when we looked at that transformation, 80% of our customers buy from one division. So 20% buy from multiple divisions, but a lot of them don't even know it.
When you think about water infrastructure, transport and treatment are very different. You've got mechanical kind of electromechanical pumping, and then you've got biological treatment.
Those are very different customers within a utility, and sometimes they're not even the same utility in a market. We have a process when we do have overlap, where we do have internal lead sharing.
We built an enterprise selling team over the past two years that also works at kind of an enterprise level calling on these types of customers when we can have a more holistic solution-driven conversation, but that's really the 20 of our business, if you kind of put it in 80/20 terms. The new structure really just better aligns the company on how customers move water, treat water, measure water, optimize water systems.
For me, it's bringing together shared technologies, Joe, and end markets, and it enables us to unlock greater value across the portfolio and operate with greater speed and accountability and a sharper focus on growth. Maybe just a couple of examples as I wrap this up.
As we pivot to more industrial exposure, we do see a lot of overlap in WSS and WI today. Within WI and Applied Water.
A good, maybe example of this, it's evidence in the Cornell-Roper deal. I'd walk into meetings and we would have two and sometimes three segment presidents in the meeting.
As we look at our pipeline, we're cultivating targets where there's multiple segments involved. By aligning this way, it's just going to make us much more efficient as we execute on our portfolio and get better focus.
The second thing I would say is there is significant R&D synergies when you think about a treatment portfolio and a transport flow portfolio. Where we align pumping and treatment into discrete segments.
There's operating synergies as well. For example, our castings, a lot of that is outsourced in Applied Water today.
By bringing flow together in our pumping business, we think there's a lot of in-source opportunities that give us more economies of scale. The last thing, which is a benefit from this as well, is eliminating the WI segment support cost.
There's a lot of, I would say, outweighing very positive than any of the negative of moving this way. Our customers actually will be much more benefited by this structure.
Joe Giordano
Then, just a follow-up, Matthew, you mentioned you're excited about the former Water Infrastructure growth into 2027. Orders look like they're going to be flat to down this year, so that kind of surprises me.
What historically, normally orders kind of at that rate this year, it kind of means growth pressured next year? Then, Andrea, if you could just comment on the margin profile of the stuff you're booking into MCS now versus what you're currently putting up in margins for that segment.
Thanks, guys.
Matthew Pine
No problem. In terms of Water Infrastructure, transport remains very healthy.
I talked about 80/20 walk-away in China. That's been a big drag on some of the orders.
We lap that in Q4. I have meetings with the treatment team, and in looking at our backlog coming into Q4, we feel really confident that we can get WI to mid-single-digit growth, but even treatment into potentially mid to high single digits as we exit the year.
I think there's really good momentum. There has been some delays in terms of those projects maybe being pushed out four, six, eight months.
Some of that has to do with how the utilities are bidding this projects, kind of contractor manager at risk, which is kind of making them go a little bit slower. In general, we see momentum there as we exit the year.
Andrea van der Berg
Joe, on the MCS margin profile, one of the biggest drivers of the margin profile that will benefit MCS is on the international metrology divestiture. Then also, as I mentioned, on water projects, the water metering backlog was up sequentially and it's up year-over-year, we continue to see strength on water metering.
It's just that book-and-ship business in the near term. Mix will be the biggest driver or variable for our 2027 margin because of the strong incrementals in water.
Again, we have strength in our backlog year-over-year and sequentially within MCS on the water metering business.
Joe Giordano
Thanks, guys.
Matthew Pine
Thank you.
Operator
The next question comes from Nathan Jones with Stifel. Please go ahead.
Nathan Jones
Good morning, everyone.
Matthew Pine
Hey, good morning, Nathan.
Nathan Jones
I guess I'll do the data center questions. I think you talked about 3Q revenue or 3Q orders up 200% year-over-year.
I think, Matthew, you've talked about exiting the year at 2% of revenue from data centers. Can you just talk about I guess what the expected growth there is in 2027, can this add a point of growth, a couple points of growth to the 2027 outlook?
Matthew Pine
Maybe just at a high level. We're definitely excited about the opportunity.
We're staying disciplined in terms of how we're investing. We're trying to invest behind demand versus way in front of it.
We're not building a ton of capacity ahead of what we see, but we are adding capacity, and that's going to have a little bit impact on margins in the short term, but normalizing back to kind of our standard margins for the company. As you said, the data center orders are up 200% for Applied Water again in the quarter.
We're seeing broader opportunities across the entire portfolio, especially with our expanding relationship with Amazon that we mentioned in the prepared remarks. We do, to your point, expect data centers to exit at 2% of Xylem revenue on a run-rate basis.
We clearly see it as a attractive growth opportunity in '27. I think we'll be able to size that better in February, but, just as I was making my comments around our 2027 revenue just a moment ago, Applied Water is definitely going to be at a much higher growth rate than we've been signaling in the past on that business, is benefited by the data centers.
Nathan Jones
Got a follow-up on data centers. It appears to me that a bigger opportunity over time would be around recycle and reuse of water and potentially build-own-operate projects at data centers.
Are you at a point where you're having discussions with customers about things like that? Can you talk about any of the opportunities over what I would imagine would be a few years, you could go retrofit existing data centers that are liquid cooled.
Just any thoughts you've got around that.
Matthew Pine
At a high level, there's not a lot of water consumption at the data center itself, the direct usage, especially as a lot of those are being converted to air-cooled chillers. That's not really a huge benefit.
Now, there are opportunities that we've seen and we're taking advantage of where a data center can't get municipal water because, for whatever reason, could be location, it could be that the municipal water doesn't give them a permit because they expect them to use too much water. We would take surface water into the data center and treat that.
That's more an exception than the rule. Really what we're seeing the benefit of kind of the I'd say the broader AI ecosystem build-out is on semiconductor chip fab, and I mentioned we've had a few wins here recently with some new customers in that area.
The one that is on the horizon that's probably not '27, but for sure it's going to be '28, '29, and '30 is power. Power is where the most water is used in the AI ecosystem.
We're positioned very well there from the legacy Evoqua business, especially on nuclear. As those projects come online, both in Europe and in the US, we're well positioned to take advantage of that growth.
Nathan Jones
Thanks for taking the questions.
Matthew Pine
Thank you.
Operator
The next question comes from William Grippin with Barclays. Please go ahead.
William Grippin
Excellent. Thank you for the time and the opportunity.
Just wanted to dig in here a bit more on Andrea, I think you mentioned affordability concerns. What product segments, I guess within that context, do you really consider or sort of see as being more discretionary?
Then you did reference funding in your prepared remarks. As we look into next year, what are you seeing in terms of the overall funding picture and what have you been hearing from your municipal customers?
Matthew Pine
Thanks for the question. I'll take that.
I would say in general, let me just elevate at a high level. I would say that municipal demand remains, I'd say, fundamentally healthy, and there's obviously, all of the secular drivers that are driving that.
I would say at the same time, though, we are seeing caution in some areas on muni spending. I wouldn't characterize it is as a broad-based slowdown, per se, but I do have several conversations with CEOs over the course of, each quarter.
In my recent conversations with utility CEOs here in the US, I would say that they are more cautious about the general economy than they were a quarter or two quarters ago. They're seeing, increases in construction costs, energy costs, financing costs, along with a little bit of, spillover from energy of pushback on customer rate increases in some areas.
I wouldn't say it's it's holistic, but in in some areas. That is leading to a deferral of spending on things that are not immediately operational in need.
For us, that really shows up in mainly in metering, both kind of the short-cycle replacement nature of the metering that we do, as well as some project push-outs, where utilities kind of have flexibility on timing. I would say, treatment demand remains really strong, but I as I mentioned earlier to Joe, projects are taking just a little bit longer.
In some cases, due to contractor availability, they're tied up on AI jobs, for example, or they're re-scoping them due to inflation, or I mentioned before, they're bidding them as contractor manage- manager at risk, which takes more time. I would say the last thing I would wrap up on, there's been some commentary that I'd like to, get out in front of here is and I think it's important to keep it in context, that our US, the Xylem US utility capex exposure is less than 10% of our revenue.
The majority of our utility exposure is rep- repair and replace demand, and that can't be deferred. You really see that show up in our transport orders and our transport business.
That's a that's a little bit of a state of the muni business in the US as as we see it.
William Grippin
Great. Appreciate that color.
Just wanted to ask my follow-up here on if you could provide a bit more color on the customer mix and exposure for the two businesses that you announced plan divestiture for today. Could you sort of scope or quantify to what extent those could be margin-accretive divestments?
Andrea van der Berg
Thanks, Will. Overall, the planned divestiture will improve our portfolio's mix, resilience, growth, and margin profile, while, again, sharpening our focus on higher-growth and more attractive verticals as part of our portfolio rotation.
As we highlighted, these two businesses represent 9% of Xylem revenue, but less than 5% of Xylem EBITDA. From a revenue growth profile, they're negative this year, with our forward expectation that will be well below our target framework.
It also, again, reduces our exposure to China. This year, China is 2% of Xylem revenue, and after the divestiture, China will be 1% of revenue.
From an EBITDA margin perspective, these two businesses are dilutive to EBITDA margin, while Applied Water Americas margin is accretive to Xylem overall margin.
William Grippin
Very helpful. Thanks very much.
That's all for me.
Matthew Pine
Thank you.
Andrea van der Berg
Thank you.
Operator
The next question comes from Steve Volkmann with Jefferies. Please go ahead.
Steve Volkmann
Yes, it was. Thank you.
I would just want to follow up on that last question. Are there also some opportunities sort of stranded costs for these two businesses that you might be able to get at over time, and what might that look like?
Andrea van der Berg
No, great question. As reminder as well, we'll be closing the Cornell-Roper acquisition in Q4, too, which will be adding additional revenue, and that's accretive to our growth and margin as well.
Then we continue on our transformation. We will still continue to have benefits from structural cost actions as 80/20 continues to be embedded in our operating model.
Steve Volkmann
Great. Then Matthew, I think you mentioned this in your prepared remarks around having capital to sort of deploy, but I'm curious how you're thinking about replacing the EBITDA that's lost from these divestitures.
Do you already have stuff in the pipeline? You're going to be looking for something and you'll maybe just take your time on that or maybe you buy back some stock in the meantime?
Just curious how you're thinking about that kind of EBITDA impact as you divest these things.
Matthew Pine
Yeah. Maybe just elevate to kind of our priorities in terms of capital deployment.
The first is going to be organic investment, then, to your point, on M&A. From a bolt-on perspective, looking to move that more towards high-growth verticals.
We're going to grow dividend in line with earnings, and then at the end, we're going to use what's left for opportunistic buybacks. To Andrea's point, we're going to close on Cornell-Roper here by the end of the year.
By then, we'll be managing about 1.5 to two times leverage. From a proceeds perspective, we'll take the proceeds from Applied Water, Specialty Flow Control divestitures, and it'll give us some more capacity to execute against a healthy pipeline, which will allow us to accelerate the strategic rotation of our portfolio.
Really the proceeds are not going to come into play till the end of '27, beginning of '28. We have time to, a, work on the business, to your first question, and then we've got time to plan and continue to execute against our healthy pipeline on acquisitions.
Steve Volkmann
Super. Thanks, I'll pass it on.
Matthew Pine
Thank you.
Operator
This concludes our question-and-answer session. I would like to turn the conference back over to Matthew Pine for any closing remarks.
Matthew Pine
We'll wrap it up there. Thanks for your questions today, and thanks to everybody who joined on the call.
A lot of our colleagues join these calls, and just want to say to our colleagues, really appreciate all you're doing to transform Xylem and make it a best-in-class company. As always, we appreciate your interest in Xylem.
All the very best.
Operator
The conference has now concluded. Thank you for attending today's presentation.
You may now disconnect.