Yatra Online, Inc.
NNASDAQ:YTRAQ4 FY2026 · Earnings Call TranscriptMay 25, 2026
Operator
Hello everyone, and welcome to Yatra's fiscal fourth-quarter and full-year 2026 financial results call for the period ended March 31st, 2026. Today's call is hosted by Yatra's co-founder, Dhruv Shringi, Yatra's CEO, Siddharth Gupta, and Yatra's CFO, Anuj Sethi.
The following discussion, including responses to your questions, reflect the management's views as of today, May 25th, 2026. The company does not take any obligation to update or revise the information.
Before they begin their formal remarks, please be reminded that certain statements made on this call may constitute forward-looking statements, which are based on Yatra management's current expectations and beliefs and are subject to several risks and uncertainties that could cause actual results to differ materially. For a description of these risks, please refer to Yatra's filings with the SEC and their press release filed earlier this morning on the IR section of the Yatra website.
With that, let me turn the call over to Yatra's co-founder, Dhruv Shringi. Dhruv, please go ahead.
Dhruv Shringi
Thank you, operator, and good morning, everyone. Welcome to Yatra's full-year 2026 and Q4 2026 earnings call.
Fiscal 2026 has been a landmark year for Yatra. Despite some very significant macro headwinds that impacted 3 out of the 12 months of the year, it is the most profitable year in the company's 20-year history.
This strong performance is a testament to the resilience of our business model, our commitment to innovation, the balance in our revenue mix, the quality of our corporate franchise, and the dedication of our teams. I'm very proud to announce our FY 2026 results.
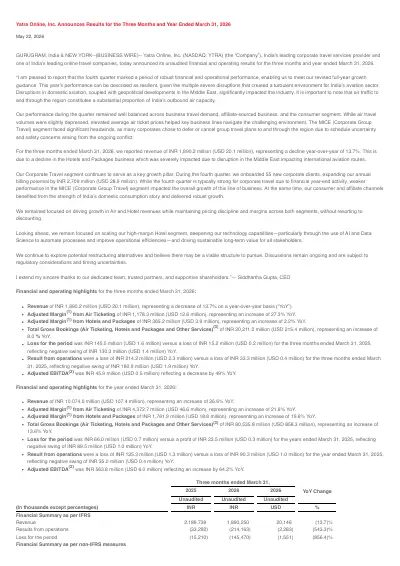
Our revenue from operations grew 27% year-over-year to INR 10,074 million, or approximately $107 million, while revenue less service cost, which is our gross margin, increased to INR 4,801 million, a growth of 22.6% year-over-year. Adjusted EBITDA grew to INR 564 million, or approximately $6 million, a growth of 64% year-over-year, reflecting strong operating leverage.
On the corporate customer acquisition front as well, we added during FY 2026 163 new corporate customers with annual billable value of approximately INR 9,568 million, or about $102 million, up from 148 customers and INR 7,475 million, or $80 million, in FY 2025. As Siddharth will delve further in his remarks, you will see that this number has been increasing on a quarterly basis, underscoring the continued traction in our enterprise travel business and the strength of our go-to-market execution.
Online penetration of corporate travel is still less than 25% in India in the managed business travel segment, and as the market leader, we are best positioned to capitalize on this as the industry moves up the online penetration curve. We have demonstrated over the years that we are not only have the ability to acquire customers, but with a retention rate of almost 97%, have the ability to retain them for a very long lifetime value as well.
In our assessment, the current macro environment driven by a conflict which has impacted energy prices and disrupted travel in the Middle East and more broadly international travel does not reflect a structural change in the underlying travel demand ecosystem. It is a short-term blip which the industry will tide over as soon as normalcy returns.
Corporate travel demand in India continues to remain resilient, and we expect recovery momentum to strengthen meaningfully in the second half of the year, driven by revenge travel, just like we witnessed in the years following COVID. That said, the escalating conflict significantly impacted our MICE and international corporate travel business, weighing on the overall Q4 results.
Several Q4 MICE and international corporate group travel bookings were either cancelled or deferred into FY 2027. Barring the impact of this, it was quite likely that we would have reported stronger results ahead of last year's performance.
The current conflict and the balance of payments challenge has also heightened the government's focus on domestic tourism as a strategic pillar. The infrastructure build-out in rail and aviation and even the domestic highway network bodes well for domestic tourism.
Yatra, given its market-leading domestic hotel supply, we believe is extremely well-positioned to capitalize on this trend. We have enhanced our API infrastructure framework, and our migration onto the Google Cloud Platform has significantly improved our ability to distribute our hotel content to a large network of domestic and international travelers.
This is a highly margin accretive business for Yatra and one that we expect to scale up further in the coming years. From a quarter's perspective, despite the headwinds, we reported resilient performance in Q4, especially in our core air and hotel segments.
Gross bookings grew 8% year-over-year, air passenger volumes were up 9.6% year-over-year, roughly 2x the industry growth rate, reflecting continued market share gains. Our hotels business continued its strong momentum with room nights growing 36% in the quarter and gross bookings growing 9% despite the significant disruption in MICE.
Total transactions increased 15.2% year-over-year, a strong indicator of platform activity and engagement. Our corporate business added 55 new clients during the quarter with an annual billable potential of INR 2,709 million, or approximately $29 million, which is higher than the 40 closures worth INR 2,234 million, or approximately $24 million, in Q3, demonstrating the strength of our sales engine even through a challenging environment.
While there is a macro disruption outside our control, more importantly, the underlying demand from our corporate customers remains intact, and we expect a meaningful portion of the deferred business to return as conditions normalize. Structurally, the outlook for India's travel and corporate mobility sector remains compelling.
India continues to be the fastest-growing major economy, with strong investment flows across manufacturing and the outsourcing-driven business travel demand. Based on the strength of our corporate customer base, our industry-leading hotel supply, and our AI-enabled corporate travel technology, we remain confident of our medium-term growth CAGR of revenue less service cost of 20% and adjusted EBITDA of 30%.
With that overview, let me hand you over to Siddharth to walk you through the details of our performance. Siddharth?
Siddharth Gupta
Thank you, Dhruv, and good morning, everyone. The larger headline is that Yatra delivered its strongest performance in financial year '26 despite a volatile macroeconomic and geopolitical backdrop.
In FY 2026, we delivered RLSC, which is revenue less service cost, or gross margin, growth of about 22.6%, while adjusted EBITDA grew 64.2% year-on-year, reflecting a strong operating leverage as well as disciplined cost control. This is particularly notable given FY 2026 reflected only 9 months of full operations, underscoring both the strength of execution during the period while maintaining financial discipline.
Another achievement worth emphasizing is the balanced nature of this growth across segments and lines of businesses. Let me start by taking you through the segment performance.
Across both air and hotels, Yatra strengthened its competitive position. The air segment delivered a healthy TTV growth of 12% for the year to INR 61,874 million from INR 55,273 million while maintaining margin discipline, with passenger growth outpacing industry levels throughout the quarter and the full year while maintaining margin throughout the year.
A point to highlight is our air margins have steadily improved from approximately 2.7% in financial year '24 to nearly 4% in financial year '26, reflecting a structural improvement in the quality of our business mix. We remain one of the very few players in this space to consistently expand air margins despite intense competitive pressure across the sector.
The hotels and packages business also gained strong momentum, led by strong TTV growth of 27%. With the government's continued push towards domestic tourism and infrastructure-led travel growth, our extensive hotel supply footprint across India positions us well to capture demand across both major metropolitan markets and emerging Tier 2 and Tier 3 cities.
Moving now to across lines of businesses, during financial year '26, Yatra added 163 new corporate customers with an annual billable value of approximately INR 9,568 million, which would be approximately $102 million, up from 148 customers and INR 7,475 million, which was close to $80 million, in financial year '25. This underscores the continued traction in our enterprise travel business and the strength of our go-to-market execution.
It is important to note that corporate wins typically take 3 to 6 months to go live and ramp up to their full trading potential. This provides strong visibility into incremental revenue contribution over the coming year.
Beyond our large enterprise wins, we continue to see significant white spaces in India's mid-market corporate travel segment, which remains substantially underpenetrated online. To capture this opportunity, we invested in building a dedicated mid-market sales team during Q3, with early contributions already visible in Q4.
Given the scale of the untapped market, we believe this segment can become a meaningful incremental growth driver for our corporate business over the medium term. Coupled with the fact that our corporate business continues to demonstrate exceptional stickiness with customer retentions consistently above 97%, this positions us well for continued strong performance in our corporate segment.
Our consumer business performed well through the year as well, demonstrating the inherent resilience of domestic consumer spending. The diversified nature of our operations and multiple revenue levers enabled us to navigate periods of disruption while continuing to deliver resilient full-year performance.
During financial year '26, Yatra benefited from incremental demand from newly signed affiliates and partnerships, helping us gain both air and hotel market share while further improving margins. This highlights the strong scalability of our API-led distribution model, which has emerged as an important growth driver.
Combined with our extensive domestic hotel supply network, it positions us to accelerate growth in the periods ahead. We are seeing strong traction in API-led distribution, with travel agents, affiliates, and B2B partners increasingly sourcing hotel inventory through the Yatra platform.
This allows us to scale transaction volumes efficiently while preserving margin discipline. We expect this trend to continue, and any near-term softness in consumer demand during the first half of the year should be mitigated as the year progresses.
Yatra delivered a resilient performance in Q4, with gross bookings growing 8% year-on-year, air passenger volumes increasing 9.6% year-on-year, approximately double the industry growth rate, while total transactions rose 15.2% year-on-year. The quarter was impacted by the conflict-related disruption, which slightly depressed air volumes and had a more pronounced impact on several MICE and international corporate group travel bookings, a number of which were either cancelled or deferred into financial year '27.
While the MICE category experienced temporary disruption during the quarter, we are seeing instances where customer preference is shifting from international to domestic programs, partially offsetting the impact. Importantly, we are already seeing signs of recovery, with Q1 run rates currently trending approximately 20% above the Q4 levels.
We continue to view MICE as a structurally attractive category, given its close linkage to corporate reward, engagement, and incentive programs. Over the years, we've built strong execution capabilities and a broad partner network across domestic and international markets, creating a meaningful competitive advantage.
Our gross margin, defined as revenue less service cost, increased 1% year-on-year to INR 1,101 million, or approximately $12 million. Adjusted EBITDA declined 49% year-on-year to INR 46 million, or approximately $0.5 million.
Our corporate business added 55 new clients during the quarter with an annual billable potential of INR 2,709 million, or approximately $29 million, which was higher than the 40 client wins worth INR 2,234 million, or approximately $24 million, in Q3. This demonstrates the continued strength of our sales engine even in a challenging operating environment.
Overall, while the quarter was impacted by geopolitical uncertainty stemming from the West Asia conflict, we remain optimistic about our trajectory, supported by our continued focus on scaling the corporate travel business. The steady addition of new enterprise clients, improving online adoption, and the growing contribution of our hotel business within the corporate segment positions us well to drive operating leverage and deliver gradual margin expansion over the medium term.
Looking ahead, AI and automation remain a core strategic focus area for Yatra. We continue to see encouraging adoption of our AI-powered servicing capabilities across both consumer and corporate channels.
Our continued investments in automation and successful deployment across customer touchpoints reinforce both operational scalability and long-term profitability. Our continued collaboration with Google further strengthens our technology ecosystem and supports product innovation across customer acquisition and servicing.
If past cycles are any indication, periods of market disruption are often followed by a meaningful release of pent-up consumer demand. Accordingly, we expect the second half of financial year '27 to be materially stronger than the first half.
While macro challenges are likely to persist in the first half of the year, we remain optimistic about financial year '27, backed by structural growth in India's travel and corporate mobility markets and Yatra's continued investment in AI technology, customer acquisition, hotel supply, and its B2E platform. As Dhruv mentioned earlier, we remain confident of our medium-term growth CAGR of 20% RLSC growth and 30% adjusted EBITDA growth.
With that, let me hand over to our CFO, Anuj Sethi, to walk you through the detailed financial performance. Thank you.
Anuj?
Anuj Sethi
Thank you, Siddharth. Good morning, everyone.
For the fourth quarter of the financial year 2026, on a consolidated basis, our revenue from operations decreased 14% year-on-year to INR 1,890 million, or approximately $20 million. Our gross margin, defined as revenue less service cost, rose 1% year-on-year to INR 1,101 million, or approximately $12 million.
EBITDA loss increased year-on-year to INR 102 million, or approximately $1 million. For the full year ended financial year 2026, on a consolidated basis, our revenue from operations grew 27% year-on-year to INR 10,074 million, or approximately $107 million.
Our gross margins rose 22.6% year-on-year to INR 4,801 million. Adjusted EBITDA of INR 564 million, or approximately $6 million, representing an year-on-year growth of 64%, while our EBITDA improved to INR 266 million, or approximately $3 million, a year-on-year growth of 31%.
In terms of segmental performance, our air ticketing passenger volume increased 2% year-on-year to 5,395,000, and our gross air booking grew 12% year-on-year to INR 61,874 million, or approximately $659 million. Here gross margin rose 30% from year-on-year to INR 2,449 million, or approximately $26 million, with margins improving from 3.42% to 3.96%.
Under hotels and packages segment, hotel room nights grew 16% year-on-year to 1,936,000. Gross bookings increased 25% year-on-year to INR 16,578 million, or approximately $177 million, while gross margin expanded 34% year-on-year to INR 1,502 million, or approximately $16 million, with margin improving from 8.60% to 9.25%.
On the liquidity front, cash and cash equivalent and term deposit stood at INR 2,512 million, or approximately $26.7 million, as of 31st March 2026. With this, I would like to hand it back to the moderator and open up for question-and-answer session.
Thank you.
Operator
Thank you. We will now begin the question-and-answer session.
Please limit yourself to one question and one follow-up. If you would like to ask a question, please press *1 to raise your hand.
To withdraw your question, please press *1 again. We ask that you pick up your handset when asking a question to allow for optimum sound quality.
If you are muted locally, please remember to unmute your device. Please stand by while we compile the Q&A roster.
If you would like to ask a question, please press *1 to raise your hand. At this time, it appears that we don't have any questions.
I will now turn the call back to Siddharth Gupta for closing remarks.
Siddharth Gupta
Reiterating, structurally, the outlook for India's travel and corporate mobility market remains compelling. India continues to be the fastest-growing major economy, with strong investment flows across manufacturing and GCCs driving business travel demand.
Based on the strength of our corporate customer base, our industry-leading hotel supply, and our AI-enhanced corporate travel technology, we remain confident of our mid-term growth in CAGR of RLSC 20% and adjusted EBITDA of maybe 30%. On that positive note, I would like to thank you all for joining the call.
I hope we were able to address all the queries that you might have. If you have any further questions, you can reach out to our IR partners at ICR.
Thank you once again for participating in this call.
Dhruv Shringi
Thank you.
Operator
This concludes today's call. Thank you for attending.
You may now disconnect.
Siddharth Gupta
Thank you.
Dhruv Shringi
Thank you, operator. Thank you.