ACRES Commercial Realty Corp.
Q4 FY2025 · Earnings Call TranscriptMarch 5, 2026
Operator
Thank you. Good day, ladies and gentlemen, and welcome to the fourth quarter 2025 ACRES Commercial Realty Corp.
earnings conference call. Currently, all participants are in a listen-only mode.
Later, we will conduct a question-and-answer session with instructions to follow at that time. If anyone requires assistance during the conference, please press star, then zero on your touch-tone telephone.
As a reminder, this call is being recorded. I would now like to introduce your host for today's conference, Kyle Brengel, Vice President, Operations.
You may begin.
Kyle Brengel
Good morning, and thank you for joining our call. I would like to highlight that we have posted the fourth quarter 2025 earnings presentation to our website.
This presentation contains summary and detailed information about the quarterly results of the company. Before we begin, I want to remind everyone that certain statements made during this call are not based on historical information and may constitute forward-looking statements.
When used in this conference call, the words believes, anticipates, expects, and similar expressions are intended to identify forward-looking statements. Although the company believes these forward-looking statements are based on reasonable assumptions, such statements are based on management's current expectations and beliefs and are subject to several trends, risks, and uncertainties that could cause actual results to differ materially from those contained in the forward-looking statements.
These risks and uncertainties are discussed in the company's reports filed with the SEC, including its reports on Form 8-K, 10-Q, and 10-K, and in particular, the risk factors section of its Form 10-K. Listeners are cautioned not to place undue reliance on these forward-looking statements, which speak only as of the date hereof.
The company undertakes no obligation to update any of these forward-looking statements. Furthermore, certain non-GAAP financial measures may be discussed on this conference call.
Our presentation of this information is not intended to be considered in isolation or as a substitute to the financial information presented in accordance with GAAP. Reconciliations of non-GAAP financial measures to the most comparable measures prepared in accordance with generally accepted accounting principles are contained in the earnings presentation for the past quarter.
With me on the call today are Mark Fogel, President and CEO; Andrew Fentress, Chairman of ACR; and Eldron Blackwell, ACR's CFO. I will now turn the call over to Mark.
Mark Fogel
Good morning, everyone, and thank you for joining our call. Today, I will provide an overview of our loan operations, real estate investments, and the health of the investment portfolio, while Eldron Blackwell, our CFO, will discuss the financial statements, liquidity condition, book value, and operating results for the fourth quarter 2025.
Of course, we look forward to your questions at the end of our prepared remarks. The ACRES team remains focused on executing on our business strategy by investing in high-quality CRE loans, actively managing the portfolio, and growing earnings for our shareholders.
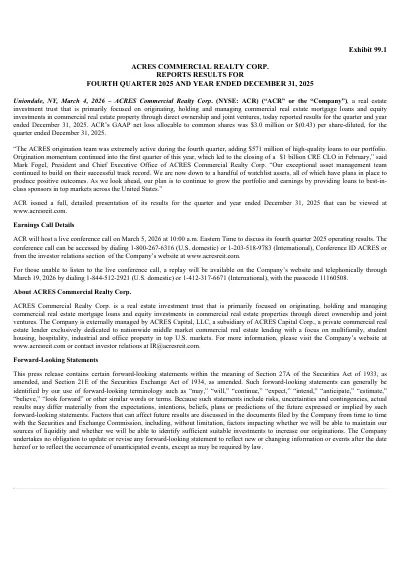
In the fourth quarter 2025, we closed new commitments of $571 million, offset by loan payoffs and net unfunded commitments totaling $127.2 million, producing a net increase to the loan portfolio of $443.8 million. The weighted average spread on newly originated loans is 2.83%.
New loan production in the fourth quarter of 2025 and in the first quarter of 2026 put us in a position to structure and price a new CRE securitization in January. On February 12th, we closed ACRES 2026-FL4, a $1 billion deal that has leverage of 86.5% and a weighted average debt spread of 1.68%.
The weighted average spread of the floating-rate loans in our $1.8 billion commercial real estate loan portfolio is now 3.35% over one-month term SOFR rates. Portfolio generally continues to perform, demonstrating sound and consistent underwriting and proactive asset management.
The company ended the quarter with $1.8 billion of commercial real estate loans across 53 individual investments. At December 31st, our weighted average risk rating was 2.7, a decrease from 3.0 at September 30th, and the number of loans rated 4 or 5 was 10, down from 13 at the end of the third quarter.
Portion of our CRE loan portfolio rated 4 or 5 based on the company's economic interest was 17% at December 31st, down from 32% at September 30th. During the quarter, another 4-rated loan paid off at par, highlighting again that the vast majority of our 4- and 5-rated loans do not suffer principal losses.
Looking back through our history, when ACRES assumed the management contract of ACR in 2020, the company had 23 loans with a par balance of $411 million, or 24% of the portfolio, risk-rated either 4 or 5. As of December 31st, 2025, only two of those 4 or 5 loans remain unresolved in the portfolio.
Our exceptional asset management team created sponsor-specific solutions to successfully resolve 21 of those loans, or $368 million of par value, recognizing a loss of only $4.8 million on those resolutions, or just 1.3% of the par balance of those loans. We expect the same or better results on the remaining 4- or 5-rated assets in our portfolio as we work actively and strategically with our sponsors to create positive resolutions.
The majority of these assets have manageable stabilized LTVs of 80% or less. To further highlight this point, as a firm since inception 12 years ago, ACRES has incurred minimal realized losses on almost $8 billion of invested capital.
We are also excited to announce that we sold one of our REO assets collateralized by an office property in Austin, Texas this quarter, which resulted in an earnings available for distribution, or EAD, gain of $1.3 million. During the quarter, we charged off a legacy $4.7 million mezzanine loan that was originated prior to ACRES management in 2018 and whose loss was fully reserved for and recognized in both GAAP and book value in 2022.
We recognized the EAD impact this quarter in connection with settlement of that loan. We will now have ACR's CFO, Eldron Blackwell, discuss the financial statements and operating results during the fourth quarter.
Eldron C. Blackwell
Thank you, and good morning, everyone. GAAP net loss allocable to common shares in the fourth quarter was $3 million, or 43 cents per share.
GAAP net loss for the quarter included $10.7 million in net interest income, which was an increase of $2.3 million over the prior quarter. This increase in net interest income was driven by net loan originations of $443.8 million and corresponding facility draws during the quarter.
GAAP net loss for the quarter also included a $3 million net increase in the performance of our net real estate operations to net income of $156,000 and a $1.5 million net loss on the sale of the previously mentioned office property in Austin, Texas. We saw a decrease in current expected credit losses, or CECL reserves, of $1.3 million, or 19 cents per share, as compared to a decrease in CECL reserves during the third quarter of $4 million, which was primarily driven by loan payoffs and net improvement in the model credit risk of our CRE portfolio, offset by a general decline in projected macroeconomic factors during the quarter.
Also, as previously mentioned, ACR recorded a charge-off of $4.7 million on a mezzanine loan that was fully reserved for in 2022. The total allowance for credit losses at December 31st was $20.4 million and represented 1.11%, or 111 basis points, on our $1.8 billion loan portfolio at par and was composed entirely of general credit reserves.
Excluding the loss for the mezzanine loan that was fully reserved for in 2022, EAD for the fourth quarter 2025 was 20 cents per share. When the mezzanine loan is included, the company reported an EAD loss of 48 cents per share, as compared to earnings of $1.01 per share for the third quarter.
GAAP book value per share was $30.01 on December 31st versus $29.63 on September 30th. Additionally, during the quarter, we used $10 million to repurchase 493,000 common shares at an approximate 33% discount to book value at December 31st.
In December 2025, the authorized amount was fully utilized, and since November 2020, the company has repurchased 5.3 million shares at an average discount to book value of 49%. Available liquidity at December 31st was $108 million, which comprised $84 million of unrestricted cash and $24 million of projected financing available on unlevered assets.
Our GAAP debt-to-equity leverage ratio increased to 2.8 times at December 31st from 2.7 times at September 30th from net originations on our CRE loan portfolio. At the end of the fourth quarter 2025, the company's net operating loss carryforward was $32.1 million, or approximately $4.89 per share.
With that, I will now turn the call to Andrew Fentress for closing remarks.
Andrew Fentress
Thank you, Eldron. We're pleased with continued execution of our plan to drive shareholder value.
In the fourth quarter, we originated $571 million of new loans. We repurchased shares at accretive levels, sold an REO asset, improved the credit quality of the portfolio, and positioned the company to resume paying a dividend to common shareholders.
Since assuming the role of manager in July of 2020, ACR book value has increased a total of 66%. All the team here at ACRES is energized by the opportunity set we see in front of us, both in the asset class and the competitive landscape.
We will continue to deploy capital through careful underwriting and then manage each investment to the optimal outcome for shareholders. We greatly appreciate your continued support and investment in ACR, and we look forward to your questions.
This concludes our opening remarks. I'll now turn the call back to the operator for questions.
Operator
Thank you. If you'd like to ask a question, press star, 1 on your keypad.
To leave the queue at any time, press star, 2. Once again, that is star, 1 to ask a question.
We'll pause for just a moment to allow everyone a chance to join the queue. Thank you.
Our first question comes from Matthew Erdner with Jones Trading. Please go ahead.
Your line is now open.
Matthew Erdner
Hey, good morning, guys. Thanks for taking the question.
Could you touch a little bit more on the loans that you guys completed this quarter? As a really impressive number in terms of net loan growth.
I heard you mention the 283 spread there, but could you give any additional kind of color on that? Then, as well, what the current pipeline looks like?
Mark Fogel
Sure, Matt. This is Mark.
The color on that portfolio is it was mostly multifamily-type execution. The average loan size was probably about $40 to $50 million.
Spreads ranged between 250 and 325. It was purposely focused, our origination effort, on multifamily this quarter and the next quarter in that we were in the process of looking to execute a new CLO, and CLO execution was extremely dependent on a significant amount of multifamily.
On the bright side, our CLO execution includes reinvestment opportunity to do up to 40% of our assets outside of multifamily.
Matthew Erdner
Got it. Then how long is that reinvestment period?
Is it 24 months?
Mark Fogel
30 months.
Matthew Erdner
Got it. Awesome.
Then, with the additional kind of equity investments, page 11 of the deck, what's your plan for that? Then, would we or should we expect an exit from any of those assets as we go through the year?
Mark Fogel
I think on one of them right now, you can expect an exit, one of the smaller land deals that we have. We're actually under LOI right now to sell that asset.
One of the other assets is out on the market right now. We expect that we'll get some offers during the year, and we'll make a decision based on whether those offers come in.
Matthew Erdner
Got it. That's helpful.
Then last one from me, just noticed something on the balance sheet. Non-controlling interest jumped up to about $130 million, call it, from about 1.
I was just curious what that was.
Mark Fogel
Sure. This is Andrew.
The company sold a position or a portion of its previously issued financing arrangement with J.P. Morgan, and so that interest is recorded as an NCI.
Matthew Erdner
Got it. That's helpful.
Thank you, guys.
Mark Fogel
Thank you.
Operator
Thank you. We'll now move on to Chris Muller with Citizens Capital Markets.
Your line is now open.
Christopher Muller
Hey, guys. Thanks for taking the questions.
Nice to see originations come in really strong. Based on your illustrative earning slide, it looks like there's some at least capacity to grow the portfolio and push leverage a little bit.
Could we see this pace of deployment we saw in the fourth quarter in the near term, or was that mostly due to the CLO execution in January?
Mark Fogel
No, Chris. We expect we'll see a decent amount of additional deployment, a significant amount of it occurred in the first quarter of 2026.
We're projecting net growth in the portfolio of $500 million to $700 million in 2026.
Christopher Muller
Got it. That's great to hear.
I guess turning gears a little bit, I believe the capital loss carryforwards expired at the end of the year. Thinking about potential upside to book value, would any future gains on REO be fully tax going forward, or are there any other offsets that would apply?
Eldron C. Blackwell
Hey, this is Eldron. No.
Let me start with we still have remaining NOLs, $32.1 million at the QRS. That's available to us.
That's a when, not an if. As long as we continue to have depreciation as part of our normal operating expenses, I don't expect in the future that any gains on those capital items would be taxable.
We also have NOLs in our TRS, any activity down there is also protected.
Christopher Muller
Got it. There's still a little bit that will flow through.
I guess just a quick clarifying one. The $3.4 million of realized losses on core activities, was that just the mezzanine loan write-off that you guys talked about, or is there something else in there?
Mark Fogel
That was a big chunk of it. We recorded a $4.7 million EAD loss attributable to this mezzanine loan that we inherited as part of our taking control of the REIT, and we recorded a specific reserve for that back in 2022.
Christopher Muller
The specific or the CECL reserve release in the quarter, that was a specific reserve release related to this asset, is that right?
Eldron C. Blackwell
Part of it was the specific reserve, the $4.7 million. The other $1.3 million was just improvement in net credit of the portfolio on our general reserves.
Christopher Muller
Got it. I appreciate you guys taking the questions today, and great to see the capital deployment picking up.
Mark Fogel
Thanks, Chris. Thank you.
Operator
Once again, if you'd like to ask a question, please press star and 1 on your keypad now. Thank you.
We'll move on to Gabriel Poggi with Raymond James. Your line is now open.
Gabriel J. Poggi
Hey, good morning, and thanks for taking the questions. I've got a couple.
For year-to-date originations, has there been any change in spreads? Has there been any mix shift away from multifamily?
Just anything you could provide there would be helpful. Pardon me.
Mark Fogel
In 2026, originations to date have mostly been multifamily. As I said, we were geared towards ramping up for our CLO.
Spreads overall in that portfolio are about 2.83%. We're seeing spreads come down on the multifamily side for sure across the board.
As I said, we're looking at other asset classes for reinvestment activity, and going forward, you'll see a different type of mix within our portfolio. We're pretty heavily weighted towards multifamily right now, and I would expect that some of that will sort of start to fall off over the course of 2026.
Gabriel J. Poggi
Got it. Is the goal there to kind of maintain that 280-over spread while mixing out to other asset classes, or are you content to kind of have asset yields bleed a little bit lower just because of the competitive nature of the market?
Mark Fogel
No, our intent is to be above and beyond 283. There are certainly a lot of opportunities in other asset classes where spreads are better, some more risk-reward opportunity in self-storage and office and retail.
Historically, our portfolio has been only 60% to 65% multifamily, and that's where we expect it to get back to.
Gabriel J. Poggi
Thanks for that. A question on repayments in '26, you've got about $400 million update there, obviously, the CECL reserve has come down.
Do you expect just a normal cadence of repay activity for '26? Anything in there that we should be aware of?
Mark Fogel
No, we expect that repayments in '26 will be healthy. We're projecting about $500 million of repayments in '26, mostly older vintage assets.
Importantly, what that does for us, if you mix in new originations in '26, is it brings down our older vintage, call it '23 and older type assets down to about only 15% of the portfolio.
Gabriel J. Poggi
Thank you for that. One more, and this is kind of a high-level question, but as you guys think about ramping the portfolio, right, in slide 14 in the deck, and taking total leverage to 3.5, because of the capital structure and pref versus common, right, you tilt more to a higher leverage ratio on the common level.
Where's the comfort level as you think about leverage to the common, and where do you want to max out there in that ramp? I see the current state, the mid, and then the full tilt, but just how do you think about that in the bigger macro environment, where the comfort level is, leverage to the common equity?
Thank you.
Mark Fogel
Gabe, it's Andrew. I think what we show is, we're inside of our comfort level at that inside of 4 turns.
I don't think you'll see us go above that.
Gabriel J. Poggi
Got it. Inside of 4 on total, my words, leveragable capital, which then could push
Mark Fogel
your
Gabriel J. Poggi
leverage on the common higher, but total leveragable capital inside of 4. Right.
Mark Fogel
Correct.
Gabriel J. Poggi
That's helpful. Thank you, guys.
Mark Fogel
Thank you.
Operator
Thank you. At this time, there are no further questions in queue.
I will now turn the meeting back to our presenters.
Mark Fogel
Thank you, everyone. We appreciate your support, and we look forward to reconnecting with all of you in the coming weeks.
If you have any questions, please reach out to myself or Eldron. Have a great day.
Operator
Thank you. This brings us to the end of today's meeting.
We appreciate your time and participation. You may now disconnect.