Acacia Research Corporation
NNASDAQ:ACTGQ3 FY2026 · Earnings Call TranscriptNovember 5, 2026
Operator
Good morning everyone, and welcome to Acacia Research Corporation third quarter 2026 earnings conference call. My name is Vincent, and I'll be your conference facilitator today.
At this time, all participants are in a listen-only mode to prevent background noise. Following management's prepared remarks, we will open the call for questions.
Please note that today's call is being recorded and is also being webcast through the Investor Relations section of Acacia Research's website. I would now like to turn the conference over to Cody Slach of Gateway Group.
Cody, please go ahead.
Cody Slach
Thanks, Vincent. Joining today's call are MJ McNulty, Acacia's Chief Executive Officer, and Michael Zambito, Acacia's Chief Financial Officer.
Before management begins its prepared remarks, I'd like to remind everyone that certain statements made during today's call constitute forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. These statements reflect management's current expectations, estimates, and projections regarding future events and operating performance, and involve risks and uncertainties that could cause actual results to differ materially from those expressed or implied by these forward-looking statements.
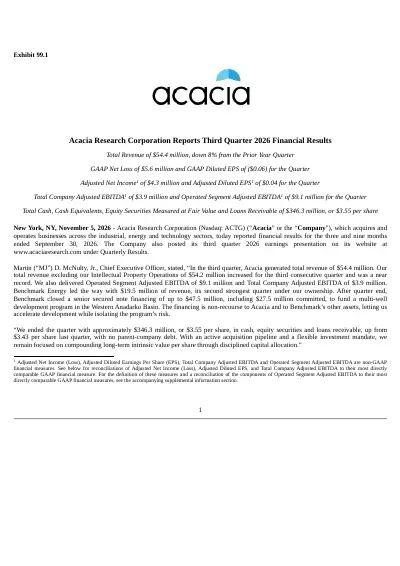
Please refer to Acacia's filings with the Securities and Exchange Commission, including our annual report on Form 10-K and quarterly reports on Form 10-Q, for a discussion of these risks. Earlier this morning, Acacia issued a press release announcing its third quarter 2026 financial results.
That release, together with our earnings presentation, is available in the Investor Relations section of our website. During today's call, management will discuss certain non-GAAP financial measures.
Reconciliations are included in this morning's earnings release. With that, I'll turn the call over to Acacia's Chief Executive Officer, MJ McNulty.
MJ McNulty
Thanks, Cody, and good morning, everyone. Thank you for joining us today and for your continued support for what we're building here at Acacia.
We're pleased with our performance in the third quarter. Our results reflected continued strength at Benchmark, consistent cash generation at Printronix, and strong performance in our public securities portfolio, partially offset by soft end market conditions at Deflecto, where we continue to make operational progress.
Together, these results underscore the benefits of our diversified business model. During the quarter, we generated total revenue of $54.4 million.
Our total revenue excluding our intellectual property operations of $54.2 million increased for the third consecutive quarter and was at a near record. We ended the quarter with $346.3 million in cash, securities, and loans receivable, and no parent company debt, providing us with significant financial flexibility.
Our objective has never been to maximize short-term earnings. Instead, we focus on compounding long-term intrinsic value per share through disciplined capital allocation, acquiring businesses at attractive valuations, improving their operations through active ownership, and deploying capital where we believe it can generate attractive long-term returns.
The third quarter and the weeks since have offered several examples of that approach in action. At Benchmark, during the quarter, our initial Cherokee well continued to outperform our expectations, and subsequent to quarter end, we completed drilling our second Cherokee well, and we closed a dedicated financing of up to $47.5 million to accelerate development of Benchmark's Cleveland drilling inventory, all of which we will discuss shortly.
In our public securities portfolio, similar to last quarter, another one of our holdings announced an agreement to be acquired, ultimately generating realized gains for Acacia. Looking ahead, our pipeline remains robust.
We continue to actively evaluate attractive opportunities in the private markets, and we're increasingly more active and seeing more compelling opportunities in the public markets, specifically in small and micro-cap businesses that fit our acquisition criteria. We remain patient and disciplined, pursuing only opportunities where we believe our operational expertise and investment approach can create value beyond the purchase price.
With that overview, let me turn to our operating businesses, beginning with Benchmark. Benchmark continues to perform well, with operating performance and cash flow exceeding our expectations.
Asset-level EBITDA is up substantially year-over-year, and we expect to continue that growth into 2027, while operating expenses have remained in line. As we continue growing adjusted EBITDA, we will also be able to layer in hedges at higher commodity prices and lock those in over time.
Our second Cherokee well, Moontower, has been online for about a week. While it is early in flowback, results are encouraging and are tracking ahead of our first Cherokee well.
In total, Benchmark has approximately five operated Cherokee units, each of which we believe can support two wells. We'll continue to develop these units methodically, bringing cash flow forward where returns support it.
As we continue to successfully develop our Cherokee asset, we'll take advantage of opportunities to bolt on additional units and acreage. Subsequent to the quarter end, on October 2nd, Benchmark created a wholly owned, bankruptcy-remote subsidiary within which it closed a senior secured reserve-based lending facility with Sybilo Energy Partners.
This senior secured facility provides up to $47.5 million of borrowing capacity, with initial availability of $27.5 million, of which $18.5 million was funded at closing. The initial draw was complemented by a $6 million equity--$6 million of equity capital from Benchmark.
The proceeds used to fund the new subsidiary are dedicated to an operated multi-well development program targeting Benchmark's Cleveland drilling inventory in the Western Anadarko Basin. The program is initially four wells, with the potential to expand the program over time.
The financing is held in a separate special purpose vehicle and is non-recourse to Benchmark's other assets and to Acacia. This structure allows us to accelerate development of attractive locations while isolating the program's risk and preserving balance sheet flexibility.
As we've seen in the Cherokee formation, we're seeing a meaningful increase in Cleveland formation drilling activity across the Western Anadarko, with excellent results. Results today are substantially better than they were a decade ago, driven by a focus on top-tier rock, disciplined spacing, and modern completion techniques.
We believe our Cherokee and Cleveland drilling programs offer an attractive risk-adjusted return profile for Acacia. Our core strategy at Benchmark has been to acquire proved reserves at a discount to their intrinsic value.
Most of that value has come through producing reserves, but every acquisition Benchmark has made since its formation in 2023 has also included proved undeveloped locations. Today's market presents an opportunity to begin harvesting some of those locations, which is exactly what our strategy was built to do: take advantage of opportunities as the market presents them.
It's worth highlighting how this value creation is reflected in our financial statements. Over the past several quarters, Benchmark has invested meaningful capital in its drilling program.
Under GAAP, that capital is recorded at cost, our book value reflects what we've invested, rather than the potential future value of those new reserves. When wells perform as our Cherokee well has, the difference between the underlying future value of these newly added reserves and the GAAP book value of those wells is at its greatest at the beginning of a drilling program.
This gap will narrow over time as we generate positive income from that production and the value of the underlying reserves is converted into that income. We're pleased with the initial results from our drilling and believe this program has and will continue to meaningfully increase the intrinsic value of Benchmark's oil and gas assets.
Investors should just be aware that this value is not yet reflected in our book value. For a more complete view of this, you'll be able to see the change in reserves when we release our year-end 2026 reserve report, which will be filed with our 10-K in the first quarter of 2027.
Those proved reserves will provide more granularity on the total value of the assets. It's also worth noting that Benchmark holds significant resource potential that is not included in the proved reserves.
Finally, we continue to actively manage our commodity hedging program. Our objective is to generate strong free cash flow, reduce earnings volatility, and protect against downside risk.
We do not speculate on commodity prices. Approximately 70% of our expected oil production is currently hedged, and we'll continue adding volumes over the next 12 months.
In addition, approximately 70% of our expected natural gas production over the next 12 months is hedged, with floors above $4 per MMBtu over the next 6 months, providing meaningful protection in a relatively soft near-term gas market. Because these hedges are mark-to-market each quarter, reported results will include non-cash gains and losses, such as the $5.1 million unrealized loss this quarter, which should not be viewed as indicative of the underlying economics of the business.
Turning to Deflecto. Revenue for the third quarter was $27.2 million, compared to $30.8 million in the prior-year period, and adjusted EBITDA was $1 million, compared to $2.6 million in the prior-year period.
Results were driven primarily by softer demand in our air distribution end markets, specifically in the Canadian and US housing markets, coupled with increased input costs. While our office products end market showed a revenue decline, this was primarily driven by the decline in revenues associated with the sale of our floor mat business, which we sold in November of 2025.
Our transportation safety revenues have held steady year-over-year, and we're optimistic about the positive trends we're seeing in the underlying Class 8 market. We were encouraged, however, that performance improved as the quarter progressed, with September showing a meaningful step up in profitability.
We believe that improvement reflects the actions we've taken over the past several quarters: optimizing our manufacturing footprint, reducing product lead times, streamlining the organization, tightening cost discipline, and executing on pricing. These initiatives have fundamentally and structurally enhanced Deflecto's earnings potential.
We are optimistic about the opportunities in the transportation market and remain focused on what we can control. We are encouraged that the actions we've taken to simplify operations and reduce our cost base position Deflecto to benefit from improved profitability in a recovering demand environment.
Turning to Printronix. Printronix continued to perform well and generate consistent free cash flow.
We continue to leverage the strength of its installed base and global distribution network to expand sales of higher-margin consumables and complementary products. Through the quarter, we continued to grow the installed printer base and operated the business with disciplined cost management.
During the quarter, Printronix generated revenue of $7.5 million and adjusted EBITDA of $1.5 million. While small to the overall portfolio, we've been pleased with the operational and commercial turnaround of the business.
Turning to our intellectual property platform. During the quarter, we continued to pursue monetization of our Wi-Fi 6 and other portfolios, and generated licensing revenue of approximately $300,000.
As a reminder, licensing activity is inherently episodic and is best evaluated over longer periods. We have a positive view of the value that remains in the portfolio, both in Wi-Fi 6 as well as in our R2 patents.
We have also further reduced the platform's overhead to better align its cost structure with the timing and nature of licensing opportunities, which we believe should enhance the platform's go-forward earnings profile as future licensing opportunities are realized. Lastly, turning to our public securities portfolio, which continued to perform well during the quarter.
During the third quarter, another one of our public company investments announced an agreement to be acquired, generating realized gains of $8.2 million for Acacia. Similar to last quarter, this demonstrates our ability to identify undervalued businesses, build strategic positions with discipline, and monetize those investments when the risk-reward becomes compelling.
Our public markets investments are an extension of our broader capital allocation strategy. When we identify a business that may fit our platform, we can establish an initial position while conducting additional due diligence and evaluating a potential strategic transaction.
We also remain disciplined in managing existing positions, monetizing investments when they approach our assessment of intrinsic value, and redeploying capital where we see more attractive opportunities. With that, I'll hand the call over to Mike to review our financial results in greater detail.
Michael Zambito
Thank you, MJ. As MJ discussed, the third quarter reflected continued execution across our operating businesses and the benefits of Acacia's diversified business model.
Before reviewing the financial statements in more detail, I'd like to highlight a few key financial takeaways. Total company revenue was $54.4 million for the quarter.
Total operated segment revenue, excluding intellectual property, was $54.2 million. Total company adjusted EBITDA was $3.9 million, while operated segment adjusted EBITDA, excluding IP, totaled $11.6 million.
We ended the quarter with $346.3 million of cash, equity securities, and loans receivable, while continuing to maintain no parent company debt. Turning to our income statement.
Total revenue for the quarter was $54.4 million, compared to $59.4 million in the prior-year period. Energy operations generated revenue of $19.5 million.
Manufacturing operations generated revenue of $27.2 million. Industrial operations generated revenue of $7.5 million, while our intellectual property business generated licensing and related revenue of $300,000.
Turning to expenses. Consolidated G&A expense for the quarter totaled $15.4 million, versus $16 million in the third quarter last year.
Across our businesses, we continue to emphasize disciplined cost management, including the further reduction of overhead in our IP business. GAAP operating loss for the quarter was $3.6 million, and total company adjusted EBITDA was $3.9 million.
We believe adjusted EBITDA remains a useful supplemental measure of operating performance because it helps investors evaluate the underlying earnings power of our businesses by excluding certain non-cash and non-recurring items. Turning to our operating segments.
Benchmark generated adjusted EBITDA of $9.1 million and free cash flow of $2.7 million for the quarter, while continuing to invest in attractive development opportunities, consistent with our disciplined capital allocation framework. Deflecto generated adjusted EBITDA $1 million, while continuing to focus on operational improvement.
Printronix generated adjusted EBITDA of $1.5 million and continued to produce strong free cash flow. Within our IP segment, adjusted EBITDA totaled negative $2.5 million.
We didn't generate any paid-up license fee revenue in the quarter, and as a reminder, this revenue stream is episodic. In the meantime, we've continued to lower our cost base in the segment, which you will start to see reflected in the coming quarters, and align expenses more closely with the timing and nature of licensing opportunities.
Turning to earnings. GAAP net loss attributable to Acacia Research Corporation was a $5.6 million loss, or negative 6 cents per diluted share.
Adjusted net income attributable to Acacia Research Corporation was $4.3 million, or 4 cents per diluted share. A reconciliation of GAAP and non-GAAP results is included in this morning's earnings release.
Turning to the balance sheet. At quarter end, cash, cash equivalents, equity securities measured at fair value, and loans receivable totaled $346.3 million, an increase of approximately $11.7 million during the quarter.
We continue to maintain no parent company debt. On a consolidated basis, at quarter end, total gross indebtedness was $90.4 million, consisting of $59.5 million of non-recourse debt at Benchmark and $30.9 million of non-recourse debt at Deflecto.
Subsequent to quarter end, Benchmark closed its senior secured development facility of up to $47.5 million, which is non-recourse to Acacia. Book value at quarter end was $551.6 million, or $5.65 per common share, compared to $557 million, or $5.71 per share, at prior quarter end.
Changes to book value were primarily driven by $2.6 million in operating income from our operated segments including IP, and $2.3 million in gains from our public equity portfolio, offset by parent expenses of $6.3 million and realized and unrealized energy hedge losses at Benchmark of $6.1 million. The unrealized loss associated with our oil hedging program, which was $5.1 million in the quarter and $9.7 million year-to-date, reflects mark-to-market accounting on derivative positions that extend over a multi-year horizon, and does not correspond to realized economic outcomes within the quarter.
The charge is driven by changes in future price expectations, and does not impact current period cash flows or margins. Overall, we believe our balance sheet remains one of Acacia's key competitive advantages.
Our liquidity, conservative capital structure, and strong cash generation provide meaningful flexibility to continue investing in our existing businesses while evaluating new investment opportunities. I'll now turn the call back to MJ.
MJ McNulty
Thanks, Mike. As you've heard today, Acacia delivered another quarter of solid execution.
Benchmark continues to perform well and has secured dedicated capital to accelerate its development program. Deflecto is making the operational progress that we believe will drive future performance.
Printronix continues to generate consistent cash flow, and our public securities portfolio again generated attractive realized gains. Our strategy remains straightforward and unchanged: we seek to acquire businesses at discounts to what we believe is intrinsic value, fundamentally improve them through active ownership, and build them into leaders in their niches.
With $346.3 million of cash, securities, and loans receivable, no parent company debt, and operating businesses that continue to generate attractive cash flow, we believe Acacia is well positioned to capitalize on the opportunities we see in both the private and public markets. Vincent, we'd now be happy to take any questions.
Operator
Thank you. At this time, we will now begin question-and-answer session.
If you would like to ask a question, you will need to press star one on your telephone keypad. Your first question comes from Anthony Stoss of Craig-Hallum.
Please go ahead.
Anthony Stoss
Morning MJ and Michael. MJ, I'm hoping maybe not to put you too much on the spot, but on the acquisition side of things, can you maybe just give us a little bit more color on activity levels?
Have you made bids for things and you've been outbid, or just any kind of additional color would be helpful, then I had a follow-up.
MJ McNulty
No, and nice to talk to you, Tony. Not putting me on the spot at all.
We've been pretty active. We have been bidding on things.
We have been outbid on things, and we are progressing other things. As the two public names that we mentioned we were involved in, we're not buying stakes in public companies purely to build a book of public names and trade around them.
We're doing that for a strategic reason, as evidenced by their sale. There were processes there, and so we've been pretty active on the public side.
On the private side, we've continued to see some interesting things. The market there from a financing standpoint, depending upon the type of asset, has been a little choppy.
We think that finally, a lot of the private equity sellers are starting to get a little bit of religion around where their assets sit and returning capital to their limited partners. We're pretty encouraged by the pipeline of opportunities that we've got.
Anthony Stoss
Perfect. Then on the Cherokee side of things, I just wanted to make sure I heard it correctly, you drilled a second well and you have higher expectations for more output from that second well, and then I guess when will the third well be drilled, since you seemingly can have what, 10 wells, I think you mentioned, five areas, two wells each?
MJ McNulty
That's exactly right. We have five units.
A unit can hold two wells, as you mentioned. We continue to look at attractive incremental units where they make sense relative to acreage that we hold from the Revolution acquisition.
The commodity price environment and the drilling environment right now is attractive, we're not going to commit to when we're going to drill incremental Cherokee wells, but putting the Moontower down was very attractive capital opportunity. Then this Sybilo partnership we have with the reserve-based lending facility on a non-recourse basis in the Cleveland is also pretty attractive.
If you recall from the Cherokee acquisition, we kind of priced it on a PDP basis. The discount rates on those PDPs have come in, and so as we see new opportunities to acquire businesses in Benchmark, they're at higher prices than where we acquired Revolution, but Revolution had a very large inventory of Cleveland drilling locations that we can take advantage of, and the Sybilo partnership allows us to do it on a non-recourse basis with very favorable terms associated with it.
Anthony Stoss
Perfect. Thanks for all the detail.
MJ McNulty
Of course.
Operator
Your next question comes from Brett Reiss of Janney. Please go ahead.
Brett Reiss
Hi MJ, hi Mike. Can you hear me?
MJ McNulty
Hey, Brett. Hey, Brett.
Brett Reiss
Great. First question or two is on the IP portfolio.
Is Atlas in the Wi-Fi 6 portfolio? Are you participating in some sort of consortium called Avanci?
MJ McNulty
We're consistently looking at ways to monetize that portfolio and participate with other people that have programs to go out and monetize IP, and we think that there's a good amount of value in continuing to do that as well as to pursue the direct communication and process that we have historically pursued that you all have seen. All right,
Brett Reiss
but to the extent you're participating in this consortium of Avanci, does that give us the opportunity to have a royalty or recurring revenue stream from the patent portfolios we own with respect to Wi-Fi 6?
MJ McNulty
That's a strategic question, which is do we do fully paid-up licenses, which we've done in the past, or do we create ongoing royalty streams? What we've seen, at least historically in our pursuit of monetizing these patents, is that the fully paid-up tends to be more attractive relative to the ongoing royalty stream.
To the extent that we have an opportunity to participate in an ongoing royalty stream where the opportunity may not otherwise be available to us, that's attractive as well. It's incremental earnings for our portfolio.
Brett Reiss
Right. Now, I see in the news release, you added or purchased additional patents with respect to Wi-Fi 7.
Are you already positioning yourself if the industry migrates from Wi-Fi 6 to 7, whatever economic benefits you have with Wi-Fi 6, you'll just roll it up as the world migrates to Wi-Fi 7?
MJ McNulty
No, we definitely think that that's attractive, and, Brett, similar to the way we approach all of our acquisitions, when we acquire things, we acquire them because we think that there's a big discount to intrinsic value, and so that's how we approach anything in the IP portfolio as well.
Brett Reiss
Okay. Pivoting to Benchmark.
Even after the special purpose acquisition vehicle with Sybilo, we still own 73% of Benchmark? Nothing changes there?
MJ McNulty
That's a good question. There is no ownership change in Benchmark associated with this partnership with Sybilo.
The partnership with Sybilo is purely a senior credit facility on very attractive terms to augment $6 million of our Benchmark equity that went into that vehicle. There is no ownership change associated with Benchmark.
Brett Reiss
Okay. This vehicle, Sybilo owns x amount of it and we own x amount of it, is that correct?
MJ McNulty
We own 100% of it, Brett.
Brett Reiss
Okay. All right.
Their loan is collateralized by only those assets that are in that special purpose acquisition vehicle and not our other oil and natural gas assets, is that correct?
MJ McNulty
That is correct. It's 100% bankruptcy-remote vehicle.
Just to expand on that a little bit, sorry to cut you off. The only collateral in that vehicle is the equity that we contributed to it and the well locations that we contribute to it.
Brett Reiss
Okay.
MJ McNulty
Those well locations are not, just to be clear, and I think I said this, those well locations are not Cherokee well locations, they're Cleveland well locations, of which we have many, many.
Brett Reiss
Okay. There'll be an 8-K filed eventually, or maybe it's existing now, where the all-in costs of this financing from Sybilo will be something that shareholders can review?
MJ McNulty
We're not 8-K-ing it. It is not material.
Brett Reiss
Okay.
MJ McNulty
There will be some information in the 10-K that will give a little bit more detail around it next quarter. The reason it's not 8-K is because it happened post quarter, it's not in the Q, but it'll be in the K.
Brett Reiss
Okay. AMO Pharma, any update on how things are moving along there in terms of potential strategic partners, the timing of the registrational study, any sense of how much contribution we may have to fork up to monetize the asset?
MJ McNulty
There are a lot of questions there. Let me take them from the top.
We're pretty enthusiastic about AMO's potential. As we have a partner in that investment, we're, call it 18.5% or something of the total ownership cap table, and our partner is, by and large, the rest of that.
We and they have been working very closely with the company on registrational studies and related work, as well as making sure that the market commercially and from an M&A standpoint understands the story and where the company sits. As we've said, these assets are bought, not sold, and we've been actively making sure that the market understands where AMO is and what the value proposition is.
As we've said in the past, our goal here is to monetize this, not to hold it and continue to develop the drug.
Brett Reiss
Great. Deflecto, there was a $700,000 restructuring charge.
Do you think the restructuring charges are coming to an end, and that your aspiration, I think, to make Deflecto an $8 million to $10 million EBITDA business eventually, are we shooting for that, and will we see that in the next two years or so?
MJ McNulty
Look, we continue to do restructuring. I look at the restructuring in two ways.
One, the market has been a little softer than what we would have liked it to be. We are seeing improvement in the market and we're encouraged by that improvement.
Two, there are a lot of opportunities to restructure the business. As I mentioned in the script, we've fundamentally and structurally improved the earnings power of the business, so as volumes go up, we believe margins on those new volumes or those rebounding volumes is going to be a lot higher.
In terms of the numbers you threw out, that is the track we're on is to generate that or better if the market cooperates in earnings potential.
Brett Reiss
With the--
MJ McNulty
We still like the business. We feel we're very enthusiastic about the business.
Brett Reiss
Now, the agita that came from the Trump tariffs, now that it's possible some of these will be rolled back, will that become a tailwind rather than a headwind for Deflecto?
MJ McNulty
If the tariffs are rolled back, I would expect a tariff rollback to be a tailwind for Deflecto. I would caution that it's Thursday and the elections were two days ago, it's far too premature to have a view on what may or could happen.
Brett Reiss
Okay. Last one, are you at liberty to say which public equity investment you made where you generated that $8.2 million gain, which I thank you for?
MJ McNulty
I wish we could take a victory lap, but we can't. I'm sorry.
Brett Reiss
Okay. I appreciate your patience in answering all my questions, and continue the good, interesting work.
This is not boring.
MJ McNulty
Thanks, Brett. Definitely not boring.
Okay. Again, if you would like to ask a question, please press star, then the number one on your telephone keypad.
Again, that will be star, then the number one on your telephone keypad.
Operator
Your next question comes from Adam Eagleston from Formidable Asset Management. Please go ahead.
Adam Eagleston
Good morning, guys. How are you today?
MJ McNulty
Hey, Adam. How you doing?
Adam Eagleston
Good, doing well. Thank you.
Brett stole part of my question, which you couldn't answer, about the name of the company. Can you give us an idea of what type of ROIC that was, at least?
MJ McNulty
It's the overall ROIC, we held the position for probably inside six months, and don't hold me to this number, but it was probably a 2.5x or something like that.
Adam Eagleston
Great, great work. At least that gives you a little bit of a victory lap there, I hope.
MJ McNulty
Thanks for asking the question, Adam.
Adam Eagleston
Of course. With that being said, you still have a large cash pile on the books.
You're getting some bids out there on the private side, but getting outbid. Are you maybe going to do a little bit more of this on the public equity side or kind of how are you thinking about the cash at this point, because we're just not getting a lot of credit for it if you look at the discount between book value and the current share price?
MJ McNulty
It's a good question. We are seeing attractive things on the private side.
We have been outbid on things. There has been a couple of the things we looked at that we really liked, there were very irrational private equity buyers out there.
We are seeing a lot of interesting things on the public side, and we've been much more active there. As you can see, having spent my career, or a good part of my career in private equity, you spend a lot of time on a deal, somebody else buys it, and you kind of get a stick in the eye and told to walk away.
On the public side, it tends to be potentially a little more interesting in that even if you don't end up owning the business, if it transacts, then you have the potential to make some money on the public position that you hold, and so we are more active on the public side.
Adam Eagleston
Got it. No, that's helpful.
Again, we're just not getting a ton of credit there. Then, of course, my last question, given the discount to book value currently, and it sounds like, if I heard you correctly, as we get to the end of the year, there's some accounting machinations that might actually increase that book value ceteris paribus, how are you thinking about cost of capital and capital allocation, and specifically a buyback?
MJ McNulty
When we look at cost of capital, we look at flexibility and opportunity. We do have a lot of cash, and I would say when you look at the cash number, it's cash, securities, and loans receivable, it's not all pure cash.
The ability to put that cash to work in the public markets, as we evaluate bids in the private markets, the return on that capital is pretty attractive. When we look at underwriting returns, we're looking at, mid to high teens plus, depending upon how we view the risk adjustment associated with any particular opportunity.
The return when we put that money to work, we expect to be very attractive.
Adam Eagleston
Got it. If it's mid to high teens plus, given the current discounts, 20-ish percent, again, I just think that's a lever we should consider pulling.
MJ McNulty
I understand that. Then I just want to make sure I understand your comment about year-end book value.
I just want to make sure I'm answering that question or addressing it appropriately.
Adam Eagleston
I thought you said there was something with regard to some of the Benchmark accounting that sounded like a positive effect on book value. Maybe I misheard.
MJ McNulty
I just want to clarify that. When we drill a well, there's obviously, or hopefully, significant future value associated with that well, net asset value of that well.
When we put it on the books, that potential future value doesn't show up anywhere. It just goes on the book at cost, and then as we produce, there's depreciation and depletion associated with that well and net income.
The net income is what feeds the book value. At year end, we'll publish our reserve report, and not book value, but that reserve report is what gives investors a view into the actual value of the reserves that we own.
Adam Eagleston
Got it. Thanks for clarifying that.
MJ McNulty
Of course.
Adam Eagleston
All right. Hey, that's [encouraging?]
to see. Nice job.
MJ McNulty
Oh, yeah, no, thanks, Adam.
Operator
There are no further questions at this time. This now concludes today's conference call.
Thank you for participating. You may now disconnect.