Advanced Energy Industries, Inc.
Q3 FY2026 · Earnings Call TranscriptNovember 2, 2026
Operator
Greetings, and welcome to the Advanced Energy third quarter 2026 earnings call. At this time, all participants are in a listen-only mode.
A question-and-answer session will follow the formal presentation. If anyone should require operator assistance, please press *0 on your telephone keypad.
As a reminder, this conference is being recorded. It is now my pleasure to introduce Edwin Mok, Vice President of Strategic Marketing and IR.
Please go ahead.
Edwin Mok
Thank you, operator. Good afternoon, everyone.
Welcome to the Advanced Energy third quarter 2026 earnings conference call. With me today are Steve Kelley, our President and CEO, and Paul Oldham, our Executive Vice President and CFO.
You can find today's earnings press release and presentation on our website at ir.advancedenergy.com. Before we begin, let me remind you that today's call contains forward-looking statements that are subject to risks and uncertainties that could cause actual results to differ materially and are not guarantees of future performance.
Information concerning these risks can be found in our SEC filings. All forward-looking statements are based on management's estimates as of today, November 2nd, 2026, and the company assumes no obligation to update them.
Any targets beyond the current quarter presented today should not be interpreted as guidance. On today's call, our financial results are presented on a non-GAAP basis unless otherwise specified.
Detailed reconciliations between our GAAP and non-GAAP results can be found in today's press release. With that, let me pass the call to our President and CEO, Steve Kelley.
Steve Kelley
Thanks, Edwin. Good afternoon, everyone, and thanks for joining the call.
We delivered a record third quarter, with revenue and earnings above the high end of guidance. Strong factory execution enabled us to meet increased customer demand.
Total revenue grew over $120 million sequentially. Revenue in each of our target markets grew sequentially and year-over-year.
Earnings per share more than doubled from a year ago, largely due to higher volume and operational leverage. Over the past year, we invested in capacity expansion and strategic piece-part inventory.
These investments are enabling higher revenue, increased profitability, and greater customer satisfaction. In 2026, our execution and supply chain resilience have become competitive advantages.
Our new flagship factory in Thailand is beginning to generate revenue. Multiple data center customers have already qualified the factory, and semiconductor customers are expected to follow shortly.
Our Thailand production lines are being brought up by subject matter experts from around the world. After recently visiting the factory, I have no doubt that Thailand can become the largest and most efficient factory in our network, a true flagship.
In addition, we continued to increase output at our factories in the Philippines, Malaysia, and Mexico. We are expanding our footprint and becoming more efficient in all three locations.
The result is that we are on track to expand our total revenue-generating capacity to over $5 billion by the end of 2028. Demand is strong across all of our target markets.
We are benefiting from significant market tailwinds across semiconductor, data center, and I&M. In addition, we believe that our new products will drive market share gains.
In semiconductor and data center, customers are projecting that demand will continue to strengthen through 2027 into '28. In industrial and medical, we experienced our fourth consecutive quarter of year-over-year growth, a trend we expect to continue into 2027.
Now let me provide some color on each of our markets. In semiconductor, we delivered another record quarter, with year-on-year growth of over 60%.
Increased investment in leading-edge wafer capacity is driving record demand for AE products. Our operational performance in this market has been solid, and we've been recognized by major customers for our ability to keep pace with increasing demand.
During the quarter, we won several plasma power designs for advanced node processes, the culmination of multi-year design efforts. We believe that these wins will accelerate our growth as leading-edge processes begin to ramp their production in 2027.
We secured two additional wins in semiconductor test, the latest in a series of test-related wins. The power required to test AI chips and modules has increased meaningfully, driving the need for high power density, high efficiency custom solutions from Advanced Energy.
We expect our new plasma power and system power products to drive market share gains over the next several years. In data center computing, revenue grew almost 50% year-on-year.
Increased demand and factory execution drove the outperformance. Our business with hyperscale customers continues to strengthen, with multiple new programs driving revenue growth this year and into 2027 and '28.
We also expanded our growing list of second-wave customers, with several new wins secured in the third quarter. We expect that revenue from second-wave customers will add to hyperscale revenue beginning next year.
At the OCP Global Summit last month, we showcased our 800-volt power distribution board. With industry-leading power density, efficiency, and reliability, our modular solutions can be customized rapidly to meet the evolving requirements of 800-volt architectures.
We also highlighted our liquid-cooled power technology, which can be applied in both 50-volt and 800-volt systems, providing customers with optionality as they transition to higher-powered racks. Looking to 2027 and beyond, we expect data center revenue will continue to grow substantially, driven by three factors: growth from next-generation hyperscale programs, revenue from second-wave customers, and the eventual ramp of 800-volt solutions.
In industrial medical, revenue grew sequentially and year-over-year. Factory execution continues to improve, allowing us to meet growing demand and work down our overdue backlog.
We expect robust market conditions to continue into 2027. In the distribution channel, which accounts for roughly half of I&M revenue, distributor resales continue to outpace our sales into the channel.
In the third quarter, we secured multiple design wins in medical imaging, life sciences, test and measurement, and mil-aero applications. In September, we launched our Defiant Future family of ruggedized power supplies for aerospace and defense applications, which we expect will generate significant revenue for AE in the coming years.
To expand our customer reach, we continue to invest in digital marketing. Today, an increasing number of our I&M design wins originate as web leads, and some of those wins have turned into multi-million-dollar opportunities.
In telecom and networking, revenue grew sequentially as AI-related applications drove increased customer demand. Now for some closing thoughts.
We are executing well to meet increased demand across all of our target markets. As a result, we have increased our 2026 growth outlook to around 40%.
Looking ahead, based on customer forecasts and feedback, we believe that strong investments in AI data center and leading-edge wafer capacity will continue through 2027 into '28. We are expanding capacity by ramping up our Thailand factory as well as increasing output at our other factories.
We believe that we have enough capacity to deliver sizable upside over the next several quarters, assuming adequate supply of key components. We will continue to invest heavily in R&D.
We believe that these investments will enable us to deliver differentiated products to our customers and gain share across all of our target markets. Leveraging increased product value, improved manufacturing efficiency, and higher volume, we have line of sight to our over 43% gross margin.
Finally, we remain active in pursuing potential acquisitions which make strategic and financial sense. Paul will now provide more detailed financial information.
Paul Oldham
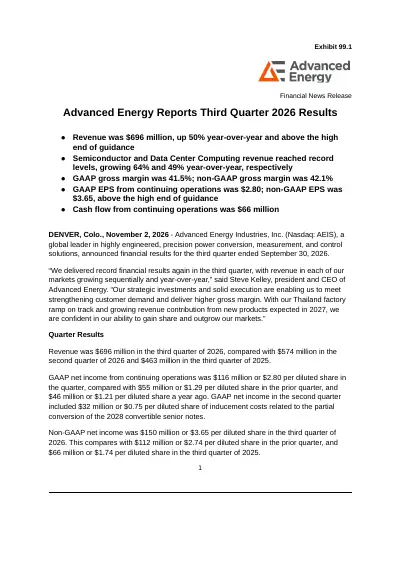
Thank you, Steve, and good afternoon, everyone. In the third quarter, we delivered record financial results that exceeded the high end of our revenue, gross margin, and EPS guidance ranges.
Revenue of $696 million increased more than 50% year-over-year, and earnings of $3.65 per share more than doubled. Gross margin improved 300 basis points year-on-year to 42.1%, contributing to record operating income.
Operating margin reached 24.4%, the highest level in recent years, and we generated operating cash flow of $66 million while continuing to invest in strategic inventory to support expected customer ramps. Now let's review our third quarter financial results in more detail.
Total revenue of $696 million increased 21% or $122 million sequentially, well above the high end of our guidance range. Solid execution allowed us to meet increasing customer demand and capture upside to our guidance.
Semiconductor revenue was a record $322 million, up 16% quarter-over-quarter and 64% year-over-year. Strong demand for leading-edge equipment, increasing etch and deposition intensity, and expanding system power revenue continued to drive robust growth.
Data center computing revenue of $256 million was also a record, up 34% sequentially and 49% year-over-year. Increasing customer demand and the initial ramp of new programs are driving higher revenues.
Industrial medical revenue was $91 million, up 13% from last quarter and 27% from last year, as we increase output to support growing customer demand. Telecom and networking revenue was up 13% sequentially and 15% year-over-year to $28 million, driven by AI-related programs.
Gross margin in the third quarter was 42.1%. Excluding the benefit of Q2 tariff refunds, gross margin expanded 140 basis points, driven by higher volume and manufacturing efficiency.
Operating expense of $123 million was within our guidance range and increased slightly quarter-over-quarter due to R&D program spending and higher variable costs. With strong top-line growth, gross margin expansion, and opex leverage, our operating margin expanded 760 basis points year-on-year to 24.4%.
As a result, third quarter operating income increased 118% year-over-year to reach a record $170 million. Depreciation was $12.2 million, and our adjusted EBITDA was $182 million.
Other income was $8 million, up from $5 million in Q2, mainly due to a full quarter of higher interest income and lower interest expense following our convertible note offering in Q2. For Q3, our non-GAAP tax rate was 15.7%, in line with our guidance.
Third quarter earnings were $3.65 per share, up meaningfully from $2.74 last quarter and $1.74 a year ago. Turning now to the balance sheet.
Following the end of Q3, we redeemed the remaining $136 million of our 2028 convertible senior notes, including unwinding the related note hedge and warrants. Since the settlement occurred on October 2nd, this remaining debt and related cash are included on our Q3 balance sheet.
As a result, total cash and equivalents were $1.42 billion, and net cash was $159 million, both up from Q2. Inventory days decreased one day sequentially to 144, and turns stayed at 2.5 times.
We expect inventory turns to remain around these levels over the next few quarters. Days sales outstanding decreased two days to 61 days, and days payable outstanding decreased four days to 81 days.
Q3 net working capital was up one day to 124 days. As a result, Q3 cash flow from continuing operations was $66 million.
During the third quarter, we paid $4.1 million in quarterly dividends and invested $31 million in capex to support the production ramp in our factories. For the full year 2026, we now expect capital investments to be towards the low end of our $180 to $195 million range on timing of expenditures.
However, we will continue to invest at an elevated level throughout 2027 as we add capacity towards our target of over $5 billion in annual output. Following the 2028 convertible note redemption, we resumed our opportunistic share repurchase program, and in the month of October, we repurchased approximately $30 million of our common stock at around $241 per share.
Turning now to our guidance. Demand continues to strengthen across our markets, with initial production of several new product programs contributing to revenue growth.
As a result, we are forecasting fourth quarter revenue to be approximately $735 million, plus or minus $25 million. We now expect 2026 total revenue to grow around 40%, up from our previous target of low to mid-30%.
Driven by increased customer demand, semiconductor revenue is now projected to grow over 60% year-on-year in the second half, up from the prior outlook of 50%. Our outlook implies semiconductor product revenue, excluding service, will grow by around 45% in 2026.
Following a strong Q3, we expect fourth quarter data center computing revenue to increase further. As a result, we are raising our 2026 data center revenue growth to the high 50% range.
In industrial and medical, we continue to expect year-on-year revenue growth for the next few quarters. In telecom and networking, revenue is expected to moderate slightly after the stronger Q3.
We expect Q4 gross margin to be in the 42% to 42.5% range. We expect Q4 operating expenses to increase to $126 to $128 million, due primarily to investments in new products.
We expect other income to be approximately $8 million, and continue to target a tax rate in the 16% range over the next several quarters. As a result, we expect Q4 non-GAAP earnings per share to be $3.90, plus or minus 30 cents, on 41.2 million shares outstanding.
Our Q4 guidance puts us on a run rate to exceed our 2030 target model three years ahead of our original plan. Let me finish with some concluding comments.
We are executing well to meet a strengthening demand environment across our markets. After strong growth in 2025, we are on track to deliver 40% revenue growth and over 90% earnings per share growth in 2026.
Current customer forecasts suggest 2027 revenue growth will be robust, and we continue to expect earnings per share to grow faster than revenue. With higher-value new products still ramping and plans to further improve manufacturing efficiency, gross margin is on track to reach and eventually surpass our target of over 43%.
Our strategies continue to position Advanced Energy for growth and increase our resilience in all market conditions. These strategies include diversifying into an expanding set of growing markets centered on our core competencies in precision power conversion, investing in leading-edge technologies and platforms, and expanding our customer reach through our digital platform.
In addition, we are building out a scalable, best-in-class manufacturing footprint, strengthening our supply chain, investing in inventory to mitigate risk, and fortifying our balance sheet with low-cost capital. As a result, we are well positioned to gain share and outgrow our markets.
With that, we will now take your questions. Operator?
Operator
Thank you. We will now be conducting a question-and-answer session.
If you would like to ask a question, please press *1 on your telephone keypad. A confirmation tone will indicate your line is in the question queue.
You may press *2 to remove your question from the queue. For participants using speaker equipment, it may be necessary to pick up your handset before pressing the star keys.
In the interest of time, we ask that participants limit themselves to one question and one follow-up. One moment, please, while we poll for questions.
Our first question is from Krish Sankar with TD Cowen.
Krish Sankar
Hi. Thanks for taking my question, and congrats on the great results.
Steve or Paul, my first question is, given your guidance, very impressive, it looks like sequentially semi grows probably mid-single digits, data center probably grows 10%. I'm just wondering, are those in the ballpark?
Given the visibility you have, any thoughts into quantifying semi and data center power supply growth in 2027?
Paul Oldham
I think you're in the right ballpark for Q4 sequential numbers. I think that's in the right range and consistent with the overall number we gave.
For 2027, we think that growth will continue to be robust. I think last quarter we said we expected it to be over 20%.
Directionally, we think that's probably around 30% at this point. Generally, we'd expect that to have sequential growth as we go through the year, but as it's not linear, necessarily, based on supply constraints and product transitions.
Having said all that, it's a pretty strong demand environment, and demand growth could likely be higher than that number, but there is some uncertainty regarding supply, which makes it difficult to give really actual specific guidance for 2027, but directionally, that's how we're thinking about it.
Krish Sankar
Got you. Thanks for that, Paul.
Just as a follow-up, within the 30% range for next year, how to think about data center and semi and I&M?
Paul Oldham
I think, again, we're not giving any guidance by market at this point, but you can look at relative growth from this year, you can also look at comments made externally about projected WFE growth and data center growth. Obviously, I&M will grow slower than those, and we expect telecom and networking to be about flat.
We're not breaking it down at this point just because it's looking forward into the next year, but I think you can get a pretty good idea of how that breakdown could look.
Operator
Our next question is from Matthew Prisco with Cantor Fitzgerald.
Matthew Prisco
Hey, thanks for taking the question. On the semi side, can you maybe offer some color on what type of visibility you're seeing today, and maybe how do the discussed wins impact your ability to grow versus WFE in '27?
Thank you.
Steve Kelley
Matt, this is Steve. I think the visibility we have into '27 from our semi customers is excellent.
They've given us detailed forecasts for the entire year. As we look into '28, we don't have a forecast by part type, but we have directional guidance that it continues to go up from '27.
I think it's quite good. For us, we're benefiting from two things.
One is obviously the market surge, and most of that is coming from our older products, and we're executing on that, and that's benefiting our top line and our bottom line. In addition, we're starting to see new products become a significant factor.
As we look into '27, we believe that more than 10% of our semi revenue will come from new products. Those new products basically are the way we're going to gain share over the next 5 years, and most of those new products are going into advanced logic and memory processes.
In addition, we have the new products on the system power side, where we've been designed into a variety of tester, burn-in, and process equipment applications.
Matthew Prisco
Great. Thank you.
Maybe over to the data center, how are you thinking about those second-wave ramps and the magnitude of contribution there in 2027 based on current conversations? Thank you.
Steve Kelley
Yeah. On the second-wave ramps, again, let's go back, I'll just define it for folks.
These are basically all the customers we have for data center products except for the hyperscalers. These encompass enterprise, networking, neoclouds, et cetera.
We believe that over time that altogether, these second-wave customers could generate more than $300 million in yearly revenue. That's not going to happen next year, but we think by '29 that's the case.
I would say, every quarter that goes by, we add to our roster of second-wave customers, we're qualified and in the early shipment phase for multiple second-wave customers. Some of that's in Thailand, and some of it's in the Philippines.
A lot of great opportunities. What I can say as we look into '27 is that we have a relatively small amount of revenue in our forecast for the second-wave customers, because we don't understand at this point which of those customers will ramp the volume and which may be constrained by other factors.
We have some in our forecast, but we're not dependent on second-wave revenue to meet our outlook for '27.
Operator
Our next question is from Scott Graham from Seaport Research Partners.
Edwin Mok
Hey, Scott, are you there?
Operator
Is your line on mute?
Scott Graham
I guess I was on mute. I'm sorry about that.
Hi. Good evening.
I was just wondering, Steve, when you talk about we see strong growth in '27, 2028, you're saying '28 is a growth year in that statement as well for semi and data centers, right?
Steve Kelley
I was commenting on semi in particular when I made that statement. We do believe it's a growth year for data centers as well.
Scott Graham
Okay. All right, thanks.
Even though you can't put a number on it, '28 should be another growth year for your two largest segments. Okay.
Steve Kelley
Yes, sir.
Scott Graham
Two most important segments for growth. Thank you.
The other question I had is more on math, if you don't mind, Paul. Was there a non-GAAP credit that rolled through the earnings this quarter for taxes?
Paul Oldham
There was actually a charge in taxes on a GAAP basis associated with a deferred tax asset that we had to write down a bit because we were able to lower our long-term tax rate in one of the jurisdictions. We treated that as a one-time GAAP-only item, and so that's why our GAAP tax rate was higher at almost 24%, 23.7%, versus our non-GAAP tax rate.
Scott Graham
Okay. If I were to reverse the sign on that number, essentially take a 30% hit on what your charges are, that would be 30, 35 cents a share swing.
You're not saying that the non-GAAP is 30 to 35 cents higher because of that, are you?
Paul Oldham
We reported our non-GAAP number, which you see there, and in the tax, if you look at the difference between the GAAP tax rate and the non-GAAP tax rate, the GAAP tax rate was 15.7%, and the non-GAAP tax rate was 23.7%. I'm sorry, the other way around.
Non-GAAP was 15.7, and GAAP was 23.6. That was entirely a function of this one-time non-cash charge for deferred tax asset that we wrote down because we're getting a lower rate in the future in one of our jurisdictions.
Operator
Our next question is from Elizabeth Sun with Citi.
Elizabeth Sun
Hi, good afternoon. Thanks for taking my question.
I guess my first question is in the longer term for data center. I think you've talked about hyperscalers growth and talked about second-wave customers, and at OCP, as Steve mentioned as well, you showcased some solutions for 800 direct-to-server.
I'm just curious, after moving to 800-volt, is there any opportunities to further expand your customer base beyond hyperscalers and second-wave customers like clouds or enterprise?
Steve Kelley
Thanks for the question, Elizabeth. You're right.
At OCP, we had a number of products on display. Probably the most important was something called the power distribution board, which is designed for customers who are moving to 800 volts or to somewhere in between.
We see a lot of customers who are looking for transitional solutions where they need to accommodate multiple power supplies, multiple different supply voltages. Our power distribution board is interesting because it's modular and it's easily customizable.
It's basically a mix-and-match approach to 800 volts and the interim solutions. One of features is best-in-class efficiency.
We had 98% efficiency, best-in-class power density, 350 watts per cubic inch, and then we can customize mechanicals, EMI performance, and obviously firmware. We also offer liquid cooling, this is something that we're importing from our plasma power group.
We've got a pretty versatile solution for customers, and those customers include hyperscalers as well as second-wave customers. There's quite a bit of interest in this modular approach to 800 volts.
Elizabeth Sun
That's great to hear, thanks. On gross margin, I think Paul used to guide exiting this year at 42 and the next year 43.
It seems like you are hitting 42% earlier than expected this year. I'm just curious, how should we think about gross margin trajectory over next year, and are you able to reach this 43 mark earlier than expected, and maybe a rule of thumb is that 50% flow-through is a good way to think about it?
Paul Oldham
You're you're right, Elizabeth. We are hitting a little bit sooner.
In fact, we guided Q4 now to 42 to 42.5%, actually over 42% that we said last year, last, quarter. At this point, we still think we have an exit rate of 43% next year.
That could be slightly higher, or could come a little earlier. It will depend on volume.
You're right, it's it's just under 50%, leverage to gross margins, sort of in the high 40s would be the drop-through rate.
Operator
Our next question is from James Ricchiuti with Needham & Company.
Edwin Mok
Jim, are you there?
James Ricchiuti
[unclear]
Edwin Mok
Hey, Jim, your line's breaking up. Can you try again?
James Ricchiuti
Is this any better, Edwin?
Edwin Mok
Oh, much better, much better.
James Ricchiuti
Yep. Terrific.
Question's about Thailand. I'm wondering, Steve, if you could talk to how many customers or data center customers are qualified, how many hyperscalers, how many of the next tier.
Sounds like you're saying pretty good, you're making good progress there. If you can give us any color on that.
Steve Kelley
I'd be happy to do, Jim. I was just out there a couple weeks ago, and I saw a product coming off the line for two different data center customers, they're already qualified.
In addition, we'll have two two of our top semi customers qualified in the next 2 to 3 months. We're starting off very strong in Thailand.
It's a pretty impressive factory, quite frankly. It's a 500,000 square feet on a single floor, it's by far our biggest factory.
The people I met were pretty amazing. We have subject matter experts from around the world who are helping to bring that factory up to speed.
We're employing our best-in-class techniques from around the world there. Warehouse is huge, and it's a linear flow, it's warehouse to assembly to test to shipment.
It's really a showplace, and I think all customers will be eager to be qualified in that factory as soon as possible.
James Ricchiuti
All right. You alluded to supply chain.
Obviously, that's a topic for a lot of folks. Are you experiencing any supply chain constraints across semi, data center, or for that matter, I&M?
Steve Kelley
The short answer is yes, but the longer answer is we've been encountering supply chain issues for most of the year, but we've had pretty effective mitigation techniques. We put in place some strategic inventory based on our experiences during COVID, and our team's pretty good at chasing parts.
We've also put in place surge capacity, because what we've found is many of these constrained parts don't get delivered until, let's say, the last 4 to 6 weeks of the quarter, we need to really push our production in the last [unclear] be some of that supply chain constraint that we won't be able to mitigate, and so we built that into our forecast for the fourth quarter and for '27. We see the problem areas being isolated components, particularly ICs.
We see some constraints on PCBs and also specialty ceramics.
Operator
Our next question is from Shane Brett with Morgan Stanley.
Shane Brett
Great. Thank you for taking my question.
My first question is on data center and your CPU opportunity. At your June quarter 2024 earnings, you talked about having 50% to 60% more dollar content in AI racks than you do with conventional server racks, which is still a lot of content.
Is this still a valid metric in assessing your CPU opportunity? If not, how should I think about your content for CPUs versus AI accelerators?
Could this sort of CPU or agentic AI opportunity become a meaningful tailwind for your data center business in 2027? Thanks.
Steve Kelley
Thank you, Shane. I would say, as power supply makers, we view any reason to build an additional rack is a good thing for us, essentially.
Whether it's a GPU, a CPU, or some other type of chip, it generally drives more demand for power supplies and other power delivery products in these racks. I think CPUs are a good thing for us.
Shane Brett
Got it. For my follow-up, I want to ask about semi.
In prior cycles, market share between subsystems has been more due to their customers' performance, but just given the pace of revisions in this WFE upcycle, it does feel as though there will be a few suppliers that can't keep up. You've clearly put yourself in a great position, but do you think that there will be share gains to come from readiness as well as scale, kind of drivers beyond just technology wins?
Thank you.
Steve Kelley
Shane, that's an excellent question, and we have seen that actually, because during COVID, I think we performed well from both a supply chain standpoint and execution standpoint. I think that's benefited us over the past 2 to 3 years as we've been working with key customers to design in new products, because they know that we can build these products over time.
That's an important part of the equation. I think today, what we're seeing is that we're outexecuting many of our peers, and we'd like to continue to be in that position.
We've been recognized by some of our customers for our ability to keep delivering to their upside requirements over the past 9 months. We're happy about that, and we think it's going to help us win new slots in the semiconductor segment.
Operator
Our next question is from Steve Barger with KeyBanc Capital Markets.
Steve Barger
Hey, thanks. Steve, it's really great to hear Thailand progressing so well.
Seems like manufacturing capacity is going to be back ahead of demand in both DC and semi, my question is, does engineering bandwidth again become the scarcer resource, and are there any attractive programs today that you're being selective about as you manage those return on engineering resources?
Steve Kelley
Steve, I think engineering resources have always been the critical path for us, whether it's semiconductor or data center. I think for us, adding capacity is not that difficult.
Most of the machines that we buy are available within 3 to 6 months. The biggest hurdle was just building Thailand, and now that's open, and so I think we've got capacity that'll get us through '28, '29 easily.
On the capacity side, I think we're good. I think from an engineering standpoint, yes, there are opportunities that we can't address because of engineering bandwidth, but what we see are an increasing set of opportunities from our subset of hyperscale customers.
We continue to broaden our participation there, and our performance is helping us win more of those two customers, essentially. In addition, we have this long list of second-wave customers, where we're getting design wins, partially due to the technology, but also because they see our factories and like what they see.
Steve Barger
Got it. The factory is actually becoming kind of a competitive advantage for new product wins.
Steve Kelley
Yes, I think it is, and, after visiting the factories a couple weeks ago, I could see where a customer would be pretty impressed by what we've done in Thailand and the improvements we've made in the Philippines. I think they're world-class factories.
Steve Barger
Got it. Then, you said the pace of distribution sales is outpacing your sales in I&M, which seems like a good sign.
I know you've had a lot of design wins in recent quarters where you were just waiting for purchase orders to come through. Does it feel like that momentum is shifting more in your favor, broadly speaking, in I&M?
Are you thinking about this in terms of multiple years of double-digit growth, given the share gains and new product wins that you've locked in?
Steve Kelley
I think in I&M, that's a distinct possibility. We've gone through quite a transformation in our industrial medical business.
4 or 5 years ago, we had some commodity business that was nestled in there, industrial medical. That's all been eliminated.
Everything you see today, all the growth is coming from high-margin new products. We're getting a little bit of a tailwind, obviously, as the market recovers from the post-COVID inventory hangover, but most of what you're seeing from Advanced Energy in our outperformance is based on these new product wins we've been able to secure over the past 2 years.
We're pretty happy with the rate of growth in industrial applications in particular, as well as semiconductor applications where they're using basically industrial medical products. Finally, we also see some interesting things happening in medical.
We're pretty happy with what's happening in I&M, and we see this trend continuing, where we continue to grow sequentially for the foreseeable future.
Operator
Our next question is from Mehdi Hosseini with SIG.
Mehdi Hosseini
Yes, sir. Thanks for taking my question.
A couple of follow-ups for Steve. Based on what your semi OEM have reported, it seems like WFE in '27 could be closer or around $200 billion, which implies a 30% to 35% year-over-year growth.
What I want to ask you is a reference to your comment that 30% of your semicap revenue in '27 is driven by new product, and given what your OEM have communicated, does that imply that your revenue in '27 will be much stronger than what your OEM are guiding for WFE growth? I have a follow-up.
Steve Kelley
Mehdi. First, let's go back to the new product statement.
What I said was that in 2027, we expected more than 10% of our semi revenues to come from new products, which is our starting point on new products. I think at your larger question, with the WFE and so forth, and are we growing as fast as WFE, if we go back to '26, and, assuming that our current guidance in Q4 is accurate, if we strip out our service business, the actual growth in our product revenue in semiconductor is roughly 45%.
It's higher than the overall semi growth rate, because service just doesn't grow at the same rate as the product revenue does. As we look at '27, we think we're going to grow as fast or faster than WFE.
More importantly, over time, with all these design wins that have been confirmed over the past few months, we think we could really outpace WFE over the next 5 to 10 years, based on what we've been able to secure for leading-edge memory and logic applications.
Mehdi Hosseini
Got it. Steve, sorry, I missed up the 10, I confused the 10 with the 30%, but going back to the semicap, I can't stop thinking about the post-COVID, and there was a mismatch of components for your OEM that had a ripple effect for subcomponent suppliers, and you did have a backlog given the shortages, and actually, some of the same customers are experiencing the same mismatch.
To what extent are you working with your OEM customers to plan for this growth into '27 and avoid mismatches or avoid any delay in complete system shipment?
Steve Kelley
Just to clarify, you're talking more about downstream supply constraints that our customers may have as opposed to supply constraints that we have in building our boxes? Is that the question?
Mehdi Hosseini
Remember back in 2022, 2023, you didn't have enough power management PMIC components. Your semicap OEM customer also had mismatches.
The mismatch was throughout the semicap supply chain, but it was more acute among your OEM customer. I want to see what you're doing in collaboration with your OEM customer to avoid some of the challenges from back then.
Steve Kelley
Basically, with our large OEM semi customers, we ship into JIT bins. Our customers give us a target, basically, a low and a high, and then we're allowed to ship into those bins as long as we keep the quantity within the low and the high targets.
What I can say is we've been keeping up there. That's why we've been recognized for our ability to keep up with our customers' demands.
I don't think we're close to the high end of those JIT bin limits, there's room for us to ship more, and that's something we could do. I would say we're a bit cautious.
We don't want to get too far over our skis. We want to make sure the customer has sufficient product from AE, but we don't want them to build too much inventory, because we don't want to go through a correction phase.
Operator
Our next question is from Quinn Fredrickson with Baird.
Quinn Fredrickson
Hey, good afternoon. Steve, you mentioned showcasing liquid-cooled power technology solutions for 800-volt OCP.
Are impressions you may have been included in Nvidia's MGX liquid-cooled reference architecture, just any color on what that might mean for you, if so?
Steve Kelley
It's always nice to be included in something like that, and we value Nvidia as obviously a key technology partner. Hopefully, other people look at that and realize Advanced Energy has some pretty advanced liquid cooling technology, and we're ready to deploy it.
I think it's great that we were recognized by Nvidia as a technology partner.
Quinn Fredrickson
Thanks, Steve. Then, as we're thinking about your growth versus WFE for '27, you mentioned calculating it ex-service in '26.
Is there any reason to believe the service business could see better growth in '27 than what you've seen here this year, where seems like growth has been a little light of typical, and if so, why would that be the case?
Paul Oldham
If you think about service, it's really largely based on installed base, and there's some trade-off between repair and non-break-fix, depending on where you're at in the cycle. Simple answer is we would expect service to kind of grow in that mid-single digits to 10% every year, pretty much.
We're not counting on a big service growth rate next year. Similarly, if we ever went into a downturn or when we do, that will continue to grow.
I think you could assume the similar relationships next year to this year.
Operator
Our next question is from Brian Chin with Stifel.
Brian Chin
Hi there. Good afternoon.
Thanks for letting us ask a few questions. Sorry, I was hopping between calls, apologies if there's any backtracking here.
Maybe firstly on data center, in terms of the '27 commentary, does sound like you're more constructive on data center growth in addition to semicap next year. Did I hear correctly that you expect strength from hyperscalers beyond your largest hyperscaler customer next year, and if so, can you expand upon that?
Steve Kelley
Yes, Brian. I did mention that we have two significant customers in hyperscale.
We haven't given out that number before, very very good that you picked that up. We're seeing strength with those two customers.
Obviously, their revenue there could be complemented by revenue from second-wave customers as well, but we're not counting on the second-wave revenue to meet our outlook for next year. Demand is very strong.
In fact, we're actually having to airship some of our power supply units because we can't keep enough in stock at the customer hub. That gives you some flavor for where we're at in the data center market.
Brian Chin
Great. Yes.
Appreciate that. Then maybe on the semicap side of the business, clearly some strong tone in terms of the positioning over the next several years.
Can you provide any more sort of granularity about maybe wins or kind of progress specifically on the oxide etch market, or in terms of maybe memory or other applications?
Steve Kelley
Yeah. I'd love to.
We've been talking about eVerest, eVoS, and NavX for the last few years, and the good news is we just won some major slots here just in Q3. This is across the board: eVerest, eVoS, and NavX.
These are our high-volume opportunities which will begin to ramp next year. We think conductor etch, the new products begin to ramp next year as some of these leading-edge processes start to ramp, and then we see our dielectric wins starting to ramp in '28.
In addition, we've won key slots in deposition. The common theme, I think, for all these wins is that this new technology is required at the advanced nodes to maintain or improve throughput and to maintain and improve yield.
There's continue to be a strong pull from customers. The other thing we've noticed is once we win one design at a customer, it starts to multiply.
It multiplies across different processes, and in addition, sometimes there's an opportunity to back-integrate the technology. Going to more recent nodes, if the end customer is having any issues with throughput or yield.
I think we're in a very good spot with these new products, and we think that they're going to form the basis for significant market share gain over the next 5 years.
Operator
Thank you. Our last question is from David Duley with Steelhead Securities.
David Duley
Thank you so much for squeezing me in. You partially answered this, but I was just kind of wondering what the key reason was that your semi business's growth rate accelerated in the back half of this calendar year.
It's I think 60% or higher in both Q3 and Q4, and you've just raised your guidance for the year to up substantially more than it was before. Could you maybe rank order what the key reasons are?
Is it you're just catching up with customer demand, or you're outexecuting your competitors, or share gains? Then I guess as a follow-up is would you expect this kind of year-over-year growth to continue into the first half of next year, given they're pretty easy comps in the first half?
Paul Oldham
I'll take a cut at that, David, and Steve Steve can fill in any other color. I think the first thing is we are seeing stronger demand in the second half.
If you remember, we started off this year a little slower, we had tougher comps a year ago, and we said we expected semiconductor demand to accelerate in the second half, and that's exactly what we're seeing. In our case, we think we're keeping up with customer demand, and so that's resulting in higher numbers both sequentially and year-over-year, and year-over-year comps are a little bit easier, so that's helping.
We do think that we've been successful and have been recognized for being able to keep up with demand, and so we're not seeing those headwinds because of our strategies around inventory and capacity, and those things are helping. Going into next year, we haven't guided exactly for how those revenue growth rates would look, but you would anticipate that if you had sequential growth in that market, even a little bit, you'd still have a pretty significant year-over-year growth.
I think you could see that for another quarter or so.
Steve Kelley
I think the only thing I'd add is that I think we're also benefiting from increasing etch and dep intensity, and also benefiting from the fact that most of the investments going into leading-edge logic and DRAM processes, where we tend to have more content.
Operator
Thank you. This concludes today's conference call.
You may disconnect your lines at this time. We thank you again for your participation.