Cullen/Frost Bankers, Inc.
Q3 FY2026 · Earnings Call TranscriptOctober 29, 2026
Operator
Thank you for your patience. The conference will be beginning in just a few moments.
Again, thank you for your patience. We will be beginning in just a few moments.
Greetings, welcome to Cullen/Frost Bankers, Inc. Third Quarter 2026 Earnings Conference Call.
At this time, all participants are in a listen-only mode. A question-and-answer session will follow the formal presentation.
If anyone should require operator assistance during the conference, please press *0 on your telephone keypad. Please note this conference is being recorded.
I will now turn the conference over to A.B. Mendez, Senior Vice President and Director of Investor Relations.
Thank you. You may begin.
AB Mendez
Thanks, Sherry. This afternoon's conference call will be led by Phil Green, Chairman and CEO, and Dan Geddes, Group Executive Vice President and CFO.
Before I turn the call over to Phil and Dan, I need to take a moment to address the safe harbor provisions. Some of the remarks made today will constitute forward-looking statements as defined in the Private Securities Litigation Reform Act of 1995 as amended.
We intend such statements to be covered by the safe harbor provisions for forward-looking statements contained in the Private Securities Litigation Reform Act of 1995 as amended. Please see the last page of text in this morning's earnings release for additional information about the risk factors associated with these forward-looking statements.
If needed, a copy of the release is available on our website or by calling the Investor Relations department at 210-220-5234. At this time, I'll turn the call over to Phil.
Phil Green
Thanks, A.B. Good afternoon, everyone.
Thanks for joining us. Today, we'll review the third quarter 2026 results for Cullen/Frost, and then our Chief Financial Officer, Dan Geddes, will also provide additional comments and guidance updates before we take your questions.
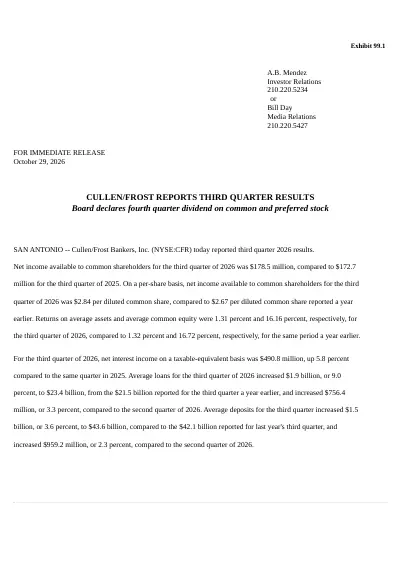
The third quarter 2026, Cullen/Frost earned $178.5 million, an increase of 3.4% compared to the third quarter of last year. Per share earnings for the third quarter were $2.84, an increase of 6.4% from the $2.67 in the third quarter of last year.
Our return on average assets and average common equity in the third quarter were 1.31% and 16.16% respectively, and that compares with 1.32% and 16.72% in the third quarter of last year. Average deposits in the third quarter were $43.6 billion.
That was an increase of 3.6% from the previous year, and average loans grew to $23.4 billion, up 9% from last year. Our consumer bank continues to deliver strong results that are grounded in consistent focus on customer experience and our investments in organic expansion, products, and technology.
Consumer loans ended the quarter at $4.66 billion, an increase of $736 million or 18.7% year-over-year. Consumer real estate lending continues to drive this outstanding growth, and I'm happy to say that as I speak to you today, our mortgage portfolio exceeds $1 billion.
Mortgage lending also remains an important opportunity to build broader relationships. Since the program began, 46% of mortgage customers have been new to Frost, and 37% of those new customers have opened additional products.
Consumer deposits also saw strong growth in what continues to be a very competitive market. Consumer deposits increased $297 million in the third quarter, driven primarily by increases in money market deposit balances.
This growth is only possible through the focused effort of our sales, product, marketing, and technology teams, and of course, through the world-class customer experiences provided every day by our frontline bankers in every Frost branch throughout the state. Non-interest income continue to grow strongly, driven by our consistently best-in-class customer growth.
Consumer non-interest income increased $2.6 million or 9.4% compared with the same period last year. Since launching our expansion program in late 2018, consumer checking accounts have grown 52%.
Our commercial line of business is also showing impressive growth. Our 90-day weighted loan pipeline reached an all-time high of $2.5 billion in the third quarter, up 16% compared to what had been the previous record in the second quarter.
Opportunities generated by our legacy financial centers grew by 14% in the third quarter, while opportunities generated by our expansion locations grew by 37%. Looking at new loan commitments booked, the third quarter was up 4% from a very strong second quarter, putting year-to-date commitments up by 19%.
Commitments of what we call core loans, that is those loans under $10 million, hit a record of $1.2 billion in the third quarter. We, once again, added more than 1,000 new relationships in the third quarter.
The expansion continues to be a significant driver of commercial relationships and accounted for 21% of new commercial relationships for the quarter. Opportunities created by other banks' mergers and acquisitions, what we call market disruption, continues to be a strong source of new relationships for us.
Year-to-date, new relationships from market disruption are up 73% compared to the same period last year. Our overall credit quality remains good by historical standards.
Total problem loans, which we define as those risk grade 10 or worse, totaled $902 million at the end of the third quarter, compared to $917 million last quarter and $828 million a year ago. Non-performing assets totaled $67 million at the end of the third quarter, compared to $114 million in the second quarter and $47 million a year ago.
The quarter-end non-performing asset figure represents only 28 basis points of period-end loans and 12 basis points of total assets. The decrease in non-performers mainly relates to one large multifamily commercial real estate loan that was discussed in last quarter's call that paid off in full through an expected property sale in the third quarter.
Net charge-offs for the third quarter were $8.4 million, compared to $9.5 million last quarter and $6.6 million a year ago. Annualized net charge-offs for the third quarter represent only 14 basis points of average loans.
In our last conference call, I mentioned my optimism about our efforts around expanding our wealth management and insurance brokerage business. In our wealth management business, we saw managed accounts grow by more than 5% year-over-year.
In our Frost Insurance Agency, commercial customers increased by more than 10% year-over-year. I'm proud of the way these teams have responded to the changes that we've made in those areas, particularly in increasing competitive environment that they operate in.
Our continued efforts and investments in these areas will contribute to future results. All across our company, our people continue to serve customers and shareholders with their commitment to integrity, caring, and excellence.
We've got the best bankers in the best markets, and that's what will continue to set Frost apart. With that, I'll turn it over to Dan for some additional insights.
Dan Geddes
Thank you, Phil. Let me start by providing some perspective on our branch expansion strategy and the growth we're seeing from those investments.
During the third quarter, our branch expansion delivered 22 cents or 8.4% EPS accretion, and 51 cents year-to-date or 6.6% of EPS accretion. We continue to be pleased with the volumes we've been able to achieve.
On a year-over-year basis, average loans grew 40% and now represent 13.9% of total loans, up from 10.8% a year ago, and contributed 48% of the growth. Deposits grew 23% and now represent 9.1% of deposits versus 7.6% in the same period last year, and contributed 49% of the growth.
The expansion branches have now grown to $3.25 billion in loans and $4 billion in deposits. Since our last call, we opened one new location in the Dallas region and have four planned openings by year-end, bringing the total for the year to 12 locations.
Now moving to third quarter financial performance for the company. Regarding our net interest margin, our net interest margin percentage was 3.78% for the quarter, up three basis points from 3.75% reported last quarter.
Net interest margin was positively impacted by a volume mix shift of earning assets from lower-yielding balances held at the Fed into both loans and investment securities. These were somewhat offset by both increased volumes of interest-bearing deposits and repos.
Looking at our investment portfolio, the total investment portfolio averaged $21.2 billion during the third quarter, up $592 million from the previous quarter. Investment purchases during the quarter totaled $1.6 billion, consisting of $625 million of agency MBS securities yielding 5.69%, $494 million of Treasuries yielding 4.21%, and $481 million of municipals yielding 5.89% on a tax-equivalent basis.
Maturities during the quarter included $1 billion of Treasuries with an average yield of 2.88%, $257 million of municipals at an average tax-equivalent yield of 4.45%, and $368 million of agency MBS paydowns. Given the recent run-up in rates, the net unrealized loss on the available-for-sale portfolio at the end of the quarter increased to $2 billion, compared to the $1.1 billion reported at the end of the previous quarter.
The tax-equivalent yield on the total investment portfolio during the quarter was 4.09%, up 13 basis points from the previous quarter. The taxable portfolio averaged $14.1 billion, up $496 million from the prior quarter, and had a yield of 3.68%, up 17 basis points from 3.51% in the prior quarter.
Our tax-exempt municipal portfolio averaged $7.2 billion, flat with the prior quarter, and had a taxable-equivalent yield of 4.93%, up six basis points from the prior quarter. At the end of the third quarter, approximately 70% of the municipal portfolio was pre-refunded or PSF-insured.
The duration of the investment portfolio at the end of the quarter was 5 years, up from 4.9 years at the end of the prior quarter. Looking at our funding sources, on a linked-quarter basis, average total deposits of $43.6 billion were up $950 million from the previous quarter.
The increase was approximately 65% in interest-bearing and 35% in non-interest-bearing deposits. Thus far in October, deposit growth continues to show momentum, with average deposits for the month sitting at $44.4 billion.
The cost of interest-bearing deposits in the third quarter was 1.73%, up 12 basis points from the 1.61% in the second quarter. Customer repos for the third quarter averaged $4.9 billion, up $471 million from the second quarter.
The cost of customer repos for the quarter was 2.67%, up two basis points from the second quarter. Looking at non-interest income and expenses, I'll point out a couple of items impacting the linked-quarter results.
Regarding non-interest income, other income was up $9.1 million, which included $7.6 million in gains from the sales of two legacy motor bank locations and a $541,000 gain on the sale of certain loans held for sale. Offsetting these gains was $7.5 million in losses on the sales of securities, where we sold $17 million in Treasuries yielding 2.15% and $18.6 million in municipals yielding 1.92%.
Given year-to-date actual performance, we recognized an additional $4.7 million in incentive compensation expense accruals during the quarter. Additionally, marketing and advertising was up $3.3 million, due primarily to additional targeted media spend during the quarter.
Regarding our guidance for full year 2026, our current outlook includes one 25 basis point hike for the Fed funds rate in December. We expect net interest income growth for the full year to fall in the range of 5% to 5.5%.
This reflects an increase from our prior guidance range of 4.75% to 5.25%. For net interest margin, we continue to expect an improvement of about 10 to 13 basis points compared to our full year 2025 net interest margin of 3.66%, no change from our guidance a quarter ago.
We expect full year average loan growth to be in the range of 8% to 8.5%. This increases the prior guidance of 7% to 8%.
Regarding deposits, we expect full year average growth to be in the range of 2% to 3%, unchanged from prior guidance. Based on current projections, we expect non-interest income growth of 8.5% to 9%, up from the prior guidance range of 7.5% to 8.5%.
Regarding non-interest expense, we expect growth to be in the 5% range year-over-year. It's at the upper end of the prior guidance of 4.5% to 5%, and it's impacted by the additional incentive accruals and advertising expense mentioned earlier.
Regarding net charge-offs, we expect full year 2026 to be in the range of 15 to 20 basis points of average loans, consistent with prior quarter guidance. Our effective tax rate expectation for full year 2026 is in the range of 15.5% to 16%, consistent with the prior quarter.
Regarding stock repurchases, I want to mention that during the third quarter, we utilized $15 million of our $300 million approved share repurchase plan to buy back approximately 93,000 shares, bringing total share repurchases for the year to $175 million and 1.26 million shares. With that, I'll turn the call back over to Phil for questions.
Phil Green
Thank you, Dan. will open the call up for questions now.
Operator
Thank you. If you would like to ask a question, please press *1 on your telephone keypad.
A confirmation tone will indicate your line is in the question queue. You may press *2 if you would like to remove your question from the queue.
For participants using speaker equipment, it may be necessary to pick up your handset before pressing the star keys. We ask that you please limit to one question and one follow-up question, and requeue for additional questions.
Our first question is from Will Jones with KBW. Please proceed.
Will Jones
Hey, thanks. Good afternoon, guys.
Phil Green
Hey, Will.
Dan Geddes
Hey, Will.
Will Jones
Hey, I wanted to start on loan growth. Obviously, a really good result this quarter.
Phil, could you just dissect for us just the breakdown between commercial and consumer growth? It doesn't really feel like Frost is having to contend with the same payoff headwinds that maybe others are.
I guess maybe is that a fair comment? Just commentary you could give us around growth you saw in the quarter, that would be great.
Thank you.
Phil Green
Okay. I think I'll talk about it in an overall way.
We've just heard from all our relationship managers with the feedback they give us as we prepare for our board meetings and to an extent, this call. I've made numerous visits to branches.
By this time, I've visited most all of our markets. What I'll tell you is I've been surprised by the durability of activity and loan growth throughout this year, even as rates have moved up.
Now, as we talk to our people, they will tell you that we're fighting competitive headwinds. The really good customers, there's big-time competition against those and against those prospects.
I think that we're seeing smaller banks be more aggressive on structure, in many cases, things that you typically wouldn't do or see. As they've told me, there's enough business out there that we're able to be successful enough to have these kinds of growth numbers.
We talked about the number of disruption relationships that we've had. When we say they're up 73%, that means they've gone from, in round numbers, we had 150 new relationships last year, we're over 250 this year.
That helps some. Then on the consumer side, the mortgage product has been so successful and continues to become a recognized high-value product in the marketplace.
Will, honestly, it's very granular, and it's just very normal, what we're seeing. Our people are working hard, we've got a great brand, there's disruption in the marketplace.
One other thing I might say is that I have heard a few times that as rates began to move up, there was a bit of a fear of missing out and not wanting to see rates go higher and taking advantage of the rate that you see in the market today. I think there's been a bit of that also.
I guess the final thing I'll say is we've instructed our people to be competitive, and we don't want to do anything stupid, and there's structural things you don't want to do. We've said a number of times through these calls this year, we're a low-cost producer as relates to funding, and we don't want to lose a great relationship, high-character relationship, a great prospect that we've been after, just for a few basis points.
We're willing to compete on price, and we've been doing that. It's just a whole lot of things.
It's not one thing. It's been very successful, in my view, right?
Dan Geddes
Will, I'll kind of add just kind of what I'm seeing is it's broad-based. I think you'll look at our growth kind of on a linked-quarter basis, and about 40% of it is what I'll call C&I-related, both a C&I loan, but also what we secure with real estate, we call an owner-occupied real estate loan.
That's about 40%. Another 40% is kind of the investor commercial real estate.
Then really the majority of the other 20% is, what Phil mentioned, is our consumer real estate, our one-to-four family mortgage product. I think Phil mentioned the 1,000 new commercial relationships, 40%, around I think it's around 42% of our loan growth is attributed to new customers that we've brought on in the last year.
Phil Green
Dan, I think that we've had over 1,000 relationships for what, six quarters in a row? Six
Dan Geddes
consecutive quarters. As Phil mentioned, we've seen an uptick.
Typically, we would get half of our new relationships from the too-big-to-fail banks, and then the other half from the other regional community banks that we compete with. Now, that number is more like 40% from the too-big-to-fail, and then that making up that difference is around that 10% from what we call the market disruption banks.
As he mentioned, well, it's up nearly 75% year-over-year. You've seen an uptick in new relationships, and it's really I think encouraging because that cohort is it's heavily C&I-related when we look at what we're winning.
It's what we would call kind of core C&I relationships in the communities that we're serving.
Phil Green
You might also mention, Dan, the percentage win rate of that business.
Dan Geddes
Typically, when I go back, and this was reports I've looked at for 20-something years of my career, we would, for a prospect, on a dollar basis, we would typically win around a third of those opportunities on a dollar basis. We're currently hovering around 78% of won opportunities from the banks that are going through mergers and acquisitions.
It's been a highly effective campaign that, in my previous experience being a banker out in the Houston market for 20 years, it has a long tail to it. It usually lasts a at least two-year period where I think if you are a business owner or if you're a consumer and your bank gets acquired, some people will leave immediately.
Others will maybe hang around and see how the new organization runs and may grow frustrated within six months, a year, two years. It may coincide with renewal of a credit if the credit culture has changed.
It's early on, but we're pleased with the results.
Will Jones
That's great. A lot of great color from both of you guys, I appreciate that.
Dan, maybe one for you just outlook for deposit cost. I recall last cycle, rates moved up that Frost was an early mover on deposit cost.
Not a defense mechanism, but just because you thought it was the right thing to do for the customer. Is that going to be the same playbook here to the extent we do get a few rate hikes?
If you could just help us out with the outlook for deposit costs and maybe what you expect betas to look like in this cycle?
Dan Geddes
Yeah. I'll give you kind of what our expectation on loan and deposit beta is.
It would be around 80% for the loans. Then from an interest-bearing perspective, we would expect maybe a similar basis.
From an overall deposit perspective, it'll be around 50%, 55% beta. You should see us pick up margin as if rates were to go up into 2027.
Will Jones
Okay. That's great.
Thank you, guys. Appreciate it.
Phil Green
Thank you.
Operator
Our next question is from Jared Shaw with Barclays. Please proceed.
Jared Shaw
Thanks. Good afternoon.
I guess starting on the expense side, you highlighted the expectation for four more branches to bring to 12 this year. Is that still a good sort of annual expectation for you as you look at future branch expansion?
With that, can we still expect to see positive operating leverage?
Dan Geddes
On the expansion, I mentioned we expect to open 12 this year. Looking into '27, we have I think 14 planned.
Inflecting a little higher. I think that's, I would say, that 12 to 15 in the near term.
Our branch expansion has just been very successful, and I don't see us slowing down. In fact, I would tend to see over time us open up more than the 12 to 15.
Then on your second question, yeah, we still have our budget to complete for '27. I would say, in looking at just the guidance that I gave for '26, you're looking at, and right for '26, 50 to 75 basis point operating leverage.
For next year, we would hope for positive operating leverage, maybe that same area or range. As we've mentioned before, the wealth management is an area that we made some leadership changes in this year and late last year, and we've added some really strong leaders, but we'll need some strong producers or wealth advisors to add into '27 and '28.
I think that you'll see us invest in our wealth management business in '27.
Jared Shaw
Okay. All right, thanks.
I guess on the fee income side, the guide for 4Q implies sort of a continued healthy growth. Should we think that that could start to accelerate once you get traction with the planned wealth management hires?
Dan Geddes
Yes, and I'll point out the fourth quarter is impacted by a put that we put in place for some Treasury bill bonds that we're going to purchase in January. They're $250 million each for three-year, four-year, and five-year that we decided to exercise a put, and we have about $5.5 million benefit to non-interest income in the fourth quarter.
That's going to help that fourth quarter growth number.
Jared Shaw
Thanks.
Dan Geddes
I guess, going into your question on wealth management, yeah, I think there's a lot of factors going into next year. I would say that it's just too early to tell.
There's a ramp-up from the hiring to the advisor producing. I would say that a typical ramp rate might be 12 to 18 months before that producer is really paying yourself back.
I think it'll be a long-term investment.
Operator
Our next question is from Ebrahim Poonawala with Bank of America. Please proceed.
Ebrahim Poonawala
Hey, good afternoon. I guess maybe I'm thinking about it the wrong way.
When we think about, or at least when I think about the branch expansion, I do believe as you get sort of customer primacy, that should drive deposit growth. Your non-interest-bearing deposit growth has been quite strong, including this quarter.
Just talk to us, as we look forward the next year or two, is it your expectation that loan growth will exceed deposit growth? Is that a result of it's too competitive, and given the makeup of your balance sheet, you don't need to be super aggressive to chase rate-sensitive deposits?
Dan Geddes
I think that, right now, with the interest rate environment, there still is an opportunity for both individuals and corporate controllers to go seek yield. Deposit growth has been, just for the industry, below loan growth.
We're certainly, I think, hitting above our weight in both categories. I would say for the near term, you're probably right in that we have the ability to go acquire relationships with that loan growth.
We're not going out there growing our loan book just to grow it. I mentioned kind of that owner-occupied category.
Those loans are specifically designed as relationship loans. They're not transactional real estate loans.
I think over time, I think we've shown the ability to grow deposits, in a lower interest rate environment at a higher rate. I think that's the backdrop, Ebrahim, is just the interest rate environment that would hinder deposit growth.
Ebrahim Poonawala
Got it. Just wanted to follow up.
I think if I heard it correctly, Phil, in your prepared remarks about half the mortgage customers new to the Frost, and I believe I think you said 1/3 of those added a second product?
Phil Green
Almost half.
Ebrahim Poonawala
Almost half. I guess my question was historically, we viewed the mortgage product as commoditized, rate-sensitive, moves to the securitized market.
Are you seeing just based on what you've seen over the last year or two as the mortgage product reliably becoming something that becomes a relatively sticky client acquisition tool? Sounds like it's happening at least with half the customers.
Phil Green
It is. I said almost half.
It's really almost 40%, but still a really good number as far as the secondary products they're bringing on. Ebrahim, you're right.
That is how we're seeing it. I might recall when they have talked about this before, but we had a rule around here when we started offering this product that nobody could say that we were going in the mortgage business.
In fact, if you did, you had to pay $5 to whoever's It cost me $60 in one meeting. I screwed up and said it.
What we wanted is to offer a mortgage product, okay, because we had four of the five consumer real estate products, but we didn't have mortgage. We were getting the call to have it.
We just wanted a high-service product that we service, that we would integrate with our overall customer service processes for and including on your mobile app. It's all there, very integrated and elegant way, a great customer experience as you go through it.
In fact, someone told me last week, I won't name the bank, but it was too big to fail, and that they had gone through the mortgage process in our Austin market. Said, "It pains me to say this, but I had a fantastic experience."
It's all about providing a product that really expands our relationship. We're servicing them, and so we have a lot of flexibility in terms of how we price them and other things.
I would say another thing that drove us this way is we're creating this amazing distribution network around this state of Texas, which is tremendously powerful economic environment, and it's a natural to have that product to push through that distribution system. All those things worked together.
One other thing I'll say, Ebrahim, and it's a different way of doing it, but we don't have any sales people, any commissioned salespeople on the street. We just have advisers that help people get into houses, right, and get through the loan process.
All those things like that, the commission part of the business and the selling of the assets and all that was a part of the, quote, business that we were in before. We're not doing that today.
We're really offering a high-quality service product that people are really enjoying, and we're being really successful in doing it. That's the way we're thinking about it.
I hope I've captured your question within that.
Ebrahim Poonawala
No, that's helpful. If I may sneak in just a follow-up to Dan's response earlier about maybe you could do more than 12 to 15 branches per year, what's the constraint there?
There's a Midwest bank expanding into Texas, 150 branches over the next three years. I'm assuming you mastered the art of opening a branch and the science behind it.
Is the constraint capital, expenses, or finding the right bankers for why that 12 to 15 could not be 2x?
Phil Green
It's all those things. I think that we have, if we wanted to, we could expand that 15.
We have, in a sense, warehoused some of our future locations because we knew others were going to be coming into these markets, and I didn't want to be behind the curve like we were, 20 years ago when Wachovia tried to build an organic network in Texas before they failed. They bought up all the great sites, and it was impossible to get a site if you wanted a bank site.
We, a couple of years ago, began putting together sites in communities that weren't quite ready for it, but we thought would be ready for it in a couple of years. I feel confident about our warehouse, if you will.
It's really important to have the right people, and because it's not just a great location and a great facility. We could put up 100 branches, and it wouldn't do anything.
You've got to have the right person leading, and you've got to have the right processes that integrate with your other lines of business and a coordinated approach to developing a trade area, which is what these branches are built to do. That takes time.
Could we scale it? Yes.
I'm not confident we would do it quite as well as we're doing right now. Will we be doing more than 15 at some point?
Of course, we will, because the math of it is that to get a consistent percentage on your base that's growing, it has to grow. Right now, I think giving you guys an indication of 15 or so, 12 to 15 or so a year, I think that's a good indication.
We'll let you know if we decide, and you'll see it if we decide to ramp it up.
Dan Geddes
The only other thing I'll add is that when we started, I was updating the management team in Houston, and then we moved into Dallas. The Dallas and then Houston, and then we moved into Austin.
Now we really have it going statewide where we are updating the management team for each of our major regions. That, I think our reach now is not just one region or two regions.
It's really looking for the best people statewide.
Ebrahim Poonawala
Got it. Thank you.
Phil Green
Thank you.
Operator
Our next question is from Peter Winter with D.A. Davidson.
Please proceed.
Peter Winter
Thanks. Good afternoon.
I wanted to talk on expenses first. Just based on the updated guidance, the expense growth is 5% this year versus around 10% the prior two years.
Do you think mid-single digit is the good level of expense growth for next year? Then, secondly, do you see opportunities maybe to leverage AI to increase productivity and efficiency and maybe self-fund some of these investments to help with the expense growth rate?
Dan Geddes
Peter, the mid-single digits, I think next year, as I mentioned, we're going to have some investments in wealth management. I would anticipate it being a little higher than just right in the middle, but not get back up to the high-single digits.
That's just my expectations without having to gone through the entire budgeting process. I do know that we'll be investing there.
To your question on AI, I think at some point, we will get to realize self-funding AI projects. I wouldn't say that we're there yet.
I would hope in the near future that that's the case to where you can get efficiencies and see it through your expense growth.
Peter Winter
Got it. Then just on credit, nice to see the decline in non-performing assets from the resolution of that multifamily loan.
Are there any portfolios that you're watching more closely, especially as rates are moving higher?
Phil Green
Peter, I think they relate still to commercial real estate. As we've said before, there are still a few of these older vintage multifamily projects.
I think we probably have four of them. They have different maturity dates.
I think this is this year?
Dan Geddes
This year.
Phil Green
I think one of them is this year. There may be two in '27 and one in '28.
They're the same song that we've been singing for the last two years, right? Rents are less, harder to lease up, more concessions, expenses higher.
What you really have to rely on is the performance of the sponsor as they either raise the equity needed to right-size it or they go about the process to sell the property, maybe they find bridge financing. Or the other thing is that the market improves to the extent that they're able to meet their necessary debt coverage ratios and those things.
That's the thing that's happening with all those projects to various degrees. I don't have any concern about any of them.
I think that the sponsors that we have are good, and I really think the underwriting that we've done sort of speaks for itself. Because if you take a look at that property that was sold, basically they sold it for what our loan was.
We underwrote it at, I don't know, somewhere from 55% to 60%. To me, that shows that our underwriting standards that were utilized at the time were adequate to meet a really unfavorable situation, and that's one of the things that gives me confidence as we look at the remaining deals.
Interest rates impact things, and so we'll continue to look at those as we move forward. That would be the one that I think we look most closely at.
Dan Geddes
Peter, I think anything interest-rate-sensitive, homebuilders are feeling the margin pressure if they're offering interest rate incentives for people to buy their homes. I think, homebuilding, I think we have about $290 million in that category to loans to homebuilders.
It's not a huge part of our portfolio, but we're watching that. The consumer has held up really well.
I think our charge-offs were 25 basis points on the consumer side, and I think our past-dues were under 1%, which that's a good signal for the health of the consumer and what we see.
Peter Winter
Got it. That's really helpful.
Thank you both.
Operator
Our next question is from Ryan Kenny with Morgan Stanley. Please proceed.
Ryan Kenny
Hi, good afternoon. Thanks for taking my questions.
I have one on the non-interest-bearing deposit growth. I'm guessing part of that comes from the treasury management investments you've been making pretty consistently over the years and ability to win commercial operating accounts.
Is that part of what's driving the growth, or is it more on the consumer side?
Dan Geddes
Right now, we're seeing it in what we call DDA, which is what you just mentioned, kind of the commercial side where yes, I think our investment in our treasury platform and the customer service that our clients receive from our bankers and their teams, I think is really what sets us apart. That's a lot of times, it's the ease of doing business.
That's an area that we get rated really high in terms of when we're evaluated by Greenwich Associates. We have the sales force in terms of the people, and it's paired with really great technology and I would say kind of the back-of-the-house customer service.
When somebody needs help 24/7, they can pick up the phone and get ahold of a person. I think that all those things play into our ability to grow those core DDA accounts.
I think it goes back to our branch expansion that we're going into communities and targeting both consumers and commercial businesses in the markets that we're entering. We don't put a branch up just anticipating retail balances and offering either really out-of-market CDs or any sort of teaser to come over.
It's we offer a square deal, we offer incredible customer service paired with world-class technology.
Ryan Kenny
Is your sense that the competition in treasury management is getting more intense as new entrants enter Texas and as the technology landscape evolves? Are there any numbers you could share on the percentage of commercial clients that have a treasury management relationship with you?
Dan Geddes
I don't have that at my hand, but we can get that and get that to you. What I would tell you on just the competition is I don't think it's any different than what we've faced before.
I think it's certainly competitive out there, but a lot of times for the commercial, it's part of a whole package. It's not just, "Hey, I have the best technology," or "Here's something that you might find useful in your business."
It's part of the whole relationship. It could be paired with a line of credit, it could be paired with an equipment loan, it's not just in and of itself.
It's part of who are you going to be dealing with. I think that's where we really shine, is our people out in the marketplace.
Ryan Kenny
Thank you.
Operator
Our next question is from Janet Lee with TD Cowen. Please proceed.
Dan Geddes
Hey, Janet.
Operator
Janet. Please check if your phone is muted.
Janet Lee
Oh, sorry. Hi.
Can you hear me?
Dan Geddes
Hello.
Operator
Yes. Yes, Janet.
Janet Lee
Hello. Hi.
Sorry about that. Just want to make sure that I'm understanding your NII guide for 2026 correctly.
If you assume kind of the midpoint of your average loans, deposits, and NIM, when we layer in loan beta at the 80% and deposit beta at the 50% to 55%, it's hard to not be above your 5% to 5.5% NII growth for 2026. I'm just wondering if there was any front-loaded benefit from loan yields in the third quarter, or if there is anything that is missing?
Dan Geddes
I don't I don't have anything that I would say that that we're, necessarily holding back. Our our one cut, our one hike, I'm sorry, was it's projected in December, and so it doesn't have much of a benefit in in 2026.
It would really be more of a 2027 benefit. I I think it's, it'll be, it'll be determined by volumes.
If we're able to achieve, either higher loan volumes, what we're, I I just I think that, if we're able to achieve higher volumes and higher-yielding assets, then maybe there's some there's some upside there.
Janet Lee
Hey, Dan,
Dan Geddes
a little inside baseball here, and I'm stepping out on a ledge, but with that credit that paid off, I know sometimes there's accrued interest that happens and That was in the third quarter, we had a nonaccrual loan that was paid off, and I want to say it was about a $3 million benefit to the third quarter, which helped the NIM in the third quarter.
Janet Lee
Okay. Got it.
Kind of circling back on your interest-bearing deposit beta comment, I believe the increase in interest-bearing deposit costs in the third quarter reflected the pricing actions you took on a good portion of your money market balances in June. You're effectively getting ahead of the September hike.
Are there similar actions that are on the plate? How should we think about the magnitude of the pricing increase on your deposits?
Dan Geddes
I guess I'll kind of mention that we mentioned last quarter that we were increasing our money market rates in these consumer tiers under $1 million and over $250,000. I'll just kind of tell you kind of how that's been playing out so far, is we had seen that those tiers decline in balances in the second quarter around 3% in those tiers on the consumer side.
We were able to actually see a slight increase, I want to say around 1%, but more importantly, we kind of stemmed the tide of seeing balances go out of those. The idea around that strategy was to capture more of the wallet share of this consumer that we're picking up that was much younger.
It was the Gen Y and Gen Z customer that we mentioned. I think we've been pleased with that program.
I think, when I look kind of out into the fourth quarter, and I just kind of try to kind of see, okay, what are we looking at in terms of just our cost on interest-bearing deposits going out into the fourth quarter with those changes? I think, with that interest rate hike in December, right now, we're looking at, gosh, I would say, deposit costs, total interest-bearing growing around 10 basis points from a 1 170.
There'll be an impact in the interest-bearing side.
Janet Lee
Okay.
Dan Geddes
From 1.73% to around a 1.87%, around 12 to 15 basis points.
Janet Lee
Right. Do you have a spot NIM?
Dan Geddes
Let me get back to you with that.
Janet Lee
Okay. Thanks.
Dan Geddes
I did want to answer that one question, I think right now that someone had asked on commercial customers on Treasury, and approximately 7% of our commercial customers are on our Treasury platform.
Janet Lee
Thank you.
Operator
Our next question is from John Pancari with Evercore ISI. Please proceed.
Girard Sweeney
Hey, good afternoon, this is Girard Sweeney on for John. Just one on the buybacks.
Dan Geddes
Hey, Girard. Hey, Gerard.
Girard Sweeney
On the buybacks, slowed down this quarter from recent quarters. How much of this was determined by the securities repositioning you had in the quarter versus the higher rate backdrop more broadly, or even where the stock was trading in the quarter?
Then looking ahead, how's your outlook compared to that $70 million to $90 million quarterly cadence that you had over the past year or so?
Dan Geddes
Girard, it was more to do with we had discussed kind of having a consistent buyback approach. There's a component of us just being in the market.
Then, I would say the delta between what we had done in the previous quarters to the $15 million that we did in the third quarter was really just the market. We were just looking at how our stock was trading and relative to the index.
Then also just wanting to hold back some powder in case of some macro event that we could utilize the balance.
Girard Sweeney
Got it. Thank you.
In terms of forward implications, really anything to think about outside of where the stock's trading like you mentioned?
Dan Geddes
I'm sorry, repeat that?
Girard Sweeney
Just on the forward implications, and just getting back to maybe that more typical cadence that you talked about, the more consistent cadence?
Dan Geddes
Again, I think that we'll kind of have that kind of three-pronged approach is be consistent with a component, have another that we kind of feel like we can use strategically during the quarter. Then, again, if you want to think about a third, a third, and a third, but a third that we would just kind of hold back for some level.
We feel good if we end up the year in the $190 million to $200 million, I think we'd be happy with that.
Girard Sweeney
Thank you very much. Then just one quick one on expenses.
Given the continued branch openings, investment in wealth, if the revenue growth slows down a bit, do you think you have the levers to still achieve positive operating leverage in '27?
Dan Geddes
Just I think there's an opportunity. will have to make sure that we've really looked at the investments we want to make from a technology standpoint, we've talked about the branch expansion and then the wealth management.
What I do think that depending on how many rate hikes we see in the forward curve, I think there's an opportunity to have a similar positive operating leverage that we were anticipating for '26.
Girard Sweeney
All right, great. Thank you very much.
Operator
Our next question is from Casey Haire with Autonomous Research. Please proceed.
Casey Haire
Great. Thanks.
Good afternoon. I wanted to circle back on the beta guidance of 50% to 55%.
That's a little bit higher than what we saw from you last cycle. Does that still hold, each 25 bip hike is good for $2 million of NII a month, or is that higher beta knock that down a little bit?
Dan Geddes
It's a little bit below that, but we're looking at around $1.5 to $1.7 million.
Casey Haire
Okay. All right.
Then just going back to the loan-to-deposit ratio question. At 55 today, is there a ceiling?
You guys have a lot of runway to move that higher. I'm just wondering, is there a level where you would not want to see that go to or exceed?
Phil Green
I think we're way off of where we were at a previous high. That was man, when was that?
That was, I think, right around the Great Financial Crisis or so. I think we may have gotten to 80% for one month.
That's still way below peer. That's an area that begins to impact your thinking in terms of funding acquisition, what you're willing to do to support continued growth there.
I think that the answer is, I don't think we have a specific number. Directionally, what we want to have over time is a consistency in the level of loan growth we're generating, compared to the level of deposit growth that we're generating.
On a long-term basis, we think that somewhere in the mid-to-high single digits for both of those would be optimal over the really long period of time. That would be what I would hope to see.
I love operating with a lower loan-to-deposit ratio because it gives you optionality in terms of what you do with your balance sheet. The real benefit and value of any banking organization is in the deposit franchise.
It's really not in the asset franchise. Just something that comes to mind is that I looked back historically, I think the latest I could get to was 90 years ago or so.
If you look at the compound annual growth rate of our company over that 90-year period in terms of absolute size, which would imply the deposit growth, it was 8.85% over that 90-year period. I think over the long term, we've demonstrated the ability to have a balance between deposits and loans, and I'd hope over the long term going forward, we'd see that same thing.
Casey Haire
Got you. Okay.
Just one last one. The bond book restructure, was that late in the quarter?
Just any help you could give us with where the bond book yield would be in the fourth quarter? It sounds like they were very low-yielding securities that you sold.
Dan Geddes
Yes. I think that it was at the end of the third quarter where we made those sales with the loss.
Your second question was just kind of looking at where we think our bond portfolio will be in the fourth quarter. I would say overall, you're going to look at around a 4.15%, 4.20% in that ballpark.
Tax-equivalent.
Casey Haire
Thank you.
Operator
Our next question is from Michael Rose with Raymond James. Please proceed.
Michael Rose
Hey, good afternoon. Thanks for taking my questions.
Maybe just going back to to Ebrahim's questions on the branch expansion. Phil, I think you said nearly half of the incremental loan and deposit growth is is coming from those branches.
From from when you started this, 10 or so years ago, these expansions, has the has the opportunity and and, the the size of these branches, the profitability of these branches, has it evolved over time? I think you probably learned a bunch from what you did in the early days in Dallas and Houston 1.0.
It seems like it's continues to be a really good opportunity for you guys to to drive growth and and ultimately profitability. If you can just talk about, kind of the evolution of, the branch expansion over the year, breakeven, deposit size, any sort of details, because it seems like it's pretty compelling at this point, particularly given some of the dislocation that we're seeing across the Texas markets with M&A.
Dan Geddes
This is Dan. I'll jump in, and then let Phil fill in any gaps that I leave.
When we started the Houston expansion, it was really a commercial-centric in terms of the loan side, and then kind of a 50/50 deposit opportunity. We executed that, and it was really successful.
As we entered into the Dallas expansion, and we saw that we were really growing consumer loans in Dallas faster than we were growing commercial loans. It really gave us this opportunity to kind of take a step back and say that this could be not our kind of Frost typical let's find a high commercial, small business market, but we could go into some consumer markets.
We actually have one in the San Antonio area that just knocked it out of the park, and it was all a rooftop play. It does really good on the commercial side, but the consumer side has just done really, really well.
It gave us kind of a realization that it doesn't have to be one or the other. It can be all of it.
We went back in and we did a 2.0 in Houston. Then it really kind of set us up for the Austin market because you think about the Austin dynamics, and it's going to be a little more consumer-centric.
With our I think 17 years now of J.D. Power awards on the consumer banking side, that we can grow this into a great consumer experience, and grow our consumer deposits with our new make sure I don't have my $5 bill, and I say our mortgage product, not getting into the mortgage business, that with our mortgage product, it really you've seen that be a factor now with the loan growth we've had in the mortgage business.
I think they're all complementary, and I was looking at some economic data from an economist that looked at growth in Texas. The growth in Texas in population is going to be around 2.5 times the growth rate of the United States.
About one in every four of kind of population growth will be in Texas over the next five years. We have customers coming to us from other states.
This is a great opportunity for us to go into, I would say greener markets than maybe we would have gone into at Houston 1.0 because of the confidence that we have on the consumer side. I think you've seen our ability.
We think we do it better than anyone in the country. We think the results show it in terms of our ability to grow deposits, especially in these markets that we're entering.
Phil Green
Dan, I think you've done a great job of explaining that evolution, and just to give you some insight into our overall thinking as we look forward. Today, we're about, I don't know, a $55 billion or so company.
Our deposit base is roughly half consumer and half commercial. As we make our way towards a $100 billion organization, and that'll take some time, but we'll get there, I'm very confident that we're going to continue with that same relative mix.
What that means is, as you look at Cullen/Frost as a $100 billion Texas organization, that with that same mix, we're going to be a $50 billion consumer bank in the state of Texas. I don't know of a $50 billion consumer bank in the state of Texas right now.
Maybe part of the too-big-to-fail has got that, but that's a really big consumer bank. It made sense to me that we're evolving into a company that has this developing expertise in tapping these consumer markets, because that's who we're going to have to be as we continue to grow, and as our size gets to be at that level.
I'm really encouraged by the fact that we have the chops to compete in the consumer markets. It's not just being able to compete on physical distribution, although that is very important, you've got to have the technological chops to meet the customers' needs today.
If you look at the J.D. Power reports that Dan referred to, at least the last one that I looked at, and for the several that I've looked at, we have the number one ranking in digital satisfaction.
We spend a lot of money to keep it there. That's one of the reasons why our expense growth is high, along with the other things that we invest in to make sure our service levels are high.
This ability to compete on the consumer side, in addition to what we've always done in the middle market commercial, I think is a big positive. It's just another reason why this mortgage product is an example of leveraging that franchise and being successful at it.
We've raised $1 billion in great assets since we've put this product in place, and they're great relationships in addition to that. I'm just so confident of our ability to develop this Texas market.
I really hope that you all are sensing that These are not just numbers, these growth rates, that are really good. I've been in this business a long time.
I know a good growth rate when I see one. It's more than just numbers on a page.
We're just being successful day-to-day, relationship to relationship, and the value proposition's working, and we're in the best markets you could ever conceive being. I'm very encouraged with what we've got going on here.
Dan Geddes
Just one other thing to add is that when we look at our branch share to market share, when you look at some of the markets that we've been in for a really long time, San Antonio, Austin, even Fort Worth, our deposit share exceeds our branch share. For instance, San Antonio, our headquarters, we have about a 10% branch share, but a 27% market share.
In Austin, it's around 6% branch share and around 7.5% deposit share. Fort Worth, 6% branch share, then almost 11% market share.
Where we started in Houston, back in 2018, we were at a 2.6% branch share and only a 1.8% market share. Now, we've increased our branch share in Houston to almost 5%, and our deposit share to 2.3%.
We've grown it 50 basis points. It has a lot of room to run.
In order to even get at par with our branch share. In a similar trade in Dallas, where back in 2019, it was a little under 1.5% branch share, and a little under 1% market share.
Now we're up to almost 4% branch share, and the deposit share has grown 20 basis points, 1.1%. You see the opportunities in both of those markets for us to continue to invest and to continue to gain market share.
Michael Rose
Very detailed response. I appreciate all the thoughts.
That is very helpful. Maybe just one quick follow-up for you, Dan.
I think last quarter, you maybe discussed adding some forward starting swaps. Any changes, or any updated thoughts there?
Thanks.
Dan Geddes
We haven't added any more than what we already had put on. I think we got about a 200 basis point spread over what we were paying fixed on that one, and I think it's a little bit under maybe 30, 40 basis points below that right now.
I think we'll likely put one another on. Our plan is to kind of put one on about every year.
This one we put on is a two-year forward starting swap, and if we put another one on next year, and then another one, and over about four or five years, we should have between $2.5 to $3 billion built up. will certainly evaluate opportunities as they come.
That's kind of the thought process, as we start getting closer to $100 billion, if they raise that limit, we'll look to lower that duration of our bond portfolio over time, and that can be an effective tool to do that.
Michael Rose
All right. Helpful.
Thank you.
Operator
Our next question is from David Chiaverini with Jefferies. Please proceed.
David Chiaverini
Hi, thanks for taking the questions. On the net interest margin, very nice expansion over the last several quarters to 3.78%, with mix shift driving the expansion.
Does the tailwind of mix shift have legs looking out over multiple quarters?
Dan Geddes
I would say yes, but depending on the shape of the yield curve, right? If it's positively sloping, I think we still have several years where we'll be repricing either fixed-rate loans or our investment portfolio into higher-yielding assets.
Just to give a sense, and I've given these numbers before, I can kind of just help a little bit with kind of where we see that opportunity on our fixed side. We have in the fourth quarter just around $275 million in fixed-rate loans that are rolling off at a 5.25%, and that we could likely get around 7.25%, there's pretty good pick-up there.
Next year, we have a little over $1 billion in fixed-rate loans anticipated to run off, and they have a run-off yield of around 5.70%, and we likely are modeling a similar 7.25% rate. There's an opportunity there.
Then just on our securities portfolio, for the fourth quarter, we're looking at around $800 million at around 4%, 4.1% that it will either mature or prepay. Then in '27, it's around two around $1.9 billion, and around about a 4.5% interest rate.
David Chiaverini
Very helpful. Thanks for that.
Then you mentioned earlier about how market disruption has been a source of new relationships, up 73% year-over-year. Are you able to size how much of your loan pipeline of $2.5 billion is from disruption in the market versus grassroots loan demand?
Dan Geddes
Let me see if I can find that. Right now, let's see.
Let me see if I can get that for you. What I can tell you is, I would say, this is for the year-to-date, we've created about $250 million in opportunities.
It's not, I would say, a huge component of our overall opportunities that we create. It's probably in that same, I would say, if it's representing 10% of our new relationships, it's probably 10% of our prospect opportunities.
It's a lot more than it was. I think that that's probably the best way I would describe it, is that we're seeing it increase probably twice as much as what we were doing last year, just because of the raw numbers, and we're winning 80% of them.
David Chiaverini
Very helpful. Thank you.
Operator
Our final question is from Jon Arfstrom with RBC Capital Markets. Please proceed.
Jon Arfstrom
Hey there. Thanks for hanging around with us.
Phil, one comment on the pipeline. You made a comment earlier that the weighted 90-day pipeline was up I think 15% or 16% sequentially from the prior quarter.
Dan Geddes
16%.
Jon Arfstrom
Yeah. That's a big number, and I think I asked this a couple of quarters ago, but that's another big number.
What would you attribute that to?
Phil Green
A lot of things. It's fairly broad-based.
I will say I'm aware of some large commercial real estate opportunities that are included in there, but I wouldn't say it was all commercial real estate. Dan, you've got some numbers there that give some insight into it?
Into just our our
Dan Geddes
Our growth in our
Phil Green
weighted pipeline.
Dan Geddes
Weighted pipeline. It's it's it's substantially above kind of where it's it's been.
This this time last year, it was $1.88 billion, $1.85 billion. What's what's encouraging is it it's about 2/3 weighted towards customer, and 1/3 weighted towards prospects.
John, what I what I kind of mentioned is typically, if it's a customer, we on a weighted on a kind of a dollar basis, we usually close about 2/3 of those just over a long period of of of history, and then prospects about a third. It tells me a couple of things.
It tells us it tells me that our customers are despite all the uncertainty out there, that they're active, and they're still looking to grow, and they still see opportunity in in this environment. You've seen you've seen that.
It's it's a pretty good split, you know. You have about you had a little bit of an increase in C&I.
Again, there was a a a bigger growth in the CRE growth. I would say that that's that's that's more of our customers in of CRE.
That to me means that these are relationships we have over years, and it's not us going and stretching on structure. It's it's our customer base that's active, and they're looking for us to be their financial a resource.
Phil Green
I think one thing also that is great about that weighted pipeline is we've looked at the correlation between fundings and that pipeline. It's actually pretty strong.
We've had the process for a number of years, and it's really a part of our sales effort on the commercial side. When I see that number being up at that level, it really gives me some confidence.
Dan Geddes
Just looking at which regions, it's basically led by what you'd expect. Dallas was actually up the most, and then Houston, San Antonio, and then Austin.
Kind of four of our core markets are driving a lot of the expectation for closings in the fourth quarter and to start '27.
Phil Green
What that really means, and Dan did a good job of outlining, it's just nothing unusual, there's nothing weird driving this activity or this success. It's pretty much basic boots on the ground, really.
Jon Arfstrom
Okay. That's good.
Just a small question. Phil, my earnings model goes back 25 years, not 90 years.
In all those earnings calls, I don't think I've ever heard the term "motor bank." Dan, can you just touch on the branch sale, what that was all about so we can understand it?
It was just, it seemed kind of random.
Dan Geddes
This probably stems from some property when we acquired a bank in Fort Worth. Phil has a memory.
Phil Green
I would say, John, maybe you'd call it a drive-through lanes or standalone drive-through.
Jon Arfstrom
It's
Phil Green
not a bank on wheels. It's where you drive up to the teller kiosk and they take care of your business in an automobile.
That
Dan Geddes
bank drive-through. Like if you're, yeah.
Jon Arfstrom
That's just cleaning up a couple of branches that don't fit. That's simple as that.
Phil Green
I can't believe you haven't heard the word "motor bank," man. Maybe that's just a Texan thing.
Motor bank, man. That's what it is.
Jon Arfstrom
All right. Thanks, guys.
Dan Geddes
Thank you.
Phil Green
Welcome.
Operator
There are no further questions at this time. I would like to turn the floor back over to Phil for closing remarks.
Phil Green
All right. Thanks, everyone.
Great questions, great interest that you show, and we appreciate it. will be adjourned.
Thank you.
Operator
Thank you. This will conclude today's conference.
You may disconnect at this time, and thank you for your participation.