Corby Spirit and Wine Limited Class A
Q1 FY2027 · Earnings Call TranscriptNovember 13, 2026
Florence Tresarrieu
Good morning, everyone, and thank you for joining us to review Corby Spirit and Wine's first quarter fiscal 2027 results. For those of you who may be joining us for the first time, my name is Florence Tresarrieu, President and CEO of Corby.
Joining me today is our Chief Financial Officer, Juan Alonso. Corby delivered a solid start to fiscal 2027, with continued growth in RTDs and improved earnings, despite a challenging market environment.
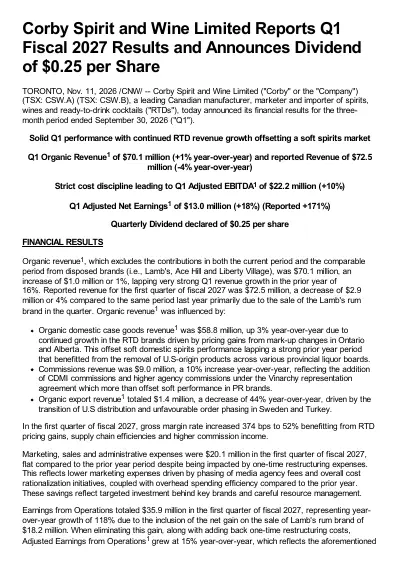
Organic revenue grew plus 1%, supported by our RTD portfolio and higher commission income, mitigating a soft domestic spirits market, while reported revenue declined minus 4%, reflecting the sale of the Lamb's rum brand. Adjusted net earnings grew plus 15— 18%, significantly ahead of revenue, reflecting gross margin improvements on RTD brands and disciplined investment behind our brands, with a continued focus on costs.
Supported by a strong cash generation, our balance sheet remains strong, with net debt to adjusted EBITDA of 0.6 times, or 0.8 times if we include the $18.7 million upfront fee payment for the Pernod Ricard representation agreement signed on October 1st, 2026. The board declared a quarterly dividend of 25 cents per share, up plus 9% compared with Q1 last year.
This performance very much reflects the resilience of our portfolio, the quality of our execution across multiple categories, and our continued focus on creating sustainable long-term value for our shareholders. While this is a solid start to the fiscal year, we remain prudent, given continued pressure in the spirits market, an evolving consumer environment, and macro and geopolitical uncertainties.
We can turn now to the market context. Complete first quarter Ontario market data was not available at the time of reporting.
Given the significance of Ontario within the Canadian spirits and RTD market, presenting results without Ontario would not provide a representative view of national trends. For that reason, the following slides reflect the latest available market data for the period ending August 31st, 2026.
Furthermore, per LCBO November 6th, 2026 update, Ontario data for weeks 1 to 20, encompassing April 1st through August 15th, are being republished to address known discrepancies, with completion expected by the end of December 2026. As a result, retail sales data may be subject to change based on the restatement.
Over the most recent three-month period ending August, market conditions have remained challenging, with some of the FY '26 tailwinds normalizing. The spirits market declined 3.7%, while our spirits portfolio declined 6%.
RTD remained resilient, with Corby outperforming the category, and wine was softer. This is a normalization, as we lap very strong performance last year, and we remain very much focused on the longer-term strength of our portfolio and the opportunities ahead.
Looking at the rolling 12 months, Corby continued to outperform the market across all three categories. In spirits, we outperformed the market by 2.5% in spend.
Our RTD portfolio grew 7.7%, 5 points ahead of the category, while wine grew 6.3%. This demonstrates the benefit of our diversified portfolio and the strength of our positions across categories, in particular in RTDs.
Looking more closely at spirits, the category remained under pressure, but Corby continues to perform ahead of the market. Over the rolling 12 months, we outperformed across major spirits categories, particularly strong relative performance in Canadian whisky, tequila, vodka, and rum.
This reflects the strength of our brands and disciplined commercial execution, and we remain focused on continuing to gain share in a challenging market. In recent months, we've seen a sharp increase in promotional activity in vodka.
In Canadian whisky, we're also seeing a decline as we lap the strong growth from last year following the removal of US products from shelves. Taken together, these factors explain some of the recent softness in our spirits portfolio.
Over the last 12 months, our RTD brands have continued to gain share, supported by innovation, strong commercial execution, and an expanded route to market. In the short term, Corby RTD brands continue to outperform as category growth normalized.
Nationally, Corby RTD volume grew plus 3.8% in the last 6 months, and achieved a market share of 10%. Cottage Springs maintained its position as the number 1 RTD brand in Ontario, while Ace Beverage Group continued to deliver strong momentum in Western Canada.
Also, Canada Dry Mott's, CDMI partnership, added meaningful scale to our RTD portfolio. Innovation remains important.
Cottage Springs and J.P. Wiser's and Canada Dry were among the leading RTD innovations in Ontario, demonstrating our ability to stay close to consumers and respond quickly to changing preferences.
Our strategic direction remains very much unchanged. We will continue to invest behind our strong brands and opportunities to gain share in spirits and accelerate our position in RTD and other attractive growth categories.
We will remain disciplined on pricing, promotional investments, and costs, while continuing to actively manage our portfolio and direct resources towards the areas with the greatest potential. The market remains dynamic, but we are confident in the fundamentals of our business and our ability to adapt, execute with discipline, and create sustainable long-term value.
With that, I will hand it over to Juan to take us through the financial results.
Juan Alonso
Thank you, Florence, and good morning, everyone. I'm Juan Alonso, Corby CFO, and I'm going to walk you through our financial results.
Before we get into the numbers, you're going to notice reference to adjusted metrics and organic revenue growth throughout this section. We believe that these non-IFRS financial measures support a better understanding of our underlying business performance and trends.
We provided detailed explanations for each of those elements in our Q1 FY '27 MD&A, and I invite you to refer to this document for any questions related to it. Corby delivered a solid first quarter, with revenue of $72.5 million, down minus 4% year-over-year due to the sale of Lamb's rum brand on August 5th.
Excluding the impact from disposed brand, organic revenue grew 1%, lapping very strong Q1 revenue growth in the prior year of 16%. This performance was driven by RTD portfolio growth, and despite a soft spirits market and a high prior-year base from the removal of US products from shelves.
With strategic investments behind key brands and diligent control of expenses, our adjusted earnings from operations reached $18.9 million, up 15% year-over-year. Adjusted earnings per share was 46 cents, up 18% year-over-year, while reported earnings per share was 90 cents 97 cents, up 171% year-over-year due to the inclusion of the gain on sale of Lamb's.
In Q1, Corby generated cash from operating activities of $7.4 million, which is $1.8 million more compared with the same quarter last year. Lastly, the board approved a quarterly dividend of 25 cents per share, which represents a 2 cents or 9% increase versus the dividend declared in Q1 FY '26.
This reflects our confidence in our outlook and ongoing commitment to shareholder returns. Turning to the drivers behind our $72.5 million Q1 revenue, down 4% on a reported basis while up 1% on an organic basis.
Firstly, the case goods, which accounted for 82% of Corby's Q1 net sales performance, reached $59.4 million, reflecting a minus 3% reported contraction, but plus 3% organic growth versus Q1 FY '26. This was driven by continued growth in RTD brands, driven by price gains from mark-up changes in Ontario and Alberta, partially offset by soft domestic spirits performance against a strong prior-year period.
Total commissions made up 12% of Q1 net sales and was $9 million, an increase of 10% versus the prior year, impacted by the addition of KDP commissions and higher agency commissions under the VinArqui representation agreement. This more than offset softer performance from Pernod Ricard brands.
Lastly, export revenue, which contributed 4% to total net sales, landed at $3.2 million, a decrease of 35% on a reported basis versus Q1 FY '26 and 44% on an organic basis. This was driven by the transition to a new distributor in the US market and unfavorable order phasings in Sweden and Turkey.
Moving to the next slide, Corby achieved a strong Q1 adjusted earnings per share growth of 18%, reflecting continued RTD revenue growth and cost rationalization initiatives. Total operating expenses decreased 7%, primarily reflecting gross margin optimization in RTD brands and lower overhead costs from efficiency gains, despite being impacted by one-time restructuring costs in Q1.
With this, Corby delivered Q1 adjusted earnings from operations at $18.9 million, which is up 15% year-over-year, and reported earnings from operations of $35.9 million, up 118% year-over-year, which was impacted by the recognition of one-time gain from the sale of Lamb's. In Q1, Corby generated cash from operating activities of $7.4 million, is $1.8 million more compared with the same quarter last year.
Consistent cash flow generation, reflecting increased earnings and expected seasonal shifts in working capital balances, specifically accounts receivable and inventories, offset by slightly higher tax payments. Free cash flows include proceeds from the sales of the Lamb's rum brand of $37.4 million during the quarter, which is net of transaction-related costs.
Our net debt position was $51.6 million, which benefited from the proceeds from the Lamb's rum brand sale during the period. As a result, our net debt to adjusted EBITDA reduced to 0.6 times from 1.3 times at the end of Q4 FY '26, demonstrating a strong solvency position and reinforcing our financial health.
As mentioned earlier, on October 1st, 2026, subsequent to the period ending September 30th, 2026, Corby paid the upfront fee related to the representation agreement with Pernod Ricard of $18.7 million. With this cash out considered, Corby's net EBITDA ratio is 0.8 times.
Our Q1 performance is a demonstration of the strength of a diversified portfolio, disciplined execution, and a clear strategy. Before I hand back to Florence, a quick look at what's ahead for Corby.
Corby is well positioned to continue driving earnings growth and delivering shareholder returns, despite facing a more challenging comparison basing following its strong performance in FY '26. We also believe we may narrow the gap between earnings growth and revenue growth over the coming quarters.
Our RTD portfolio remains a major growth engine, and we see significant potential to expand across Canada, led by strong traction from ABG. On spirits, our ambition is to continue to fight for market share despite a declining category.
Our diversified portfolio, leading brands, and strong local footholds continue to support our resilience in a dynamic market. In Ontario, we are going to continue to capitalize on route to market modernization, meeting evolving consumer preferences with agility and breadth, taking an agile approach to navigate softer spirits retail store traffic and pricing pressure from the removal of the minimum pricing.
On the financial side, our focus remains on protecting margins and disciplined investments to drive profitable growth. Now back to Florence for closing remarks.
Florence Tresarrieu
Thank you very much, Juan. As we look ahead, we remain confident in the fundamentals of our business, while staying prudent about the market environment.
Corby has a diversified portfolio, leading brands across spirits, RTDs, and wine, supported by our partnership with Pernod Ricard and strong positions across Canada. We've demonstrated our ability to adapt to changing market conditions, invest behind the areas with the greatest potential, and execute with discipline.
With a strong balance sheet and continued momentum in RTDs, we are well positioned to invest for future growth while delivering attractive returns to shareholders. Ultimately, our focus remains consistent: building a stronger, more resilient business and creating sustainable long-term value.
Thank you once again for joining us today. Juan and I are now very happy to take some of your questions.
I can see that some questions are already posted on the chat, I'm happy to answer them. Yeah?
Maybe I'm going to read them out loud, and then share with Juan. The first question from Nick Corcoran from Acumen: 'Polar Ice underperformed the market in the quarter.
Will you invest in price to try to win volume, or protect margin and maintain your share?' I can start answering, and then I will let Juan comment further.
Of course, I'm not going to be commenting specifically on the pricing actions, as I'm sure you will appreciate this is commercially sensitive. What I can say is that I don't think we're satisfied with the Polar Ice performance.
This is very much a priority of the management at Corby to make sure we're restoring the volume growth, or at least improving the trajectory, while maintaining the profit.
Juan Alonso
Yeah. Yeah.
We see as a total portfolio strategy. If there are some brands that we need to react to protect volume, we will do.
We have other brands that can compensate and offset, as it is today, the margin improvement that we have in the ready-to-drink segment. That is linked to the second question.
I'm going to read the second question. Also from Nick: 'Strong margin performance in the quarter.
How should we expect margins to track for the balance of the year?' We did have a very strong margin improvement versus Q1.
I think the first thing to highlight is Q1 last year, when it comes to RTD, it was a low basis in terms of margin performance due to some technical events in Q1 last year. We do have a strong margin improvement, and our earnings are growing much ahead of revenue in the first quarter.
For the following quarters, we intend to maintain the margin that we have in this quarter, but the gap between earnings growth and revenue growth will probably narrow. We're not going to be able to grow earnings much ahead of revenue as we did in Q1, because we are going to be overlapping already some high quarters in terms of margin improvements.
Florence Tresarrieu
Thank you. I don't know if there are any other questions, either on the chat or by phone.
We're very happy to take them if you have any. Over the phone lines, if you'd like to ask a question, please press star, then the number 1 on your telephone keypad.
If you'd like to withdraw your question, that will be star, then the number 2. Again, that will be star, then the number 1 on your telephone keypad if you want to ask question over the phone lines.
Operator
We have your first question comes from Warren Goldblum from Harbourfront Wealth. Please go ahead.
Warren Goldblum
Hi.
Florence Tresarrieu
Hello?
Warren Goldblum
Hi, can you hear me?
Florence Tresarrieu
Yes, now we can hear
Warren Goldblum
you. Yes.
Perfect. Sorry, but I seemed to get the message again.
Florence Tresarrieu
Sorry, we cannot hear you. Sorry, yeah, go ahead.
Warren Goldblum
Yeah. I wonder if you could just give some kind of commentary on the cadence.
If you look at Mott's, the commentary around the...
Florence Tresarrieu
Sorry, the line is actually quite bad, you are cutting out. Do you seem to have a do you...
Operator
Warren got disconnected. Again, if you would like to ask a question, please press star, then the number 1 on your telephone keypad.
Juan Alonso
Maybe if he can write?
Florence Tresarrieu
As he's disconnected, right.
Juan Alonso
Yeah.
Operator
As of the moment, there are no other questions over the phone lines. Florence?
Florence Tresarrieu
That's fine. I don't know if Warren has the opportunity to reconnect, otherwise we'll connect with him.
If there is no further questions, again, I would like to thank you for attending this morning. Thank you for your interest in Corby.
I wish you a very good day ahead, and a good weekend. Bye-bye.
Operator
Ladies and gentlemen, this concludes today's conference call. Thank you for participating.
You may now disconnect.