New Oriental Education & Technology Group, Inc. Sponsored
Q1 FY2027 · Earnings Call TranscriptOctober 28, 2026
Operator
Good evening, and thank you for standing by for New Oriental's FY2027 first quarter results earnings conference call. At this time, all participants are in listen-only mode.
After management's prepared remarks, there will be a question-and-answer session. Today's conference is being recorded.
If you have any objections, you may disconnect at this time. I'd like to turn the meeting over to your host for today's conference, Ms.
Sisi Zhao.
Sisi Zhao
Thank you. Hello everyone, and welcome to New Oriental's first fiscal quarter 2027 earnings conference call.
Our financial results for the period were released earlier today and are available on the company's website as well as on newswire services. Today, Stephen Yang, Executive President and Chief Financial Officer, and I will share New Oriental's latest earnings results and business updates in detail with you.
After that, Stephen and I will be available to answer your questions. Before we continue, please note that the discussion today will contain forward-looking statements made under the safe harbor provisions of the U.S.
Private Securities Litigation Reform Act of 1995. Forward-looking statements involve inherent risks and uncertainties.
As such, our results may be materially different from the views expressed today. A number of potential risks and uncertainties are outlined in our public filings with the SEC.
New Oriental does not undertake any obligation to update any forward-looking statements, except as required under applicable law. As a reminder, this conference is being recorded.
In addition, a webcast of the conference call will be available on New Oriental's investor relations website at investor.neworiental.org. I'll now first turn the call over to Mr.
Yang. Stephen, please go ahead.
Stephen Yang
Thank you, Sisi. Hello everyone, and thank you for joining us on the call.
We're pleased to start the new fiscal year with an encouraging first quarter, with revenue growth exceeding our guidance upper range. In addition to the resilience of our core business, East Buy and our new venture have also contributed outstanding results to the group this quarter.
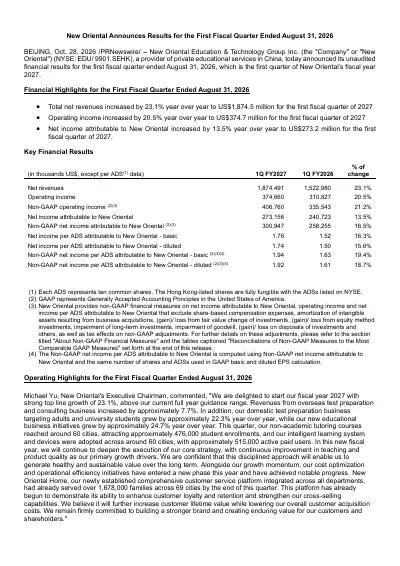
I'm glad to report our efforts across all of our business initiatives have resulted in healthy growth amid economic headwinds and external challenges. In this quarter, total net revenue grew 23.1% year-over-year to $1,874.5 million, and non-GAAP operating income rose 21.2% to $406.8 million.
Our core education business and East Buy recorded year-over-year expansion in their respective operating margins, primarily attributable to the enhanced operational efficiency and improved utilization of our learning centers. I do want to highlight here that East Buy experienced a rapid growth in the past quarter, which means it now accounts for a larger share of the group's revenue, and therefore carries greater weight in our consolidated operating margin.
Please rest assured that our overall margin remains very stable. Yet we would encourage you to also look at each business on a stand-alone basis, as this gives a clearer and more accurate picture of our underlying performance.
As said, all of our business lines continue to maintain healthy margins. At the group level, the consolidated margin reflects both the margin of each business and its relative share of revenue.
Changes in the business mix can influence the overall figure without indicating any deterioration in the underlying businesses. Now, I'm pleased to share the strong momentum demonstrated by our core business and new initiatives this quarter in detail.
Breaking it down: overseas test prep business recorded a revenue increase of about 8% year-over-year for this quarter. Overseas study consulting business recorded revenue increase of about 7% year-over-year for this quarter.
Our adults and university students business recorded revenue increase of 22% year-over-year for the first quarter of 2027. Our non-academic tutoring business has been rolled out to around 60 existing cities.
Market penetration has been steady growth, particularly across higher-tier cities. The top 10 cities contributed over around 60% of the business.
Our intelligent learning system and device business has been launched in around 60 cities. We're encouraged by continued enhancements in customer retention and scalability, with top 10 cities contributed around 50% of this business.
In summary of the above, our new educational business initiatives delivered a 25% year-over-year revenue increase in the first quarter of 2027. Turning to our integrated tourism business, which spans study tours and research camps for K-12 and university students, as well cultural tours for middle-aged and senior travelers.
We have been leveraging our culture travel, China study tour, global study tour, and camp education products to deliver value through knowledge enrichment, personal growth, and experience for cultural immersion. Our students programs now operates in about 55 cities across China, with top 10 cities generating over 50% of the revenue.
Our premium adults offerings cover around 30 provinces in China, along with selected international destinations. We're also expanding into senior health and wellness tourism through an asset-light model, partnering with more than 65 wellness facilities in key destinations such as Hainan, Yunnan, Guangxi, and Shandong.
As for our OMO teaching platform, investments in revamping and upgrading the system continue to be in the books. In this quarter, we invested $28.2 million to improve and maintain our OMO platform, which enables us to provide uninterrupted, high-quality instruction to students and cater to their individual learning needs.
Building on the launch of our proprietary AI-powered personalized learning platform, ongoing investments and refinements of AI-enabled products remain our organizational priorities, to which we expect robust contributions in the coming quarters. The platform has completed the first phase of deployment, generating meaningful sales within just 25 days of launch.
Purpose-built as a specialized vertical learning system rather than a general-purpose large language model, it draws on New Oriental's deep educational heritage and enhances the competitiveness of our products in many aspects. These encouraging early results affirm strong market traction and product-market fit, and we will continue to advance AI-driven solutions to extend our market reach and improve operational efficiency.
Now, turning to East Buy. We're hugely encouraged by its rapid growth in the first quarter of fiscal year 2027, which underscores the success of our ongoing pursuit of evolution and optimization.
We accelerated private label development, and our very own three-high standard: high safety, high quality taste, and high value for money. Stringent raw material screening, factory audits, and finished product testing before every product launch reflects our commitment to stringent quality control.
Today, our private label line-up has grown beyond 1,000 SKUs across food, nutrition and health, apparel, skincare, and other categories. Notably, several flagship products have managed to deliver robust sales.
For its live streaming platform, the addition of professional live streamers and operation specialists has strengthened East Buy's content capabilities. The new vertical accounts launched on Douyin have now expanded our channel matrix to over 30 channels across a wide range of product categories.
We also draw on user feedback to continually improve the customer experience in our live streaming platforms. Offline sales network: East Buy leveraged New Oriental's nationwide learning center network to explore new retail opportunities.
We currently have four offline experience stores and are advancing campus store rollouts on the group level. We have also developed instant retail capabilities, with front warehouses in place and a one-hour delivery trial underway in Beijing and Shanghai.
For the rest of the year, East Buy will continue its multichannel strategy to cast a wider net, accelerate private label development in food and daily necessities, optimize membership operations on its proprietary app, and improve supply chain efficiency. Together, we're convinced that these initiatives will support sustainable growth and deliver a lasting impact.
Now, I would like to share updates on a new initiative we have been piloting since fiscal year '26 Q3, and that is New Oriental Home. This family-centric app assembles our education service, East Buy offerings, and culture tourism products into a single platform, serving the entire household at every stage of life.
New Oriental Home scale up a full-spectrum resource hub that caters not only to learning, but extensive individual needs. The point-based incentive program, which now reached a large number of students, has become woven into the daily teaching and customer service, while linking positive learning habits to product and reward redemption.
We're excited to share that our registered users rose substantially, with over half of them proactively redeeming points across our 10 learning and family-oriented offerings. Collectively, this result validates our educational offerings can extend naturally into a one-stop shop for the broader family, housing customer and all that we can offer in a synergistic ecosystem.
New Oriental Home also lowers customer acquisition costs and improves cross-selling efficiency. This program has been launched across 69 cities, including Chongqing, Hangzhou, Guangzhou, and Xi'an, with over 1,678,000 registered families by the end of this quarter.
New Oriental Home has achieved cumulative activity participant rate of over 90%, scoring a campaign activation rate for the quarter reached 33%, and significantly outperforming many public domain e-commerce platforms. We're ecstatic with the opportunity to further enhance customer lifetime value, and are eager to build on this encouraging momentum in the quarters ahead.
Now, I will turn the call over to Sisi to share with you about the key financials. Sisi, please go ahead.
Sisi Zhao
Thank you, Stephen. Let me now walk you through the key financial highlights for the quarter.
Operating costs and expenses for the quarter were $1,499.8 million, representing a 23.7% increase year-over-year. The increase was primarily due to the costs and expenses related to the substantial growth in East Buy private label products and live streaming e-commerce business.
Cost of revenue increased by 28.1% year-over-year to $817 million. Selling and marketing expenses increased by 30.7% year-over-year to $262.2 million.
G&A expenses for the quarter increased by 12.6% year-over-year to $420.7 million. Total stock-based compensation expenses, which were allocated to related operating costs and expenses, increased by 31.3% to $30.6 million in the first quarter of 2027.
Operating income was $374.7 million, representing a 20.5% increase year-over-year. Non-GAAP income from operations for the quarter, excluding share-based compensation expenses and amortization of intangible assets resulting from business acquisitions, was $406.8 million, representing a 21.2% increase year-over-year.
Net income attributable to New Oriental for the quarter was $273.2 million, representing a 13.5% increase year-over-year. Basic and diluted net income per ADS attributable to New Oriental were $1.76 and $1.74, respectively.
Non-GAAP net income attributable to New Oriental for the quarter was $300.9 million, representing a 16.5% increase year-over-year. Non-GAAP basic and diluted net income per ADS attributable to New Oriental were $1.94 and $1.92, respectively.
Net cash flow generated from operations for the first fiscal quarter of 2027 was approximately $195.4 million, and capital expenditure for the quarter was $65.8 million. Turning to the balance sheet, as of August 31, 2026, New Oriental had cash and cash equivalents of $1,754.6 million.
In addition, the company had $1,441.3 million in term deposits and $2,422.7 million in short-term investments. New Oriental's deferred revenue, which represents cash collected upfront from customers and related revenue that will be recognized as the services or goods are delivered, at the end of the first fiscal quarter 2027 was $2,121.1 million, an increase of 11.2% as compared to $1,906.7 million year-over-year.
Now, I'll hand over to Stephen to go through our outlook and guidance. Stephen?
Stephen Yang
Thank you, Sisi. We have entered a new phase with healthy performance this quarter, which injects confidence in our operational resilience and growth trajectory.
Looking ahead, we're particularly confident in sustaining our momentum across our core business and new endeavors, with expectations that our diverse initiatives to deepen customer engagement will drive margin expansion, greater operational efficiency, and strong shareholder yield. Strategic expansion of capacity and nurturing the talents remain our focus.
We plan to deepen our presence in market with solid top and bottom line performance. Expansion decisions will be carefully calibrated throughout the year, guided by operational readiness, customer demand, and financial results.
Continuous pursuit of new initiatives will not hinder our commitment in delivering promising service quality, sustainable profitability, and cost discipline. In addition to confidence in healthy growth of our core education business, we will always support East Buy and other new initiatives with customer-centric mindset, and without compromising the quality standard.
Our hope is for these efforts to collectively reinforce New Oriental's standing as a trusted name among Chinese households. We will also reveal our cost reduction and enhancement measures from time to time to improve our operational efficiency and margin profile.
Considering the positive momentum and disciplined measures across our business lines, we're pleased to reiterate the previously provided full-year guidance of total net revenue in fiscal year 2027 to be in the range of $6,453.9 million to $6,680.3 million, representing a year-over-year increase in the range of 14% to 18%. These expectations reflect our current outlook, and based on the recent regulatory development and prevailing market conditions, both of which remain subject to change.
To update everyone on the shareholder return for the fiscal year 2026, the company announced a share repurchase program in October 2025, in which company authorized to repurchase up to $300 million of its ADS or common shares over the subsequent 12 months. As of October 27, 2026, the company has fully utilized the $300 million repurchase amount of authorized under its 2026 share repurchase program, for an aggregate of approximately 56.2 million common shares, including common shares represented by ADS, from the open market.
Before closing my remarks, I'd like to provide an update on our shareholder return plan for this fiscal year. As part of the implementation of the 3-year shareholder return plan adopted in July 2025, for the fiscal year 2027, the board of directors of the company previously approved an ordinary cash dividend and a new share repurchase program in July 2026.
The company announced today that its board of directors has also approved an ordinary cash dividend as the fiscal year 2027 of $0.2 per common share, or $2.0 per ADS, which will be distributed in the U.S. dollar in two installments.
For the first installment, $0.1 per common share, or $1.0 per ADS, will be paid holders to the common shares of and ADS of record as close of the business on November 18, 2026, Beijing, Hong Kong time, and New York time, respectively. Then, for the second installment, $0.1 per common share, or $1.0 per ADS, will be paid to holders of common shares and ADS of record date that will be further determined by the board of directors of the company in due course.
The payment date for the first installment is expected to be on or around December 1, 2026, and December 4, 2026, for holders of common shares and holders of ADS, respectively. For the second installment, payment date is expected to be around six months after the payment dates of the first installment.
Further details regarding the record date and payment date for the second installment will be announced by the company in due course. The aggregate amount of the cash dividend to be paid in two installments is expected to approximately $300 million.
Pursuant to the 2027 share repurchase program, the company may repurchase up to $200 million of its ADS or common shares over the subsequent 12 months following the board approval. As of October 27, 2026, the company has yet to repurchase any common shares under the 2027 share repurchase program.
The company's proposed repurchase may be made from time to time in the open market at prevailing market price in privately negotiated transactions, in block trades, and/or through other legally permissible means, depending on the market conditions and in accordance with applicable rules and regulations. The board of directors of the company will review and share repurchase program periodically, and may authorize adjustments its terms and size.
The company expects to fund the repurchase out of its existing cash balance. To conclude, long-term value creation remains the fuel of the engine, and we're keen to share with our shareholders yields of the sustainable growth we're painting for the future.
We continue to collaborate closely with government authorities across China, ensuring full compliance with relevant policies and regulations, while adapting our operations responsibly and to meet evolving requirements. This is the end of the fiscal year 2027 Q1 summary.
At this point, I would like to open the floor for questions. Operator, please open the call for this.
Operator
Thank you. The question-and-answer session of this conference call will start in a moment.
In order to be fair to all callers who wish to ask questions, we will take one question at a time from each caller. If you have more than one question, please request to join the question queue again after your first question has been addressed.
To ask a question now, please press *11 on your telephone keypad, and wait for your name to be announced. To withdraw your question, please press *11 again.
We will now proceed to take our first question. Our first question comes from the line of Jenny Yuan from UBS.
Please ask your question Jenny, your line is open.
Jenny Yuan
Hi Stephen, hi Sisi. Thanks for taking my question.
My question is on margins. In this quarter, the overall OP margin was broadly stable year-over-year, while both the core education and East Buy delivered year-over-year margin expansion.
You explained that the overall margin performance was more due to the changes in revenue mix. If this trend continues, how should we think about the outlook for overall margin expansion, and what are the key drivers of margin improvement going forward?
Thank you.
Stephen Yang
Thank you, Jenny. Let us start with the margin analysis of this quarter.
I think you're right. Both our core education business and East Buy recorded year-over-year year-over-year margin expansion due to the enhanced operational efficiency and the improved utilization of the learning centers.
In Q1, East Buy's rapid growth increased its share of total revenue. Typically in Q1, because of seasonality, core education business margin is higher than the East Buy because of the the seasonality.
This shift in our revenue mix kept our consolidated operating margin at a stable level on the for the whole group. Going forward, I think we remain confident in the margin profile of the each business line, both the core education educational business and East Buy.
We expect the margin of the all the business lines will be expanded in the in the new year, in in this fiscal year '27. I think the margin expansion, will be will be will come from the higher operational efficiency and even the better utilization of the learning centers.
Also, we started the cost control since March last year 2025, and now I think we have seen the good result. We which helps us to drive the margin up.
I will continue to be the the cost control, going forward. It will help the margin profile going forward, Jenny.
Thank you.
Jenny Yuan
Thank you Stephen for the color. Very clear.
Thank you.
Operator
Thank you. We will now take our next question from the line of Elsie Sheng from CLSA.
Please go ahead Elsie, your line is open.
Elsie Sheng
Thank you Stephen and Sisi for taking my question. My question is mainly on revenue growth outlook, because this quarter we see a really strong revenue growth and it's much higher than our full-year revenue guidance.
What is the outlook for the next few quarters, and maybe the possibility of raising our full-year revenue guidance? Especially if you look at by segment, I notice that the overseas business growth actually accelerated versus the previous quarter.
Wondering what is the driver, and does this mean that overseas business will see a turning point or recovery? Thank you.
Stephen Yang
Okay. Thank you Elsie.
I think your question is about the revenue the growth outlook, for the whole year. As I think, this quarter, the Q1, the revenue growth, exceeded our expectations again.
I think I think the reason is because we we're seeing all the business lines grow very fast. Starting from fiscal year '27, we are making a change to give the annual guidance rather than the quarter guidance.
Giving the our positive momentum, I think in the coming Q2, even the rest of the the the year, I think the revenue growth will be very healthy. I will give you the breakdown of the revenue outlook of the annual guidance, by different business lines.
I think the overseas test prep prep business, this year's revenue growth will be over 5% year-over-year in dollar terms. For our new business, I think the revenue growth will be roughly high teens, or or is that close to 20% or roughly 20%.
The high school business roughly 15% top-line growth year-over-year. College business, I think the revenue growth will be around 20% or even slightly higher.
The East Buy, yeah, you saw the numbers of the revenue growth in Q1 of the East Buy, we had a very rapid growth of the East Buy, and I believe East Buy's revenue will be accelerated in Q2. The in the for so this is the breakdown of the the different business lines growth of the of the fiscal year '27.
I think even in the coming Q2, we expect the revenue growth of the whole group will be higher than the revenue growth of the Q1. I think you will get even more satisfied with the revenue growth in the coming Q2.
Oh, another question is about the reason of the overseas-related business, I think we in Q1 we got a 7%, 8% the top-line growth, and yeah, I think due to the impact of the economic environment and even the international situation headwinds, we met some revenue growth pressure last year. I think, our team have shown the resilience in in even in the Q1 and in the in the new year.
We believe that we will take more market share from from the competitors continuously, in the in the Q2, Q3, and Q4. I think for the overseas test prep business, for this year the growth will be over 5%.
I think it's, even stronger than we expected, last year. Thank you, Elsie.
Elsie Sheng
Thank you, it's very helpful.
Stephen Yang
Okay.
Operator
Thank you. Our next question comes from the line of Alice Cai from Citibank.
Please go ahead Alice, your line is open.
Alice Cai
Good evening Stephen and Sisi. My question is on non-academic tutoring enrollment, because it was down about 10% year-over-year after calculation, but new initiatives revenue grew about 25%.
Could you help us understand the gap? Is there anything changed in how you count enrollments?
Thanks.
Sisi Zhao
Okay. In terms of the revenue, we're booking the rev the the enrollment, sorry, we're booking the enrollments on time basis.
Basically, if you look at last quarter, actually this year, the enrollment is timing is earlier than last year. For if you look at last quarter, our enrollment growth is more than 25%, it's much higher than the revenue growth of last quarter, because a lot of students this year registered earlier than last year for both the summer quarter and autumn quarter autumn semester's course.
You you you saw that the enrollments increased dramatically last last quarter. This quarter, because of the pre-enrollments, the the actual enrollment number for comparing with last year is lower.
I would suggest you to combine these two quarters together to match with the revenue growth, you will see the similar trends for that. It's a timing difference.
One enrollments is on timing, on on time basis, but revenue is on accrual basis. If you take two quarters together, put together to do the calculation, you will see it's much more reasonable.
That's the key reason. I think
Stephen Yang
the time window changed time by time. That's why, we guided the investors, the revenue growth by by an annual basis.
I want to reiterate that the the K-9, business, the new business, the growth rate in the whole year will be somewhere around the 20% year-over-year in the dollar terms. We have no change.
Thank you, Alice.
Alice Cai
It's very clear. Very clear and helpful.
Thank you.
Stephen Yang
Thank you.
Operator
Thank you. Our next question comes from the line of Lucy Yu from Bank of America Securities.
Please go ahead Lucy, your line is open. Oh,
Lucy Yu
thank you. I just have one question on the learning center expansion pace.
How many learning centers we have added this quarter, and what would that imply year-over-year growth? Thank you.
Stephen Yang
The learning center, yeah, I think we we added 2% new capacity in Q1. This is
Sisi Zhao
Q-on-Q.
Stephen Yang
Q-on-Q, this is the the net add, Q-on-Q, 2%. For the whole year, we plan to open let's say the 10% to 15% new new learning centers, in the in I think most of them we opened the new learning centers in the existing existing cities.
We do plan to open more cities, a couple of new cities in the coming in in this new year. This is another change, because we feel quite optimistic about the business of the new educational business.
I think because we're happy to see the student retention rate improvement, that means we provide even the higher quality service to the students and to the customers, and drive the utilization rate up. I think we're quite optimistic on the the new business and even the OMO business within the K-12 business.
I think in the in the coming new year, if we let we open 10% to 15% new percent new learning centers, I think the overall utilization rate will be up in the new year. Lucy.
Lucy Yu
Understood. Very clear.
Thank you, Stephen.
Stephen Yang
Thank you, Lucy.
Operator
Thank you. Our next question comes from the line of DS Kim from JPMorgan.
Please go ahead DS, your line is open.
DS Kim
Hi Stephen, hi Sisi. Thanks for taking my question, and by the way, congrats on the all-time high revenue and record-high profits.
I think the best number in the past 33 years, kudos to that. Despite the share reaction, I think the underlying operating trend looks pretty solid, at least to me.
I was going to ask about enrollment, but you already explained very well, and revenue growth for new business can sustain nearly 20% anyway, so that is more telling, I think, than the enrollment trend. Maybe perhaps let me ask on East Buy profit.
I know you can't talk about exact number because of the disclosure, but can we comment on the high level, say, when I look at minority interest, I think the momentum sequentially was down 8% quarter-over-quarter. Should we take that as a directional signal that East Buy profit dollar was down sequentially, or is that too simplistic a way to look at it?
Just as a follow-up, you just mentioned about expansion. Can I just double check, what does that 10% to 15% learning center expansion mean for K-9 or new business, this new non-academic educational businesses classroom expansion?
Does that imply, much higher number given that we probably didn't add high school? Thank you so much.
Stephen Yang
Thank you DS. The East Buy, in the Q1, the East Buy's non-GAAP operating margin, is expanded year-over-year.
You look at the number of the the MI, yeah, because East Buy, issued the granted the the ESOP last quarter, I think, typically based on the based on the GAAP, typically it recorded more share-based compensation in the first year, and and so it dragged the net profit. If you look at the non-GAAP basis, I believe the the East Buy's non-GAAP OP margin and non-GAAP net margin in the Q1, is expanded.
This is my answer of the of your your question about the the the East Buy's margin. Your second question is about the enrollment.
Can you repeat the your second question again?
DS Kim
Sorry, thank you, sir. That makes a lot of sense on non-GAAP.
Just wanted to double check, 10% to 15% learning center expansion that you mentioned, what does that mean for K-9, new education business classroom, in particular? If you could disclose, roughly.
Stephen Yang
I think roughly 15% for the K-9 business,
DS Kim
it's,
Stephen Yang
because yeah, it will be higher than the average. Yeah.
DS Kim
Thank you, sir.
Operator
Thank you. We will now move to our next question from the line of Timothy Zhao from Goldman Sachs.
Please ask your question Timothy, your line is open.
Timothy Zhao
Thank you. Thank you Stephen and Sisi for taking my question.
I think just a quick follow-up on the margin question regarding East Buy. I think, Stephen, in the beginning you mentioned that for this year you expect margin expansion across all business lines, just want to clarify here whether when you refer all business lines, whether that include East Buy or not.
For my question, I think I want to understand more about the New Oriental Home. I think definitely a lot of the operating metrics that you share is quite encouraging, including the membership and also the activation rate.
Just wondering if you can help us better understand how those New Oriental Home and all those operating metrics translate into the financials, i.e., whether that helps you to save the the sales marketing, and is there a way to quantify that? That would be very helpful.
Thank you.
Stephen Yang
Thank you, Tim. I think and in the Q1, the core education business, the margin is up, is expanded.
As well, East Buy's non-GAAP OP margin is expanded. Both of the business, the margin is expanded in the Q1.
Going forward, first of all, I think the both of the business, core business, education business and East Buy, we expect the margin expansion going forward. Don't forget East Buy's revenue growth, we recorded big business since, roughly three quarters ago.
In the in the in the Q1, we got East Buy got very fast revenue growth, and I think we and we believe in the coming Q2, the revenue growth of the East Buy will be accelerated compared to the Q1. I think the margin profile of the of the East Buy, will be positive going forward.
This is, the the East Buy and even the educational business, different business, margin and even the the revenue growth, the forecast. I will ask Sisi to answer your question about the New Oriental Home.
Sisi Zhao
Yes. Actually, New Oriental Home is a new platform that we started operation since second half of last year.
Actually, this platform, it's quite exciting in terms of that it's a platform that's combining all our key business lines, not only education, but also East Buy and tourism. We're operating on a each home household home as a whole entity to to to operate.
Actually, attracted a lot of users already. Registered family numbers already increased to 1.6 million, over 1.6 million already, and still increasing, covering all kinds of educational products, and still increasing.
Not only our own customers, but also some relatives outside New Oriental's existing customers. The user number is meaningful.
Also, we are operating this in terms using a new kinds of ways, and the the participation rates is also very high. Cumulatively, 90% participation, which means customer actually the the users of the vast majority of the users are actively attending all kinds of activities that we organized through the platform.
Also, the latest activation rates is over 30%, these these numbers are exciting. Also, in going forward, as we have this platform bigger and bigger, and have all the related customers signing in, and it can start to generate, because this is a sales platform, like we can easily cross-sell our products, not only educational, but already using the credit-based operation to have some cross-selling from education business to East Buy, the the live streaming business, and also have the ability to generate maybe even more revenue from this new revenue from this platform.
Actually, it's still early stage for this new initiatives, and we'll keep updating everyone of the new progress of the platform. At the same time, this is also a platform help us to reduce the customer acquisition cost, because we used to have individual business units covering different ages of customers, but now we're now in in using the platform to operate and also to manage the needs of the whole family, we can easily use the related to education action activities that customers are attending, and then easily reduce the customer acquisition cross-sell different business lines to to the same group of customers.
This is also exciting trend that we can reduce, we're expecting that very, very effectively we can reduce the customer acquisition cost, and expenses, operation expenses will be reduced because of the platform. Going forward, we'll keep updating the progress of the platform to all of you.
Yeah.
Timothy Zhao
Thank you. Thank you Stephen and Sisi for the answers.
Thank you. Thank you.
Operator
Our next question comes from the line of Yikun Zheng from Citics. Please go ahead Yikun, your line is open.
Yikun Zheng
Hi Stephen and Sisi. My question is about the potential for the core business margin, since the current margin level is already very healthy, and you are still rolling out the cost reduction plan.
Just wondering how much further room there is for the margin expansion going forward. Thank you.
Stephen Yang
I think going forward, I think the core education business margin, we expect to be expanded. Because that, as I said, we open the learning centers with the, more, discipline and 10% to 15%, and so we do hope to get the higher utilization rate, and even we have potential operating leverage going forward.
As I said, we started the cost control last year and will continue to do the cost control. I think even like the cost and expense, the selling marketing, even the G&A profile, I I think we can save, some money to drive the margin up.
This is, my analysis of the margin profile of the core education business. Yeah.
Thanks,
Yikun Zheng
thank you. If we look at the margin in fiscal year 2028 or fiscal year 2029, will the margin expansion still be our top priority?
Stephen Yang
Yes, because, we changed our strategy since last year. We care more about the quality improvement and even the higher student retention rate, and we don't want to open too much too many learning centers, and we care more about the higher utilization rate.
Even in the next two to three years, I think our plan is to drive the margin up, step-by-step.
Yikun Zheng
Thank you, Stephen.
Operator
Thank you. Our next question comes from the line of Jing Yuan from CICC.
Please ask your question Jing, your line is open.
Jing Yuan
Good evening Stephen and Sisi. I know we have discussed a lot about the margin, but my question is do you want to dive deeper about the operating margin?
Like you said you suggest that we look at the operating margin of the educational business and East Buy separately. Could you provide more color on the margin improvement for the like especially education business, if possible, the magnitude?
How should we look like look looking forward, how is the outlook for their separately, like the operating margin? Thanks.
Stephen Yang
As I said, in the Q1, the core education business margin was, is expanded, and the East Buy's margin is expanded, as well. The margin expansion of East Buy, is higher than the core education business, because of different, revenue growth level.
I don't want to say too much words on the seasonality, but if look at an annual basis, it is what it is. Going forward, I do believe East Buy first, I do believe the margin of the East Buy will be expanded in the coming new year.
For the core education business, we'll do the right things, keep make the learning center utilization rate up, keep doing the cost control, and to provide the investors more satisfied the margin profile going forward.
Jing Yuan
Got it, thank you.
Operator
Thank you. We have now approached the end of the conference call.
I'll now turn the call over to New Oriental's Executive President and CFO, Stephen Yang, for his closing remarks.
Stephen Yang
Again, thank you for joining us today. If you have any further questions, please do not hesitate to contact me or any of our investor relations representatives.
Thank you.
Operator
This concludes today's conference call. Thank you for participating.
You may now disconnect your lines.