GlobalFoundries Inc.
Q3 FY2026 · Earnings Call TranscriptNovember 4, 2026
Operator
Welcome to the GlobalFoundries third quarter fiscal year 2026 financial results conference call. At this time, all participants are in a listen-only mode.
After the speakers' presentation, there will be a question-and-answer session. To ask a question during this session, you'll need to press star one one on your telephone.
If your question has been answered and you'd like to remove yourself from the queue, simply press star one one again. As a reminder, today's program is being recorded.
Now I'd like to introduce your host for today's program, Eric Chow, Head of Investor Relations. Please go ahead, sir.
Eric Chow
Thank you, operator. Good morning, everyone, and welcome to GlobalFoundries third quarter 2026 earnings call.
On the call with me today are Tim Breen, CEO, and Sam Franklin, CFO. A short while ago, we released GF's third quarter 2026 financial results, which are available on our website at investors.gf.com, along with today's accompanying slide presentation.
This call is being recorded, and a replay will be made available on our Investor Relations web page. During this call, we will present both IFRS and non-IFRS financial measures.
The most directly comparable IFRS measures and reconciliations for non-IFRS measures are made available in today's press release and accompanying slides. Please note that these financial results are unaudited and subject to change.
Certain statements on today's call may be deemed to be forward-looking statements. Such statements can be identified by terms such as believe, expect, intend, anticipate, and may, or by the use of the future tense.
You should not place undue reliance on forward-looking statements. Actual results may differ materially from these forward-looking statements, and we do not undertake any obligation to update any forward-looking statements we make today.
For more information about factors that may cause actual results to differ materially from forward-looking statements, please refer to the press release we issued today, as well as risks and uncertainties described in our SEC filings, including in sections under the caption Risk Factors in our annual report on Form 20-F and in any current reports on Form 6-K furnished with the SEC. In terms of upcoming events, we will be participating in a fireside chat at the UBS Global Technology and AI Conference in Scottsdale, Arizona on December 1st.
We will begin today's call with Tim providing a summary update on the business environment and technologies, followed by Sam, who will provide details on our third quarter results and fourth quarter guidance. We will then open the call for questions with Tim and Sam.
We request that you please limit your questions to one with one follow-up. I'll now turn the call over to Tim.
Tim Breen
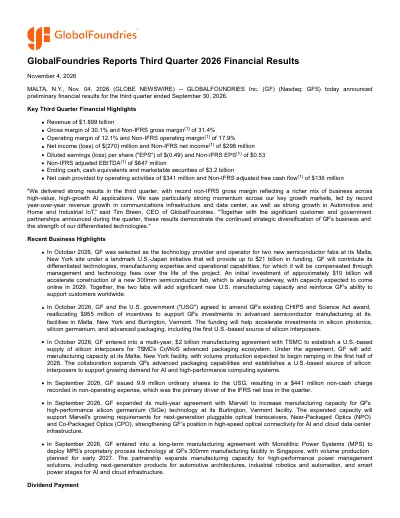
Thank you, Eric, and welcome everyone to our third quarter 2026 earnings call. GF delivered strong results in the third quarter with revenue and non-IFRS profitability metrics at the high end of our guidance ranges.
We delivered record non-IFRS gross margin, which demonstrates the meaningful progress we are making to enhance the mix of our business by ramping our differentiated technologies in high-value, high-growth applications. Our Communications Infrastructure and Data Center end market saw record levels of growth led by accelerating demand in optical networking across our silicon photonics and silicon germanium platforms.
We also delivered strong growth in Automotive and Home and Industrial IoT, reflecting broad-based secular momentum across our key markets. Thanks to the accelerated growth across several end markets, the proportion of revenue outside of smart mobile devices was the highest level in our company's history and is driving a richer, more diversified, more resilient revenue base.
Thanks to the team's excellent efforts and execution, we are ahead of plans to deliver the strategic and financial targets we set out at our Investor Day earlier in the year. We will look back at 2026 being a pivotal year for GF.
In recent weeks, we have made several significant announcements that meaningfully advance our strategy, support our financial objectives, and reinforce our foundation for durable long-term growth. We are proud to have announced a significant number of new customer and investment partnerships such as our agreements with Marvell to accelerate capacity for our industry-leading, high-performance SiGe, with Monolithic Power for critical power management solutions, with TSMC to establish a US-based supply of silicon interposers for the CoWoS ecosystem, and the landmark US-Japan Fab Expansion Plan that will transform our Malta, New York site.
These milestones firmly position GF as a diversified, holistic technology provider critical to governments and partners around the world. Let me cover these areas in more detail.
Beginning with our strong investment partnerships, announced last month, the US-Japan initiative provides a new and innovative model for GF to expand our critical US semiconductor manufacturing capacity at accretive economic returns. This initiative will unlock substantial capacity growth, support significant future customer demand, and bring the scale of our US operations in Malta, New York to mega fab level.
The unique and innovative partnership structure allows GF to expand capacity faster without investing capital, with an economic model that is accretive to our long-range plans. Through a robust structure of technology, construction, and operations fees, cost reimbursements, and EBITDA sharing, the initiative is designed to generate the profit per wafer comparable to if we had built and owned the capacity ourselves.
As another indicator of our deepening partnership with the US government, GF reached an agreement with the US Department of Commerce to reallocate $955 million of our existing CHIPS and Science Act award to accelerate investments at our Malta, New York and Burlington, Vermont facilities. The amended award will accelerate CapEx and R&D investments in our highest-value, differentiated technologies that our customers demand, such as silicon photonics, silicon germanium, and advanced packaging, including the first US-based source of silicon interposers.
In recognition of the growing role that GF is playing in the US semiconductor ecosystem, a separate agreement will be entered into to issue 4% equity to the US government, which provides a vehicle for the American people to share in GF's future success. Combined with previous announcements across our quantum, silicon photonics, and advanced packaging investments, we anticipate the total equity ownership of the US government to be approximately 7% when all agreements are finalized.
Having attained a meaningful position in GF, our Board of Directors and our US government partners do not plan on any further government equity position beyond these announced equity stakes. In summary, this landmark agreement represents a strong vote of confidence in GF and underscores our critical role in advancing US semiconductor leadership.
Let me now turn to our significant and expanding opportunity in the AI data center. We see significant momentum with customers for our optical networking solutions, where customers value GF's unique combination of high-performance photonic devices, advanced fiber coupling, RF integration, and advanced packaging.
Backed by more than a decade of investment and substantial clean room space within our modern, highly automated 300-millimeter footprint, GF can deliver differentiated performance and scale capacity rapidly as customer demand grows. Our competitive advantages are translating into strong design-win momentum and robust customer demand.
We are actively engaged with more than 50 silicon photonics customers, including seven of the top 10 optical transceiver suppliers, with active designs slotted to ramp in 2027 and 2028 for scale-across, scale-out, and scale-up networks. In 2026, we expect to deliver $0.5 billion of revenue from silicon photonics, and on the back of the strength of customer demand, order visibility, and our capacity growth plans, we now expect to exit 2027 at an annualized silicon photonics revenue run rate of approximately $1 billion, a full year ahead of prior expectations.
To support the ramping demand for optical networking in 2028 and beyond, we plan to approximately triple our silicon photonics capacity over the course of next year, which Sam will cover in more detail. In addition to silicon photonics, silicon germanium is another important and complementary driver of GF's growth in optical networking.
Our SiGe technology enables high-speed optical transceivers through transmit drivers and receive amplifiers, key interface elements between the electrical and optical domains. Customer demand for our SiGe technology continues to increase beyond current capacity, and supported by customer prepayments, we are accelerating our capacity investments to ensure that we can meet this demand.
Our recently announced multi-year strategic partnership with Marvell will help support significant SiGe capacity expansion in our Burlington Fab to enable next-generation optical solutions. Together with the reallocated US government funding from our prior CHIPS grants awards, this gives us additional resources and strong customer alignment to scale a highly differentiated platform, meaningfully accretive to GF's long-term margin targets.
Lastly, advanced packaging is another key enabler of our AI data center strategy. Under our five-year, $2 billion manufacturing agreement with TSMC, GF will establish a US-based supply of silicon interposers for the CoWoS ecosystem, with volume production expected to ramp at our Malta site in the first half of 2028 and with a framework to expand the agreement over time.
The economics of this arrangement are attractive for GF and the strategic benefits are clear. This agreement establishes a new multi-year revenue stream for GF with gross margins above our long-term targets and with co-investment from TSMC that will help fund the necessary capital associated with this project.
The silicon interposers are yet another way GF can serve growing AI and high-performance computing infrastructure demand. By combining GF's trusted US manufacturing capabilities with the leading advanced packaging ecosystem globally, we are expanding into another essential layer of AI infrastructure and supporting the tighter integration of compute, memory, and connectivity.
We believe we are in the early innings of GF's AI data center opportunity, underpinned by the critical needs of our customers for higher bandwidth connectivity, tighter integration of compute and memory, greater power efficiency, and secure, scalable supply. The results for GF: more avenues to win, greater content and value in each system, and a clear path to growth and a structurally richer business mix.
Let me turn to physical AI, as well as the meaningful progress we are making across IP, software, and custom silicon, or ISC. GF's physical AI opportunity spans a wide variety of applications across connectivity, compute, power, actuation, and sensing, and our IP, software, and custom silicon capabilities unlock even more ways for GF to win.
We believe the deployment of intelligence into vehicles, factories, robots, drones, satellites, medical devices, and other edge systems represents a significant and long-duration demand vector for GF. Together with the Synopsys ARC processor IP business we acquired earlier this year, MIPS expands our role into that of a holistic technology partner, servicing a broader set of customers with our custom silicon platforms.
MIPS recently announced three physical AI-native reference platforms focusing on compute, AI inference, and real-time control, and we are now working with several customers designing systems focused on physical AI, leveraging our expanded capabilities. The combination of RISC-V compute and AI IP, design capability, and AI-native platforms based on GF's broad manufacturing capabilities puts us in a unique position to accelerate share gain in this area.
Just over one year after we initially acquired MIPS, we are very encouraged by the strong customer traction, which is now driving several platform-level wins. During the third quarter alone, we secured custom silicon design wins that total nearly $1 billion of lifetime revenue.
These included platform wins for a radar system-on-chip and a RISC-V-based processor core designed for real-time control. In addition, we secured a win with a leading provider of high-performance data center computing solutions to design their custom board management controller system-on-chip, integrating our processor technology with third-party IP.
We also secured a notable aerospace and defense win to support the engine control processor for a leading global aerospace and propulsion company. Ultimately, these wins demonstrate how GF can capture more opportunities and support our customers across the semiconductor value chain, deepen our relationships with industry partners, and convert initial design engagements into concrete, long-duration growth opportunities.
In summary, the multifaceted progress we demonstrated this quarter shows our strategy in action. We are scaling differentiated technologies into high-growth AI markets and driving meaningful customer value with our capabilities in IP, software, and custom silicon.
We are transforming GF into a more diversified, more durable, and more profitable business, propelled by the defining megatrends of our time. I'll now pass the call over to Sam for a deeper dive on third quarter 2026 financials.
Sam Franklin
Thank you, Tim. For the remainder of the call, including guidance other than revenue, cash flow, and net interest income, I'll reference non-IFRS metrics.
The third quarter was a significant milestone for GF, not only for the continued progression in our profitability metrics, but also for the continued mix shift in our portfolio. For the first time in our history, more than two-thirds of our Q3 revenue came from outside smart mobile devices, a record for GF and further evidence of our increasingly diversified and margin-accretive mix.
We delivered record non-IFRS gross margin while continuing to fund the strategic investments that will drive GF's next phase of growth. Our strategic decisions are already enhancing our earnings power, and we believe that we're only in the early innings of this evolution.
Now on to the results. We delivered third quarter revenue of $1.899 billion, up 6% sequentially and 13% year-over-year.
We shipped approximately 647,300-millimeter equivalent wafers in the quarter, up 4% sequentially and 7% from the prior year period. Revenue from manufacturing services accounted for approximately 88% of total revenue.
Revenue from technology services, which includes revenue from IP, licensing, software, reticles, non-recurring engineering, expedite fees, and other items, accounted for approximately 12% of total revenue for the third quarter. As we continue to invest in a broader range of capabilities for our customers, we expect technology services revenue will represent approximately 12% of total revenue in 2026, which is at the upper end of the range we indicated, and with a gross margin profile that continues to be above our long-term target.
Beyond 2026, we expect that the growth of revenue from technology services associated with IP, licensing, and software, combined with strong momentum in customer design wins and tape-outs, will be important drivers of GF's revenue growth and gross margin appreciation. Let me now provide an update on our revenue and outlook by end markets.
Communications Infrastructure and Data Center represented approximately 17% of third quarter total revenue. Revenue increased 14% sequentially and 81% year-over-year, driven by robust growth in optical networking, which includes silicon photonics and silicon germanium.
Not only did Q3 represent a record year-over-year growth for this end market, it also marked the eighth consecutive quarter of double-digit percentage year-over-year growth for Communications Infrastructure and Data Center. With accelerating customer demand and improved manufacturing productivity, our expectation is that revenue from Communications Infrastructure and Data Center will grow in the range of 60% to 70% in 2026.
Furthermore, our design-win momentum across this end market has continued to strengthen. In the third quarter, we secured design wins for both silicon photonics and SiGe at a new optical transceiver customer for hyperscaler demand.
In data center power, we taped out a smart power stage gate driver on our BCD platform and secured a design win on our 650-volt GaN platform. Automotive represented approximately 19% of third quarter total revenue.
Automotive revenue increased 11% sequentially and 20% year-over-year. Consistent with our prior commentary, our expectation is that automotive revenue will grow low double-digit percentage in 2026, marking another strong year of growth for this end market, and GF continues to win with our customers to support the expansion of automotive semiconductor content.
Smart Mobile Devices represented approximately 32% of third quarter total revenue, the lowest proportion in our history and a step forward to our long-term strategic goal to enhance the diversification of mix. Revenue decreased 5% sequentially and 19% from the prior year period.
Consistent with the commentary from our customers, we continue to expect smart mobile devices to decline by a low teens percentage year-over-year in 2026. We continue to have a skew towards the premium end of the smart mobile market, and we expect to largely track the broader demand dynamics as the market adjusts to the challenges associated with memory-related supply constraints.
The long-term demand indicators continue to be positive. In the third quarter, we secured new design wins across form factors spanning both smartphones and smart glasses.
These included additional content wins in mobile power and a first-ever design win for fuel gauge ICs in premium-tier handsets. Customer engagement continues to be strong for GF's differentiated and high-performance RF, power, audio, display, and imaging capabilities to service the demand for smart and connected mobile devices.
Finally, Home and Industrial IoT represented approximately 20% of third quarter total revenue. Revenue increased 16% sequentially and 49% year-over-year on broad-based strength across connectivity, tracking, and sensing applications.
As workloads for edge AI applications continue to grow alongside the requirement for Bluetooth, wireless, cellular, and power management components to perform at higher standards, we have seen strong traction with our customers in this end market for GF's highly differentiated platforms. As a result, we continue to expect Home and Industrial IoT to grow in the range of 10% to 15% in 2026.
Looking ahead to the future growth opportunities, the design-win momentum has continued. In the third quarter, we taped out next-generation cellular IoT and Bluetooth products on our FDX platform for wireless connectivity.
We're encouraged by the momentum we're seeing across the end markets we serve and believe keep us on track with the strategic diversification objectives that we set out during our Investor Day this year. Moving now to other key financial performance metrics in the quarter.
In the third quarter, we delivered gross profit of $597 million, which translates into approximately 31.4% gross margin, up 540 basis points year-over-year. Q3 gross margin achieved a company record and was at the high end of our guidance range.
R&D for the quarter was $164 million, and SG&A was $93 million. Total operating expenses of $257 million represented approximately 14% of total revenue and were up 9% quarter-over-quarter, reflecting recent acquisitions.
We delivered operating profit of $340 million for the quarter at an operating margin of 17.9%, at the high end of our guided range and up 250 basis points from the prior year period. Third quarter net interest income was $9 million, and other expense was $6 million, and we incurred tax expense of $45 million in the quarter.
We delivered third quarter net income of approximately $298 million, an increase of approximately $66 million from the prior year period. Diluted earnings of 53 cents per share was at the high end of the guidance range based on a fully diluted share count of approximately 558 million shares.
Let me now provide some key cash flow and balance sheet metrics. Cash flow from operations in the third quarter was $341 million.
Third quarter CapEx, net of proceeds from government grants, was $205 million or roughly 11% of revenue. Adjusted free cash flow for the quarter was $136 million.
Free cash flow in the third quarter benefited from approximately $150 million of customer prepayments and government grants received. At the end of the third quarter, our combined total of cash and cash equivalents and marketable securities stood at approximately $3.2 billion.
Our total debt was $1.1 billion, and we also have a $1.5 billion revolving credit facility, which remains undrawn. On October 9th, we paid a quarterly cash dividend of 12 cents per share.
On October 27th, the Board of Directors approved a dividend of 12 cents per share payable on January 14th, 2027 to shareholders of record as of December 22nd, 2026. In the third quarter, we also repurchased $100 million of our shares.
Let me now provide you with our outlook for the fourth quarter of 2026. We expect total GF revenue to be $2 billion plus or minus $25 million.
We expect gross margin to be approximately 31.5% plus or minus 100 basis points, which at the midpoint reflects approximately 250 basis points of year-over-year expansion. Excluding share-based compensation, we expect total operating expenses to be $235 million plus or minus $10 million.
We expect operating margin to be in the range of 19.8% plus or minus 170 basis points. At the midpoint of our guidance, we expect share-based compensation to be approximately $68 million, of which roughly $16 million is related to cost of goods sold.
We expect net interest and other income for the quarter to be between negative $5 million and $1 million, and income tax expense to be between $44 million and $68 million. Based on a fully diluted share count of approximately 575 million shares, which reflects the expected issuance of equity to the US government, we expect diluted earnings per share to be 59 cents plus or minus 5 cents.
Subject to the timing of the closures associated with the remaining equity issuances to the US government, we expect that our fully diluted share count will be approximately 600 million shares commencing 2027. Now let me provide an update on some broader financial drivers, milestones, and outlook.
With respect to pricing, the third quarter saw meaningful blended ASP growth, both sequentially and year-over-year. This marked the first quarter of year-over-year blended pricing improvement since 2023 and is consistent with the commentary we provided on our last earnings call, especially as we execute the continued mix shift of our business.
With respect to tax, we continue to expect a non-IFRS effective tax rate in the mid-teens percentage range for the full year 2026. Net CapEx for 2026 is expected to be approximately 15% to 20% of revenue, which remains below our long-term model, and we continue to expect free cash flow margin of approximately 10% in 2026.
Touching briefly on the CapEx outlook for the year ahead, we expect 2027 to represent a year of accelerated investment for GF. Throughout the second half of this year, our customers have substantially increased their demand for our differentiated solutions across critical technologies such as silicon photonics, silicon germanium, FDX, and advanced packaging.
Importantly, we have the ability to grow our capacity quickly and efficiently within our existing four-walls manufacturing footprint, resulting in a strong return on investment for new CapEx spending. Robust demand and customer commitments form the foundation of our capacity investment principles.
As these signals strengthen, we expect approximately one-third of our net CapEx in 2027 to be supported by customer prepayments for incremental capacity agreements. In parallel, we also expect to secure CapEx offsets from investment tax credits and government grant frameworks, including a proportion of the recently announced $955 million repurposing from our previously awarded CHIPS grants.
Against this backdrop of customer demand, prepayments, and government support, we now expect net CapEx investments of approximately $4 billion into our manufacturing footprint in 2027 while continuing to deliver our free cash generation targets. These critical investments will unlock capacity constraints, accelerate future growth, and continue to evolve our business into a more diversified, resilient, and accretive portfolio.
Our third quarter results demonstrate that GF's strategy is translating into stronger financial performance. Importantly, we believe these improvements are structural.
Our revenue mix continues to shift towards differentiated, high-value technologies and services, while our government and customer partnerships are enabling us to make capital-efficient investments to scale and accelerate key technologies with favorable economics. All of these drivers reinforce our confidence in the long-term financial targets we presented at our Investor Day.
GF today is more diversified and better positioned to capture more value than it ever has been. In closing, I want to thank our employees around the world for their continued focus and execution.
Their work made this quarter's performance possible and gives us confidence in what GF can achieve next. With that, let's open the call to Q&A.
Operator?
Operator
Certainly. Our first question for today comes from the line of CJ Muse from Cantor Fitzgerald.
Your question, please.
C.J. Muse
Good morning. Thank you for taking the question.
I think one of the key themes from this call is you guys moving to a structurally richer business mix, particularly as I think about silicon photonics pulled in by a year. I'm curious, you laid out targets of exiting '27 at 35% gross margins, 40% exiting '28.
You're raising pricing starting Jan 1. How I guess is that portfolio of changes impacting your thinking about your gross margin trajectory into '27 and '28?
Sam Franklin
Hey, CJ, I'll take that one and then Tim probably overlay some of the strategic dynamics as well. Look, we're really pleased with the margin trajectory, and I think you've seen from us consistently this year near on 500 basis points of year-over-year margin growth.
If you go back to what we said we were going to do at the Investor Day back in May, we feel like we're doing exactly that. Mix has been a key component of it.
We've also seen some gradual pickup in utilization as well through this year, but fundamentally, it's been driven by those strategic decisions that we've taken over the last couple of years. Technology services as a percentage of revenue clearly falls through as a richer mix and margin driver as well.
That's continued to grow during the course of this year. On balance, we feel like we're actually hitting that target, and we're well on track to the target that we set out in May.
Remember, at the start of this year, we said we wanted to exit the fourth quarter of 2026 with a 30% gross margin handle. We were bumping up on that in our 2Q results.
Our 3Q results, obviously, we've gone through that target. We're quite pleased with even where the guide is for fourth quarter.
It shows about a point and a half of growth relative to that original target we had. Very much feel at this point that we are on track to those gross margin goals that we set out earlier on this year.
Obviously, there's still some way to bridge from call it the 31.4% in 3Q up to the 40% that we want to exit the fourth quarter of 2028 with. That mix dynamic and where we're continuing to invest in those corridors where we're seeing very strong demand signals from customers is continuing to push us in the right direction as it relates to that margin accretion.
No change to the goals that we laid out just a few months ago, but maybe I'll pass it to Tim for some of the other structural and strategic dynamics.
Tim Breen
Thank you, Sam. No, CJ, I think the right way to think about this is we're delivering what we said earlier this year, right?
We're winning in those secular growth markets and we're winning with leading customers, who, in many cases, are new to GF. The announcements we made just this quarter, customers like MPS, customers like TSMC, expanded business with Marvell, by the way, the many others that supported our several announcements over the quarter just tell you kind of the breadth of engagement we have.
That's giving us a lot of confidence to bring those technologies to market, accelerate those ramps, accelerate the capacity investments, and obviously unlock even more growth through the partnership we've struck with the US and Japan. Look, it's been a great period of accelerating our business model and, look, we're very confident in the trajectory ahead.
C.J. Muse
Thanks for that. I guess as a follow-up question, could you speak to, I guess, your early look to Q1 seasonality?
If I look at it, the implied SMD, you're talking down 22% year-on-year for Q4 and down 40% from your prior peak. At the same time, CID is tracking 80% implied in Q4.
Would love to hear how you're thinking about the March quarter.
Sam Franklin
Happy to give you a little bit of color, CJ. Obviously, just mindful that we're only going to guide one quarter at a time.
The way you've characterized it is the right way, and we think that relative to where we said earlier on this year, we're broadly on track with several of those end markets, right? We expected that Mobile would be down in the low teens percentage.
No change for that for the full year '26. We expected that IoT would be in that 10% to 15% range full year, again no change, and Automotive low double-digit percentage growth.
That's been a consistent theme for us. Really the step change has been the accelerated growth that we're seeing in Comms Infra and Data Center, and the way you've thought about it for the fourth quarter is the right way.
Looking out to 2027, obviously, we'll put more color on that when we get to the next call, but just going back to what we said as part of our Investor Day in May, look, I think the general trends are very constructive as it relates to Automotive, IoT. Remember in that space, we said low double-digit growth is our long-term goal for Automotive and sort of mid-teens for IoT.
Comms Infra and Data Center is where we think that there's very strong momentum to continue growing. The target that we put out previously in our long-term model was 30-plus percentage points.
You can infer from where we've reported in Q3 and the direction of travel for Q4 that we're seeing that continued momentum in that space. I'd say that that is probably a tailwind going into 2027.
Then look, Mobile, we've been consistent on the commentary there and largely tracking where we see the rest of the market. I don't think any surprises on that front.
Hopefully, that gives you a little bit of color as we're thinking about it for the full year. Obviously, happy to give you more color on Q1 when we get to the next quarter.
C.J. Muse
Very helpful. Thank you.
Operator
Thank you. Our next question comes from the line of Sahej Sarna from Stifel.
Your question, please.
Sahej Singh
Hey, thank you for taking my question. Congrats, by the way, on the partnerships you've lined up this quarter.
I think they say a lot about where Global sits in the AI supply chain. Tim, I guess, thanks for the color that customer prepayments will support roughly a third of 2027 net CapEx, I think I heard.
Since May, you've sort of talked about customers discussing advance payments to secure FDX, SiPh, and silicon germanium capacity. You've had CPO tape-outs in the first quarter and a scale tape-out in the second.
I guess even directionally, could you give some color into how much of your 2027, 2028 SiPh and SiGe capacities now under signed commitments? Are those agreements even reaching into 2029 as NPO and CPO potentially come in?
Tim Breen
Yeah. No, thank you, Sahej.
I think the picture is as follows. The acceleration of optical communication is very clear, and I think we're still at the very early innings of that as you see just optical links replacing copper in all aspects of the data center.
Just demand is truly skyrocketing. We're having those discussions with our customers and lining up the supply they need.
We are absolutely booked out through '27, increasingly booked out through '28, and the question for us is how fast we can add more capacity to meet their requirements in '28. Many of them are seeking capacity assurance through '29 and even some cases beyond.
I think in every single case, they're willing to put their balance sheet to work to support us in those investments as well. It's a very constructive environment in terms of visibility, in terms of demand.
It's really now down to us in terms of execution, right, installing tools, driving productivity. That's really what you're seeing accelerate our own trajectory even within '26.
We're doing better than we expected based on our acceleration of investments and the ability to ramp those tools to production quickly. That's true across all those corridors you mentioned.
I'd say increasingly that will also be true in advanced packaging with some of the interposer work we've also announced.
Sahej Singh
Thank you for that. I guess interposer work is topical as well.
Sam, thank you for the color on the blended ASPs. I guess I'd like to build on CJ's question on the margin drivers, particularly to help us frame pricing specifically.
At the Investor Day, you were pretty clear that the bridge to the 40% exiting '28 doesn't embed significant price increases from supply and demand. Now with ASPs up year-over-year for the first time since 2023, should we think of pricing as additive to the 40%?
Then on the TSMC interposer agreement, thanks for the color that margins sit above your long-term targets. At roughly $400 million a year or about 4% of revenue against '28 consensus, is it fair to think of that as adding on the magnitude of 50 basis points to corporate gross margins at run rate alongside the 100 to 200 basis points from the US-Japan program?
Sam Franklin
Sure. There's a little bit to unpack there, Sahej.
Maybe I'll I'll start with the the pricing point and then we can talk more broadly around margins. Look, it's it's encouraging what we've seen in the third quarter, but also not surprising.
We we gave you color on this in prior quarterly earnings updates where we said we expected the second half of 2026 to be the point where we lapped, some of those pricing headwinds, if you like, that we've seen over the course of of the last few years. That was certainly the case in the third quarter, quarter-over-quarter.
Blended ASPs were up about 2.5%, and and for the for the year-over-year period, they're up almost 5%. We feel that across all of the end markets that we operate in now that pricing is a much more constructive dynamic.
Obviously, mix is a is a key component to that as well. We are servicing a richer mix of demand within the end market portfolio that we have.
Looking out to 2027, look, I'd say this combination of richer mix and blended ASP mix improvements points us towards probably about a 10% uplift in blended ASP and mix for 2027, which I think is is consistent more broadly with with the market. It's consistent with what we said we were going to do as it relates to pricing actions as well that we took towards the end of the the first half of 2026.
Naturally, that serves as a tailwind, but I would say, Sahej, in the same way that we've when we've seen pricing going the other way in prior years, pricing is only one component from the margin perspective and is actually a far less impactful component than than even the broader mix dynamics are concerned, the utilization, the depreciation, the productivity within our manufacturing footprint. Like I said to CJ, we're not looking to change the targets that we put out there from the perspective of our gross margin accretion over the course of the next couple of years.
You can infer that these decisions, these announcements that we've made over the course of the last couple of months, really give us more clarity, more certainty on our ability to hit those targets. I'd say, no major change on on that front, but we're encouraged by the momentum.
Naturally, as you would expect, the announcement for the silicon interposers with TSMC, when that starts to ramp in the first half of 2028, we would expect that to be margin-accretive as well to our overall objective. No change to the targets, greater visibility, and and we think a high degree of momentum to get to those targets.
Sahej Singh
Thank you. Very helpful.
Operator
Thank you. Our next question comes from the line of Jim Schneider from Goldman Sachs.
Your question, please.
Jim Schneider
Good morning. Thanks for taking my question.
Maybe just sort of building on the theme that's been asked for the last few questions, wanted to maybe clarify more tactically where you see the various moving parts of utilization, pricing, and mix going in the first half of '27. It seems like if anything, mix is improving, pricing, as you said, is getting better.
Then I guess the question is about utilization. Do you think you're going to be able to maintain sort of at least flattish utilization, cuz it seems like given everything that's going on with the smartphone market and it's relatively dilutive margins, that mix or gross margins could actually at least stay flat in the first half if not go up?
Sam Franklin
Happy to take that one, Jim, and look, I think I'll echo what I said around some of the structural drivers that we see across those end markets. Naturally, from a Mobile point of view, we think we largely track that market.
The offset that we're seeing in terms of mix benefits from the other end markets are a tailwind from our point of view going into next year. I will say that naturally there's a degree of seasonality from the fourth quarter into the first quarter.
You can see that in prior years. Given some of the structural shifts that we're seeing within those end markets, we do think that there should be a slightly less pronounced impact from a seasonality point of view, fourth quarter into the first quarter.
Obviously, I'll give more color around that when we get to the next call. Hopefully, that helps gives you a little bit of insight from a tactical point of view.
Then, look, as it relates to 2027 more broadly and into 2028, like Tim said and like I said, we think we're increasing our visibility on getting to those objectives that we set out from a margin point of view and really have our eyes set on getting to that 40% gross margin. We think we're making good progress towards that.
Tim Breen
Maybe Jim, one one comment I'll add is about just thinking about utilization. It's also about flexibility.
We've spent a lot of time over the last 3 years really investing in our manufacturing footprint to make it as flexible as possible so that we can respond. When one market is weaker and one market is stronger, we can respond and use that capacity across where there's growth.
Obviously, there are always limitations to that, but that's definitely a factor that's helping us overall improve utilization this year and ticking up into next year as well.
Jim Schneider
That's fine. Thank you.
Then maybe just to clarify on the smart mobile device market, clearly there's been some correction there for all the reasons we understand. I'm just wanted to clarify, your outlook is unchanged on the full year.
Could you maybe characterize where you think the downstream inventory levels stand with respect to component inventories in smart mobile devices and just kind of making sure you're sort of aligned with inventory levels and you can go in terms of unit demand tracking from there? Thank you.
Tim Breen
Thanks, Jim. I think the broader topic on SMD is just how the market is quite bifurcated.
I think the high end is not that bad, right, all things considered. Obviously, can weather the memory impacts much more.
The low end is much, much worse. Our exposure is much more to the high end of the market.
I'd even say in this current environment, some of the capacity in the industry more broadly is being taken up by other end markets, which actually, in turn, leads mobile customers to come back to us and look for more supply to make sure they have enough to build what they need to build. I'd say overall, we're not seeing any kind of concerns from an inventory point of view.
Like I said, overall, we're going to track the market going into 2027, but the situation's perhaps not as bad as people might think.
Jim Schneider
Thank you.
Operator
Thank you. Our next question comes from the line of Mehdi Hosseini from Susquehanna International.
Your question, please.
Mehdi Hosseini
Yes. Thanks for taking my question.
I want to double-dip into Communication Infrastructure. Tim, can you please update us on how you see the mix between SiPh and SiGe changing into 2027, 2028?
I ask the question in this context because last time, you highlighted that in '26, SiGe mix is higher than SiPh. Again, I want to see how that mix is changing over the next couple of years.
I do have a follow-up. Yeah.
Tim Breen
No, thanks, Mehdi. I think the story, I'd say, is very simple.
The optical transition is pulling both of them very strongly, and I'd say SiGe is getting a particular pick up because of the transition to 200 gig per lane speeds, and I think that's going to continue going forward. We're sold out effectively of both.
We're adding capacity for both. We have an excellent roadmap for both, right, and I think our strategy will continue to operate on that basis.
I think both are going to see very strong growth going into '27 and beyond. Like I say, customers are now willing to put their balance sheets to work to help us invest and add capacity, again, in both those end markets, very strong.
You didn't ask it, but I'll answer anyway, the transition to technologies like NPO are going to accelerate that story even further because that requires even higher performance photonics, but also extra SiGe content as well. Those are tailwinds for the business going forward.
Mehdi Hosseini
I was actually going to follow up on NPO, which is kind of a black box. In my opinion, NPO is more about integration, heterogeneous integration.
You have PIC and EIC, which is quite different than discrete components associated with a pluggable transceiver. My follow-up question for you is, how do you see GlobalFoundries content changing from pluggable to NPO transceivers?
Tim Breen
Yeah. No, it's a great question.
I'd say overall, the transition from pluggable to NPO and to CPO, by the way, which we still believe will continue to happen, all of that creates a growing content opportunity for us because obviously, as you go forward in higher performance, the PIC has to do more, right, in different applications. You have more SiGe content in each of those applications.
Then as you get closer to the XPU, you have some of the packaging components, be that fiber attach, your die-to-wafer bonding, and so on, also play an important role. I'd say the opportunity increases as you get closer to the ultimate chip, and therefore, our investments in R&D, building the scale platform, and others have really begun to pay off very well in terms of customer interest and traction for long-term roadmap in those areas.
Mehdi Hosseini
Great. Thank you.
Operator
Thank you. Our next question comes from the line of Harlan Sur from J.P.
Morgan. Your question, please.
Harlan Sur
Good morning. Thank you for taking my questions and a great job on the quarterly execution.
June quarter utilizations were in the high 80% range. Did that increase in the September quarter, maybe towards the 90% range?
That would imply the team still has another 8 to 10 percentage points of utilization increases ahead. If that's the case, by my calculations, you still have roughly about 400 basis points of gross margin improvement in front of you just from utilizations, right?
How much of that potentially gets unlocked in 2027 as manufacturing activity and utilizations continue to increase?
Sam Franklin
Hey, Harlan, good morning. Maybe just to pick up on that, you're right, utilization in the high 80s in the second quarter.
Utilization in the third quarter was also in the high 80s. One of the reasons for that is that we've been investing CapEx through this year.
We've been adding to the capacity, which, in effect, adds to that denominator for the purposes of calculating utilization. You're right, we do still see utilization upside as an opportunity from a margin point of view, but as you heard on the call, we're going to be continuing to invest in that capacity and really sort of grow the overall corridors where we see strong demand to be able to expand margins from a mix point of view, but also from a utilization point of view into 2027.
At this point, headroom to certainly grow into from a utilization point of view, and we think we're going to keep growing that denominator as we invest CapEx dollars to grow our capacity.
Harlan Sur
No, I appreciate that. Then for Tim, on the photonics front, lasers are also in tight supply, right?
High-quality lasers, very, very tight supply situation. Marvell is paying a healthy premium to acquire Lumentum, right, partly for their indium phosphide laser portfolio.
The GF team has done a very good job in compound semiconductors, right? Silicon germanium, you talk about quite a bit, targeted for high-quality TIAs and drivers is a good example.
Indium phosphide lasers would also add to your SiPh capabilities and portfolio. Is the team considering adding indium phosphide manufacturing to your technology offerings?
Tim Breen
No, it's a great question, Harlan. You're definitely seeing a strong interest in that part of the value chain, expressed by the transaction you mentioned, but also other investments that we're hearing about in the industry.
We're focusing on the integration of indium phosphide into our technologies, right, and I think part of the roadmap is about having integrated lasers, integrated SOAs for future optical applications. By the way, just like we're also investing in novel materials for future, enhanced modulation to go to 400 gig per lane and beyond.
Harlan Sur
Yes.
Tim Breen
Part of our roadmap is what we can invest at the silicon level. Discrete laser manufacturing, not on our current roadmap, but obviously, we'll continue to be open to opportunities going forward.
Harlan Sur
Oh, thank you.
Operator
Thank you. Our next question comes from the line of Joseph Moore from Morgan Stanley.
Your question, please.
Joseph Moore
Great. Thank you.
In the last cycle, it seemed like a lot of the focus on wafer securing was coming from automotive. You had big automotive OEM deals that were working with GlobalFoundries, and, obviously, we had a shortage of cars that was driven by all of this.
As I look at things now, your automotive business is doing fine, but I worry about looking at all the capacity going to interposers, and silicon photonics, and AI. These fabs are getting full.
Do you think we could be looking at another capacity crunch in the automotive space? I guess how are you thinking about that?
How are your customers thinking about that? Are you seeing people start to focus on those supply chains in the way that they did a couple of years ago?
Tim Breen
Thank you, Joe. It doesn't get as much in the limelight, but I think the sector continues to be advancing forward in terms of the automotive sector, that is, in terms of its thinking on supply security.
We have a lot of conversations with automotive players, not just for the next 12 months, but the next kind of 3 to 5 years. A lot of them, they're very keen also to see that geographic supply diversification as well.
That plays particularly well for us given our US footprint and our European footprint. I would expect continuous investment, more engagement, more direct business opportunities in auto as well.
Many of them are doing that, both OEMs and Tier 1s. That also plays, by the way, into our custom business where a part of what we've announced in our prepared remarks was progress in things like custom radar, which is another area we're developing further within the platform.
I'd say automotive continues to be in line with what we talked about at our Investor Day, strong, consistent growth opportunity, and where GF is really very well positioned to play across multiple technologies and with multiple end customers.
Sam Franklin
Joe, maybe just more broadly as you think about some of the CapEx that we've guided to today for 2027, as you'd expect, a lot of that is going into interposers, silicon photonics, SiGe, data center applications, but we're not leaving our other end markets behind, and Automotive is a key component of that. As we think about driving towards that low double-digit percentage growth, investing into some of our automotive capacity corridors across the footprint will also feature within that overall $4 billion net CapEx that we indicated for next year.
Joseph Moore
That's helpful. Thank you.
In terms of the OEMs you mentioned that those relationships are direct, I feel like that's what's been unique about the last few years is that you're getting automotive OEMs showing awareness of foundry supply chains and things. I guess are they emphasizing it enough do you think?
Is it still very much a focus on that geographic sourcing? Is that coming from the Tier 1s or is that coming from the OEMs?
Tim Breen
I think it's both. I think part of it also is increased differentiation.
If you look at today's cars, the content growth has just tremendously increased over the last years. All of them have roadmaps to do more, right, as you move to different architectures.
Some of that's linked to electrification, but some of it's just linked to performance and feature sets of the cars. I think it's also been led by the more kind of silicon native OEMs.
By the way, I would cite, obviously, Tesla, but I would also cite the Chinese players that are increasingly setting the tone globally for what the automotive industry needs to do in terms of performance. I just think you've got a much more aware end market, and that creates a lot of opportunities for players like us.
Joseph Moore
Great. Thank you.
Operator
Thank you. Our next question comes from the line of Krish Sankar from TD Cowen.
Your question, please.
Krish Sankar
Hi. Thanks for taking my question.
I have two of them. First one, Tim or Sam, can you give an update on the silicon photonics competitive landscape?
Obviously, there is TSM Coupe, Tower, STMicro, now UMC. Also along the same path, I think the Marvell-Lumentum merger highlights one of the bear aspects, which people worry is, is it going to be into optical transceiver overbuild in 2028?
I'm just kind of curious if you have any thoughts around that, and I had a quick follow-up.
Tim Breen
Yeah. No, great, great questions, Krish.
Look, overall, it's great to see other players believing the same thing we believe, that the optical transition is just getting started. That's why you're obviously seeing people enter the space who previously weren't very engaged in photonics.
We've been doing this for 10 years. We've got very strong technology roadmap and positioning today.
We've also got a lot of investments beyond the PIC level into the packaging side, which I think will play more and more into those new applications we talked about earlier like NPO and CPO. I think perhaps even more important right now is we've got a scalable fab footprint to invest and grow with our customers without adding fab space particularly for photonics and SiGe where they need that capacity rapidly.
That's one thing they're betting on in terms of coming to GF for more of their capacity. I think we feel very confident in our competitive position within that landscape.
Look, I view the recent announcement, the Marvell-Lumentum announcement, again, as a really strong endorsement of that optical transition. Both are betting a bit, if you like, their future on optical, which I think is reassuring.
Both, by the way, are close partners with GF, have been public about that as well. We think this is a great opportunity for all of us to do more, to innovate faster, and to grow the business.
I think it's a tailwind.
Krish Sankar
Great. Thanks for that, Tim.
Then a quick follow-up on the TSMC CoWoS interposer agreement. It's a $2 billion manufacturing agreement.
Is any of it flowing through CapEx next year? Will the wafer supply there be dedicated to TSM for the first 5 years, or do you have flexibility over that?
Tim Breen
Yeah. It's part of the CapEx that Sam has talked about, definitely that's included within the $4 billion number that he's shared.
Look, interposers is a critical technology for all forms of high-performance compute where you're integrating multiple die with HBM and so on. We've had a roadmap for some time in that.
The TSMC agreement stands on its own and that's accretive in its own right. We're also engaging with a number of other customers for future interposer requirements.
These are getting increasingly sophisticated with integration of deep trench capacitors and so on. I think it's actually a very interesting area that we're spending R&D money and effort to actually build more for the future because it fulfills our sweet spot in terms of technology mix.
Krish Sankar
Thank you, Tim.
Operator
Thank you. Our next question comes from the line of Atif Malik from Citi.
Your question, please.
Atif Malik
Hi, thank you for taking my questions. You guys have been busy with the partnership announcements with TSMC, Marvell, Monolithic Power.
To what extent are these partnerships incremental to the long-term model shared at the Investor Day?
Tim Breen
I think, yeah, Sam commented on that a bit earlier. The way I think about it, Atif, is that we set out at only 6 months ago a set of strategic goals, which I think are both appropriate for the business and very much strategically aligned with where we have a right to win.
These are evidence points that we are winning in those directions with those customers. Too early to update the numbers of our strategic goals, but as Sam said, all of these give us increased confidence that we're on the right track to deliver and exceed those goals over time.
Atif Malik
Great. Then, Sam, what is the satellite communications exposure within CID, and what's the gross margin profile?
Sam Franklin
Look, we don't break out the individual components. I will say that in 2025, we gave a little bit of color around SatCom.
We delivered about $100 million of revenue within that component of the end market from a relative standing start in the prior year. You've seen publicly we've made some announcements that associate ourselves with some of those key players within the satellite communications market more broadly.
You've only got to look at low Earth orbit satellite launches and the continued momentum within that end market to see that it's an important growth vector within Comms Infra and Data Center for us. Look, more broadly, this is a technology that we're servicing that demand with, which is accretive to the long-term goals that we've set out.
Tim Breen
Maybe just to add on my side, I think one of the reasons we're seeing strong long-term momentum in technologies like SiGe beyond the data center is actually things like satellite communications, right? When you want to launch satellites 300 miles in space and have a high-performance, high-bandwidth solution, bringing that bandwidth back to Earth, you need high-performance RF technologies.
We've been doing that for a very long time, and SiGe is getting also traction from those areas as well, it's so very encouraging.
Atif Malik
Thank you.
Operator
Thank you. Our final question for today comes from the line of Chris Caso from Wolfe Research.
Your question, please.
Chris Caso
Yes, thank you. Good morning.
My first question is with regard to the CapEx. The $4 billion number you mentioned, it's a big number relative to what you guys have spent in the past.
A few questions on that. One is if you could discuss, given some of the prepayments and credits in that, how much of that is cash out the door from GlobalFoundries that would affect your cash flow for next year, just kind of separating out what's supported by others and what you're putting out yourself.
Then in terms of when that turns into revenue and kind of the timing of that. I guess what I'd really like you to answer, which you probably won't, is how much revenue gets generated by $4 billion CapEx, but I'll settle for the when.
Sam Franklin
Chris, I think that we've been relatively underinvesting from purely a CapEx point of view over the last, call it 3 years. If you look at the aggregate over the last 3 years, it's only been a little north of 10% of revenue versus what we said previously was targeting a 20% net CapEx to revenue and what we reiterated earlier this year.
The principal reason for that is the foundation of our investment decisions into capacity is demand, and we've seen a step change function in that demand outlook as we go through this year. It's for technologies across photonics, FDX, advanced packaging, SiGe, more recently what we announced with TSMC on interposers.
This has been the single biggest change in terms of how we think about that investment into the footprint. Now our customers recognize that as well, and actually, to Tim's earlier comments, they've been very, very constructive conversations in terms of the prepayment, capacity reservations for incremental capacity discussions that we've been having.
We expect those largely to close in call it the fourth quarter and into early 2027 as well. That $4 billion net number that I gave you, obviously, we don't net customer prepayments from that in terms of how we calculate net CapEx.
Think of that as $4 billion net CapEx to GF, but within that $4 billion, we expect that we'll get about call it a third of that supported by customer prepayments. You won't see that flow through as a net to CapEx, but you will effectively see it flow through towards our free cash flow.
That's why we feel good about still remaining the targets around our free cash flow margin for 2027. Then look, the other dynamic, as you said, is around government grants and broader support frameworks.
If I take the ITC as an example, that's now 35%. Now we don't get all of that 35% in-year.
In fact, some of what we'll get as a net to CapEx next year will be from ITC that was accrued in call it the 2025 time frame. We will, however, get as an offset to CapEx next year the government grants that we've announced during the course of this year.
Some of that is in relation to quantum computing. We've also got the $955 million repurposing from the original CHIPS Office grants.
About 80% of that $955 million, we expect will allocate towards CapEx. Not all of that will be allocated in 2027 as an offset, but we'll probably get the majority of that coming through in 2027 as well.
All points towards a good indicators from a free cash point of view. Then look, the way we think about the ROI is really a function of payback.
When you take that combination of the government grants, the ITC, the offsets to our overall CapEx burden, we see strong paybacks inside a sort of 2-year time horizon for most of those technologies that we outlined. It forms an important part of our investment decision-making, and given the margin profile and the mix associated with these corridors, we see a strong ROI and a relatively quick ramp to demand and revenue.
Obviously, it's really a function of how quickly we can get those tools installed, qualified, and ramped. The beauty of our expansion footprint is that we can do it within our existing four walls.
We're not reliant like some others are around building incremental fab capacity to do it. We can do it within our existing four walls, so that accelerates the time to revenue as well.
Tim Breen
Maybe I'd just add, the way we've been thinking about this is it's a unique moment for us to accelerate our business with the participation of our customers, with the participation of governments. Maintaining a very strong balance sheet, maintaining our free cash flow generation objectives, it's the right way to navigate the current situation that we're in.
Operator
Thank you. This does conclude the question-and-answer session of today's program.
I'd like to hand the program back to Eric Chow for any further remarks.
Eric Chow
Thank you very much for joining today. We look forward to seeing you at the UBS conference on December 1st.
Thanks again.
Operator
Thank you, ladies and gentlemen, for your participation in today's conference. This does conclude the program.
You may now disconnect. Good day.