Intellicheck, Inc.
NNASDAQ:IDNQ3 FY2026 · Earnings Call TranscriptNovember 12, 2026
Operator
Please note that this conference is being recorded. I'll now turn the conference over to Keaton Olsen, Investor Relations Manager.
Thank you, you may begin. Thank you, operator.
Good afternoon everyone, and thank you for joining us today for Intellicheck's third quarter 2026 earnings call. Before we begin, please note that today's call includes forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995.
Words such as will, believe, expect, anticipate, and similar expressions identify these statements. These include statements about the customer transition we will discuss today, our expectations for revenue, profitability, and adjusted EBITDA, our tax valuation allowance, and the expected benefits of our products and partnerships.
These statements are based on management's current expectations as of today, November 12th, 2026, and involve risks and uncertainties that could cause actual results to differ materially. Those risks are described in our filings with the SEC, including our most recent Form 10-K and Form 10-Q.
The company undertakes no obligation to update these statements. Certain figures on this call have been rounded.
Management will also discuss non-GAAP financial measures, including adjusted EBITDA and adjusted gross margin, which is adjusted gross profit as a percentage of revenues. Operator: Please note that this conference is being recorded.
I'll now turn the conference over to Keaton Olson, Investor Relations Manager. Thank you, you may begin.
Keaton Olsen
Thank you, operator. Good afternoon everyone, and thank you for joining us today for Intellicheck's third quarter 2026 earnings call.
Before we begin, please note that today's call includes forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. Words such as will, believe, expect, anticipate, and similar expressions identify these statements.
These include statements about the customer transition we will discuss today, our expectations for revenue, profitability, and adjusted EBITDA, our tax valuation allowance, and the expected benefits of our products and partnerships. These statements are based on management's current expectations as of today, November 12, 2026, and involve risks and uncertainties that could cause actual results to differ materially.
Those risks are described in our filings with the SEC, including our most recent Form 10-K and Form 10-Q. The company undertakes no obligation to update these statements.
Certain figures on this call have been rounded. Management will also discuss non-GAAP financial measures, including adjusted EBITDA and adjusted gross margin, which is adjusted gross profit as a percentage of revenues.
Definitions and reconciliations to the comparable GAAP measures are in the press release we issued this afternoon. We will begin today's call with Bryan Lewis, Intellicheck's President and Chief Executive Officer.
He will be followed by Adam Sragovicz, Chief Financial Officer. Following their prepared remarks, we will take questions.
I'll now turn it over to Bryan.
Bryan Lewis
Hey, thanks Keaton, and hello everyone. Thank you for joining us today.
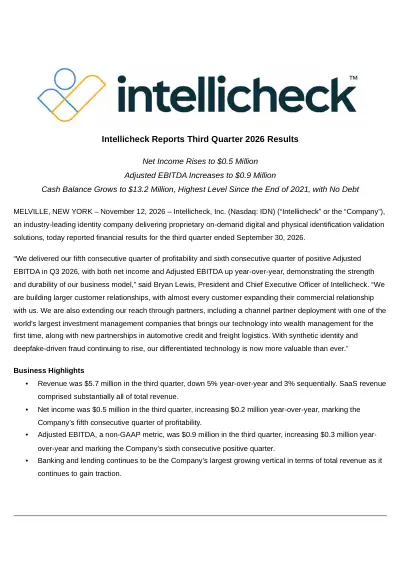
I'd start by saying there's several things I want you to take away from our third quarter performance. First, we continue to be profitable with $471,000 of net income and $892,000 of adjusted EBITDA in Q3.
Our $13.2 million cash balance at quarter end is at the highest level since the end of 2021, and we have a debt-free balance sheet, which will support continued investment in our growth priorities. Second, Intellicheck continues to bring on new customers, and by and large, our existing customers continue to expand their usage and commitment to us.
Third, we win and defend business against competitors that come in and try to play the "we're good enough, and we will cut our price" game. I'll give you some details on these items later on, but in short, four sources continue to deliver growth for us: deeper adoption inside existing accounts, competitive displacement, rapid onboarding, and our customers' own M&A activity.
I believe the fact that our customer base continues to generate more value demonstrates the validity of our product. With that, we grew 6% across new and existing accounts.
I will quickly speak to the client who decided on a redundancy program, meaning no single vendor would run any mission-critical portion of their business. They continue to tell us they are in an evaluation period, and I want to make this point very clear.
They continue to tell us they are evaluating if that is the right strategy for them. I'm going to quote from them, "We continue to see Intellicheck as a key player in our vendor strategy to provide resiliency and redundancy across all of our our use cases."
In fact, they signed a new purchase order. They remain committed to putting in place our new API, which gives them access to many more risk signals, particularly in the digital space, as opposed to the years-old API they are currently on.
Can I say we'll retain as much of the business as we had? The answer is I can't.
Can I say we're fighting to keep what we had? The answer is yes.
Given we win head-to-head on accuracy against our competitors, I look forward to the fight. I believe the key to our growth, and this will continue to be key, is the diversification strategy we put in place a few years ago.
What once was rightly called a company dependent upon retail credit card transactions is no longer the case. We are in roughly 14 diverse industry groups today, and as criminals find new ways to steal, that industry base can easily grow.
The great thing is once we get into an account, we grow, through either new use cases or selling additional risk signals to a client. The banking and lending market remains central to that effort, and these are high-value clients.
Our focus includes banks, credit unions, card issuers, fintech platforms, and alternative lenders. Across these customers, we can support identity verification in person, online, and through the call center, giving us multiple ways to expand the scope of the relationship.
Our goal is to create more entry points into an account and more reasons for a customer to use Intellicheck. A new customer can start with one workflow, while our broader platform gives us ways to support additional identity checks as that relationship develops.
We are focused on turning these opportunities into ongoing revenue, rather than simply increasing the number of names on a customer list, which is still important to us. We already serve five of the top 10—I'm sorry, we already serve five of the top 12 US banks and card issuers, with our technology used across more than 8,000 bank branches, and growing, and thousands of retail locations where our customers issue credit and perform account look up.
That footprint gives us a base from which to pursue additional workflows and and locations alongside new accounts. The focus is on the revenue opportunity within each relationship, not simply its initial size.
That opportunity extends beyond the barcode check alone. Our modular services include document liveness, document verification, face verification, international document verification, and device confidence.
They let us address different customer requirements within a broader relationship. The priority is to turn those capabilities into additional use cases and revenue, not simply add products to a presentation.
Since our last call, we announced developments that show how this strategy reaches beyond our existing accounts. In August, a recently signed channel partner secured a major deployment with one of the world's largest investment management companies.
That brings our technology into wealth management for the first time, supporting both fraud prevention and the auto—I'm sorry, the onboarding experience for legitimate customers. The channel model matters because our partners can incorporate Intellicheck into the services they already provide and deploy it across their enterprise customer base.
We do not have to build every customer relationship through a direct sale. It brings our technology into another high-van—high-value financial services market through a partner's enterprise relationship, rather than requiring us to build a direct sales channel into every respective customer.
In October, we reached a partnership agreement with Agility Credit, an approved automotive credit bureau reseller. It places our identity verification ahead of the credit pull within a platform that also includes credit data, device intelligence, and compliance workflows.
We expect this partnership will help grow our automotive dealer scanning volumes. We also entered—recently entered into a partnership with Kamiteaux, the company behind Dock Optimizer, to help prevent fraudulent freight pickups, giving us another way to extend our technology into logistics through the workflows these companies already have in place.
The integration puts identity verification into the driver check-in process, tying the verification results to the driver, carrier, and the load. You might have seen our recent collaboration with DESKO, highlighting another application, pairing document capture hardware and our verification software with an integrated biometric camera.
The prototype was announced for the Money 20/20 showcase last month, demonstrating the potential to bring document validation and in-person facial capture into one workflow at a bank counter or other point of transaction. DESKO has about 500,000 scanners in place across the US.
We believe this collaboration, combined with our desktop delivery method, will be a very effective channel for us to get into the smaller banks and credit unions who we feel are underserved by their captive software providers. A few other highlights to review.
One of the most well-capitalized PE-owned competitors recently came after one of our renewals. This competitor continues to try and compete on price, and they did not succeed as we secured the renewal.
I believe this shows that when pain, as in losses for the client, are high, good is not good enough. The better product wins, not price.
Our clients' M&A also helps us grow. In September, one of our bank clients completed its merger with another, adding 300 new branches to the network, using Intellicheck to speed up customer acquisition and fight identity theft.
Also, one of our delivery clients is expanding use cases and regions, and our belief is that will continue. Manufacturers that sign with us to identify who's on the assembly line continue to enforce that their suppliers use us as well.
One auto client alone had 10 suppliers sign with Intellicheck. I should also talk about the diversity of the products we offer, because I think people forget that.
Facial biometrics, liveness, deepfake detection, analysis to see if the document has been tampered with or is a photo of a real document. These are all products that help us our help us expand our client and industry base.
This also helps lead to expansion with with clients. For example, we have a small client providing escrow services to the title space that within months of signing with us doubled their spend as they added some of these new services.
We believe diversification of both the client base and products offered has been the right strategy. I am always asked about the social media client, and here's what I can say.
They have fixed all of their issues remated related to image quality, which is in their control, whereas prior to the fix they put in, upwards of 30% of what they sent us could not be processed. After their fix, only about 0.6% could not be processed.
Again, I like to use customer words. I asked them if we were talking to the right people, the answer was, "You have found the right person."
The decision to expand is mostly engineer-driven and data-driven, and the numbers all look good. I have had So as I have said, they remain a wild card.
I can't make a definitive prediction, but the data looks good, as they have said. These opportunities build on the same underlying technology.
We analyze hidden, authoritative security data in ID barcodes, rather than relying on whether a document looks real. Our longstanding AAMVA relationship and experience across more than 250 valid ID types support that differentiation.
That approach is designed to, first and foremost, help customers onboard good clients faster. I always point to one of our banks who was hoping for a 2% uplift in completed online new account openings, and actually realized a 23% uplift, 63% of which were the coveted Gen Z demographic.
Stopping identity theft is almost a byproduct of the speed at which we can enable customer acquisition. Our software-based model lets customers use the hardware they already own and support their in-person, online, and call center channels under one contract.
For us, the commercial objective, alongside adding new logos, is to expand deployment across those channels, add the identity signals a customer needs, and increase the revenue opportunity within the relationship. Before I hand the call over to Adam, I want to highlight that our differentiation and our increasing agility in going to market, including with new partners, position us to address the real challenge of rising fraud activity.
Synthetic identity fraud and overall and deepfake-driven fraud continue to be significant challenges for commercial activity, and there is no sign this will slow down anytime soon. This trend, while unfortunate, serves to make our technology and product solutions more valuable than ever before.
I am confident this value will be recognized by an increasing number of channels, leading to new revenue opportunities, and that our technology is distinguished from what most of our competitors can offer. I am equally confident that as we execute, this differentiation will lead to new growth opportunities that translate into growing revenues and improving cash flow.
With that, I'll hand it over to Adam to walk you through the quarter and the financial detail.
Adam Sragovicz
Thanks Bryan, and good afternoon, everyone. Third quarter revenue came in at $5.7 million, down 5% from a year ago and 3% from the second quarter.
The primary driver of the year-over-year decline was the fact that Q3 2025 included nonrecurring engineering revenue. Both net income and adjusted EBITDA for the quarter were above the third quarter of last year, coming in at net income of $471,000 and adjusted EBITDA of $892,000.
That gives us five consecutive quarters of positive net income and six consecutive quarters of positive adjusted EBITDA. I'll walk through the revenue detail, the rest of the P&L, and the balance sheet.
For the first nine months of 2026, revenue rose 7% to $17.2 million, and SaaS revenue grew 8%. Gross margin was 90.9%, up [from?]
90.5% a year ago. Adjusted gross margin, which excludes noncash amortization of capitalized software, came in at 93.3% compared to 92.8% last year, as our cost of revenue before amortization fell 11% to $386,000.
Operating expenses were $4.9 million, down 7% from a year ago and flat with the second quarter. R&D fell 16% year-over-year to $1.2 million.
Most of the decline came from lower spending on outside development firms and a lower incentive compensation accrual, partly offset by a full quarter of costs for data science hires we made in the spring. SG&A came in at $3.7 million, 3% below last year.
We spent less on trade shows and sales headcount, and more on customer success staff and professional fees, mostly legal and investor relations work, along with a catch-up in stock-based compensation. Professional fees also account for $201,000 sequential increase in SG&A.
Operating income was $367,000 compared with $238,000 last year. Other income, mostly interest on our cash, doubled to $104,000.
Net income was $471,000, or 2 cents per diluted share, compared with $290,000, or 1 cent per diluted share, in the third quarter of 2025. Adjusted EBITDA was $892,000, a 15.5% margin, up from $631,000 a year ago.
Stock-based compensation rose to $338,000 from $204,000, largely from catch-up adjustments, and depreciation and amortization was $187,000. For the first nine months of 2026, net income was $1.8 million, or 9 cents per diluted share, against a loss of $279,000 in the prior-year period.
Adjusted EBITDA reached $2.9 million compared with $688,000. We recorded no income tax expense.
We had about $30.5 million of federal NOLs at the end of 2025, and we continue to carry a full valuation allowance against our deferred tax assets. We ended September with $13.2 million in cash and no debt, up about $1.3 million from June 30th and $3.5 million from year-end.
Cash from operations was $3.3 million for the first nine months of 2026 compared to $2.1 million in the same period last year, which puts the third quarter at roughly $1.1 million. Last quarter, I mentioned we expected operating cash flow to decline and that we could use some cash in future periods.
The third quarter came in better than that, mainly because the timing of customer payments and renewals. Renewal timing also drove deferred revenue up to $1.6 million from $1.2 million at June 30th.
Accounts receivable was $2.7 million, flat with June and down from $3.4 million at year-end. Our largest customer carried no receivable balance at quarter end.
Working capital was $13.5 million, and stockholders' equity was $23.6 million. The fourth quarter may carry a lower volume run rate at our largest customer for all three months, where the third quarter only absorbed it for part of the period.
As Bryan said, they continue to tell us this is an evaluation and the volumes have seen some volatility. Our seasonal retail lift usually comes in the fourth quarter as well, and we'll keep an eye on how much of the gap that covers.
We still expect to be profitable on a net income basis and to generate positive adjusted EBITDA for the full year of 2026. We will hold the line on costs while we keep funding engineering and the go-to-market work behind desktop and our channel partnerships.
We have no plans to raise capital in the near term. With that, operator, we'd like to take questions from our institutional analysts.
Operator
Thank you. We will now be conducting a question and answer session.
If you would like to ask a question, please press star, one from your telephone keypad, and a confirmation tone will indicate your line is in the question queue. You may press star, two if you'd like to remove your question from the queue.
For participants using speaker equipment, it may be necessary to pick up your handset before pressing the star keys. One moment please while we poll for questions.
Once again, that's star, one. Thank you.
Our first question will be coming from the line of Mike Grondahl with Northland. Please proceed with your questions.
Logan Hennen
Hey guys, this is Logan on for Mike. Thanks for taking our question.
First one, can you provide us with some insight into how the remaining customer base, excluding the large customer, as well as some of the key verticals performed in the quarter? Thank you.
Bryan Lewis
I'd say banking, lending continues to grow. That's one of our key verticals.
Automotive, through partnerships, also continues to grow, because that's, again, a market I love partnering with 19,000 rooftops that are tied to a name brand, and I think about 16,000 rooftops that are independents. Get into them through those guys.
If you're looking for exact numbers, I think Adam might have some of that, but we do see some good things happening during this time of year because stadiums are full. Football is going on, so that helps us.
I love that space. I love getting into the stadium space, and we're doing quite well there because it's, again, no new hardware, really simple to make sure that I'm of age and that I should be able to get that beer.
Let me know, Logan, did that answer your question?
Logan Hennen
It was helpful, yes. I think what I was kind of looking for, last quarter you disclosed that the remaining customer base grew 19% in the first half of 2026, excluding that customer.
Do you guys have a number for that remaining customer base in 3Q?
Bryan Lewis
Everything grew 6% in 3Q.
Logan Hennen
Got it. Appreciate that.
Bryan Lewis
It generally can become a slow quarter because people are worried about doing integrations and other things going into Q4, if they're anyway related to dealing with a retail customer, cuz that is the holiday season and they want to make sure it's done. The first half, I think if you look at our numbers historically, it's always been the best part of adding new names and other things.
Now, I also think the diversification bit is going to change that because we are adding, you're a trucking company, you're a manufacturer, you don't care about that stuff. There's no point-of-sale system you're worried about going down.
They can do what they want, when they want, which I think is the good bit about diversifying who we were, and again, getting away from, as I said, people justifiably thought we were just a credit card company. We're not.
Logan Hennen
Appreciate that, Bryan. That's very helpful.
Then one last one from us. Regarding wealth management, can you help us understand how the channel partner deployment, how that came to fruition?
Maybe how we should think about expansion potential within that vertical? Thank you.
Bryan Lewis
That came because that channel partner was using a product offered by AAMVA called DLDV, and it wasn't working because two of the largest states don't allow it to be used for anything, two major states require that I give prior written authorization to the DMV for somebody to check me against the database, and their specs for that product even say it does not say that the document is real. They did research, came to us, and said, "We think you're the guys."
We did a joint sales pitch on that investment management firm, and they realized, "Yep, this is what we need. It's simple.
It's easy." Cuz what most people are really worried about is how hard is it for their end customer to do it.
Many of our customers don't want to do things like facial recognition cuz it scares people. We offer it, but I would say the majority of our digital customers don't do it because they're so confident in our ability to say that's a fake license, you know you have a bad actor.
The way that we do it makes it easy for anybody. I don't know about you all, but getting older, people's hands shake.
It's really hard to take a good picture of a driver's license when your hand shake. We don't need that.
We turn the phone into a scanner, and I will tell you that before I can even almost open that bit and get my license in front of it, it is already caught and scanned the license. We make it really simple for their customers to use us, onboard, and validate.
Logan Hennen
That was very helpful, Bryan. Thank you, and best of luck the rest of the year.
Bryan Lewis
Cool. Thank you.
Operator
Our next question is from the line of Rudy Kessinger with D.A. Davidson.
Please proceed with your questions.
Rudy Kessinger
Hey guys, thanks for taking my questions. First, I do want to follow up on the largest customer.
I do see in the 10-Q that as of Q4, they have reduced down to I think it says a 65% to 75% reduction in their scan volumes versus what they were at previously. What have they communicated to you?
I know you said they have purchased a new scan bucket, I believe. What's your gut tell you, just based on what they've communicated about what they'll be running at in Q4 and into 2027?
Is there a good chance they might bump those back up, or should be expected it's at that poor decline for the foreseeable future?
Bryan Lewis
Hey Rudy, I wish I had a magic ball and I could tell you what they're going to do. All I can tell you is they continue to tell us that this is an evaluation.
There is tremendous volatility day-to-day in the volumes we are seeing come in from them. I think it's up to them to make the decisions that they want to make.
This is the biggest shopping season that we are basically into where most of the fraud happens. All I can say is they continue to say we're a valued partner.
They're evaluating things, and they'll let us know. Me, I don't make stuff up, I don't lie about it.
All I can say is that's what they've said. Sandra and team are all over them, like what can we do, how do we do it.
I think it's going to take their clients who will end up sharing the loss on fraud to realize, "Yeah guys, we need to go back to what we were doing." That's my gut, but we'll see.
Rudy Kessinger
Okay. Then secondly, I know you're lapping the large deal with the Southeast regional bank that hit Q3 last year, and you had mentioned there was the deceleration, 19% to 6% on the rest of the business ex your largest customer.
As you look to Q4 and into next year, just based on your pipeline and what you have visibility to, what kind of growth in the business ex that customer are you expecting? I'm,
Bryan Lewis
as you know Rudy, we don't really give guidance, but I'm looking at really focusing on channel partners, who I think are part of the quickest way that we can get into new customers. We've got some channel partners that we are in discussions with who do volumes that are significantly larger than any one of our banking clients.
That is the focus right now, because I think that's the quickest route to revenue, while we also chase the whales and then also go after, again, what I consider underserved by their core banking providers, the credit unions, the smaller banks, those folks who are getting whacked by fraud, but are held captive by whoever is giving them the software. Between this DESKO alliance, this desktop tool that we have to deliver our product, those are the areas where I see growth.
New names in financial services through desktop or DESKO, and then new names in interesting, large, and new markets within other partnerships.
Rudy Kessinger
Got it. Super helpful.
That's it for me. Thanks for taking my questions, guys.
Bryan Lewis
Cool.
Operator
Thank you. At this time, I'll turn the floor back to management for closing remarks.
Bryan Lewis
Everybody, thanks again for joining the call. Just want to reiterate, we're focused on growing logos, increasing the value of each relationship, and using our partners to reach customers we could not reach as quickly on our own.
That means new deployments, broader use of our services within existing accounts, and turning signed opportunities into recurring revenue. Thank you all for your time today.
We look forward to updating you on our progress when we report our fourth quarter and full-year results. Thank you, and have a good evening.
Operator
This will conclude today's conference. You may disconnect your lines at this time.
We thank you for your participation, and have a wonderful evening.