InfuSystems Holdings, Inc.
AAMEX:INFUQ3 FY2026 · Earnings Call TranscriptNovember 10, 2026
Operator
Good day, and welcome to the InfuSystem Holdings third quarter 2026 financial results conference call. All participants will be in listen-only mode.
Should you need assistance, please signal a conference specialist by pressing the star key followed by zero. After today's presentation, there will be an opportunity to ask questions.
To ask a question, you may press star then one on a touchtone phone. To withdraw your question, please press star then two.
Please note, this event is being recorded. I would like to turn the conference over to Mr.
Stefan Eftychiou with Bristol Investor Relations. Please go ahead.
Stefan Eftychiou
Good morning, and thank you for joining us today to review InfuSystem's financial results for the third quarter ended September 30, 2026. With us today on the call are Carrie LaChance, Chief Executive Officer, and Barry Steele, Chief Financial Officer.
After the conclusion of today's prepared remarks, we will open the call for questions. Before we begin with prepared remarks, I would like to remind everyone certain statements made by the management team of InfuSystem during this conference call constitute forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995.
Except for statements of historical fact, this conference call may contain forward-looking statements that involve risks and uncertainties, some of which are detailed under risk factors in documents filed by the company with the Securities and Exchange Commission, including the annual report on Form 10-K for the year ended December 31, 2025. Forward-looking statements speak only as of the date the statements were made.
The company can give no assurance that such forward-looking statements will prove to be correct. InfuSystem does not undertake and specifically disclaims any obligation to update any forward-looking statements, except as required by law.
Additionally, management may discuss certain non-GAAP financial measures during today's call. Reconciliations of those measures to the most directly comparable GAAP measures are contained in today's earnings release.
Now, I'd like to turn the call over to Carrie LaChance, Chief Executive Officer of InfuSystem. Carrie?
Carrie Lachance
Thank you, Stefan, and good morning, everyone. Welcome to InfuSystem's third quarter fiscal year 2026 earnings call.
Thank you for joining us today. I will provide a third quarter overview, highlighting our progress in the quarter.
Then Barry will provide additional detail regarding our financial results and the primary drivers of the quarter. I will then come back with some closing comments before opening the line to questions.
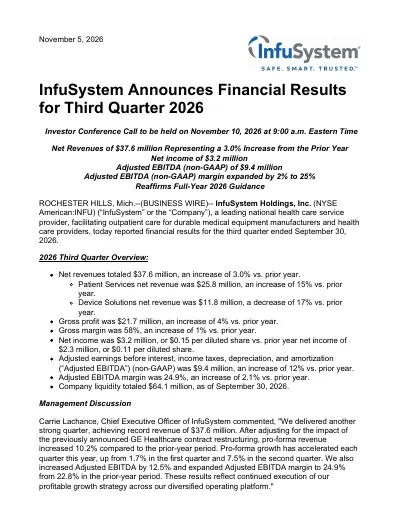
We are pleased with the third quarter results, and believe they demonstrate continued execution of our profitable growth strategy. During the quarter, we achieved record revenue of $37.6 million, and after adjusting for the previously announced GE HealthCare contract restructuring, generated pro forma revenue growth of 10.2%.
Pro forma growth has accelerated each quarter this year, up from 1.7% in the first quarter and 7.5% in the second quarter. We also expanded adjusted EBITDA margin to 24.9% from 22.8% in the prior-year period.
These results reflect the continued strength of our diversified operating platform and the progress we have made executing our strategic initiatives. The most encouraging aspect of the quarter was the continued growth we are seeing from investments made over the last several years.
Our oncology business remained strong, while our wound care business continued to scale rapidly. In particular, our compression therapy product lines, focused on lymphedema treatments, are becoming an increasingly meaningful contributor to our growth and further validate our strategy of leveraging our existing patient services infrastructure, clinical capabilities, and payer relationships to support complementary therapy categories.
Wound care revenue increased 112% during the quarter, including approximately $1.6 million of growth from compression therapy products. Lymphedema remains a chronically underserved market, and we believe there is still a lot of runway ahead.
We also continued to benefit from actions taken to improve the profitability of Device Solutions. The restructuring of our GE HealthCare contract and ongoing operational improvement initiatives contributed to higher profitability while helping us improve operating cash flow and further strengthening our balance sheet.
At the same time, ERP-related expenses continued to decline as implementation activities gave way to stabilization and optimization efforts. As we look ahead, we continue to see opportunities to improve the economics of our patient services platform through additional workflow automation and software-enabled process improvements.
We believe reducing the cost of processing third-party payer claims can further enhance operating efficiency while supporting growth opportunities in wound care and other therapy categories. We expect to begin making modest additional investments in these initiatives during the fourth quarter.
These investments are intended to build upon the technology foundation we have already established and further strengthening our ability to scale efficiently over time. Based on the performance through the first nine months of the year, we are reaffirming our full-year guidance.
We continue to expect pro forma revenue growth of 6% to 8% for 2026 after adjusting for the impact of the GE HealthCare contract restructuring, and continue to expect adjusted EBITDA margins to remain in the low to mid-20% range. We remain focused on disciplined execution, profitable growth, and creating long-term value for our shareholders.
With that, I'll turn the call over to Barry.
Barry Steele
Thank you, Carrie, and good morning, everyone. I'll provide some additional detail regarding the financial results and the primary drivers for the quarter.
Third quarter revenue increased 3% to $37.6 million. After adjusting for the impact of the GE HealthCare contract restructuring, revenue grew 10.2% on a pro forma basis.
The quarter benefited from strong performance in oncology and wound care, partially offset by lower Device Solutions revenue associated with the contract restructuring and lower equipment sales activity. Within Patient Services, oncology grew 7.2% and continued to perform well, driven by additional treatment volume, improved reimbursement fit rates, and collections.
Wound care again delivered exceptional growth, led by compression therapy products and negative pressure wound therapy. While we recorded certain reserves associated with adjustable compression wraps during the quarter, underlying demand for the category remains strong, and wound care exceeded our prior forecast.
Within Device Solutions, results were mixed. Equipment rentals, depot services, and non-GE field services performed well.
Adjusting for the GE HealthCare restructuring, biomedical services revenue grew 19.8% on a pro forma basis. Biomedical services in particular benefited from both strong device repair volume at our repair depots and increased field-based projects outside of the GE HealthCare contract.
These positives were partially offset by lower equipment sales and softer disposable product revenue than anticipated during the quarter. Gross profit increased 4.4% year-over-year, and gross margin expanded to 57.8% from 57.1% in the prior-year period.
The largest positive contributors to profitability continue to be the improved economics associated with the GE HealthCare contract restructuring, ongoing procurement initiatives, productivity improvements, and the favorable impact of higher revenue. These factors more than offset pressure from product mix changes within Patient Services, reserve activity, and inflationary cost increases.
Net income was $3.2 million, or 15 cents per diluted share, compared to $2.3 million, or 11 cents per diluted share, in the prior-year period. Adjusted EBITDA increased 12.5% to $9.4 million, and adjusted EBITDA margin expanded to 24.9% compared to 22.8% in the prior-year period.
The improvement reflects the benefits of revenue growth, the previously announced GE HealthCare contract restructuring, operational improvement initiatives, and lower ERP-related implementation expenses, partially offset by changes in revenue mix and other normal cost pressures. Turning briefly to cash flow and the balance sheet.
Operating cash flow for the first nine months of 2026 increased 5% to $18.1 million, including 10.4% $10.4 million in the third quarter. During the same period, the company invested $8.7 million in medical equipment and repurchased approximately $5 million of common stock.
We ended the quarter with $54.1 million of liquidity, and reduced net debt by $8.9 million during the quarter to approximately $10.6 million, or 0.32 times trailing adjusted EBITDA, down from 0.61 times at the end of June. These metrics were achieved despite experiencing approximately $5 million of temporary working capital pressure during the quarter related to billing and invoicing issues following our ERP implementation.
Importantly, this was not driven by customer demand, reimbursement changes, or credit deterioration. The majority of the increase relates to invoices that were either delayed or required customer-specific revisions before payment could be processed.
These revisions were primarily related to customer-required invoice formatting associated with the new invoice format, rather than errors in the underlying data. We identified the issue during the third quarter, implemented corrective actions, and collection trends improved steadily through September and into October.
Based on October collection activity, we estimate roughly $1.3 million of the excess receivable balance has already converted to cash. We expect further normalization of collections over the coming months.
Overall, we remain very pleased with the continued improvement in cash generation and balance sheet flexibility. Regarding guidance, our updated forecast remains consistent with the outlook communicated earlier this year.
Based on our current expectations, we continue to expect full-year pro forma revenue growth within our previously communicated range of 6% to 8%, and adjusted EBITDA margins in the low to mid-20% range, including the modest additional investments Carrie mentioned that we expect to begin in the fourth quarter. Our most recent forecast remains supportive of these objectives.
I will now turn the call back over to Carrie.
Carrie Lachance
Thanks, Barry. Our third quarter progress reinforces the focus for the balance of the year: advancing our growth priorities, executing with discipline, and strengthening our platform to support greater scale and long-term value creation.
Operator, we are ready for the Q&A portion of the call.
Operator
We will now begin the question-and-answer session. To ask a question, you may press star then one on your touchtone phone.
If you are using a speakerphone, please pick up your handset before pressing the keys. If at any time your question has been addressed and you would like to withdraw it, please press star then two.
At this time, we will pause momentarily to assemble our roster. Our first question today comes from Tollef Kohrman of Craig-Hallum.
Please go ahead.
Tollef Kohrman
Hello, and thank you very much for taking the questions, and congrats on the nice quarter. This is Tollef Kohrman on for Matt Hewitt.
Really strong performance out of wound care, and you noted the 112% growth and strength from compression therapy lines. What are your expectations in regards to volume for the rest of the year, and where do you see that business trending in the coming periods?
Thank you.
Carrie Lachance
Hi, good morning, Tollef. Great question.
I appreciate that. We continue to see the referrals coming in relatively strongly.
We have the new systems that are allowing that volume to come in pretty efficiently on that. We do continue to expect the volume to remain as it did in the third quarter for the fourth quarter.
Certainly, as we talk about that new system that we're implementing over this quarter and the fourth quarter, adding to our new ERP and our new revenue cycle system, that will enhance growth for next year. We do expect some continued strength over the next few quarters.
Tollef Kohrman
Awesome, great to hear that. Then you mentioned modest additional investments.
What are your return expectations, and where should we expect to see those improvements? Thank you.
Barry Steele
I'll jump in on this one. It's the same things we've been working on with our revenue cycle system, but even enhancing its we'll say machine learning and efficiency capabilities even further with additional software that kind of complements it.
We believe that we'll see pretty quick turnaround in terms of saving costs that offsets the cost of the project. More importantly, the key here is for us to continue to lower the breakeven point for processing claims so that we can bring in more business more efficiently, even smaller claims with new partners.
That's really the driver. We're finding ways to be able to scale faster and be more efficient because that's required for us to continue to grow in the categories that we've been adding to.
Tollef Kohrman
Awesome, great. Thank you for that detail.
Carrie Lachance
Thanks, Tollef.
Operator
Our next question comes from Jim Sidoti of Sidoti and Company. Please go ahead.
Jim Sidoti
Hi, good morning. Thanks for taking the questions.
I just want to get this one out of the way. The issue that caused the delay in the earnings release and the conference call, is that 100% resolved at this point?
Barry Steele
It's completely resolved. It was something came up at the very last minute literally in the evening of Monday.
We had a question. We didn't have a quick answer, and we decided that for us to fully get our audit firm comfortable, we delayed the earnings for 48 hours.
It's completely behind us. No changes to the financials whatsoever.
Jim Sidoti
Great. The strong performance for the lymphedema business, is that all ongoing sales?
Was there any stocking or pipeline fill in those results?
Carrie Lachance
No, ongoing new referrals. That's all new business for us.
Jim Sidoti
Great. The oncology business, it continues to just do very, very well.
What's driving the growth there, and do you expect that to continue?
Carrie Lachance
We do. Our oncology sales team, really strong team.
They continue to add new customers. Our rates are increasing and our collections are increasing.
We have been working on improved workflow wins within our oncology customers. That's implementing with their ERP, producing automated reports, and really streamlining that improved connection between the customer and InfuSystem to ensure both accuracy and receipt of all our referrals.
We do continue to expect that, as well as adding new customers.
Jim Sidoti
At the beginning of the year, I think you said you weren't going to move oncology onto the new revenue cycle management systems right away. Has that happened at this point?
Carrie Lachance
It hasn't yet. We're working on that.
That is actually one of our goals by end of year. It may sneak into Q1 of next year, but working through some of the ERP, and Barry talked about a couple of the just delays and issues with our current ERP.
Obviously up and running and functioning well. We're stabilizing that system, etc.
We did delay that oncology move over. We want to get that right.
It's a big portion of our business, and so we are working through those processes, and hopefully by end of year, but it may sneak into Q1 just a little bit.
Barry Steele
I was just going to add, our priority is to improve the systems so we bring new business in. Oncology is gravy, and that we definitely will get some efficiencies and things out of moving it over.
As you can tell, oncology's volume's growing nicely, and we're really focusing on making it possible to bring new business in, for sure.
Jim Sidoti
Okay. It's not uncommon at all to have a couple hiccups when you move to a new ERP system.
At this point, do you think you're past those?
Barry Steele
There's still things that we're working on. One of the things that nobody's asked about yet is in the quarter, we were a little bit late on getting some collections in.
Part of the things we're working on is fixing how our invoices appear and how we get invoices to customers. Those are things that are making tremendous improvements, and we do expect that next year will be the year that we start to get some benefits out of the system, although I would say that we're getting some already.
It's a great foundation for making even more further enhancements and improvements in various areas. All right.
Jim Sidoti
I'll just wrap up with that, the cash flow is strong even without those improvements. Once those improvements are complete, I would expect cash flow to get even better.
What's your priority for use of cash at this point?
Barry Steele
We haven't changed. Obviously, we have priorities for cash flow or capital allocation.
We would like to invest in the company, do new things. We're investing in systems and things, as although we're not needing to invest a lot of cash in those things.
Buying back shares is something we've been doing. It's kind of all-of-the-above strategy, but we definitely are building up a little arsenal at the moment.
Jim Sidoti
All right, great. All right, thanks again for taking the questions.
Carrie Lachance
Thanks, Jim.
Operator
Our next question comes from Benjamin Haynor of Lake Street Capital Markets. Please go ahead.
Benjamin Haynor
Morning, thanks for taking the questions. First off for me, just on the adjusted EBITDA margin guide, thinking about low single digits to or low to mid-20s, I should say, that's implies a fairly big range for Q4.
I think if you do the math, it's Q4 EBITDA could be $5 million or could be $15 million, depending on how you look at low to mid-20s. Is there any refinement that you could offer to how you think about Q4?
Barry Steele
Thanks, Ben. Maybe one thing to point out, I saw your note.
Maybe we view what low to mid means a little bit differently than others. It's definitely not 20% to 25%, it's a little tighter than that.
It's more like 22% to 25%. Where we've been tracking is right in the middle of what we think that means.
Benjamin Haynor
That's helpful. Thanks for the clarification there.
Then, there's a lot of moving pieces with the ERP implementation, you're getting some benefits now, more to come in 2027. With what you've kind of laid out there now and whatever road map you have in place, do you see kind of gaining all the or the bulk of the benefits that you'd get midway through next year, by the end of next year, in 2028?
How do you think that ultimately tracks?
Carrie Lachance
I can let Barry touch in from a from maybe a margins perspective. However, I I would say from a volumes perspective, by by mid-year next year, you're really going to see us the the growth be able to come in, adding new partnerships and and being able to to ramp successfully there.
I would I would really count on by by mid-year next year, continuing throughout the end of the year, of course.
Barry Steele
I would just add on a margin picture, there's some cross-currents running here. Some of the new business we see coming in has lower gross margins.
We're working to make sure that we can lower our cost of processes so we can keep the same EBITDA margin. Yet also as we go through time, we see cost pressures and inflationary impacts, we're trying to combat those.
We do think that there's plenty of opportunity to help margins even improve, right? This is taking costs out with the ERP processes, even taking working capital out if possible, and making our claims processing more efficient on base business, like the oncology.
We're working on the cost issues, we're bringing in new business that doesn't have a lot of capital requirements, which is really important to point out, but might have a little bit lower margin, but definitely brings forth very quick cash. We're very, very happy about that.
Benjamin Haynor
That's helpful. Thanks, Carrie.
Thanks, Barry. I'll jump back in queue.
Carrie Lachance
Thanks, Ben.
Operator
This concludes our question-and-answer session. I would like to turn the conference back over to Carrie LaChance for any closing remarks.
Carrie Lachance
Thank you, Alan. Thank you everyone for joining today's call.
We are encouraged by the progress reflected in our third quarter results. The business is demonstrating strong underlying growth, improving profitability, and increasing cash generation, while our newer therapy categories continue to gain traction and validate the investments we have made in our platform.
We believe our strategy remains sound, our execution remains disciplined, and we are well positioned to continue building long-term value for patients, customers, employees, and shareholders. Thank you again for your time and support.
We look forward to updating everyone on our progress next quarter.
Operator
The conference is now concluded. Thank you for attending today's presentation.
You may now disconnect.