Ingersoll Rand Inc.
Q3 FY2026 · Earnings Call TranscriptOctober 30, 2026
Operator
Hello everyone. Thank you for joining us, and welcome to Ingersoll Rand's Third Quarter 2026 Earnings Call.
After today's prepared remarks, we will host a question-and-answer session. If you would like to ask a question, please press *1 to raise your hand.
To withdraw your question, press *1 again. I will now hand the conference over to Max Vorcheimer, Director of Investor Relations.
Max, please go ahead.
Max Vorcheimer
Thank you for joining Ingersoll Rand's Third Quarter 2026 Earnings Call. I'm Max Vorcheimer, Director of Investor Relations, and joining me this morning are Vicente Reynal, our Chairman and CEO, and Vik Kini, our Chief Financial Officer.
Our earnings release and presentation were issued yesterday afternoon and are available on the Investor Relations section of our website, where a replay of this call will also be posted. Before we begin, please note that today's discussion will include forward-looking statements, subject to the risks and uncertainties described in our SEC filings and on slide two of this presentation, which you should read in conjunction with the information provided on this call.
We will also reference certain non-GAAP financial measures. Reconciliations to the most comparable GAAP financial measures are included in our earnings release and this presentation, both of which are available on the Investor Relations section of our website.
Today, we will review our third quarter results, discuss segment performance, and provide an update to our full year 2026 guidance. During Q&A, please limit yourself to one question and one follow-up to allow time for other participants.
With that, I'll turn the call over to Vicente.
Vicente Reynal
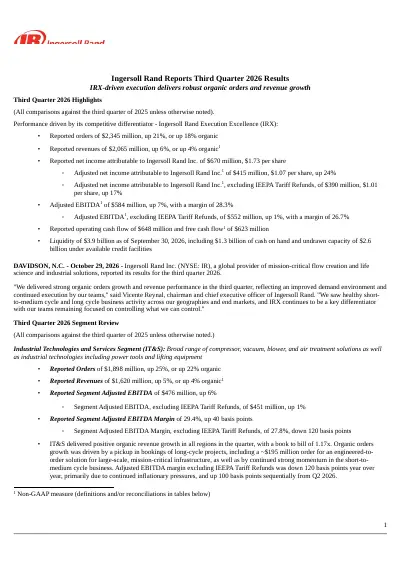
Thanks, Max, and good morning to everyone, and thank you for joining today. Beginning on slide three, we delivered robust financial performance in the third quarter, highlighted by 18% organic orders growth, 4% organic revenue growth, and a 17% year-over-year increase in adjusted EPS, excluding the benefit of IEEPA tariff refunds received during the quarter.
Organic orders growth accelerated across both short-to-medium cycle and long-cycle businesses, including a particularly large engineered-to-order solution win that we'll discuss in more detail shortly. Important to note that excluding this large ETO order, organic orders still grew high-single digits.
As we will discuss this morning, we're raising our full year revenue and adjusted EPS guidance. The board has also authorized a $2 billion increase to our share repurchase program, providing greater flexibility to compound shareholder value.
M&A continues to be our top priority for capital deployment, supported by a robust pipeline of attractive, strategic bolt-on opportunities. We're excited about the momentum we're building, including another acquisition that we successfully closed this morning, which I will look forward to sharing more about in a moment.
Turning to slide four, underpinning our performance is IRX, or Ingersoll Rand Execution Excellence. IRX remains our key enabler of execution, and it is how our teams around the world stay focused on controlling what we can control, supporting our customers, driving productivity, and allocating capital effectively.
A key strategic imperative of the IRX process, as you can see on the slide, is to deploy talent. Earlier this morning, we announced new leadership appointments.
Scott Watson, who was previously leading our Life Sciences business, has been named Senior Vice President and Group President of ITS North America and ITS EMEA. Sean Carlson, who was previously leading our Precision Technology business, has been named Senior Vice President and Group President of the PST segment.
These appointments reflect the growth of our businesses and the depth of our leadership bench. Their leadership in these roles will position us to move faster, execute with greater focus, and better serve our customers.
I also want to recognize Mike Weatherred, who will transition to an advisory role through May 2028 before retiring. A longtime member of our leadership team, Mike helped drive IRX adoption across the company, where it is now very firmly embedded in our culture.
We thank him for his many contributions and wish him well in his next chapter. Turning to slide five, I am pleased to share that this morning we closed on the acquisition of Ivec Corporation, a leading provider of small-volume precision liquid metering and dispensing systems.
The business adds approximately $40 million in annual revenue and will sit within our PST segment, specifically in the Life Sciences business. It expands our expertise in key precision pump technologies and strengthens our solution for Life Sciences customers, and was acquired at a low-double-digit multiple consistent with our disciplined valuation standards.
Year-to-date, we have closed or signed eight transactions, and we have an additional seven transactions at the LOI stage. Our funnel remains healthy, with more than 200 companies, and approximately 90% of our deals continue to be internally sourced.
For 2026, we now expect to be approximately 200 to 300 basis points of annualized inorganic revenue. Our 400 to 500 basis point target is an average over the cycle, and not a single year goal, and it remains unchanged.
This year simply reflects transaction timing, not any change in our strategy or the strength of our funnel. Our disciplined M&A strategy remains a key differentiator and an important driver of long-term value creation.
Now, I will hand it over to Vik, who will review our financial performance.
Vik Kini
Thanks, Vicente. Starting on slide six, the third quarter was a strong quarter of execution.
Orders finished at $2.35 billion, up 21% year-over-year, with organic orders up 18%. Book-to-bill finished at 1.14, well above what we typically see in the third quarter, with the pick up in short-to-medium cycle business coupled with long-cycle project bookings improving meaningfully.
Revenue grew 6% year-over-year to $2.1 billion, with organic revenue growth of 4%. Aftermarket revenue represented 36% of total revenue during the quarter and continues to be an important contributor to the resilience of our portfolio.
Important to note aftermarket grew mid-single digits in Q3. Adjusted EBITDA was $584 million.
This includes $32 million of IEEPA tariff refunds received in the quarter, $25 million in ITS and $7 million in PST. Excluding those refunds, adjusted EBITDA was $552 million, up 1% year-over-year with a margin of 26.7%.
The year-over-year margin decline was driven primarily by the known inflationary pressures and pricing dynamics in China. Importantly, margins improved meaningfully on a sequential basis, up 130 basis points from Q2 excluding tariff refunds, consistent with what we outlined last quarter.
Unallocated corporate costs were $44 million in the quarter, and we continue to expect approximately $170 million for the full year. Notably, our adjusted tax rate for the quarter was approximately 17%.
We have been simplifying our global legal entity structure since the 2020 merger, aligning it with how we operate the business. Through strong planning and execution, we are able to now use foreign tax credits we previously could not, which drove a discrete benefit in Q3.
We expect these changes to provide a durable benefit to our tax rate and cash repatriation efforts going forward. As you'll see in our updated guidance, we now expect a full year adjusted tax rate of approximately 20%.
Adjusted EPS was $1.07 for the quarter, and excluding IEEPA tariff refunds in Q3, adjusted EPS was $1.01, up 17% year-over-year. Turning to slide seven, free cash flow for the quarter was $623 million, which includes $162.5 million of ILC Dover transaction-related recoveries collected in the quarter.
Excluding those recoveries, free cash flow was approximately $461 million, up roughly 40% year-over-year. We ended the quarter with approximately $3.9 billion of total available liquidity, including approximately $1.3 billion of cash and $2.6 billion of available revolving credit facility capacity.
Leverage improved to 1.6x, down from 1.7x last quarter and 1.8x a year ago. During the quarter, we deployed $90 million towards acquisitions and returned $358 million to shareholders through $350 million of share repurchases and our quarterly dividend.
As Vicente noted, the board authorized a $2 billion increase to our share repurchase program, incremental to the $313 million remaining under the existing authorization. This gives us flexibility for additional opportunistic repurchases over the short and medium term, while M&A remains our first priority.
Our balance sheet remains a strategic asset, and this authorization does not change our ability to execute on the acquisition funnel. As an update on the ILC Dover transaction, last quarter we announced an initial recovery of $187.5 million.
Since then, we have reached a series of additional settlement agreements that brings total gross recoveries to approximately $425.1 million. We collected $25 million in Q2 and $162.5 million in Q3, and we expect to collect the remainder of the recoveries in the fourth quarter.
Consistent with our focus on earnings quality, these recoveries are excluded from adjusted earnings. We are very pleased with the final outcome of the recovery process with respect to the ILC Dover transaction, and intend to use the proceeds in line with our capital allocation strategy.
I'll now turn the call back to Vicente to discuss our segment performance.
Vicente Reynal
Thanks, Vik. Turning to slide eight, ITS delivered a strong quarter.
Orders increased 25% year-over-year, including 22% organic growth, resulting in a book-to-bill of 1.17 times. Organic orders were driven by continued momentum in the short-to-medium cycle businesses, as well as a significant pickup in long-cycle activity.
On our last call, we noted the acceleration in long-cycle bookings during the first four weeks of July. That momentum held throughout the quarter, and later in the period, we booked an approximately $195 million order that is an engineered-to-order solution for mission-critical data center infrastructure.
This order covers integrated backup power solutions for mission-critical data center operations, paired with a differentiated filtration system engineered to the customer specifications for maximum uptime, longevity, and reliability. Let me give you some further color on how we have positioned ourselves to enter new growing markets, and data center is just one example.
We're taking technologies proven in demanding industrial applications and bring them to a new end market. Several companies we have acquired in recent years had power generation and thermal management capabilities that historically served industrial customers, and we were able to adapt them very quickly for data centers.
We're getting faster at combining technologies from across our portfolio into differentiated solutions that competitors cannot easily copy. We also win on engineering depth and extensive network of service technicians.
Let me work through the economics of this large order. This order is accretive to EBITDA dollars and adjusted EPS from the start.
As we ramp, we're investing in dedicated capacity, engineering resources, and supplier qualification, initial shipments will carry margins below our company average. That's a deliberate choice.
We're investing now to secure a position in a fast-moving market where speed and reliability decide who wins. IRX gives us a proven playbook to drive productivity, pricing discipline, and aftermarket pull-through as volumes scale, and we expect margins to move towards portfolio levels as the ramp matures and additional orders follow.
Revenue on this order will convert over the coming quarters, most meaningfully in 2027, and we expect future orders in this space to be a bit lumpy. Our entry into data centers show how IRX let us move fast and win in new markets.
A year ago, we had no presence here, and in less than 12 months, we have built a sizable funnel and established partnerships with several customers. That did not happen by chance.
With the massive investment flowing into data centers, we have been deliberate about looking across our portfolio and bringing our unique capabilities together for this end market. Our technology breadth gives us a clear competitive advantage.
We combine power generation, thermal management including chillers and water cooling pumping skids, and other critical flow technologies leveraging our proven legacy portfolio and acquired innovations. Combined with our global engineered-to-order capabilities, that let us deliver complete customized solutions faster than customers can get them elsewhere, which positions us to capture profitable share in this market.
I would like to also highlight that excluding this award, ITS organic orders were up high-single digits, and long-cycle organic orders were up over 20% in the quarter, building solid backlog for 2027. Revenue increased 5% year-over-year, including organic growth of 4%, with all regions contributing positive organic revenue growth for the second consecutive quarter.
ITS adjusted EBITDA, excluding IEEPA tariff refunds, was $451 million, with a 27.8% margin, down 120 basis points year-over-year, driven primarily by known inflationary pressures and the China pricing dynamics noted earlier. Margins rose 100 basis points sequentially from Q2 as price-cost continues to improve.
Over time, we still believe that the ITS business, outside of the data center ramp we just discussed, has the right to play in the 30% to 40% incremental margin range, and we believe the current pressures are transitory. For our Innovation in Action highlight, we're showcasing our new line of oil-free rotary screw compressors, redesigned for world-class energy efficiency performance and reliability, including a new rotor design and an optimized cooling jacket.
Advanced sensor technology transmits real-time operating data to the Ingersoll Rand service network, enabling proactive monitoring and maintenance. That connectivity supports our customers' uptime and also strengthens our aftermarket and recurring revenue opportunity over the life of the installed base.
Turning to slide nine, PST delivered another excellent quarter and continues to demonstrate the strength of the platform we have built. Orders increased 7% year-over-year, including 4% organic growth, with a book-to-bill of 1.01 times.
Revenue increased 7%, including 6% organic growth. Life Sciences technologies continue to deliver solid momentum, with low-double-digit growth in both orders and revenue.
Excluding IEEPA tariff refunds, adjusted EBITDA was $145 million, with a 32.6% margin, up 180 basis points year-over-year and 110 basis points sequentially. Margins expanded in both Precision Technology and Life Sciences technologies, reflecting strong execution and continued IRX benefits.
We're pleased with the PST sustained margin improvement, including five consecutive quarters of incremental margins above 40%. For our Innovation in Action, we're highlighting YZ Systems Zero Emission Odorization, or ZEO platform.
Gas odorization is a critical safety requirement that ensures communities have a safe supply of natural gas. ZEO incorporates a Milton Roy electric pump to dramatically reduce utility companies' carbon footprint across the pipeline network, and an average-size utility can reduce methane emissions by up to 15 million cubic feet per year using this next-generation platform.
It is a great example of commercial synergies across our brands and how our portfolio supports mission-critical infrastructure. Turning to slide 10, given our performance through the first nine months, today we are updating our full year guidance.
Starting with revenue, we now expect revenue growth for the year to be in the range of 5.5% and 7%. The increase in outlook is driven by an increase in organic growth expectations, now expected between 2% to 3.5% for the year.
We continue to expect approximately 2.5% growth from M&A and approximately 1% from FX. Our adjusted EBITDA guidance, excluding Q3 IEEPA tariff refunds, is unchanged at $2.13 billion to $2.19 billion.
Despite ongoing inflationary pressures and challenging pricing environment in China, we're holding our range, and we currently expect to finish at the bottom half of the range. Our corporate cost estimate remains on track at approximately $170 million for the year.
We're raising adjusted EPS, excluding Q3 IEEPA tariff refunds, to $3.58 to $3.70. The increase is driven primarily by a lower adjusted tax rate, now approximately at 20%, and a lower share count of approximately 390.5 million, reflecting our year-to-date repurchases.
Net interest expense is still expected to finish at approximately $230 million. For free cash flow, we now expect to deliver more than 100% conversion of adjusted net income, including the ILC Dover-related recoveries.
Our underlying operational free cash flow conversion remains unchanged at approximately 95%. Our capex forecast remains at approximately 2% of sales.
Finally on slide 11, as we continue this portion of the call, I am encouraged by the momentum we're seeing across the business. Demand continues to improve across both short and long-cycle activity.
Our teams continue to execute at a high level, and our M&A pipeline remains very robust. In a complex global environment, we continue to stay nimble, leveraging our in-region, for-region manufacturing footprint and pivoting quickly toward the most attractive end markets.
Our strong balance sheet, ample liquidity, and expanded repurchase authorization gives us significant flexibility to keep executing on our disciplined capital allocation strategy, which compounds earnings and delivers durable value creation for shareholders. IRX remains the backbone of our organization and continues to enable execution and outperformance across the company.
With a 1.14 times book-to-bill and a growing long-cycle backlog, we believe we're well positioned to finish 2026 strong and carry real momentum into 2027. Finally and most importantly, I want to thank you, our employees around the world, for their continued commitment, dedication, and ownership mindset.
Your efforts continue to drive our success and help us deliver strong results for all the stakeholders. With that, I will turn the call back to the operator and open the line for questions.
Operator
We will now begin the question-and-answer session. Please limit yourself to one question and one follow-up.
If you would like to ask a question, please press *1 to raise your hand. To withdraw your question, press *1 again.
We ask that you pick up your handset when asking a question to allow for optimum sound quality. If you are muted locally, please remember to unmute your device.
Please stand by while we compile the Q&A roster. Your first question comes from the line of Mike Halloran with Baird.
Your line is now open, please go ahead.
Mike Halloran
Hi, thank you. Morning everyone.
Vicente Reynal
Morning, Mike. Hey,
Mike Halloran
maybe we could just start on where you were ending there, Vicente, on the momentum you're seeing across the portfolio. Maybe just dig a little deeper on end markets, geographies, where you're seeing the most success right now, any areas or pockets where you haven't seen that recovery curve materialize, and then obviously the sustainability as we move into next year.
Vicente Reynal
Mike. I would say that we're very encouraged by the global momentum we're seeing across basically all the regions.
If I take for example ITS, let me break that by each of the respective regions. On the order side, Americas was up mid-single digits, EMEA was up low-20s, which included a very nice acceleration on some long-cycle projects, and Asia Pacific ex that large data center, which it is for Asia Pacific, outside of China, was definitely up also low-single digits.
You can see that the momentum we saw really well into kind of all the regions. From an end market perspective, I would say anything related to food, beverage, kind of the more core fundamental end markets that we have always played into, we're seeing better momentum across all of them.
I would say nothing in particularly that I would categorize as negative, except the kind of known things, such as, for example, electric vehicle and also renewable natural gas, that those are kind of end markets that have been kind of down and flattish here for now quite some time, but we're not seeing pickup. In terms of kind of the fundamental, mostly food, beverage, clearly biopharma with the Life Sciences businesses that you saw, power generation, wastewater, some nuclear exposure to us as well, that's where we're seeing good momentum now.
Mike Halloran
That's helpful. Then on the margin side, maybe just talk through kind of the two components.
First, the Chinese pricing, when do you think you start lapping that and signs of change there, at least stability? Then secondarily, on the price-cost side, when do you think your margin and/or EBITDA dollar neutral?
Just some updated thoughts there, please. Thank you.
Vik Kini
Sure, Mike. I'll take that one.
I'll start with your last question on the price-cost side. On the price-cost side, yeah, I think we continue to be encouraged by kind of the momentum we're seeing.
Fair to say here that in Q3, price-cost was slightly dollar positive, but obviously still a margin headwind. That being said, I think as we said in our last quarter call, we've been taking the requisite actions through the course of the year, and we did see, I'd say, some sequential improvement from Q2 now into Q3 and the back half of the year, which I think was a strong catalyst obviously of the sequential margin expansion you saw across the enterprise, and particularly on the ITS side.
I think our view as we continue to move forward is that equation will continue to improve as we move through the balance of the year, but really into 2027. Then on the China side of the equation, similar.
I wouldn't say anything has dramatically changed there. We acknowledge that China still is a headwind from a pricing perspective in a very comparable range to what you saw in Q2, but we would acknowledge here that things are largely stabilizing in that respect from the levels we saw kind of exiting Q2, and we would expect that we will be lapping that really as we get through kind of by the first half of next year.
Mike Halloran
Thank you, guys. Appreciate it.
Vik Kini
Thank you.
Operator
Your next question comes from the line of Nigel Coe with Wolfe Research. Your line is open, please go ahead.
Nigel Coe
Thanks. Good morning everyone.
Vicente Reynal
Morning. Morning, Nigel.
Nigel Coe
Good morning. Congratulations on the large data center order.
Just want to make sure that you're competing here against the likes of Carrier, Trane, the traditional chiller manufacturers. Just want to make sure that's the case.
Then, obviously ex this one order, high-single-digit 9% order growth. If we took out larger compressor orders, how would you characterize the growth in the small, medium-sized compressors?
Then, Vik, just maybe just clarify on this $195 order, that'll be kind of accounted for sort of over time, sort of percentage of completion accounting on that order? Thanks.
Vicente Reynal
Yeah. Nigel, on the first question around some of the data center capabilities, I'll talk more about kind of what's more unique and differentiated on what we're doing.
I think we're playing here across both power and thermal management with technologies that can be more holistically put together. As you have known, we do very good sizable of our businesses engineered-to-order solutions, and that's the area where we believe we have a competitive advantage: the ability to be able to create a combined engineered-to-order mission-critical where there's high density, low footprint, modularity, and be able to kind of ship it to the location so you can do plug-and-play.
That is a unique capability that we have been utilizing in other end markets, and now that we're kind of leveraging the power of the technologies that we have and creating some unique solutions. I think that's more on kind of where I will say we have a competitive advantage.
On the second question around the high-single digit, last quarter, as you remember, we reported low-to-mid-single-digit order growth in short-to-medium cycle, and this quarter we were squarely in the mid-single-digit range. That tells you that we continue to see that sequential acceleration and some very good kind of momentum here.
I would say this was due to a continued broad-based industrial improvement as we just kind of said, and as well as that strong execution by our teams in the equipment, that it was basically up low-double digit, outpacing aftermarket, although aftermarket was still also high or positive in the kind of mid-single digit. Again, even excluding anything else, we still see both short-to-medium cycle, as well as the long-cycle momentum here.
Vik Kini
Then Nigel, on your question regarding the revenue cadence and the accounting treatment, yes, to answer your question, the $195 million order will be POC, with the majority expected to be kind of consumed or digested through the course of 2027.
Nigel Coe
Great. I know I have three questions as it were.
If I could just have a quick follow-on. Really nice sequential momentum in ITS margins in 3Q.
Just based on your commentary around the EBITDA for the full year, what should we expect for ITS margins in 4Q? Thank you.
Vik Kini
Nigel, I'll take that one. I think the simplest way to think about Q4 is we expect to see essentially a similar level of sequential improvement from Q3 to Q4 as you saw from Q2 to Q3, approximately 100 basis points.
I would, I would point to a lot of the same drivers that we've called out before. I'd say, slightly improving price-cost equation, the, the Q4 volume, that that sequentially continues into Q4.
Obviously Q4 is our typically our strongest volume from a quarter from a seasonality perspective. Then obviously the productivity equation, which generally follows that, which whether it be, the classical procurement side or some of the, I2V-type initiatives.
Very similar I'd say drivers, but comparable margin expansion sequentially in Q4.
Nigel Coe
Great. Thanks, Vik.
Vicente Reynal
Thank you.
Operator
Your next question comes from the line of Steve Volkmann with Jefferies. Your line is now open, please go ahead.
Steve Volkmann
Good morning, guys. Thank you for taking the question.
Back to the big $195 million order, how should we think about that sort of more medium term? Is there a funnel of additional orders that could be similar?
Would you be surprised if we didn't have more of these to talk about a year from now?
Vicente Reynal
Steve, I would say that the funnel is fairly substantial and robust. About a year ago we were not playing in this end market.
We obviously structured ourselves, hand-selected a few team members, and over the past 12 months, we've been able to talk to a lot of hyperscalers, collocators, and understanding voice of customer in terms of what's needed and what's missing, and that's where we're playing right now, basically fulfilling those critical needs that are today in some ways unmet. Funnel is growing and continues to accelerate.
Steve Volkmann
Okay. Then my follow-on I guess, Vicente, is how do you sort of manage this from a top-down perspective?
What I mean is that there's a lot of angst around sort of the rate and cadence of data center spending and lots of views around what that's going to look like. You're allocating some capital, building out some supply chain, etc.
Is this a risk if things don't come out the way you think they should, or can you somehow sort of flex this variable?
Vicente Reynal
Great question, Steve. I think the beauty of this one here is that we're taking products that we have in our portfolio that are actually widely used in the industrial landscape based on current solutions that we have.
I think if later down the road some of this data center volume kind of goes down, we still have the products that we're selling to industrial space. In terms of incremental capex and opex, just think about it from a capex perspective, we're still going to be well within our 2% of sales on that capex.
I think we're a low capex intensity, and we're being very thoughtful in the places that we play. We're not going super broad-based.
We're going very focused on some specific customers. We've done a lot of customer segmentation, and we're selecting either one, call it a few hand-selected hyperscalers as well as collocators, and that's basically we're very focused on deep customer relationship.
Steve Volkmann
Okay. I appreciate it.
I'll pass it on.
Operator
Your next question comes from the line of Rob Wertheimer with Melius Research. Your line is open, please go ahead.
Rob Wertheimer
Thank you. Good morning.
A quick clarification on the data center order: is that a framework kind of agreement or is that specific to one site where you might see other sites of similar scope?
Vicente Reynal
This is one site.
Rob Wertheimer
Wow. Perfect.
Then, Vicente, this is a little bit of a bigger-picture one, but you think about AI's impact across biopharma, and there's already some kind of glimmerings of new drug discovery, new applications, all sorts of things that are changing faster than we're used to. If you look ahead a few years, do you see this as a thing that changes your opportunity in the space?
Do you see any momentum there? Maybe just talk about how that world is changing.
Thank you.
Vicente Reynal
Great, great question, Rob. As you have seen, we have been investing actually in lab automation.
We made an acquisition with Scinomix, but also inside our business, we have another company called Zinsser Analytic. Those are companies that basically do robotic automation for drug discovery.
We are a participant of developing this machinery, and actually providing this robotic automation to customers that are leveraging AI to actually create recipes for personalization of medicine, particularly in the immunotherapies. We think that as more customers continue to use AI, and they continue to do this personalization, whether therapies or other things that require some mixing of different compounds, and that is going to be actually a very good play for us moving forward.
Rob Wertheimer
Thank you.
Operator
Your next question comes from the line of Nathan Jones with Stifel. Your line is open, please go ahead.
Nathan Jones
Good morning everyone.
Vik Kini
Morning. Hey, Nathan.
Nathan Jones
I guess I'll ask one on the PST side. You mentioned five consecutive quarters with incrementals above 40%.
Is that kind of the way we should be thinking about, I don't know, the next five quarters, and longer term how we should think about the path to the targeted 35% margin level?
Vik Kini
Nathan, I'll take that one. Listen, we've always talked about the PST business being one that obviously, it's a higher margin profile business, and you clearly are now seeing, I think, the benefits of, I'd say solid pricing momentum, but obviously the volume, particularly led by areas like biopharma, like Vicente just mentioned.
I think now obviously with a well-integrated segment between the two platforms we have with Precision Technologies and Life Sciences, yes, we think that this is one that with I'd say the kind of normal growth algorithm, executing towards that 40% type incrementals is kind of where this business wants to operate. To your point here, we've now solidly been above, well, about 30% EBITDA margins here for several quarters, executing that now about 32% range here in Q3, with expectations to be in a similar range here in Q4.
I think our exit momentum is quite solid, and clearly the mid-30s kind of EBITDA target range that we'd put out is, I'd say, well within sight.
Nathan Jones
Okay. I'm going to ask about the same question that I ask Vicente on every call about quote-to-order times.
Obviously you've seen an improvement in momentum here in orders, you're talking about strengthening in end markets. Are you seeing that quote-to-order times start to shrink or are customers still fairly hesitant on pulling the trigger?
Vicente Reynal
I'd say we're definitely seeing better momentum and acceleration through the process. I don't say it's back to normal levels, but clearly we're encouraged by the decision-making improvement.
The quote-to-order cycle, I'd say they have not shortened meaningfully. I would say projects getting to the finished line, yes, definitely we're not seeing cancellations.
I think the most important leading indicator here that we're tracking really extensive across the entire company is the number and obviously dollar amount of RFQs, request for quotes and request for pricing. These are customers trying to get a preliminary pricing on specific projects, and that we're definitely seeing rapid acceleration.
Nathan Jones
Great. Thanks for taking the questions.
Vicente Reynal
Thank you.
Operator
Your next question comes from the line of Joe O'Dea with Vertical Research. Your line is now open, please go ahead.
Joe O'Dea
Hi, good morning.
Vicente Reynal
I'll
Joe O'Dea
start on the data center topic, but could you just go through a little bit the process that you went through for adapting the technologies you have for data centers and expand on what you do internally, what technologies you use from partners? Did you need to establish some new partnerships in doing this?
Then just regionally, do you have some advantages in Asia, or what about the U.S. as an opportunity for you just given the size of the market there?
Vicente Reynal
We're taking technologies from companies that over the past few years we have acquired around thermal management and also combining our ability of developing very quick engineered-to-order skids solutions. It could be skids for filtration, it could be skids for moving liquids and fluids, and that's core of what we have done for many, many, many years.
I think that what's very unique here is how we took the approach of basically I personally spent a lot of time with a hand-selected group of teams on a global basis to go out and really understand what were the meaningful gaps that were not being offered to some of these customers, and then now we're going back into the regional execution as we always do. In this case, started with Asia Pacific, because in Asia Pacific we had a bit more experience around that kind of power management and some thermal management solutions.
That's really why it started in Asia Pacific. Clearly the U.S., we're seeing now, as we always do, we typically start in one region and then we start kind of piloting that, and then we move into the other region, similar to what we have done in the historical with like Care solutions or recurring revenue, right?
In this case, for data centers, we started in Asia Pacific, and now we're moving globally. About six, nine months ago, then we kind of came to the U.S.
and with a very similar approach and solutions, and now we're seeing good momentum there. The last area of focus for us to as well has now started to be is India, where we were there a few weeks ago, and we're seeing some rapid acceleration in, again, taking the same solutions that we develop in Asia Pacific and moving them to the other specific regions to offer something similar to the needs that are out there.
In terms of partnerships, no, this is not too dissimilar to what we do in our engineered-to-order solutions. We always have a very good solid supply chain, and we're leveraging that supply chain to really create what we're creating here.
Specific kind of signed partnerships and things of that nature, nothing that I would call out, yeah.
Joe O'Dea
Got it, that's great. Then just in a near-term one, when we think about growth into the end of the year, the full year range gives pretty wide range of outcomes for fourth quarter organic.
Is it a base case where the comp does get a little bit tougher, but there's some demand acceleration? Can you do a pretty similar level of organic growth in Q4 as you did in Q3, pretty similar between the segments?
Just any color you're willing to provide there.
Vik Kini
Joe, I'll take that one. I think you're spot on here in the context of, obviously Q4 has a little bit more of a meaningful comp on a year-over-year basis.
I think the way to think about Q4 is, right now expectation is, in the two, 2%-plus kind of range for the total company on an organic basis, and actually both segments looking fairly comparable. That's kind of the expectation at this point in time, but I think as you've seen us before here, there's opportunity to obviously outperform that.
Clearly we'll continue to execute, but I think that's probably the right way to think about Q4 based on the guide at this point in time.
Joe O'Dea
Thank you.
Operator
Your next question comes from the line of Joe Ritchie with Goldman Sachs. Your line is now open, please go ahead.
Joe Ritchie
Thank you. Good morning, guys.
Vicente Reynal
Morning. Morning, Joe.
Joe Ritchie
I'm curious on the margin profile of this order, the data center order. It sounds like you're using solutions that you've used previously, sold these types of products before.
Is the fact that it is kind of dilutive to the portfolio margins a function of investments that you're making? Is this type of solution typically dilutive?
If there's any way to kind of level set the margin profile of this particular award, that would be great.
Vicente Reynal
Sure, Joe. Think about it similar to sometimes when we do an M&A, that typically as we bring in M&A, it kind of comes in in the kind of 20s, and then obviously we ramp it up to fleet average over the course of the medium term.
I think is very similar here. Obviously this is all organic, but the investments in some of the opex that is needed to kind of do this ramp, it comes in at that kind of level, call it start to be in that low-20s, and then obviously fairly quickly as we start seeing more incremental volume as well as the continued execution of the output, this business can get to that fleet average that we have.
Joe Ritchie
Got it. That's helpful context, Vicente.
Then sounds like the demand environment even outside of this award has been pretty healthy. I'm curious if you're willing to comment on October trends and how things have started so far this quarter.
Vicente Reynal
Joe, no commenting on October. I think last quarter we were commenting on July just because it was a unique moment in time.
I would say things continue to be healthy. We're seeing healthy demand, broad-based, on a global basis, and we're just encouraged with how the teams continue to execute and are seeing some of the wins.
Joe Ritchie
Great. Thank you, guys.
Vicente Reynal
Thank you.
Operator
Your next question comes from the line of Andy Kaplowitz with Citi. Your line is now open, please go ahead.
Andy Kaplowitz
Hey, good morning everyone.
Vicente Reynal
Morning, Andy.
Andy Kaplowitz
Vicente, I know you said transaction timing around M&A has been a bit more difficult this year, but with the financial metrics you want to get, can you get what you need here? Then it seems like you're laddering into repurchases a bit more.
In terms of your priorities around capital deployment, are you adapting a bit to sort of the current environment?
Vicente Reynal
Hi, Andy. I think M&A continues to be that priority.
I think we're a very disciplined buyer, we remain disciplined, but in terms of the funnel, funnel continues to be over 200 companies and very active. I think it's nothing that we're worried about M&A flywheel at all.
I think in some respects, we're very, very encouraged with what we're seeing here on the M&A front, and it's just basically a matter of here timing, not nothing to worry about.
Andy Kaplowitz
Great. Then can you give a little more color into what you're seeing in PST in the near term?
I think your order comps were more difficult in Q3 than Q2, but growth seemed to stay strong, at least on the Life Sciences side of the business. Maybe just comment on the durability of the order and revenue strength you're seeing in PST.
Vik Kini
Andy, I'll take that one. I think we continue to be really encouraged by what we're seeing in PST.
I think as we mentioned here, Life Sciences orders were up low-double digit on an organic basis, which I think continues to speak to the strength in just kind of the Life Sciences kind of platform and kind of the trends that Vicente mentioned earlier. On the Precision Technology side, obviously, when you look at the total and you see low-double digits for our Life Sciences, there was a slight headwind on the overall Precision Technology orders, which was really driven, I would say, by just the timing of some of our longer-cycle pump projects, which was down roughly mid-single digits.
When you actually look at the, what we'll call more short-to-medium cycle kind of core pump business within Precision Technologies, that grew low-single digits on an organic basis. Again, I think it speaks to, I'd say the durability of what we're seeing.
To your point here, I think the strength in the order profile that we've seen over the last few quarters is translating nice to revenue, and you see obviously the margins going with it. Again, we'll spare any commentary on 2027 guidance at this point in time, but I think we continue to feel encouraged by the momentum we're seeing and kind of the exit we're seeing here to the balance of the year.
Andy Kaplowitz
Appreciate the color, guys.
Vicente Reynal
Thank you.
Operator
Your next question comes from the line of Nicole DeBlase with Deutsche Bank. Your line is now open, please go ahead.
Nicole DeBlase
Thank you. Good morning, guys.
Vicente Reynal
Morning.
Vik Kini
Hi, Nicole.
Nicole DeBlase
Just after Vik you said that you're not going to talk about 2027, I'm going to try to ask a question about 2027. I guess, thinking about some of the puts and takes on ITS margins, right?
Obviously kind of impacted by price-cost this year. Inflation has continued, but it sounds like from the opening remarks you guys are feeling better about the price-cost roll-forward into next year, but we've also got this dilutive large order that's going to ship in 2027.
What I'm trying to think through is the likelihood that you guys can kind of get back to expanding ITS margins 50 bps a year next year, or is that maybe too optimistic with some of these headwinds?
Vik Kini
Yeah. Nicole, we'll obviously give a lot more color here in a few months when we give guidance and whatnot.
I'd say just to give a little bit of color commentary here, let's talk obviously about kind of, I'll say the core ITS, and I'll park the data center order here for a moment. I think our view moving into next year is that we would expect kind of pricing, again, similar to what we talked about entering this year, to be kind of in that normal 1% to 2% range.
I think we will get some carryover obviously from the actions that we've taken through the course of 2026, not too dissimilar from what we've spoken about before. I think the good news here is I don't think we're necessarily comping the tariff-driven pricing and things of that nature.
Obviously we'll continue to calibrate based on how any inflationary headwinds and things like that, you've seen us be able to be very proactive on that sense. Then obviously we're going to continue to drive the productivity equation, and I think we're encouraged by at least how volumes have continued to trend here over the back half.
I think back to kind of Vicente's prepared comments here, we do think that the core business kind of operating in that 30% to 40% incrementals range, probably ITS maybe more towards the lower end of that range, but we think that that's probably a prudent way to think about how we think expectations are, at least framing up. As such, we'll obviously give a little bit more of a finer point on the overall margin equation, but I think we feel good about how ITS is trending, and now you see that obviously in the margin profile sequentially improving here as we move through the back half of this year.
Nicole DeBlase
Perfect. That's actually really helpful.
Thanks, Vik. Then just with respect to another orders question, the short and medium-cycle orders, that mid-single-digit figure that you guys gave for 2Q, was that pretty stable across the quarter, and did we kind of exit there in September?
Vik Kini
Nicole, I would say it was fairly stable through the course of the quarter. Nothing I would point to in terms of any variability or anything like that during the course of the quarter, very, very comparable and relatively stable.
Nicole DeBlase
Thank you. I'll pass it on.
Vik Kini
Thank you.
Operator
Your next question comes from the line of Amit Mehrotra with UBS. Your line is now open, please go ahead.
Amit Mehrotra
Thanks. Good morning.
I just, maybe had a question on growth and what you're seeing sort of as a leading indicator. I know, Vicente, you have some visibility into sort of the utilization of the assets in the field, not complete visibility, but some visibility.
I know that was sort of inching up above 70%. Can you just maybe update us on that?
Then ultimately we're all trying to figure out if this order inflection, if I can even call it that, ex the data centers, is actually ultimately going to translate to accelerating growth. Any color you can say about where we are today obviously low to mid-ish single-digit growth, is what you're seeing on the utilization and the order front giving your confidence that we're going to be accelerating growth next year?
Vicente Reynal
I think based on everything that we're seeing here, Amit, at this point in time, whether it is the utilization of compressors and machines that are connected, yes, we do think that that momentum continues. You see it on the PMIs as well.
We always said that typically ITS will turn and accelerate couple quarters after PMI has demonstrated to be above 50 for a few months, and obviously you saw that in January in the Q1, and basically now it's couple quarters later that we're seeing some of that acceleration. We always said that it just takes that tailwind to see for us.
I think at this point in time, despite some of the kind of geopolitical macro environment going on, we're seeing that good momentum, and hopefully things will continue to get better and improve moving from here. We're seeing things on that acceleration and positive momentum.
Amit Mehrotra
Then just, Vik, on the margin, it was nice to see the step up sequentially in margins as you guys expected. There's a pretty big sort of implied step up obviously in the fourth quarter.
You talked about the 100 basis points sequentially, but if I just look at I guess the sequential change in profit versus the sequential change in revenue implied by the guidance, it's sort of like 65%, which is a big number. Could you just help us think about maybe some of the puts and takes there that give you that type of drop through sequentially at least?
Vik Kini
Sure, Amit. I'll take that one.
I think a couple things to think about here. One, as we indicated here, we've been taking certain pricing actions through the course of the year, fairly standard for us.
I think the concept of continuing to see sequential slight improvements on the price-cost equation, I think is kind of what's embedded. The other piece here that I think also is piece of the equation here is, remember, a lot of our, I'd say direct material-driven savings, whether it be classical procurement savings, I2V, they tend to follow kind of your cost of goods sold profile, which typically tends to be much better second-half weighted and typically a lot more into the Q4 timeframe.
I think between those factors, as well as just some of the kind of, I'd say normal course things we've been doing, whether it be some of the prior restructuring actions, things of that nature, that's kind of all what's kind of built into, I'd say the build from Q3 to Q4. The other way I'd kind of think about this here is the level of sequential margin expansion from Q3 to Q4 not too dissimilar from what you saw from Q2 to Q3.
Obviously we're going to continue to execute here, but obviously that's kind of what's built in, and not too dissimilar I think from sequential improvements you've seen in years past as well as in terms of the Q4 being the high-water mark on margins.
Amit Mehrotra
Great. Thank you, guys.
Appreciate it.
Vik Kini
Thank you.
Operator
Your next question comes from the line of David Raso with Evercore ISI. Your line is open, please go ahead.
David Raso
Hi, thank you for the time. A little minutiae here, but I wanted to dig into the China business in ITS, how it's dragging on the margins.
Can you help us a bit? Obviously we have the revenue size, we don't have the Q yet, but it's roughly 11%, 12% of the segment.
What's the relationship with the China margins to the segment average for ITS right now?
Vik Kini
David, I'll take that one. Broad strokes, whether it's the China business or frankly total Asia Pacific, but obviously China is the biggest piece of it, it plays in a range that's very comparable, I would say, to the fleet average.
Now, fair to say obviously, it's been healthier than that historically. Clearly we've seen headwinds for some of the aforementioned pricing dynamics.
I think right now, it's still in the general range of I'd say the total ITS segment, nothing dramatically different. We don't actually see a tremendous amount of mix between our regions, but you clearly have seen headwinds there.
I'd say the other piece that's become, I'd say a little bit more relevant over the last few quarters is, obviously off of a different baseline than where we were a few years ago, you are seeing good growth. We've talked about that low-double-digit-type volume-type increases in the China-type realm, but it is fair to say that that's obviously been much more original equipment driven than aftermarket at this point in time.
Again, we view that as a positive from a more medium-term perspective as, obviously more installed base that we will then ultimately be able to serve through the aftermarket. I think your point about it being a headwind has clearly been valid over the last number of quarters.
David Raso
Is the margin improvement sequentially for the whole group consistent with what we saw in China in the quarter, or the China margin still flat to down sequentially? I'm just trying to get a sense, because you said that the segment has a right to play in the
Vik Kini
30%
David Raso
to 40% incrementals, and I'm just trying to get a sense of China's impact on that for '27.
Vik Kini
Sure. I would say from a sequential perspective, I'd say China is obviously seeing I'd say sequential improvement, very similar to other regions, but on a year-over-year basis obviously continues to still be a bit of a headwind.
David Raso
Thank you very much. Appreciate it.
Vicente Reynal
Thank you.
Operator
Your last question comes from the line of Brandon Nispel with Morgan Stanley. Your line is open, please go ahead.
Brandon Knutson
Good morning everyone, and thank you for taking my question. On the $195 million order, it sounds like you want to start at that at lower margins and then scale up the volumes there and get that to segment-level margins, as you take this solution to other regions, do you also foresee if it's a bigger initial order that those would come through at a margin dilutive level initially before ramping up to segment level?
Vik Kini
Brandon, I'd say, again, as we continue to execute, probably fair to say that they'll probably start a little bit better, but I would say we would expect to see a continued improvement over the medium term as we continue to kind of ramp up in this area. I think the simplest way to say it is maybe a little bit better than probably what you've seen on this initial order, but, again, take that as nothing but a starting point.
As Vicente said, as we continue to ramp and almost see this kind of almost like acquired M&A and things like that as it continues to mature in the medium term, we would expect to get kind of this overall platform closer to fleet average as you've seen us do for other parts of the business as well.
Brandon Knutson
Great. Then to ask a question on M&A slightly differently.
You've highlighted this year is going to be roughly 200 basis points below the through-cycle M&A target that you're looking to hit. What have been the factors that have been impacting deal timing this year, and do you see those factors in the environment around M&A getting better as we start looking towards '27?
Vicente Reynal
Brandon, I would say couple factors have been mostly just, one, at the beginning of the year, kind of with what was happening in the Middle East. I think keep in mind we're doing sole source, family-owned, entrepreneur companies.
Some of these companies kind of put a bit of a pause and kind of moved to the sidelines. Again, deeper due diligence that we continue to do, obviously in some cases being prudent due to the pricing dynamics of some of the transactions that we were seeing.
Nothing I'll say too dissimilar that is kind of really concerning to us. I think the only kind of aspect here that I will say maybe moving forward is maybe whether it is better Middle East or better other things that geopolitical stability, I think that might be the only thing that could change.
Again, with over 200 companies in the funnel and we have a pretty active funnel here. Like I said, nothing really to pinpoint exactly to one issue or another and why the transition in terms of the delays, but we're not worried about continue to doing that 400 to 500 basis points through the cycle.
Vik Kini
Brandon, the only other thing I'd add is even this morning here the announcement of Ivec, I think speaks to that, obviously one that's been in the funnel, one that got to the finish line here. I think it speaks to obviously the activity, and we would expect to see transactions like that continue to unfold here over the near term, if you will.
Operator
There are no further questions at this time. I will now turn the call back to Vicente Reynal for closing remarks.
Vicente Reynal
Thank you, and I'll say thank you all for your time and continued interest in Ingersoll Rand. One more special thank you to our employees around the world whose ownership mindset and commitment to executing through IRX helps compound durable, long-term value for all of our shareholders, which, again, of course includes our employees who are shareholders of the company.
Thanks again, and have a great day.
Operator
This concludes today's call. Thank you for attending.
You may now disconnect.