ITT Inc.
Q3 FY2026 · Earnings Call TranscriptNovember 5, 2026
Operator
Welcome to ITT's 2026 third-quarter conference call. Today is Thursday, November 5th, 2026.
Today's call is being recorded and will be available for replay beginning at 12:00 p.m. Eastern Time.
At this time, all participants have been placed in a listen-only mode, and the floor will be open for your questions following the presentation. If you wish to ask a question at that time, please press star one one on your touch-tone phone.
If at any point your question has been answered, you may remove yourself from the queue by pressing star one one. We ask that you please pick up your handset to allow optimal sound quality.
It is now my pleasure to turn the floor over to Carleen Salvage, Vice President, Investor Relations and FP&A. You may begin.
Carleen Salvage
Thank you, Liz, and good morning. Joining me in Stamford today are Luca Savi, ITT's Chief Executive Officer and President, and Mike Savinelli, Interim Chief Financial Officer.
Today's call will cover ITT's financial results for the three-month period ended October 3rd, 2026, which we [announced?] announced yesterday evening.
Please refer to slide two of the presentation available on our website, where we note that today's comments will include forward-looking statements that are based on our current expectations. Actual results may differ materially due to several risks and uncertainties, including those described in our 2025 annual report on Form 10-K and other recent SEC filings.
Except where otherwise noted, the third-quarter results we present this morning will be compared to the third quarter of 2025 and include certain non-GAAP financial measures. The reconciliations of such measures to the most comparable GAAP figures are detailed in our press release and in the appendix of our presentation, both of which are available on our website.
Today's earnings call includes year-over-year commentary on the performance of SPX FLOW that reflects financial information before the acquisition date of March 2nd, 2026. With that, it is now my pleasure to turn the call over to Luca, who will begin on slide three.
Luca Savi
Thank you, Carleen, and good morning. Let me begin by thanking our employees around the world who have delivered another outstanding quarter.
Our results are a direct reflection of the hard work we do at ITT each and every day for our customers and our shareholders. I couldn't be more proud, and I can assure you there is more to come.
I would also like to extend a special thank-you to our colleagues at Habonim in Israel and Goulds Pumps in Saudi, who continue to excel in extremely challenging environments. Ilan, Kalim, and their teams have demonstrated remarkable resilience whilst continuing to deliver quarter after quarter.
Their unwavering commitment to serve our customers is second to none. This is the very best of ITT.
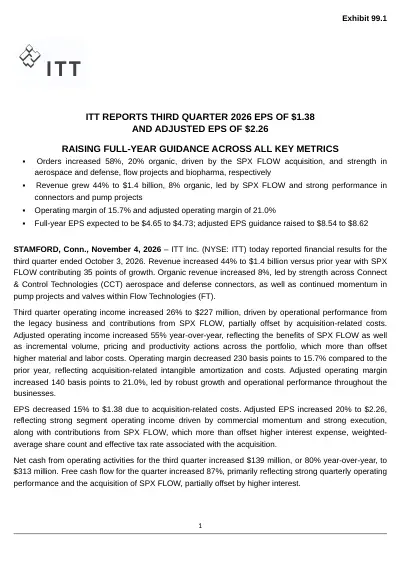
Now let's turn the highlights to our third quarter. We grew orders 58% or 20% organically.
We grew revenue 44% or 8% organically, reflecting a book-to-bill of 1.08 for the quarter. We expanded operating margin 140 basis points, reaching 21% for the very first time.
We delivered EPS of $2.26, up 20% year-over-year. Finally, we generated $464 million of free cash flow year-to-date, up 26% from the prior year.
A truly outstanding quarter. Let's delve now into the details on orders.
Orders are, once again, the highlight of the quarter with continued aerospace recovery, defense content expansion, healthy project activity, and ongoing market share gains across the portfolio. CCT continued its strong momentum from Q2, growing organic orders 55%, driven by aerospace tailwinds and defense share gains.
In defense, Casaria keeps on winning market share and achieved 146% growth in orders, driven by awards in submarine, tactical radio platforms, and the F-35. With a very healthy backlog for the short- and medium-term and our growing participation across key defense programs that provide multi-year visibility, Casaria will be a significant platform for growth in the years to come.
Connectors also grew 37% in the quarter, driven by broad-based strength across all regions, all channels, and all end markets. In Motion Technologies, we continued to strengthen our position through a combination of platform re-wins and conquer awards that will fuel future market share gains in friction.
In KONI, orders were strong again this quarter, growing 24%, driven by strength in rail and European defense, including a significant order for Patria. Finally, Flow Technologies delivered 108% orders growth, with organic orders up 11%, driven by key project wins in oil and gas, including Venezuela, and in marine energy transition, alongside continued strength in biopharma for our valves business.
In SPX FLOW, mixers delivered 6% growth from large project orders in North America and China, whilst Waukesha Cherry-Burrell grew 10%, driven by strong original equipment run rate to North America distribution. On revenue, organic growth across all segments contributed to another quarter of strong performance, underscoring once again the power of ITT's differentiation.
In CCT, organic revenue grew 19%. Commercial aerospace continued to benefit from increasing production rates and pricing actions, whilst defense growth was bolstered by European defense wins coupled with Casaria's expanding presence on marquee programs.
Connectors also grew its industrial segment 31% globally, mainly through distribution. MT once again outperformed global vehicle production across all regions, resulting in a year-to-date outperformance of 560 basis points.
Flow Technologies grew revenue [cough] 99% or 6% organically, led by sustained momentum in pump projects and strength in our short-cycle valves businesses. Valves revenue increased 20%, and we still generated a healthy 1.2 book-to-bill.
Finally, SPX FLOW revenue grew 6% in Q3 and 8% year-to-date, keeping the business on track to deliver high-single-digit growth for the full year, supported by strength in nutrition and health, Waukesha Cherry-Burrell, and mixers. On operating margin, CCT margins expanded 100 basis points year-over-year to a record 22%, as volume and pricing actions more than offset inflationary pressures.
We continue to invest in resources, in automation, and capacity to deliver today's backlog and capture tomorrow's share gains. Casaria also contributed to CCT's performance, expanding margin to over 19%, benefiting from pricing and operating leverage.
Done, Mike and team, for Casaria's margin expansion, as well as revenue growth and orders. Motion Technologies expanded margin 70 basis points to 21%, as net productivity more than offset customer pricing pressures in friction.
Flow Technologies delivered margin of 22.4%, improving 100 basis points sequentially, as integration synergies accelerate. All of these contributed to EPS growth of 20% to $2.26.
Now to cash and capital deployment. In Q3, we generated $288 million of free cash flow, bringing our year-to-date total to $464 million.
With this strong cash performance, we paid down over $200 million of debt and reduced our leverage ratio to 2.3 times. We now expect the year-end ratio to be approximately 2.1.
We also continue to repurchase shares, $50 million in Q3 and over $150 million year-to-date. In the quarter, we also acquired Aerospace Contacts, strengthening our supply chain and improving our ability to support future growth in CCT.
On the topic of M&A, it has been 8 months since we completed our largest acquisition, SPX FLOW. Let me now share our progress on the two biggest drivers of value creation: growth and cost synergies.
On the growth front, year-to-date revenue growth of 8% was driven by strength in nutrition and health, which has grown 16% year-to-date as a result of a healthy backlog. This performance, coupled with strength in Waukesha Cherry-Burrell and mixers, more than offset the challenges in the former industrial pumps segment.
Given this performance and the backlog for Q4, we are confident SPX FLOW will achieve high-single-digit growth in 2026. Also, orders momentum continues to be strong, resulting in a book-to-bill of 1.04 times year-to-date and the backlog growing 7% versus the prior year.
As we look ahead, our focus is on unlocking SPX FLOW's growth potential by deploying the ITT playbook of driving market share gains and relentless execution both operationally and commercially. In nutrition and health, we are simplifying the organization to increase accountability, eliminate bureaucracy, and accelerate decision-making, whilst driving more innovation and leveraging an already strong customer intimacy.
I was able to experience this intimacy firsthand when I met with Danone's leadership team in Paris. This partnership is exceptional.
Our teams are working side by side to develop capital plans and design specialized equipment to improve productivity, increase throughput, and reduce energy consumption to help Danone win. This level of partnership is a powerful competitive advantage that helps us secure long-term growth opportunities.
In mixers, we are utilizing our technical leadership to expand aftermarket penetration, and we are driving productivity and VAVE initiatives to improve cost competitiveness. For the future, we have also now laid the groundwork to deliver on the revenue synergies through localization in Latin America and the Middle East, leveraging the Goulds footprint and network.
At Waukesha Cherry-Burrell, we are expanding our TAM by growing our presence in China and India, and by entering the attractive industrial process market. We're already leveraging our installed base and customer relationships to drive share gains in North America for our Bornemann hygienic twin screw pump platform.
In industrial pumps, the picture is mixed. Bran+Luebbe pumps, on one hand, need to get closer to our customers in Asia and the Middle East by localizing assembly as well as engineering, whilst resizing our European operations.
On the other hand, our Johnson Pump, engineered and manufactured in India, has successfully conquered the Indian market. We can leverage this competitive product to expand sales globally.
I was fortunate to spend time with Sarjit and his team in our plant in India. It's a good plant, a good team, and we will invest and grow this business.
On cost synergies, we are ahead. The team has built a robust pipeline of synergies well surpassing our original $80 million target.
For 2026, we targeted $15 million of savings, and since closing, in just 8 months, we are projecting savings of over $20 million by year-end. This translates to an annual run rate greater than $30 million.
Corporate and business unit G&A synergies are executed, and supply chain and procurement actions are well under way and will deliver savings in year two. Whilst it is still early innings, we are performing well ahead of plan.
Thank you, Lori, Bartek, the entire team, and the EYP team for your hard work and for delivering these amazing results. With that, let me turn the call over to Mike to discuss Q3 results in more detail.
Mike Savinelli
Thank you, Luca, and good morning. As Luca highlighted, Q3 marked another quarter of strong execution.
We once again delivered growth across key financial metrics, including revenue, adjusted operating margin, earnings per share, and free cash flow. Our teams delivered over $1.4 billion in revenue, growing 44% and 8% organically.
SPX FLOW contributed 35 points of total revenue growth in the quarter. CCT grew 19% organically, fueled by strength in industrial connectors and aerospace and defense.
As Luca highlighted, Casaria continues to be a key contributor to the segment's growth. Motion Technologies grew 2% organically, driven by continued friction outperformance and aftermarket strength.
Finally, Flow Technologies grew 6% organically, reflecting continued strength in projects and valves. Strong execution across ITT, combined with SPX FLOW, drove 55% adjusted operating income growth and 140 basis points of margin expansion.
CCT grew operating income 27% and expanded margin 100 basis points to 22%, as the team converted higher volume into strong earnings growth with disciplined pricing and productivity initiatives that more than offset inflation. Flow Technologies delivered a 22.4% margin in the quarter, up 100 basis points sequentially, driven by cost synergies.
MT expanded 70 basis points to 21%, overcoming commercial pricing pressures by driving net productivity of 140 basis points. Although inflation remains present across the macro environment, we continue to effectively manage price costs and invest in initiatives that support margin expansion and long-term value creation.
Year-to-date free cash flow totaled $464 million, reflecting a margin of 11%. Excluding acquisition-related expenses highlighted in Q1, free cash flow increased 46%.
Lastly, strong revenue growth and robust margin expansion drove adjusted EPS to $2.26 for the quarter, increasing 20% versus the prior year. This marks yet another quarter of exceptional earnings growth.
Now let's turn to the Q3 EPS bridge on slide six. EPS growth was primarily driven by strong operational performance across all legacy businesses, which contributed 31 cents of growth through operating leverage, pricing, and net productivity savings.
The operational contribution from SPX FLOW added 80 cents of growth, partially offset by the impacts of the incremental interest, share count, and tax rate. What makes these results even more compelling is that we achieved them while making significant investments in engineering resources, in R&D, in LiDAR, and in production capacity to support future growth.
Now let's move to slide seven to discuss our updated 2026 outlook and guide. We are raising our full-year organic revenue guidance range to 7% to 9% growth, reflecting stronger bookings in CCT, continued strength across both project and short-cycle businesses in FT, and strong operational performance across all businesses.
On adjusted operating margin, we expect to deliver over 100 basis points of expansion to approximately 20.6% at the midpoint, fueled by top-line growth, favorable price-to-cost ratio, productivity gains, and accelerated synergy savings. Our tax projects have reduced the effective tax rate to 23.75% as of Q3, and this is considered in the full-year guide.
Because of the year-to-date results and the momentum we've generated in the first three quarters, we are raising our adjusted EPS outlook for 2026 to $8.58 at the midpoint. This represents a 36-cent increase and a 19% growth year-over-year, fueled by volume, pricing, productivity initiatives, and accelerated realization of cost synergies.
We now expect SPX FLOW's net contribution to be over 20 cents. Notably, the low end of our new guidance range now exceeds the high end of our prior range.
Finally, turning to cash and capital structure, we are raising the midpoint of our free cash flow guidance to $610 million, representing a free cash flow margin of approximately 11%. Strong cash generation continues to support our deleveraging efforts, and we remain ahead of plan as we drive towards approximately 2.1 times by year-end.
Now let me turn the call back over to Luca to wrap up on slide eight.
Luca Savi
Thanks, Mike. Before closing the call with key takeaways, I would like to share an organizational change within the ITT leadership team.
Davide Barbon, currently Senior Vice President and President of Motion Technologies, will expand his responsibilities and take the leadership role of Connect and Control Technologies in addition to MT. I would like to thank Michael Goode for his contribution in improving CCT over the last few years.
CCT is the business in our portfolio with the highest growth potential, the largest margin expansion potential, and the richest opportunity for continuous improvement. This is the perfect court for Davide to excel and run his playbook, where he can exercise once more his commercial acumen, his relentless drive for continuous improvement, and his 100 over 100 approach, capturing the 20 others leave behind.
Davide's incredible track record in APAC and in MT makes him the ideal fit to transform CCT. Congratulations, Davide, and thanks for all you've done, and above all, for what you will do and the value you will create for our customers, our shareholders, and our people.
Now, before we move to our favorite part of the call, the Q&A, let me drive home a few points. The message is the same: ITT differentiation is driving share gains, which continue to fuel growth across our platforms.
Our relentless execution continues to deliver margin expansion and accelerate earnings. Trust me, there is more to come.
Our acquisitions are turbocharging value creation and increase our growth opportunities. Guys, the strategy is sound and executed rigorously.
Q3 was strong, and our backlog is healthy and growing. This momentum gives us confidence for Q4 and entering 2027.
As always, I appreciate your time and continued interest in ITT. Liz, please open the line for Q&A.
Operator
The floor is now open for questions. At this time, if you have a question or comment, please press star one one on your touch-tone phone.
If at any point your question has been answered, you may remove yourself from the queue by pressing star one one. Again, we do ask that while you pose your question, you pick up your handset to provide optimal sound quality.
Please limit your questions to one question and one follow-up. Our first question comes from Scott Davis with Melius Research.
Luca Savi
Hi, Scott.
Mike Savinelli
Hi, Scott.
Jake Levinson
Hey, good morning. It's actually Jake on.
Surprise. [laughter] We've got a busy morning, I figured I would humor you folks.
I just had a quick question for you as you've got leverage coming down here pretty quickly. Now I think you peaked almost three times, will probably be well under two next year.
Is the organization in a place where you actually have the capacity to go out and do something I don't know if it's of the size of SPX, but certainly something on the larger side?
Luca Savi
Hi, Jake. I would say the focus right now continue in generate the cash, deliver on the synergies, pay down the debt, and be ready for something larger in 12, 15 months.
Now, this doesn't exclude bolt-on acquisitions. I would say in the next 12 months, you shouldn't be surprised if we are able to add some bolt-ons.
When it comes to larger acquisitions, I think that we still need to deliver and for our shareholders and prove the value of SPX FLOW. It's still early innings, as I said.
Jake Levinson
That makes sense. Just on a different topic, I didn't hear much of a mention of the Middle East.
I know there's obviously still a lot of disruption there, but those project discussions, are they starting to move forward at this point and the region's sort of settling into a new normal? Or is that still getting pushed to the right?
Luca Savi
Sure. Thanks, Jake.
When you look at the Middle East, we really have two operations there, Jake. We have Habonim, making valves, hydrogen, LNG in Israel, and Goulds Pumps in Dammam, Saudi.
When you look at the former, it's performing exceptionally well. We are growing orders, we're growing revenue, we are suffering a little bit on the operating margin because of the cost.
You can imagine the operations are not as efficient as they could be, the cost of transportation. You're talking about high teens versus in the 20s.
That is going incredibly well. Done to Ilan and the team.
The latter, which is the Goulds Pumps in Saudi, well, first of all, this business has been growing, and on a look at the full-year basis, probably this business this year will be growing more than 20%. This is because we're delivering a very healthy and very good backlog that we had at the beginning of the year.
When it comes to the orders, the orders shifted to the right, as you said. I'm pleased to share that in Q3, some very good orders start materializing, but of course, not at the level that it was in the past.
Things are moving, and we booked some good orders for some very good investment with Saudi Aramco.
Jake Levinson
That makes sense. Thank you, Luca.
I appreciate it. Pass it on.
Luca Savi
Thank you, Jake.
Operator
Our next question comes from Jeff Hammond with KeyBanc Capital Markets.
Luca Savi
Hi, Jeff.
Jeff Hammond
Hey, good morning. Hey, just on flow margins, they were a little light versus my expectations.
I don't know if that's mix or some of the Middle East noise. Just kind of maybe talk about margin progression.
I know the synergies are running ahead, but margin progression on the core.
Luca Savi
Sure. If you look at Flow Technologies, the margin at 22.4% is if you look at the legacy, the legacy was approximately 20 23%, and so you had 60 basis points of dilution in the margin of Flow Technologies.
Now, sequentially, it improved 100 basis points, Q2 over Q3. Volume and price were positive, but you rightly said, Jeff, the mix was negative.
There was a negative mix as well as 60 basis points of acquisition dilution.
Jeff Hammond
Great. Then just on flow, can you just speak to pipeline?
I think you covered Middle East pretty well, but there seem to be some concerns about orders, which turned out pretty good, but might just pipeline and flow. Then just as you think about revenue synergies on SPX FLOW, you listed a lot of opportunities, just how do you think that's coming along versus expectation where that starts to deliver differentiation in '27?
Thanks.
Luca Savi
When you look at the pipeline, the funnel is healthy, and it continues to grow. It was up in Q1, it was up in Q2, it's up again in Q3, roughly 6% year-over-year.
This is really a powerful flywheel, the way that I see, Jeff. Because you have a good revenue growth when you look at the business, right?
On top of this good revenue growth, you have a book-to-bill which is above one. Orders are coming in faster than your revenue growth.
The funnel of opportunities is actually increasing 6% in the quarter year-over-year. The funnel gets replenished even at a faster rate than you're booking the orders.
It's a powerful flywheel. It's fair to say that when you look at geography, the most powerful region is North America, and this is really the best growth engine that we have within Flow Technology.
Latin America is good as well, but North America is definitely where the growth is. Going to the second part of your question, revenue synergies.
It takes time in terms of revenue synergies. This is really why we didn't put them in the model.
Now, having said that, Waukesha has done an outstanding job, Rudy and the team to move super fast to localize the inventory, to start selling this Bornemann pumps. We're proceeding quite fast on the localization also of the assembly and the venture of the machining.
I'm feeling very positive about that. As a matter of fact, we had just recently a touch-base with Wendy on the localization of mixers both in the Middle East and in Latin America.
Things are progressing quite well, I would say, but it takes time to get revenue synergies in the books.
Jeff Hammond
Okay. Thanks so much.
We'll be patient. [laughter]
Luca Savi
Thank you, Jeff.
Operator
Our next question comes from Mike Halloran with Baird.
Luca Savi
Hi, Mike. Hey,
Mike Halloran
good morning, everyone. How are you doing?
Luca Savi
Good. How are you?
Mike Halloran
I'm lovely. CCT, just another quarter of dynamic trends here.
Maybe you could talk about maybe more context on durability, I suppose. What is this mean for forward visibility, all else equal?
How do these contracts that you're winning right now cadence out? What's the line of sight to continue to see the strength, maybe not at this level, but still strong win rates and customer penetration on a forward basis?
Luca Savi
Sure. Let me address this in two ways.
When you look at the strength of the order in CCT is broad, is across the board. You have it in controls, up 34% in orders.
You have it in connectors, up 37%, after already a Q2 of 38% up. Casaria, 136%.
Now, and it's broad across different segments: it's aero, defense, it's industrial. Now, if I think about some of these markets, aerospace, the recovery will keep on going.
Defense, the spending will keep on happening. I think that from a market point of view, we will continue to have these tailwinds for a while, and the team is doing a great job in winning market share on the award side.
Now, in terms of the ability to translate this into revenue, we got a very good situation here because we look at the backlog in the short, medium, and the long term. Our backlog for Q4 and for 2027 is up more than 30% versus what we had last year at this point in time.
The one for the long term, the big platform, is up more than 100%, which gives you extreme visibility. This is really a good platform for growth for the future, Mike.
Mike Halloran
Thank you for that. Then prepared remarks, you alluded to CCT having the most margin upside.
Not really surprised, but maybe just give some context on why you feel that way and what those aspirations look like.
Luca Savi
Sure. For the aspiration, you will have to wait our next Capital Markets Day that is going to happen next year, right?
You need to be patient on that one. Let me tell you why we see that way.
Is the segment, is the market where you've got the best pricing leverage in, and therefore, this is an area where we have done a good job, but believe me, we can do much, much more, and that is a big lever. Second, when I look at the continuous improvement and the lean and the factory and the operations, this is probably the value center of the business that is still behind compared for sure to MT, but also compared to Flow Technologies.
Therefore, there is plenty of opportunity there, and not to talk also in terms of the purchasing. Because of this lever and the level of maturity that we have there compared to MT or Flow Technologies, this is why we think we have this great opportunity.
Mike Halloran
Thanks, Luca. Appreciate it.
Luca Savi
Thanks, Mike.
Operator
Our next question comes from Joe Ritchie with Goldman Sachs.
Luca Savi
Hi, Joe.
Mike Savinelli
Hi, Joe.
Aanvi Patodia
Hey, Luca. Hey, Carleen.
This is Aanvi on for Joe. Good morning, and congrats on the quarter.
Luca Savi
Thank you.
Aanvi Patodia
I just wanted to touch upon the 2026 guide and the puts and takes around it. I recognize you took up the organic growth guide, but you've had a really strong order growth, as well as organic year-to-date.
Q4 kind of implies a low- to mid single-digit growth in the quarter. I know you've spoken about the four extra days coming out of Q4.
I just wanted to understand the puts and takes on what we should keep in mind and how you're thinking about it versus your initial guide.
Luca Savi
Okay. I think that when when we look at the Q4, I think that our guidance is having a Q4 which is pretty much aligned with our with our Q3.
I think that what you what we need to pay attention here, as as you rightly said, is in Q4, we're going to have four days less on a year-to-year on a year-over-year basis. Then also, probably some headwind when it comes to the automotive market.
What we see is that because of the dynamic in the market, there is the potential that several OEMs might decide to shut down earlier in December that originally forecasted. For that reason, specifically when you look at Motion Technologies, it will be on a year-over-year more of a challenging compare, even though they're growing on a on a yearly basis, but Q4 will be to be more challenging for them.
Aanvi Patodia
Got it. That's helpful.
Just as my follow-up, since you mentioned Motion Technology as well, the margins in that segment have really been a standout and have now sustained for 21% at the 21% for the last three quarters. I just wanted to understand how repeatable that productivity performance is and what kind of volume assumptions you're baking in to achieve your 2030 margin targets, given some of the softness that we're seeing in the auto OEM space and also the price/cost environment.
Luca Savi
Sure. You're spot on.
21 21% now is the new floor. Really, the team is doing an exceptional job in really consolidating this 21% and then to continuous to improve.
I would say that when you think about we are targeting our long target by 2030 with a 23% independently from the growth in the market. The reason for that is because we still have several opportunities to improve in our costs, in our plant.
Let me give you a couple of examples. If you think about our high-performance plant, which we started in 2025.
Now, we are making money this year, but Q3 was at just double-digit profitability and much dilutive to the profitability of several of the plants in friction. As we're ramping up, that margin will go up.
There are plenty of opportunities still to improve productivity in the plant and eliminating waste, and then the introduction of new formulation like the Geopad, which will start production for a European OEM in Q1 2028, that will give us some room, as it's going to be a much more cost-competitive product.
Aanvi Patodia
Got it. Thanks for that detail, Luca.
I'll get back in queue.
Luca Savi
Thank you.
Operator
Our next question comes from Daniel DiCicco with BMO Capital Markets.
Luca Savi
Hi, Dan.
Daniel DiCicco
Morning, everyone.
Luca Savi
One one more
Daniel DiCicco
one more on CCT. Obviously, impressive growth again, another really strong orders quarter.
I know you acquired Aerospace Contacts to help the supply base there, but maybe you could talk through some of the investments you're making to help sustain that growth, and if there's any other areas that you're kind of focused on. Thanks.
Luca Savi
Thank you, Dan. Spot on.
We acquired Aerospace Contacts in July, and actually spent a couple of days with Art and the team in Phoenix with them the other week. Is a good plant.
We got good machines for the high-mix, low-volume contacts. Ed and Melissa are doing fantastic job, the management over there.
We are talking to Ed and Melissa to invest in new machines also to address the high-volume, low-mix contacts, which completely different type of machine, and therefore, setting up a different shop floor close by. We also invested in new machines, and this has been a process that started more than 12 months ago in Weinstadt, Germany, for our molding, for our machining, and also in Nogales, Mexico.
This is really to be able to supply this level of growth. This analysis continue on a monthly basis, I would say.
Daniel DiCicco
Great, thank you. Just the Casaria numbers are huge, and so I know you'd mentioned the F-35, but just what are some of the other platforms you're seeing there?
Then what is really driving those wins for you all? Thanks.
Luca Savi
Sure. Mike Stravalle, Mike, the team in Casaria team are doing a fantastic job in execution.
They're really well-known in the market for doing a consistent, good job and for delivering on time. This was a feedback that we got it loud and clear also during the due diligence.
Therefore, because of this consistent execution, they are able to win market share. I know it might not sound particularly sexy, there are not cool words saying it, but it's just great at execution and they're differentiating in executing.
They are able to win in the submarines, the Virginia and Columbia class, the fighters, the F-35, and they are also on the missile programs. Is broad-based, I would say.
Daniel DiCicco
Great. Thank you so much.
Luca Savi
Thank you, Dan.
Operator
Our next question comes from Joe Giordano with TD Cowen.
Joe Giordano
Hey, good morning, everyone.
Luca Savi
Hi, Joe.
Joe Giordano
Morning. Luca, I've felt for a long time that Davide did not have enough work to do, I'm glad to see him doing this now.
[laughter] I just am curious like MT playbook, how applicable is it to CCT, right? Like MT, you think about friction in particular, very consolidated, big plants that serve a global footprint, high volume.
CCT, smaller businesses, more plants, more like a lot of higher mix type stuff. How does he take what he's done so well at MT and apply it to CCT?
Luca Savi
Sure. Okay.
When you talk about drive for continuous improvement, that can apply at whatever manufacturing setup that you have, right? Then those differences are absolutely true.
You're absolutely true, Joe, and those tend to be used by people as excuse to justify numbers that are not the way that should be. This is that I honestly say.
Let me give you a specific example: in Shenzhen. Shenzhen is our plant in Connectors in China.
Sergio is taken over that plant and the business of our connector business in Asia-Pacific and in China. That plant is performing in terms of on-time delivery at the 99%, exactly like MT; has got the best quality track record of all the plants in Connectors; and is really using the playbook of friction and Motion Technologies, like for like.
It has been done, right? You really need to have the drive, the willingness, and the stamina to make it happen.
Davide has that.
Joe Giordano
You mentioned earlier the industrial pump piece of SPX needs to be closer to customers, talked about opening up in China and India and probably reducing exposure in Europe. That all makes sense, but my first thought is that could take a ton of time to do.
Of all the qualities you have, patience maybe isn't [laughter] one of the primary virtues I'd think about. Could you maybe talk to us about how realistic it is to do that quickly?
Luca Savi
Sure. If you think about it, when I was in Shidu a couple of months ago, the team was already setting up the assembly operation for the Bran+Luebbe pumps in China.
Let's not forget, Bran+Luebbe is a very well-known brand. It's really well-known in the market.
We do not need to sell or spend time in selling the brand. It's just that we need to localize it so that we can reduce the lead time, so that we can make it more cost-competitive.
It doesn't make any sense this day to make these pumps in Germany and thinking that you're go cost-competitive and the lead time and price, and sell it in China. Those times are gone.
Setting the assembly in China is I wouldn't say it's easy-peasy, but it's not that complicated. The same thing is in the Middle East.
We are setting up the assembly of Bran+Luebbe also in the Middle East. The resizing in Europe is happening, and it's happening right now.
Now, it's a good plant in Europe, don't get me wrong. Obviously, the chemical market in Europe has been declining, and therefore, we need to adjust the supply to the demand for that region.
Did I answer your question, Joe?
Joe Giordano
You did. Thank you.
Luca Savi
Thank you, Joe.
Operator
Our next question comes from Andrew Obin with Bank of America.
Andrew Obin
Hi, Andrew. Hi, guys.
Good morning. How are you?
As I said, let's more questions related to Davide because, clearly, he is underutilized. Maybe on Motion Tech, you're sort of highlighting in terms of technology, right?
You have consistent history of market share gain. Maybe, can you just talk to us if and when we're going to see the impact of electronic brakes and actual products with geopolymer sort of impacting organic growth in this business?
I know you've made the investments. I know you are sort of at the cutting edge of technology.
Is it a '27 event? Is it a '28 event?
When do we start seeing that? Thank you.
Luca Savi
Sure. Thank you, Andrew.
It's a very pertinent question, because when you look historically, every single time there is a technological change, be the copper-free brake pad, be the electric vehicles, or the Euro 7 regulation, and eventually will be the new brakes, this is where we leapfrog and when we gain a sizable amount of market share. Because our R&D is how we differentiate.
You have seen it, Andrew, in Italy when you went to Barge. It's a powerhouse.
It's going to play in our playground. It's really good for us.
Now, I think that when you look at those brakes, you start seeing those brakes in China, and I would say you will start seeing more and more. I would expect the China to be probably the region that will see them faster and with faster adoption.
When you look at the Geopad, we will start seeing the Geopad entering the market in Q1 2028. After that, many of the new platform that we will either try to conquer or that we will re-win will be based on a formulation that might be in the Geopad family.
Andrew Obin
Thank you. Maybe a follow-up question on Joe Joe Giordano's question on sort of learnings from Motion Tech.
It seems Termoli is a very, very unique facility, you sort of doing cutting-edge stuff there. What's the opportunity to take manufacturing processes that you use in Termoli and look, I, as I said, Joe sort of talked about the fact that it's what the nature of the process is.
Can you take what you take at Termoli and take it to, maybe Casaria, take it to your other businesses? Because what you're doing there is very unique in my understanding.
You've guys been quite successful.
Luca Savi
Yeah. What you saw in Termoli, Andrew, is and that level of automation, I think that similar, you need to adapt it, could be probably adapted to some of the controls and some of the connector business.
Automation is definitely an area where we can improve in those two areas. Different, I would say, for Casaria.
Can we improve the automation in Casaria? Sure, but that will be a little bit more tricky.
Controls
Andrew Obin
[crosstalk] I'm just using it as an example. Sorry, Luca.
Yeah.
Luca Savi
No, no, no, no, no. No, no.
Connectors and controls, absolutely. Now with Davide being in charge of CCT, I think that it will be also easier to expand the responsibility and double-hat some more people in Motion Technologies, too.
Andrew Obin
Thank you very much.
Luca Savi
Thank you, Andrew.
Operator
Our next question comes from Robert Davies with Wolfe Research.
Luca Savi
Hi, Robert.
Mike Savinelli
Hi, Robert.
Robert Davies
Hi. Morning.
Thanks for taking my question. First was just if you could cover the price/cost dynamics across the different segments, just be kind of curious where you're pushing through prices most aggressively, where kind of costs are rising most quickly.
Just a bit more color by segment would be helpful. Then the other one was just around M&A and the comment you made earlier on the bolt-ons.
I'd just be curious now sort of post the SPX FLOW deal, when you look across the portfolio, is there any sort of regional gaps? Is it sort of product kind of holes you need to fill in the portfolio?
What would be a sort of primary place to look? Thank you.
Luca Savi
Okay. Thanks, Robert.
When you look at the price/cost, I think that the dynamic has not changed, and it's still very much the same. What you have is a price/cost positive in Flow Technologies.
The team is acting very quickly, and we are ahead of the game here, and therefore, that dynamic is positive. On CCT, is even more positive, I would say, in terms of pricing cost.
This is also the comment that I made earlier. This is the segment where we got more pricing leverage, and this dynamic is happening, and that will be price/cost positive, for the full year.
Obviously, when you look at pricing, the dynamic is different in Motion Technologies. This is where you have to give price and efficiency to the customer.
Now, having said that, three, four years ago, we were able to work with our customers to ensure that the major commodities and energies get indexed in the contract. What you have is that if the commodities goes up, copper, tin, steel, or energy cost goes up, you are getting some price, some compensation.
You only have a time lag on that one. Don't forget, you always need to give efficiency in this market.
Having said that, if you look at between those changes in the contract, the move of the commodities, as well the efficiency that we are delivering in the business, you see that the margin keeps on improving in Motion Technologies, and was 70 basis points in the quarter, and we are really flooring at 21 today.
Robert Davies
Thank you.
Luca Savi
Oh, and then the M&A. Sorry, I was forgetting, Robert.
Sorry. On the M&A front, I would say yes, we are active on the M&A front.
We are cultivating, Bartek and myself and the business leader, and we are spending time cultivating. Now, the sectors that we are spending time are really on CCT, on the connectors, particularly on aero and defense, and on the Flow Technologies.
These are really the areas where we are spending time and cultivating. Now, we're also looking, but this probably is a little bit still early, on the SPX FLOW business unit.
If you think about mixer, if you think about the nutrition and health, there might be areas where there are technology gaps or product gaps where we might need to make some acquisitions. Those acquisitions will not be today large.
It will be just to cover a product gap, also because we want to ensure that we consolidate the performance of SPX FLOW.
Operator
Once again, if you do have a question, you may press star one one on your touch-tone phone at this time. Our next question comes from Vlad Bystricky with Citigroup.
Luca Savi
Hi, Vlad. Hi, Vlad.
Vlad Bystricky
Hey, guys. Morning.
Thanks for getting me in here. I guess maybe just first question for me, Luca, just following up on the price/cost question that you just answered and sort of the different dynamics in Motion Tech [cough] in the friction business in particular, have you seen any changes or incremental pressure on commercial terms from the OEMs just given the competitive dynamics that are out there for them globally?
Luca Savi
I would say, it has always been tough, and it gets tougher and tougher, I would say. That's the dynamic of that business.
This is the game in that market. Having said that, Vlad, this is helping in building super-resilient team and team that are really driving continuous improvement with a hunger that you've seen in MT that now we're going to spread also in CCT.
Vlad Bystricky
Got it. That's helpful, Luca.
Then I guess just stepping back, if I think about the bigger picture here, obviously, very strong organic growth on the revenue side this year, strong organic orders growth, but there's still obviously some macro crosscurrents out there in the broader economy. Can you just talk about how you're thinking about some of the puts and takes heading into next year and how that could influence or impact your ability to continue to grow organic top line sort of at an accelerated pace versus the longer-term 5% plus target you have out there?
Luca Savi
Sure. Thanks, Vlad.
I would say we need to talk about the market in all the different segments, right? If you look at Motion Technologies, listen, the automotive market is what it is.
Can we change that market? No, we can't.
What we can do is continue to outperform. I can tell you that we think that we will be able to outperform the market for the next two, three years because we saw the award.
We won the awards last year and this year, and therefore, we know what is going to start and the one that we conquer. You should expect an outperformance in 2027 and the next couple of years similar to what you had here in 2026.
The rail will be growing, and I think that that trend is continuing. When you look at KONI, you've got also the tailwind of defense.
That is a positive tailwind in that business when it comes to MT. Now, if you look at Flow Technologies, we look at Flow Technologies, oil and gas, chemical, general industrial, North America, Middle East, is an interesting dynamic there.
Our backlog at the end of the year will be higher than what it was last year, and not talking just about the SPX FLOW, I'm talking about our own backlog, right, in the legacy backlog. That is a positive trend.
If you think about the Middle East, is a headwind because the backlog in the Middle East will be lower, but we already covered that and surpassed with the, for example, Venezuela or other investment in North America. That is good.
North America keeps on being a engine growth. Latin America is positive as well with investment on the mining, and we'll end back the year with a higher backlog.
Good trend there, and definitely a good starting point, higher backlog beginning of 2027. Then when you look at CCT, listen, the backlog for Q4 and '27 is 30% or more higher than it was last year at this point in time.
The one for '28 and above is even higher. When you look at aero and defense, there is a tailwind.
This is really the first time, to be honest with you, this year where we have been able to have some tailwinds, and we take it.
Vlad Bystricky
Understood. Thanks, Luca.
Luca Savi
Thanks, Vlad.
Operator
Thank you. This does conclude today's teleconference.
Please disconnect your lines at this time, and have a wonderful day.
Luca Savi
Thank you.