Lument Finance Trust, Inc. 7.875% Series A Cumulative Redeemable Preferred Stock
Q2 FY2026 · Earnings Call TranscriptAugust 14, 2026
Operator
Good morning, and thank you for joining the Lument Finance Trust Second Quarter 2026 Earnings Call. Today's call is being recorded and will be made available via webcast on the company's website.
I would now like to turn the call over to Andrew Simon with Investor Relations at Lument Investment Management. Please go ahead.
Andrew Tsang
Morning, everyone. Thank you for joining our call to discuss Lument Finance Trust second quarter 2026 financial results.
With me on the call today are Jim Flynn, our CEO; Jim Briggs, our CFO; Greg Calvert, our President; and Zach Halpern, our Portfolio Manager. Last evening, we filed our 10-Q with the SEC and issued a press release to provide details on our recent financial results.
We also provided a supplemental earnings presentation, which can be found on our website. Before handing the call over to Jim Flynn, I'd like to remind everyone that certain statements made during the course of this call are not based on historical information and may constitute forward-looking statements within the meaning of Section 27A of the Securities Act of 1933 and Section 21E of the Securities Exchange Act of 1934.
Such forward-looking statements are subject to various risks and uncertainties that could cause actual results to differ materially from those contained in the forward-looking statements. These results and uncertainties are discussed in the company's reports filed with the SEC, in particular, the risk factors section of our Form 10-K and Form 10-Qs.
It is not possible to predict or identify all such risks, and listeners are cautioned not to place undue reliance on these forward-looking statements. The company undertakes no obligation to update any of these forward-looking statements.
Further, certain non-GAAP financial measures will be discussed on this conference call. Our presentation of this information is not intended to be considered in isolation nor as a substitute for the financial information presented in accordance with GAAP.
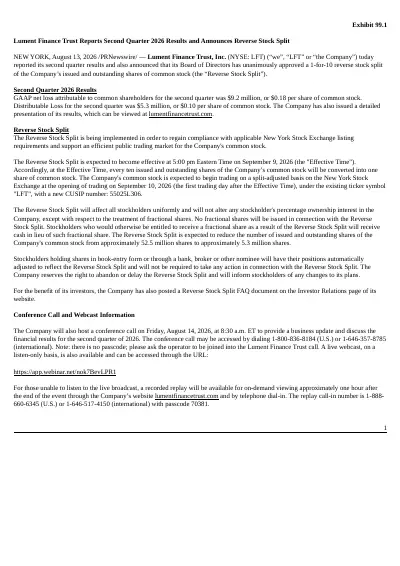
Reconciliations of these non-GAAP financial measures to the most comparable measures prepared in accordance with GAAP can be accessed through our filings with the SEC. For the second quarter of 2026, we reported a GAAP net loss of 18 cents and distributable loss of 10 cents per share of common stock.
In June, we had declared a quarterly dividend of 4 cents per share with respect to the second quarter, in line with the prior quarterly dividend. I will now turn the call over to Jim Flynn.
Please go ahead.
Jim Flynn
Thank you, Andrew. Good morning, everyone.
Welcome to the Lument Finance Trust earnings call for the second quarter of 2026. We appreciate you joining us today.
We also wanted to express our appreciation to our investors for their patience, support, and continued engagement as we work through issues in the legacy portfolio. We recognize the challenges that the company has faced, and we remain focused every day on improving outcomes for our shareholders.
Looking at the economic and market conditions in the country today, conditions remain generally stable. There is continued uncertainty around monetary policy weighing on investment activity.
Recent economic data has increased uncertainty regarding the path of the Fed, including whether short-term rates may remain elevated for longer than previously expected. Long-term rates also remain elevated, continuing to pressure transaction activity and real estate valuations.
Within multifamily, fundamentals continue to improve as the sector moves beyond peak supply levels. While rent growth remains modest, long-term demand drivers, including housing affordability challenges, continue to support the multifamily rental sector.
Capital markets remain active, with liquidity available across warehouse, securitization, and institutional lending channels strong through the first half of this year. The CRE CLO market continues to be an important source of financing for multifamily mortgage assets, and investor demand for floating-rate credit remains relatively strong, particularly for repeat issuers with proven track records.
Active asset management remains our highest priority. We continue to work closely with borrowers and operating partners to maximize outcomes across both performing and non-performing investments.
We continue to proactively evaluate resolution strategies for legacy assets while maintaining a disciplined approach to credit. While the market for certain legacy assets remains soft, we are beginning to see an acceleration in resolution activity, including both negotiated sales and other paths to monetize or stabilize challenged positions.
We continue to work tirelessly to resolve these assets in a manner that protects value, improves liquidity, and positions the company to reinvest capital efficiently. On the portfolio side, during the quarter, we were intentional about managing liquidity on our balance sheet to support ongoing portfolio management efforts while selectively redeploying CLO capital when available.
We generally held on to cash from non-securitized asset loan payoffs. Our financing profile remains well positioned following the refinancing initiatives completed earlier this year.
We believe our current liquidity position remains appropriate to support asset resolution activities, portfolio management, and selective capital deployment opportunities. As capital becomes available through resolutions and repayments, our objective is to redeploy it efficiently into investments that meet our credit standards and are expected to be accretive to earnings.
We are being disciplined on timing and asset selection, but we are also focused on ensuring that the company's capital is put back to work as efficiently and quickly as possible. Our board of directors recently approved a 10-for-1 reverse stock split of our common stock after having determined that such actions were in the best interests of the company and its stockholders, providing flexibility to maintain compliance with the applicable New York Stock Exchange listing requirements and support an efficient public market for the company's common stock.
The reverse stock split is expected to become effective at the close of business on Wednesday, September 9th, and the company's common stock is expected to begin trading on a split-adjusted basis on the New York Stock Exchange at the opening of trading on Thursday, September 10th under the existing ticker symbol, LFT. The reverse stock split will affect all stockholders uniformly and will not alter any stockholder's percentage ownership interest in the company, except with respect to treatment of fractional shares, which will be paid out in cash.
We have also posted for our investors a reverse stock split FAQ document on our website. We believe the reverse stock split is an important step toward reducing technical pressure on the public stock price and supporting a more orderly market for our shares.
While this action does not change the underlying economics of the company, we believe it helps address one of the external pressures on the stock and allows investors to focus more clearly on the value of the portfolio, our asset resolution progress, and our earnings trajectory. Our priorities remain unchanged.
We are committed to resolving legacy assets, protecting book value, and thoughtfully redeploying capital into high-quality multifamily investments. We appreciate the continued patience and support of our investors and capital partners as we execute on this plan.
While we recognize the resolution of our non-performing and REO assets remains challenging, we are seeing improving momentum in deal resolutions and sales activity. As those resolutions occur, we intend to reinvest capital efficiently and on a disciplined basis.
We remain committed to fully deploying our capital in 2027, which we believe will be an important driver of improved earnings and, over time, enhanced shareholder value. We recognize there is still work to do and the timing of certain NPL and REO resolutions remains subject to submarket conditions.
That said, we believe the company has the support of its capital partners, a clear path to redeployment, and the platform capabilities necessary to move forward constructively. With that, I'd like to turn the call over to Jim Briggs, who will provide details regarding our financial results.
Jim?
Jim Briggs
Thanks, Jim. Good morning.
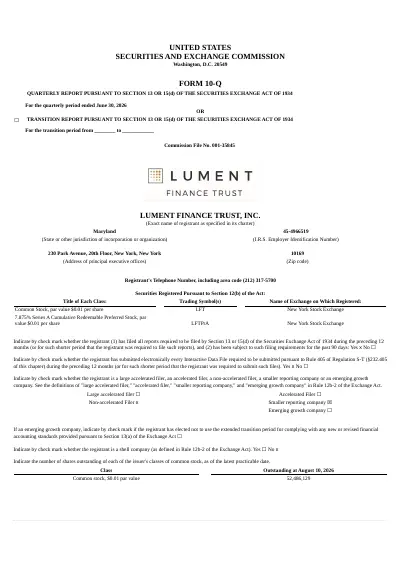
Last night, we filed our quarterly report on Form 10-Q and provided a supplemental investor presentation on our website, which we'll be referring to during our remarks. Supplemental investor presentation has been uploaded to the webcast as well for your reference.
On pages 4 through 7 of the presentation, you'll find key updates and an earnings summary for the quarter. For the second quarter of 2026, we reported net loss to common stockholders of $9.2 million, or 18 cents per share.
We reported a distributable loss of $5.3 million, or 10 cents per share. A few Q2 P&L items I'd like to highlight: Our Q2 net interest income was $4.5 million, sequential decline from $5.7 million recorded in Q1.
This was primarily driven by a lower average loan portfolio balance quarter-over-quarter as we chose to build liquidity during the quarter rather than reinvest principal repayments from loans held outside of CLO. The ending outstanding UPB of the total portfolio was approximately $1 billion compared to $1.13 billion as of March 31st.
The weighted average coupon of our loan portfolio declined to 704 basis points compared to 709 basis points in the prior quarter, due to payoffs of higher-spread loans relative to newly acquired assets, as well as a slight decline in the average SOFR rate during the period. Although we had greater payoffs compared to Q1, our exit fee income was relatively flat to prior quarter, and recognition of extension fee income was down by about $300,000 quarter-over-quarter.
Our total operating expenses, including fees to our manager, were higher quarter-on-quarter at $3.9 million versus $3.7 million. Primary driver was higher reimbursable expenses compared to Q1, driven primarily by resource allocation.
Difference between reported GAAP net loss and distributable loss during the quarter was primarily attributable to an $8.6 million net provision for credit losses recorded in the period, $5.1 million of realized losses on mortgage loans and REO included in distributable, and $390,000 of depreciation on REO. The $8.6 million in net provision for credit losses recorded during the quarter, which is excluded from distributable earnings, was driven primarily by specific reserves on our risk-rated 5 loans.
As of June 30th, we had six loans risk-rated 5, all collateralized by multifamily assets. Greg will provide a bit more detail in his remarks.
We evaluated our risk-rated 5 loans individually to determine whether asset-specific reserves were necessary. During the quarter, we recorded specific provisions related to two loans downgraded to a 5 risk rating in the quarter and three loans that were already risk-rated 5 at March 31st, including one property that was foreclosed upon and transferred to REO during the period.
Specific reserves totaled $7.4 million at quarter-end, representing approximately 18% of the associated UPB of specifically evaluated assets. The $5.1 million in realized losses included in distributable earnings related to three assets that were fully resolved in the quarter.
These included discounted payoffs on two previous 5 risk-rated loans, one in Philadelphia and one in Des Moines, with proceeds generally consistent with their March 31st net carrying values. In addition, we sold one REO property in San Antonio for $12.1 million and recognized a small GAAP gain on that sale.
The realized losses reflected in distributable earnings this period were primarily attributable to prior-period reserves and impairments recorded on those assets. At quarter-end, our CLO's capital was substantially fully deployed at an 88% advance rate and a cost of funds of SOFR plus 191.
As of June 30, a portion of our loan and REO portfolio were pledged to warehouse facilities that provided financing at an effective advance rate of 68% and a weighted average cost of funds of SOFR plus 209. We ended Q2 with an unrestricted cash balance of $29 million, and FL3 was substantially fully deployed.
The company's total book equity at the end of the quarter was approximately $205 million. The total book value of common stock was approximately $145 million, or $2.76 per share, decreasing sequentially from $2.97 per share at March 31st.
I will now turn the call over to Greg Calvert to provide details on the company's investment activity and portfolio performance during the quarter. Greg?
Greg Calvert
Thank you, Jim. During the second quarter, LFT acquired or funded four loans with an aggregate UPB of $91 million and experienced $184 million of loan payoffs.
As of June 30th, our total loan portfolio consisted of 51 floating-rate loans with an aggregate unpaid principal balance of approximately $1 billion, a weighted average floating rate of 330 basis points over SOFR, and an unamortized aggregate purchase discount of approximately $800,000. The weighted average remaining term of our book as of quarter-end was approximately 18 months, assuming all available extensions are exercised by our borrowers.
100% of the portfolio was indexed to one-month SOFR, and 91.7% of the portfolio was collateralized by multifamily properties. As of June 30th, approximately 81% of the loans in our portfolio were risk-rated at 3 or better, compared to 77% as of March 31st.
Our weighted average risk rating quarter-over-quarter remained stable at 3.1. During the quarter, we had several positive asset resolutions, including the resolutions of the two loan assets Jim mentioned in his remarks, which had been risk-rated 5 as of March 31st and for which we received payoff proceeds consistent with March 31st net carrying values.
As of June 30th, we had six risk-rated 5 loans with an aggregate principal amount of $98 million, or approximately 10% of the unpaid principal balance of our quarter-end investment portfolio. Four of these loans, with an aggregate UPB of $62 million, were also risk-rated 5 as of the prior quarter due to either maturity or monetary default.
Two of these loans, with an aggregate UPB of $36 million, were downgraded to a 5 risk rating for the first time due to monetary default. As of quarter-end, the REO portfolio in total consisted of four multifamily properties with an aggregate carrying value of approximately $61.6 million and a weighted average occupancy rate of approximately 67%.
During the period, we completed a sale of one San Antonio REO asset with a carrying value of $12.2 million. We also foreclosed on a multifamily property in Arlington, Texas.
The $15.7 million loan associated with that property had been risk-rated a 5 as of March 31st. Subsequent to quarter-end, we foreclosed on a multifamily property in Dallas, Texas.
This property had a $21.9 million mortgage loan associated with it and was risk-rated 5 as of 6/30. We have been very active in seeking positive asset resolutions and maximizing recovery values, and are pleased with the significant progress we have made so far.
Yet, we understand that there is still more work to be done on behalf of our shareholders. With that, I'll pass it back to Jim Flynn for his closing remarks and questions.
Jim Flynn
Thanks, Greg. I'd like to thank everyone for joining us today and for your continued partnership and support.
We recognize and appreciate the patience of our investors as we work through our legacy assets and reposition the company for improved earnings. We remain focused on resolving those challenged assets, redeploying capital efficiently, and moving the company toward a fully invested, higher-earning portfolio in 2027.
Importantly, we continue to have the support of our capital partners as we move forward, and we believe the actions we are taking today position LFT to create value for our shareholders over time. With that, I'll ask the operator to open the call for questions.
Operator
Thank you. Ladies and gentlemen, we will now begin the question-and-answer session.
Should you have a question, please press the star followed by the 1 on your touch-tone phone. Should you wish to cancel your request, please press the star followed by the 2.
If you are using a speakerphone, please lift the handset before pressing any keys. Once again, that is star 1 should you wish to ask a question.
Your first question is from Steven Sachs. Your line is now open.
Steven Sapp
Yes, hello.
Jim Flynn
Morning.
Steven Sapp
I've been a shareholder for many, many years, and I see the book value declining considerably along with the stock price, which is what I'm concerned about. Your dividend, which I bought many years ago, has declined also significantly.
I see what you're paying now, and my question is, I don't know how you're going to continue to pay that. A very simple question I have, it's just a size of scale.
I don't think there's any company that's smaller than your company as far as assets and market cap in this particular space. There's another company I own, Cherry Hill, which recently made a merger with MITT.
My question is, I see your expenses going up. I don't blame you, inflation is there, people got to earn money, everything costs money these days, but do you see an opportunity to merge with another company because the scale just doesn't make sense, or just sell the assets, since you said the book value is $2.76?
Thank you. Thank you.
Jim Flynn
Thank you for the question. Thank you for your time as a shareholder.
We appreciate that support. I think that you've certainly identified a challenge which we've discussed in the past, which is our size, and compared to many of the larger competitors in the space, that is accurate.
It's also one of the reasons our portfolio, probably on the average, has distressed assets in the same relative percentages as the peer set. Our challenge is our size, and so we've held liquidity on our books and not redeployed that capital.
That's further suppressed earnings in addition to losses that have been taken on underperforming loans. That's one of the drivers as you point out, and as we move through these assets and redeploy capital, we should be able to improve earnings as we move forward.
In terms of evaluating potential M&A opportunities or other strategic alternatives, that is something that we continue to do with our bankers, with anyone that has discussions with us, with our board. All of those options are evaluated as they come up.
Unfortunately, over the past couple of years, we've been unable to execute on any of those that were discussed, and to the extent something came forward, we certainly would discuss that with the board, and take any alternatives that could create shareholder value seriously, and will continue to do so as we move forward.
Steven Sapp
The other question is, how about just wrapping up and selling the assets at $2.75 before they get any lower?
Jim Flynn
That's a fair question, certainly a consideration of our board and the management and discussions with the board. The one caveat I would say is if you take a look at the market, the market for selling portfolios of assets of this type, particularly some of the older vintage multifamily assets, if we were to attempt to sell that into the market, it might be difficult to sell the entire portfolio at those recoverable values.
As you point out, I think, to the extent there is a strategic investor or someone that we were able to find, it would be something we would have to consider as a management team and a board.
Steven Sapp
Concern I have is the book value, not just of you, but of many of these companies in the space, that they're overinflated. The book value should be what you should be able to receive, in my opinion.
Jim Flynn
We believe that our book value does represent what we will receive on these assets.
Steven Sapp
Okay. Listen, I've taken enough of your time.
I appreciate you answering my questions. As I said, I've been a shareholder of prior to when you raised money through a rights offering.
You can see how long I go back, and this has been the most disappointing REIT that I have. I have a significant portfolio of REITs, and this has been the most significant.
Hopefully, you can turn this around. I remember when I bought this, everybody said you were conservative, and that this would be a very, very good management company, and that's why I bought the stock.
Hopefully, you guys can turn it around or make a decision to look out for the shareholders instead of having the increase in expenses. That's sort of like an insult to me as a shareholder.
Everybody has to suffer. The stock is down, but I think the management should take some responsibility, and the best responsibility is one word: money.
That's all the questions I have. I appreciate the time that I had here, and I appreciate your answers.
Again, I hope you look out for the shareholders. That's my concern.
Thank you very much.
Jim Flynn
Thank you. We appreciate both your questions and your time as an investor.
Operator
Thank you. Your next question is from Lee Zulch from OverCap.
Your line is now open.
Lee Zulch
Good morning. Is the 12/15/25 stock repurchase program still in effect?
Is the $10 million there to buy common shares?
Jim Flynn
I'll defer to Jim Briggs on the timing of that agreement, but in general, the question around repurchasing shares and other strategic alternatives are all on the table in discussions with our board. To answer as I think the underlying question is, the technical question on whether that agreement is...
Jim Briggs
That is still open. Yes.
Jim Flynn
Very helpful.
Lee Zulch
Thank you.
Operator
Thank you. Your next question is from John Power from Redwood Fund.
Your line is now open.
John Power
Good morning. Thank you for your time.
If the stock buyback plan is still open, and your stock is trading for 25% of NAV, why hasn't the board and management actually made any stock repurchases in the open market?
Jim Flynn
Any discussion around stock repurchases or other alternatives also has to reflect a full view of liquidity and maintain liquidity to make sure that we can resolve underperforming assets. Certainly, our current stock price does not reflect what we believe is the fair value of our assets, and it is something that we will continue to discuss with the board around whether we take any action in that regard.
John Power
Any thoughts on how to close that gap?
Jim Flynn
There are several, right? Certainly, you mentioned a stock repurchase would certainly would certainly help.
The the primary way for us to improve book value is to work through assets, and get them resolved off our books and redeployed efficiently. Today, we have, roughly a billion of of assets outstanding, including non-performing loans.
We should be closer to 1.4. That's a significant drag on earnings, not to mention that, a a portion of those assets, are some $300 million in, including REO, are are inefficiently financed or not financed at all.
That is the biggest drag on our earnings, and so working through these assets, to your point, having three resolutions last quarter, we expect to have, several more here over the next quarter or two, and and and really move through that legacy portfolio, which will allow us to which will allow us to, to to move forward, with redeploying that capital efficiently. That's the biggest that's the biggest drag, but along the way, we're going to continue to see if there are, certain other, potential oppor- opportunities to enhance the book value, or the the the trading price of our shares relative to book value.
John Power
Thank you. We appreciate you holding these calls and talking to shareholders and investors.
Thank you.
Jim Flynn
Thank you for your support.
Operator
Thank you. Your next question is from Greg Bennett.
Your line is now open.
Greg Bennett
Hey, good morning. On your supplemental data, when you have closing date for a loan and then you have maturity date, you look at some of these loans that were done in '21, let's say, I take it this is the problem portfolio.
Am I correct that most of these problem loans are the ones that were done in '21 and '22? Would that be correct?
Jim Flynn
That would generally be correct, maybe into early '23, but that is generally the kind of across the industry and our portfolio the time of the most challenged assets, typically valuation issues, meaning they were overvalued to begin with.
Greg Bennett
When we're looking at these in the maturity date, there's some that I'll see that the closing date was '21. How many of these have an extension?
I guess what I'm trying to get at. If you take a loan that was done in '21 and you see that the maturity date is '27 now, that would have been a six-year loan.
Shouldn't there be an asterisk next to that, which tells us that you actually did a loan extension that we could identify maybe these were the weaker loans? Does the maturity date include a loan extension, or is that what their original term was?
Jim Flynn
It would be what the current maturity date is as in the supplemental, and I'll ask the team to step in if I say anything wrong, but most of our bridge loans have a total maturity of five years, usually three years initial term with two one-year extensions, occasionally it's two with three one-year extensions. The outside maturity date is listed as that five-year period.
For any loan that has gone through a modification with an extended maturity date, the maturity date in the supplemental would be listed as the current maturity date. We can provide that data in future supplementals to be clear, but for loans that were done in '21 that have a maturity date of '27, that would be an extension, because we don't have any loans that have an initial maturity beyond six years.
Beyond five years.
Greg Bennett
Okay.
Jim Flynn
I don't know if One time I think Zach or Okay, go ahead, sorry.
Greg Bennett
No, go ahead and finish.
Jim Flynn
I was just going to say, I suspect that someone doesn't have the data right at their fingertips, but we can certainly provide that in the future. If anyone else on the team has that, meaning the number of extensions.
Some have extended to four, too, right? At the end of the three years, and then they get an initial period because of some agreement that they've reached with us on an extension, typically a paydown.
Greg Bennett
Yeah. Do the problem loans have to do with just the management of a property that has finished its remodeling or its construction, or that they're just not managed well, or is it because they're still using a loan to put capital renovation into a property?
Jim Flynn
Any troubled loan, we're generally no longer advancing on in terms of your last question. In terms of management, it's a bit of a mixed bag.
Certainly, in some cases, it's due to management. Most often, it's because sponsors have themselves run out of capital.
That these are not their only properties or only loans, and they just no longer have the capital to commit to the assets that they have, whether in our portfolio or others. What happens when sponsors no longer invest capital, even minor things, is properties deteriorate, which make it harder to rent new units.
I think the answer to your question is, in many cases, it is bad management. It's not necessarily that sponsors don't know how to do it or what to do, it's that they no longer have the resources as they've held on to these assets for an extended period waiting for the market to turn better, the submarket that they're in, thinking places like Houston or San Antonio and those types of markets that have struggled.
They just kind of run out of money and resources. In many cases, it doesn't mean that they don't know what they're doing, it just means that they no longer have capital.
That's a challenging environment where you've had cap rates expand, you've had increases in interest rates, and so that sponsor doesn't have capital to put into the asset. We are trying to work with them to exit the asset, hopefully at our loan proceeds, but at this point in many cases, as we've seen below loan proceeds, and that process is frankly a challenging one with some sponsors who are unwilling to cut their losses, to speak, and move on.
That's something that has accelerated a bit here in 2026, moving toward a resolution, but that is the biggest problem, that sponsors acquired assets at valuation levels that have since declined meaningfully, their expenses have gone up, and their resources have been drained.
Greg Bennett
Going forward, when you do commit to loans, obviously, there's a lack of confidence based on the stock price. I'm wondering, from a management point of view or from ORIX, sponsor, Well, first of all, the commitment going forward that maybe you only invest in two-rated loans, to try to improve, I guess, what the quality of the portfolio is.
I don't know if that would matter or not. Then the other thing is, go ahead.
Jim Flynn
I was going to say, we've certainly evaluated investment criteria and have considered sponsor strength as one of the key components here in terms of common themes among struggling assets. Again, I think the portfolio for multifamily assets across the entire industry, not just LFT's portfolio, has seen significant struggles in assets that were acquired, as you identified, in the '21 to '23 period.
They were acquired at a time of lower interest rates, lower expenses, and lower cap rates. All three of those things have moved meaningfully against those owners, and so we've taken a particularly closer look and identified stronger sponsors on newer assets, those with deeper pockets, more capital, more experience, and those that have not necessarily grown as significantly as many sponsors did during that period.
That is certainly something that we have done, and if you look at our portfolio that's been invested since that period, it's performed quite well.
Greg Bennett
One thought I have, and I don't know if this is available or not, but part of the reason for investing in your company had to have been the relationship with Lument and then the parent company, ORIX. I don't know, this would be self-serving, but since the insiders own roughly, if you think about it, the insiders own roughly 45% of this company, the publicly traded company with ORIX, I guess, the largest shareholder, if there's some way to build investor confidence back in the price of ORIX or the sponsor basically, I don't know how you would do it, but taking back these assets for a preferred stock in the company, and allow the parent company to work this out.
They're the ones who put these loans on. They were the ones that you didn't buy these from a broker.
Part of the appeal of investing in this is that you weren't relying on third parties to bring you these deals. These were all underwritten and done in-house by the parent company, which we pay a management fee.
That might be a crazy idea, but closing the discount is not going to happen until we see the tide turning, and the way to turn the tide faster would be to, I think, eliminate the lack of confidence. We're a smaller group now, and with the reverse split, we're going to be even smaller.
Is that possible to do that?
Jim Flynn
Is it possible? I'm sure it's possible, but in terms of looking at the portfolio and finding ways for whether through our parent or other investors to find ways to basically, what I would say is to kind of box that risk or move that risk of those what is now a shrinking part of the portfolio, but still having a meaningful impact on our earnings, both, again, as I said, in losses and from effectively and efficiently deploying capital, what you describe, minus I won't say the parent is committing to doing anything like that, but the idea of trying to box that risk into a portfolio of loans that could be set aside and work through is something that we certainly have been and are evaluating, and to the extent we can figure something out that's accretive to the shareholders, we certainly would like to do so and we'll explore that opportunity as we move forward here.
I think your question and your thought is a good one, and there are opportunities we're looking at with investors about ways that we could possibly do that. Or something like that, I should say.
Greg Bennett
Yeah. In your comments, you framed that the outlook is starting to look more positive for some of these problem loans.
I see the San Antonio property paid off $11 million, whatever, you have that. Now you're down to what, $50 million of real estate owned or I don't have a sense necessarily that real estate owned or problem assets is necessarily getting better.
Is that you indicate
Jim Flynn
What's happening, what's starting to turn, again, we're looking at markets that have not seen good news for several years that we're seeing occupancy increasing, vacancy declining, absorption increasing, limited supply contracting or being limited, right? Those dynamics are starting to happen in markets that haven't seen that for years.
To clarify maybe my remarks, what we're starting to see is some positive momentum in markets that have struggled for years in rental growth, occupancy, vacancy, and deal momentum, right? We're starting to see a few deals get done.
What we've seen for a couple of years now is assets go under contract or at least initial LOIs for sale, these are performing and non-performing, and those sales fall through for whatever reason, usually something in diligence comes up or the market just moves against, and the buyer walks away. What we've seen in a couple of instances, including this quarter, is that we got to a resolution.
It's not positive relative to the original loan amount, but it's positive to move the asset off our books, to recapture that liquidity, and to be able to redeploy it into performing assets. To be clear, it's more about resolving, right?
Having these assets continue to remain on the books and linger is a drag at any value.
Greg Bennett
'Optimistic'
Jim Flynn
is the wrong word, but there are signs in these markets that we could see some deal momentum. Now, I would also offer that we're not the only lender that are trying to sell or dispose of assets in these markets, and so that has put some pressure on, going back quarters now, but even as we go forward, we'll continue to see other lenders kind of having the same experience, which means we might see some struggling or distressed assets coming to market from several lenders in the same places.
That would be the only caveat. To be clear, I'm not suggesting that these are complete turnaround stories.
It's just relative to where we are, we're starting to see some aspects change.
Greg Bennett
Okay. Hey, one other comment for trying to build the investor confidence: Is there any way of these loans that are underwritten by the parent, is there any provision in there going forward, these aren't bought from brokers, you guys are underwriting it, where the trust has a put provision, that if we don't like the way this is turning out, we do have the ability to put some of these loans back to the parent, or that would be something that would
Jim Flynn
The the loans are underwritten by by Lument, which was owned by ORIX, and and we underwrite the loans, obviously. I don't I don't think I don't think that that is a a market provision.
I don't I don't, having a put right back to the manager when a loan goes bad would be would be a challenge to to get, our parent or probably any parent to agree to, but, certainly evaluating when assets have gone bad, how we can revise underwriting standards or look at assets differently, we'll continue to do. And, as I said earlier, we will continue to explore all opportunities and options to, speedily move these resolutions off the balance sheet, with the help of existing and/or new investors.
We have, we have not found a opportunity to to date that has been something that we feel would be accretive, to shareholder value. Hopefully, we can do so here, in the in the in the coming quarters, but we haven't been able to as of as of yet.
Greg Bennett
Okay. One other question: distributable loss, I'm not familiar with that term.
What does that mean to a shareholder in a company, the terminology 'distributable loss'? It sounds like free cash flow, but that's something when you get your year-end taxes, 1099, that that's considered a loss?
Do you know for individual investors what that might mean?
Jim Flynn
The distributable loss and, yeah, I'm not a tax expert, but distributable loss is a GAAP concept and it's not a tax concept.
Greg Bennett
That's fine. All right, that's good.
Jim Flynn
Are you there?
Greg Bennett
Yeah. Yeah.
Thank you for having the call. Hopefully, I guess I'm getting off this call and I'm not sensing that necessarily the tide is necessarily turning, but I guess we'll see in the next couple quarters.
Jim Flynn
Yes. Thank you, and certainly appreciate your support.
Operator
Thank you. Your next question is from Martin Brody.
Your line is now open.
Martin Brody
Hi, good morning. The last caller asked many questions I was going to ask.
I'm a long-suffering shareholder, too. I go back to several name changes.
Hunt Companies, I think it was originally. In June, in the middle of June, June the 25th, June the 15th, the quarter was almost over, and you declare a second-quarter dividend of 4 cents, which thrilled me at the time, but it sort of misled me a little bit, because I was assuming if you're paying 4 cents, then at least you had some positive income, or earnings available for distribution.
Can you tell me why you did that when the, as I said, the quarter was almost over, you clearly knew the state of income, expenses at that point?
Jim Flynn
Whenever we discuss the dividend, we share with our board and discuss with the board, the current projections for the quarter and for the year, and for, frankly, the future. Based on the projections at the time, we felt that 4-cent dividend was appropriate for the quarter based on where we expected things to be.
A few of the resolutions resulted in bigger losses upon ultimate sale or payoff than we were expecting, and as we go through the dividend discussion in our next quarter with the board, we'll evaluate the current projections for this quarter and for the next several quarters, and go through the same discussion we do each quarter. It's a quarterly discussion based on not just that quarter, but the year's anticipated and expected returns.
Martin Brody
Okay. The next question is this is probably impossible, but you have an outside manager of which you pay a considerable fee to, and I understand that, but that is taking a larger and larger percentage of income.
Is it possible to internalize management?
Jim Flynn
I'm sorry. I missed the last part.
Martin Brody
Internalize management.
Jim Flynn
To lower the fee?
Martin Brody
No,
Jim Flynn
well,
Martin Brody
both, actually. Thanks for bringing that up.
Lower the fee and internalize management. Both ways would save money, of course.
Jim Flynn
Yeah. I don't think that that is likely, but what I would point out, I think internalizing management would actually increase fees.
There's a cap on reimbursable fees and expenses that a standalone public company of this size would likely go beyond. There's currently no plans to internalize the manager.
Martin Brody
Okay. Not quite sure.
Seems like a fairly simple business. Maybe I'm wrong.
One last question has to do with stock trades. At the end of June, I think it was the day before they went ex-dividend, there was a 5 million share print at the end of the day, which is, as massive.
In fact, a year ago, approximately the same time, there was also 5 million share print. I was surprised that there was no reporting of this.
Can you shed any light on that? I'm sure you're aware of it in time.
Jim Briggs
I can answer that, Jim.
Jim Flynn
Go ahead.
Jim Briggs
LFT, a year ago, a little over a year ago at this point, as you point out, there was a big print at the end of June. LFT had been added to the FTSE Russell 3000.
What you saw a year ago and change and what you saw this past June was the effects of any activity from that rebalancing and index funds that were indexing to that Russell 3000 that we were in. That explains that big print, June of '25 when LFT was added and when LFT was pulled out, that became effective at the close of business on that date, and you saw the big print.
There was a lot of activity on that day as well. Oh,
Martin Brody
okay, great. That answers that question.
I had no idea they were removed. Okay.
Thanks very much. Good luck with the future.
Jim Flynn
Thank you.
Operator
Thank you. There are no further questions at this time.
Please proceed with the closing remarks.
Jim Flynn
I want to thank our investors for joining today. Again, for your patience, appreciate the questions and feedback and support.
We will continue to work to improve the earnings profile and with intents to increase our trading price relative to book value. Thank you all, and we'll speak next quarter.
Operator
Ladies and gentlemen, the conference has now ended. Thank you all for joining.
You may now disconnect your lines.