RBC Bearings Incorporated
Q2 FY2027 · Earnings Call TranscriptOctober 30, 2026
Josh Carroll
Good morning, and thank you for joining us for RBC Bearings fiscal second quarter 2027 earnings call. I'm Josh Carroll with the Investor Relations team.
With me on today's call are Dr. Hartnett, Chairman, President, and Chief Executive Officer; Daniel Bergeron, Director, Vice President, and Chief Operating Officer; and Rob Sullivan, Vice President and Chief Financial Officer.
As a reminder, some of the statements made today may be forward-looking and under the Private Securities Litigation Reform Act of 1995. Actual results may differ materially from those projected or implied due to a variety of factors.
We refer you to RBC Bearings' recent filings with the SEC for a more detailed discussion of the risks that could impact the company's future operating results and financial condition. These factors are also listed in the press release, along with a reconciliation between GAAP and non-GAAP financial information.
With all that said, I'll now turn the call over to Dr. Hartnett.
Mike Hartnett
Thank you, Josh, and good morning to everyone, and thank you for joining us. Again, as normal, I'll begin today's call with a brief review of our second quarter results, then discuss some trends that we are seeing across the end markets, before turning the call over to Rob, who will provide additional details.
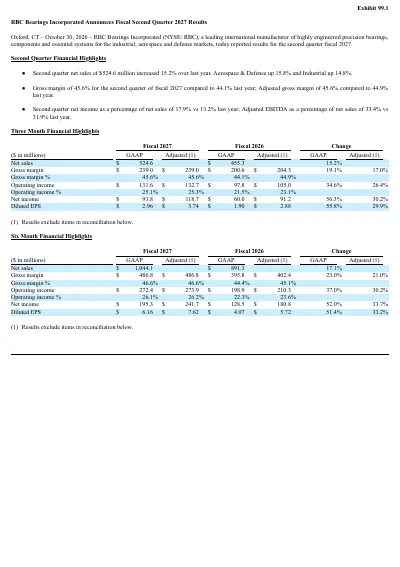
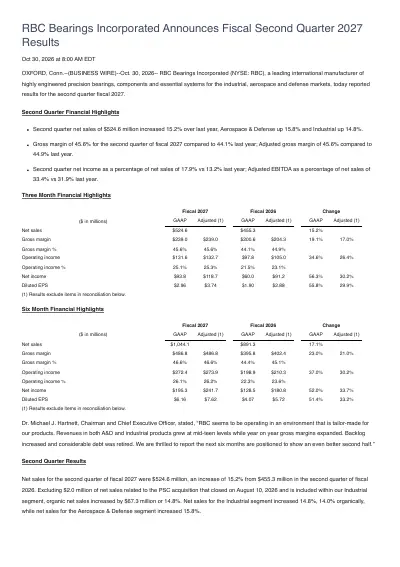
We delivered a strong second quarter, with net sales increasing 15.2% year-over-year to $524.6 million. This was driven by continued demand in our aerospace and defense environment and a 14.8% growth from our industrial business.
Consolidated gross margin for the quarter was 45.6%. Adjusted EPS increased 29.9% year-over-year to $3.74, compared to $2.84 in the prior year.
Adjusted EBITDA rose 20.4% to $175 million, versus $145.3 million last year. That's 33.4% of revenues.
Free cash flow remained strong at $85.2 million, and that was net of a $24 million acquisition, and we retired $96 million of debt during the period. Turning now to our two business segments, approximately 56% of our revenue during the quarter came from our industrial segment.
A&D, aerospace and defense, which was 44% of sales, continues to expand. Segment revenue increased 15.8%.
The components were: commercial aerospace was up 17.4%, defense 13.6%. Both were constrained by production capacity, which is easing as new equipment comes online.
Across the A&D business, including space, we are seeing record order activity, increasing inquiries, customer requests for accelerated deliveries, and long-term commitments. On space, this sector continues to shine.
In the first half, revenues expanded 78%, showing a continuous demand for components from an ever-expanding stream of new and old customers. Of course, this business is still in the early stages of maturity, and we recognize the long-term growth prospects it represents to RBC, and are planning future expansions accordingly.
On marine, we continue to boost production of components for submarines, and are working to triple our output on these products from our baseline. We are now about 30% complete, 70% to go to reach our goal.
We are planning continued expansions through FY28. Turning now to our industrial business, performance remained strong during the period, with OEM revenues increasing 24.2% and distribution revenues increasing 10.6%.
Overall, the sector was up 14.8%. During the quarter, we saw growth across aggregates, metals, food and beverage, warehousing, semiconductors, grain, and power generation.
No significant contraction was seen in any of the core industrial markets. Overall, we remain invigorated by the strength, breadth, and outlook for the total RBC business.
To the RBC team listening today, thank you for always going the extra mile in support of our customers. We believe and continue to believe our differentiators that make the difference are outstanding service levels, strong brands, unique certified products, leading market positions, technical expertise, and most of all, our dedicated employees.
With that, I'll turn over the call to Rob, who will walk us through the financials.
Rob Sullivan
Thank you, Mike. We delivered another strong quarter ahead of our expectations, with net sales growing 15.2%, which led to a 19.1% increase in our reported gross margin.
Gross margins of 45.6% on both a reported and adjusted basis, compared to 44.1% reported and 44.9% adjusted in the same period last year. The gross margins this quarter reflect the benefits of increased volumes running through our production facilities, along with the impacts of contract renewals and favorable mix.
Second quarter A&D sales increased 15.8% year-over-year. Net sales from our industrial business increased 14.8% during the period, or approximately 14% excluding $2 million of sales from PSE, which was acquired in August.
A&D reported gross margins during the quarter were 42.2%, and industrial margins were 48.2%, compared to 38.7% and 48.2% in the prior-year period, respectively. On the SG&A line, we had total costs of $83.4 million, or 15.9% of net sales for the quarter.
This ultimately resulted in an adjusted EBITDA of $175 million, or 33.4% of net sales for the quarter. That represents a 20.4% increase in adjusted EBITDA dollars during the quarter compared to the same period last year.
Interest expense for the quarter was $9.3 million. This was down 30.6% year-over-year, reflecting the improved leverage position achieved over the last 12 months, coupled with lower interest rates.
We paid off $96 million of debt during the quarter, which included repaying the remaining balance of our term loan ahead of the November 2026 target we set a year ago. The tax rate in our adjusted EPS calculation was 22.2%, compared to last year's 22.0%.
This led to an adjusted diluted earnings per share of $3.74, representing growth of 29.9% year-over-year. Free cash flow in the quarter came in at $85.7 million, with conversion of 91.4% of net income, compared to $71.7 million and 119.5% last year.
Conversion through six months stands at approximately 119% of net income. Our strong balance sheet and improved financial flexibility provides us opportunities to pursue a balanced capital allocation strategy as we continue to deleverage.
Looking into the third quarter of fiscal 2027, we are guiding revenues of $520 million to $525 million, representing year-over-year growth of 12.7% to 13.7%. On a nine-month basis, that would mean sales of $1.564 billion to $1.569 billion, representing growth of 15.6% to 16% year-over-year.
The outlook reflects the normal seasonal impact of the holiday period on our third quarter. Adjusted gross margins in the next quarter are expected to be in the range of 45.5% to 45.75%, and SG&A as a percentage of net sales is expected to be in the range of 16.25% to 16.5%.
With that, operator, please open the call for Q&A.
Operator
Thank you. We will now be conducting a question-and-answer session.
If you would like to be placed into the question queue, please press star one on your telephone keypad. You may press star two if you would like to remove your question from the queue.
We ask you please ask one question, one follow-up, then return to the queue. Our first question is coming from Jason Holcomb from Morgan Stanley.
Your line is now live.
Jason Holcomb
Hey, Mike, Dan, and Rob.
Mike Hartnett
Mike,
Jason Holcomb
Mike, in the press release you noted that you expect the second half of the fiscal year to be better than the first half. Can you maybe provide more detail on that comment, and provide some context on what you're expecting for growth in the second half for industrials and aerospace and defense?
Also it'd be great if you can maybe comment on any notable differences in expected growth dynamics between commercial aero and defense.
Mike Hartnett
I'm just making notes of your question, Jason, hang on. Sure.
It's easy to explain. The easiest component of the expansion in the second half is we got an extra week in there.
The way our accounting calendar works, it gives us an extra week. That explains some of it.
I think what's more relevant here, though, the efforts that we've put in over the past several years, and the capital that we've put in over the past several years, will now show in these quarters. It'll show more in the fourth quarter than the third quarter, for reasons which I'll explain.
We've added capacity. We have the machinery.
We've trained the people. We've did the logistics behind the supply chain, and that effort is going to produce dividends for us in the next six months.
Behind that, we're behind our plan for the year on marine production. We're just not producing what we planned to produce.
We've had some difficulties in the supply chain. Those difficulties have required us to insource some processes that are somewhat complex, but manageable.
We expect to do some significant catch-up, particularly in the fourth quarter of our year, on our marine plan. That's another element that's important to us.
On the third quarter, third quarter is always a tricky quarter for us because it's a short quarter, everybody knows there's plenty of holidays. I think what people don't feel is a lot of our business goes to either the government or A&D customers that have market caps in excess of $100 billion.
I won't name any names, but you know the names. They seem to use a lot of December in terms of holidays and vacation time.
A lot of our products that have to be shipped are shipped in accordance with a release that has to come from them with regard to certifications for quality and logistics. We're depending upon them in many cases for these certifications.
In this particular year, there seems to be more of that than normal. Some of that might roll into the fourth quarter, and some might not.
It's really hard to tell. That's the basis of our third quarter forecast right there.
Let's see. I think when we look at the aerospace and defense side, I suspect if we can get the marine up and on its feet, then I think we're certainly going to be north of 15% on the A&D side of the business, maybe hovering closer to 20.
On the industrial side, very, very GDP dependent, and so I think we're always sort of budgeting a high-single-digits expansion on the industrial side of the business, because we're not great forecasters of what the GDP is going to be out six months. If you know somebody that is, please introduce us to him.
Jason Holcomb
Thanks, Mike. Maybe just as a quick follow-up.
I guess, in your comment on the logistical sign-offs for kind of calendar 4Q, I guess, is that more directly related to the insourcing with some of the things you're doing in marine, or is that a separate comment that maybe is about maybe market share that you're winning on other programs? Maybe just a little extra on that would be helpful.
Mike Hartnett
No, actually marine seems to be a little bit independent of that, but it's usually aerospace, defense, maybe a little bit space. I think space is in there, too.
That's a little bit more administrative. There's more administrative releases on the defense side.
Jason Holcomb
Got you. Then maybe just one last quick one is just you mentioned on marine kind of tripling output from the baseline for that business.
I guess do you have a sense of how long you think it would take to achieve that?
Mike Hartnett
I think once we put the insourcing project to bed, and I hope we have all the linen in the pillows, and that's imminent. I think we'll probably be past 70% next year, and be in FY28, and we'll round that off in FY29.
Jason Holcomb
Got it. Thank you very much, guys.
I'll hop back in the queue.
Operator
Thank you. Next question is coming from Steve Barger from KeyBanc Capital Markets.
Your line is now live.
Steve Barger
Hey, good morning, guys. Mike,
Mike Hartnett
Good morning, Steve.
Steve Barger
Good to talk to you. First question's on defense, on missiles and munitions.
How much of what you're seeing today is just for replenishment of depleted inventories versus a structural increase in production rates, and what's your visibility like there?
Mike Hartnett
It's certainly the programs that we've been on are programs like the Tomahawk, the GMLRS, the Standard Missile, and the hypersonic missile / Zumwalt program. We've been pretty well much steady-state manufacturing product for those systems as is normal.
Certainly build rate for those systems is stepped up substantially. We're going to see a substantial stepping up in that next year.
Or maybe some of that in the fourth quarter. It's hard to predict.
If you look at the Tomahawk, it's no secret that Tomahawks have been built at 200 a year kind of rate. They now are going to 1,000 a year kind of rate.
We produce several fuel system components for the Tomahawk missile, which are critical to the missile. We're actually in the process now of laying out floor space to bring up those production rates in accordance with that kind of demand.
GMLRS is something that we're well-tooled on, and I think there's a 40% or a 20%, I don't remember the trailing numbers, but it's at least a 20% step-up in volume, and we're tooled, and we won't have any trouble meeting that step-up. The hypersonic Zumwalt program is a big one for us, and we're kind of in the middle of that.
That hypersonic is going through its testing, and once testing is completed, we'll be released for manufacturing. I think we're probably 18 months away from that release.
Steve Barger
I know your submarine programs are the biggest part of defense. How big is missiles and munitions as a percentage of defense revenue for you?
Mike Hartnett
Good question. Rob, how big is this [laughs]?
Rob Sullivan
I think it's running in the range of $50 million a year right now.
Mike Hartnett
Yeah.
Steve Barger
Got it. Okay.
Then one follow-up on industrial. In your prepared remarks, you noted a lot of positive end markets.
We're hearing the same from other companies. Can you talk about what you're seeing from the more traditionally cyclical OEM markets, to the extent that you have exposure?
I'm just trying to get the sense of whether we'll see an equipment CapEx cycle beyond the pickup in aftermarket and distribution that's already taken place.
Mike Hartnett
Certainly our most cyclical OEM end market in industrial is oil and gas. With what's going on in the world, there's a renewal there.
We're seeing a pickup there.
Steve Barger
Got it. You don't have much machinery, like traditional machinery exposure, right?
Mike Hartnett
We have it, it's not material.
Steve Barger
Okay. All right, thanks.
I'll get back in line.
Operator
Thank you. Next question is coming from Michael Ciarmoli from Guggenheim Securities.
Your line is now live.
Michael Ciarmoli
Hey, good morning, guys. Thanks for taking the question.
Nice results. Maybe, Mike, I know the answer to this, but I'll answer it anyway.
Just given kind of the demand coming from marine, missiles, all things aerospace and defense, are you seeing any risk to your businesses of being second sourced at all as the industry in general is broadly looking for more capacity?
Mike Hartnett
I think the overall answer to that is no. We hear a lot of talk about bringing on second sources for certain positions.
That talk usually is directed at us to be the second source, [laughs] so.
Michael Ciarmoli
Right.
Mike Hartnett
We do take a lot of pride in service levels. A bearing is a very small part of an airframe.
I guess if you look at a 737 and you look at the discounted selling price of a 737, it's probably $60, $70 million, and our content is $200,000. If you don't create the problem, if you're not the problem, they won't be looking for a solution, because they have other problems to solve.
Our whole theory in life here is, don't be the problem. [laughter]
Michael Ciarmoli
Right. That's always good advice.
What about just on the capacity constraints you talked about in marine? Can you quantify that in terms of revenue, and even that area, I guess maybe honing in specifically, was that more on the legacy RBC, was it more on the VACCO side, any additional color there?
Mike Hartnett
It's more legacy RBC. VACCO is got the same charge is tripling their production, and they seem to be more able to do that, because their designs are different than Sargent's designs, completely.
The problem is in Tucson, and so we kind of work on that every day, trying to bring solutions to what they need. Fortunately, the requirements that they have, which are technically somewhat sophisticated from a metallurgical standpoint, were equipped in other plants, RBC plants, to manufacture those items.
We're in the process of retooling some of those RBC plants today to bring their manufacturing rate of those products consistent with Sargent's needs. That's why, it's a timing thing at this point.
I'm reasonably sure that we're going to feel the effects of that in the fourth quarter.
Michael Ciarmoli
Okay. Then just last one for me.
Rob, do you have the aerospace OEM growth rate in the quarter, and maybe just kind of what you're seeing there in terms of kind of from Boeing, from Airbus, from the engine OEMs? Are you kind of in line with their rates, or are you looking into next year to where they want to get to in rates across the narrowbodies and widebodies?
Rob Sullivan
Let me give you the numbers. Total commercial OEM was $114.9 million this quarter.
Michael Ciarmoli
Yep.
Rob Sullivan
Distribution was 21.5.
Michael Ciarmoli
Got it. Just so you have it,
Rob Sullivan
defense was 67.5 on the OEM side and 26.4 on the distribution side.
Michael Ciarmoli
We're
Rob Sullivan
certainly seeing sequential growth in the OEM side consistently as we've been ramping up, and that's certainly driving a lot of it.
Michael Ciarmoli
Got it. Perfect.
Thanks, guys.
Operator
Thank you. Next question is coming from Scott Deuschle from Deutsche Bank.
Your line is now live.
Scott Deuschle
Hi, good morning. Rob, was the sequential backlog increase related to marine, or was that something else?
Rob Sullivan
It's mostly aerospace, as you can imagine. Some of it was out of VACCO, some of it out of Sargent, marine, and then just some other aerospace contracts flowing through.
Scott Deuschle
Okay. Then Mike or Rob, you mentioned 78% growth in the space business in the first half.
Can you share a rough split of that between organic and inorganic from VACCO?
Rob Sullivan
I'd say that VACCO certainly makes up a large portion of that when you look at it. Even if you look this quarter, Q2 versus quarter two last year, it's still up a few million bucks on an organic basis.
Scott Deuschle
Okay. Then, Mike, if an aerospace OEM were to add RBC as a second source of supply on an existing product that's currently sole sourced to someone else, and then you sign that contract say this quarter, how long would it take for that to begin to ship to that customer and then show up in your results?
Is it a year, or longer, or shorter?
Mike Hartnett
It depends upon if it's a standard product that we're already producing, we would probably give them a lead time kind of delivery, and just phase it in. The lead time would be, depending upon product line, but at this point it could be 50 weeks.
Scott Deuschle
Okay. Then last question for me, just on that earlier point about capacity.
What are the primary machine tools that you use to produce aerospace bearings? Then how long does it take to get those tools if you order them now?
Mike Hartnett
The primary machine tools, if you can get the material. [chuckles] The material is also a problem, but you have to be way ahead of the game on the material side.
The primary material machine tools are turning and cutting machines, and those are made by Mori Seiki and people like that. Then the next step in the process would be heat treating.
Usually there's the turning machines lead time six months. The heat treating equipment lead time, depending upon the type of heat treating you want to do, is a year to 18 months.
Then there's finishing equipment, and we use 15 months planning to get it on our floor and get it operational. Sometimes it's a little quicker than that, but not very much.
There's several different finishing operations that have that kind of lead time. You might have a grinding operation, and then you might have a polishing operation and stoning operation.
Both of those machine sets have that kind of lead time. That's sort of the major machine tools.
At the same time, you need operators, and folks that can deal with that level of complexity on the floor that can run these machines. Simultaneously, you have to be training those people, and as you train those people, you usually have a drop back in plant efficiency, because you have a lot of people in training, and not a lot of people in making.
Your paid hour versus your earned hour is diluted. Your earned hour is diluted.
That's sort of the manufacturing equation for bearings right there.
Scott Deuschle
Okay. Then I guess as you look forward, do you see the constraint on growth as being continuing to be focused on tooling capacity and your ability to bring that in, or does it start to shift more toward labor as you get into next year?
Mike Hartnett
I think we're okay from labor standpoint. We're not perfect, but it's a fringe item at this point because of some of the approvals that we've recently gotten for our plants in Mexico, where there's plenty of labor and plenty of labor availability, and plenty of machine tool capacity.
I think the major component here is going to be continuing to cycle in advanced machine tool systems to upgrade those systems that we have on the floor to improve throughput and efficiencies.
Scott Deuschle
Thank you very much.
Operator
Thank you. Next question is coming from Pete Skibitski from Alembic Global.
Your line is now live.
Pete Skibitski
Hey, good morning, guys. Nice quarter.
Mike Hartnett
Morning, Pete.
Rob Sullivan
Hey, Pete.
Pete Skibitski
Hey, Mike, can you update us on where you're at, especially at Boeing, on production rates, just because they've obviously had some trouble stabilizing here at 47 a month on the MAX, and trying to get to 10 on the 787? I know it differs by plant, but maybe you can give us kind of an average of where you think you produced at this quarter?
Mike Hartnett
Yeah. I think [clears throat] I trying to think of the last meeting I had on that two weeks ago, and I think they were clocking it at about 42 to 45.
It's a little disproportionate because we're getting business volume from previous suppliers of Boeing who have sort of exited the supply chain, to say it nicely. That's a little bit disproportionate to their rates, which pushes a couple of our plants to a higher speed limit.
Pete Skibitski
Right. Organically, it's almost like you're in the low 40s organically, if you exclude market share gains.
Mike Hartnett
Right. I think that's fair.
Pete Skibitski
Okay. Sounds good.
Then, just one more, just one maybe for for Rob. Rob, one of the, better SG&A spend quarter quarters you guys have had in probably three or four years, I I guess.
You're looking like a bit of an uptick here in the third quarter, but, how do we Was there any kind of unusual one-time lower spend levels this quarter, or, are are we able to maybe see a pronounced downward trend over the next few years? Maybe just update us on kind of what you're seeing SG&A wise.
Rob Sullivan
I think we're seeing more just the leverage of the increase in sales over time. Obviously, as certain compensation items run through, you get a little bit of an uptick in dollars moving forward.
We're pretty comfortable right now where we are, and we're pretty pleased to see the leverage on the increased sales compared to where we were a year ago. We were closer to 17%.
It's just kind of continuation of the discipline that we've been trying to put in place.
Pete Skibitski
Okay. Great, thanks, guys.
Rob Sullivan
Just to add to that quickly, the uptick in the next quarter is largely centered around stock comp, which I think is going to be up probably $1.5 million next quarter. That's driving us closer to that forecasted rate.
Pete Skibitski
Okay. That's like a first quarter, third quarter thing, typically?
Rob Sullivan
It's just the timing, and so I think that Q2 was up from Q1 on stock comp, Q3 is a little bit up from Q2.
Pete Skibitski
Got it. Thank you.
Rob Sullivan
Thanks.
Operator
Thank you. Next question is coming from Tim Thein from Raymond James.
Your line is now live.
Tim Thein
Hey, thank you. Good morning.
First question's just on industrial. I think you said nearly 11% growth on the distribution side in the quarter.
If you have a look at the results of some of the public suppliers there, they're not growing at nearly that rate. I'm just curious if maybe you could add some context there, and obviously they're getting a bit of pricing.
Just curious, are you seeing any signs of inventory build from some of the customers, or maybe gaining some share, or a combination of that? Anyway, just a bit of context in terms of what you're seeing on that side of the industrial house, and whether you think that's the sustainability, I guess, of that.
Thank you.
Daniel Bergeron
I think one of our advantages there, Tim, is that if we kind of use Dodge as the proxy on the industrial side of our business, their product availability across their line items, and they have thousands of line items, 97% of the time, 95% of the time, 96% of the time, when a customer needs that product, it's in stock. Their service levels are extraordinarily high.
This is an aftermarket kind of thing, that somebody needs the part because there's a part that failed in somebody's machine someplace that they need right away, and we have it in stock, and so they buy it from us. I think our service rates are industry leading, and I think that brings a lot of revenue into Dodge.
RBC, the balance of RBC's industrial business, sort of runs the same plan.
Tim Thein
Understood. Okay.
Then maybe one for Rob, just how to think about some of the cost items here as we think about what that picture looks like today versus 90 days ago. Just how you're thinking about this, I guess more the gross margin level, the impact of the potential inflationary headwinds, how that's changed, if at all, in terms of how you're thinking about the back half of the year, just given changes in freight and logistics, et cetera.
How impactful is that? Thank you.
Rob Sullivan
That's a fair question. I think we've been running this inflation race for a few years now, trying to stay ahead of it, and I think we've done a pretty effective job across the board.
I think last quarter, we increased our outlook for the year from 50 basis points to 100 basis points of margin expansion for the full year. I think we still feel good that that 100 basis points is very very achievable.
We certainly keep very close eye on the cost pressures as they come on, and we're constantly making sure we're making adjustments where we can to stay in front of it.
Tim Thein
Okay. Thank you, guys.
Operator
Thank you. Next question is coming from Ronald Epstein from Bank of America.
Your line is now live.
Andrew Steinman
Hi, good morning. This is Andrew Steinman on for Ron.
I just wanted to ask about the capital allocation strategy here given the comments on the supply chain, and particularly in marine. Are you guys looking at M&A opportunities where you could potentially vertically integrate areas of weakness in the supply chain?
Any color there would be appreciated.
Daniel Bergeron
Yeah. Hi, it's Dan.
Of course, we're always taking a look to see if there's an opportunity to insource it, but it's not the main focus of our M&A strategy. I think we're out looking, Rob and I, like always.
RBC, we've been doing this for over 23 years and have completed over 27 acquisitions, we continue to do that. Rob's job is to get the balance sheet in shape and delever it so we're in a good position to participate in any transactions that come by, and so him and his team have done a great job getting that leverage down under one, and we'll continue to do that and continue to delever, and we'll continue to look for deals to get done.
The three legs of the stool, right? Pay down that debt, invest in organic growth, and continue to look for M&A.
Andrew Steinman
Just a quick follow-up. Are there any particular categories in the marketplace that appear attractive as a bolt-on acquisition?
Daniel Bergeron
We like deals that bring new products and technology that we can bring over our current customer base to better leverage our position in our market with our customers. We like defense assets, we like aerospace assets, and we like industrial assets.
Andrew Steinman
All righty, thank you.
Operator
Thank you. Next question is a follow-up from Scott Deuschle from Deutsche Bank.
Your line is now live.
Scott Deuschle
Sorry if I missed it, Rob, but were there any end markets in the industrial business that batted well above their weight in terms of driving this growth, particularly on the OEM side? Or was that growth pretty balanced across the different end markets?
Rob Sullivan
You're saying OEM specifically?
Scott Deuschle
Or you can broaden it out as well.
Rob Sullivan
Yeah. Mining and metals did really well this quarter, and then semiconductor, while it's small, it was mighty, and it was up significantly this quarter as well on the OEM side.
Really, broad-based expansion across so many end markets there.
Scott Deuschle
As
Daniel Bergeron
a reminder, Scott, our OEM business was up 24.6%. [laughter]
Scott Deuschle
Right. Yeah.
Then is there much of a margin benefit that also hits for the aerospace and defense business when you hit this marine unlock at the end of the year, or is it more of just a revenue tailwind?
Rob Sullivan
There's definitely a margin benefit. We've been feeling some pinch on the margins, I think, with some of the headwinds in the marine business.
I think that there's definitely opportunities there as we work through and ramp up.
Scott Deuschle
Can you quantify that pinch at all, as a couple million dollars a quarter, or something like that?
Rob Sullivan
For their business, I think it's, past quarters, 5 or 6 points on that business, it's, yeah, it's impactful. The aerospace margins, that was one pinch.
The other side of it again is that Q1 and Q4 just notably have the most production days and tend to be our strongest operating quarters. Q2 has fewer production days, you feel a little bit of that seasonality pinch in the efficiency.
So.
Scott Deuschle
Thank you.
Operator
Thank you. We have reached the end of our question-and-answer session.
I'd like to turn the floor back over for any further closing comments.
Daniel Bergeron
Questions this morning hopefully gave you a good understanding of [clears throat] the positive outlook that we have and we feel about the business. Look forward to talking to you, probably in late January, early February.
Operator
Thank you. That does conclude today's teleconference.
You may disconnect your line at this time, and have a wonderful day. We thank you for your participation today.