BRC Group Holdings, Inc.
Q1 FY2026 · Earnings Call TranscriptMay 7, 2026
Operator
Good day, and welcome to the BRC Group Holdings, Inc. first quarter 2026 earnings call.
My name is Isabelle, and I will be your EverCall moderator. The format of the call includes prepared remarks from the company, followed by a question and answer session.
Please note that all attendees will be on a listen-only mode until the Q&A portion of the call. At this time, I will turn the call over to Bryant Riley, co-CEO of B.
Riley. You may now begin.
Bryant Riley
Good afternoon, and thanks for joining our call. I want to start by saying how enthusiastic our entire team is by where our firm sits today.
The deliberate steps we've taken to strengthen our balance sheet and align our core operating platform have positioned us well to capture the current market opportunity. That conviction is reflected in our momentum, which carried over from 2025 into our first quarter.
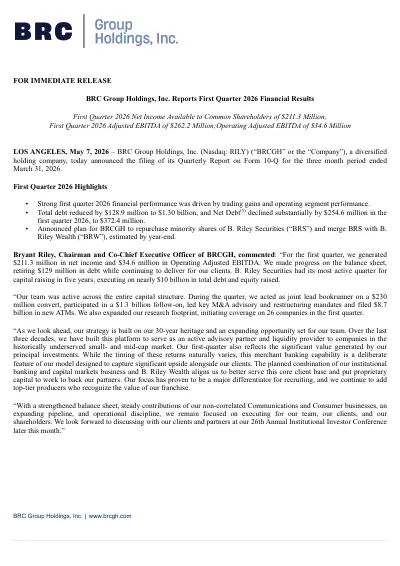
For the first quarter, we generated net income available to common shareholders of $211.3 million and adjusted EBITDA of $262.2 million. Operating adjusted EBITDA was $34.6 million, up close to 40% sequentially.
Net debt stands at $372 million, down approximately $255 million from year-end. Our CFO Scott Yessner will walk through the financials in detail.
My remarks today focus on three pillars: our first-quarter execution, our strategic path forward, and our ongoing commitment to our core franchise. During the quarter, our team executed against two key priorities: strengthening our balance sheet and delivering for our clients.
On the balance sheet, we continue to optimize our capital structure. In March, we fully redeemed our 5.5% senior notes due 2026.
We also retired $40.4 million of debt through bond-for-equity exchanges and open market repurchases through the end of March. Altogether, total debt is down $129 million in the quarter, and we expect that trend to continue.
While we enjoyed a solid quarter across the entire platform, B. Riley Securities delivered our most active quarter for capital raising in five years.
During the quarter, we executed on nearly $10 billion in total debt and equity raises for clients. We acted as joint lead bookrunner on Lightbridge's $250 million convert, participated in a VSEC $1.3 million follow-on, and were key advisor to Nabors in the TrueCar take-private.
We were active across the entire capital structure. We saw $8.7 billion in new ATMs in the first quarter, including a $6 billion facility for Iron and a $1 billion facility for SMR.
We've also expanded our research footprint, initiating coverage on 26 companies in the first quarter alone. We see deep, expanding opportunity set for our team in the quarters ahead and expect momentum to continue.
Ultimately, our broader strategy remains straightforward: we reinvest operating cash flows into our businesses and compelling market opportunities, with our core franchise serving as a primary engine. Next year marks our 30th anniversary, and over the last three decades, we've intentionally built our business based on a commitment to being an active, dedicated advisory and liquidity partner for companies in the historically underserved small- and mid-cap market.
We have navigated every market cycle. During periods of macro stress, we have stayed committed to this strategy while others have cycled in and out.
This consistency and our commitment to this market have proven to be our structural advantage. That same commitment is why we launched BRC Special Situations Finance to enhance our commitment to small- and mid-cap companies by providing capital and liquidity solutions.
We will continue to leverage our platform and put capital to work to back our clients and our long-term partners. Executing our strategy requires absolute operational discipline and a world-class team.
We're incredibly grateful for our team's hard work and continued dedication to the firm and our clients. I will now turn the call over to co-CEO Tom Kelleher to provide additional context on our operating performance.
Tom?
Tom Kelleher
Thanks, Bryant. In April, we announced our intention to repurchase the outstanding minority stake of B.
Riley Securities and combine B. Riley Securities with B.
Riley Wealth. We are incredibly excited about this.
The proposed transaction streamlines our corporate structure, but more importantly, it intentionally aligns our investment banking, our broad retail and institutional distribution, and our equity research engine. Scott will spend some more time on the numbers, but from an operational standpoint, the platform is continuing to normalize from all the activity that has transpired over the last two years.
Targus continues to stabilize their business, operating at roughly break-even. We are encouraged by recent improvements in distribution channel sales as tariff concerns begin to ease.
Our Communications Group continues to deliver high-margin cash flow by leveraging our team in India. We remain relentlessly focused on efficiency across the entire enterprise.
We are actively deploying AI not just as a corporate efficiency tool, but as a force multiplier across our entire revenue-generating platform. By equipping our bankers, sales force, and research teams with advanced tools to accelerate analysis and insights, we are empowering our teams to scale their output and capture more market opportunity without proportionately increasing our cost structure.
While technology allows us to operate faster and smarter, our core business is fundamentally a relationship business. Our ultimate differentiator remains our people and the partnerships we build.
In two weeks, we will host our 26th Annual Investor Conference at the Ritz-Carlton in Marina del Rey. With approximately 200 companies and 1,000 attendees, this conference remains the clearest expression of who we work with and the partnerships we build.
During the conference, we will once again host our annual Big Fighters, Big Cause charitable boxing gala benefiting the Sugar Ray Leonard Foundation and its mission to knock out pediatric diabetes. We are proud to have raised over $6 million for this cause since inception.
Next week on May 13th, B. Riley Securities is hosting our annual Commissions for Charity Day, where 100% of our equity trading commissions will be donated to Children's Hospital LA.
For nearly three decades, our firm has been defined not just by the deals we execute, but by the relationships we build. While we are incredibly proud of our operational execution this quarter, these events reflect the true character of our firm and our commitment to our clients, our partnerships, and our community.
Our proprietary platform continues to serve as a major differentiator for recruiting, and we are actively leveraging it to add high-impact talent. We are fielding numerous conversations for positions across the company, and just last month, we welcomed back one senior sales trader as well as brought on an institutional salesman new to the firm.
High-performing producers want to be part of a company where deals are actively getting done, where the platform supports them, and where the culture is set by the fellow producers across our management team. With that, I will turn the call over to our CFO Scott Yessner to walk through the detailed financials.
Scott?
Scott Yessner
Thanks, Tom. I'm pleased to share an update on our first-quarter 2026 financial performance, investment holdings, and capital and liquidity.
To start, I would like to walk through our financial performance. Year-over-year first-quarter total revenues were $352 million compared to $186 million.
The increase in total revenues was driven by $161 million of higher trading gains on investments, primarily in Babcock & Wilcox common stock, $130 million of which is related to the value appreciation in the first quarter of 2026. Service and fee income was $152 million for the quarter, lower year-over-year by $6.7 million.
Investment banking and brokerage revenues increased $12 million, offset by lower revenues from exited businesses in the prior year of $10.4 million, lower B. Riley Wealth management revenues of $4.6 million, and lower Communications Business Group revenues of $4.1 million from normal subscriber attrition.
Next, year-over-year first-quarter total operating expenses were $199 million compared to $247.5 million in 2025, a reduction of $48 million. The reduction was primarily due to a combined $28 million of eliminated costs from exited businesses and the Communications Business Group subscriber declines, with the remaining reduction of approximately $20 million from across a range of operating expenses including lower legal fees of $3.7 million.
Despite the lower operating expenses in total and in varying expense lines, accounting fees related to the audit and accounting activities was $4 million higher than 2025, which was also at an elevated level. We have returned to a normal operating calendar, which will allow us to drive infrastructure improvements that we believe will ultimately lower our accounting fees and other elevated costs.
Continuing down the income statement, first-quarter other income excluding interest expense was $106 million, primarily due to a $99 million increase in the Babcock & Wilcox fair value appreciation. The company's total increase in the Babcock & Wilcox investment across trading income and other income for the first quarter in 2026 was $229 million, booked in different revenue lines due to the investment being owned by multiple entities within the BRC Holdings structure.
Year-over-year first-quarter interest expense was $20 million, a decline of $10 million from 2025, driven by lower average borrowing balances from senior note redemptions and other debt reductions. These details culminate with first-quarter 2026 net income attributable to common shareholders of $211 million, diluted income per share of $6.57, compared to a net loss of $12 million, diluted loss per share of 39 cents in the first quarter of 2025.
First-quarter 2026 adjusted EBITDA was $262 million compared to a loss of $45 million in 2025. Please refer to the reconciliation tables in our earnings press release for the adjusted EBITDA calculation.
Next, I'll review our segment operating performance. Please note our former Communications business segment has been separated into four reportable segments, which we aggregate and describe as the Communications Business Group.
The Capital Markets segment, which is comprised solely of B. Riley Securities, had first-quarter 2026 total revenues of $172 million compared to $2 million in 2025, and segment income of $137 million compared to a segment loss of $36 million in 2025.
The revenue and segment income increases were primarily driven by fair value increases in Babcock & Wilcox reported in trading gains. Additionally, core investment banking revenues also increased $9.7 million year-over-year.
Next, the Wealth segment had first-quarter 2026 revenues of $52 million compared to $47 million in 2025, a $5 million increase, and segment income of $16 million compared to $2 million in 2025, a $14 million increase. The revenue and profit increases were driven by an $8.9 million increase in market value of carried interest in a fund that owns SpaceX, for the portion owned by the Wealth segment.
Wealth segment ended the first quarter with $11.9 billion in assets under management and 190 registered representatives. The Communications Business Group is the aggregate results of Lingo, magicJack, Marconi, and YMax reportable segments.
The Communications Business Group had first-quarter aggregate revenues of $60 million compared to $64.5 million in 2025, a $4.5 million decline, and aggregate income in the first quarter of $12.6 million compared to $10.6 million in 2025, a $2 million increase. The first-quarter results are in line with our expectations.
The operating leverage continues to be a core business strength, as demonstrated by the results. Our Targus business, which comprises the Consumer Products segment, had first-quarter revenues of $44 million compared to $42 million in 2025, and operating segment loss of $2.6 million compared to a loss of $5.1 million in 2025.
After a period of declining sales, we are pleased with the revenue increase and the narrowing operating loss, which is due to improving the sales mix margins and lowering operating costs. Next, I'd like to provide an update on the company's investment holdings portfolio, which is reported on our balance sheet in securities and other investments, loans receivable at fair value, and equity investments.
Investments are held across consolidated entities, where valuation changes are primarily booked as revenue in either trading gains and losses or realized and unrealized gains and losses. At March 31st, 2026, securities and other investments increased $193 million to $640 million from December 31st, 2025.
The increase is primarily driven by a $229 million value increase in the Babcock & Wilcox investment and a $12.6 million increase in the partnership interest related to our mark value of carried interest in funds that own SpaceX for all BRC entities, offset by a sale exit of $41 million of private stock holdings, rounding out the balance change. At March 31st, 2026, the Babcock & Wilcox stock price used in the valuation was $14.59 a share, with the company owning approximately 27.4 million shares, and the SpaceX carrying value was marked at $526 per share.
Securities and other investments are reported in detail in the 10-Q, with subtotals including public equities, private equities, corporate bonds, other fixed-income securities, and partnership interests and other. In the public equity subtotal, the Babcock & Wilcox valuation was the primary driver.
The private equity subtotal amount, which has over 50 investments including the venture capital portfolio, was lower by $42 million, primarily from the private stock holding exit described earlier. Partnerships and other investments increased $13.4 million, primarily due to the SpaceX carried interest value increase described earlier.
Continuing with investment holdings, loans receivable at fair value declined $1.4 million in the first quarter to an ending balance of $24.9 million at March 31st, 2026. In the quarter, loan lending activity included approximately $20.1 million in fundings and $21.8 million in repayments.
Also, we received a $6.7 million loan recovery, recognized through the income statement in fair value adjustment on loans. For the last balance sheet line item of our investment holdings, equity method investments were $90.7 million at March 31st, 2026, virtually flat from December 31st, 2025.
The GA Group investment, formerly Great American, comprises $83.7 million of the March 31st, 2026 balance, also virtually flat to December 31st, 2025. GA Group had good quarterly performance, which is disclosed in summary in the filed 10-Q.
Next, I'll provide an update on our liquidity and capital. At March 31st, 2026, cash, cash equivalents, and restricted cash had total balances of $178 million compared to $229 million at December 31st, 2025.
In the first quarter 2026, BRC reduced total debt by $129 million, which includes a $96 million RILYK bond redemption on March 30th, 2026 and $40 million of bond exchanges and buybacks. At March 31st, 2026, total debt was $1.3 billion, and net debt declined $255 million to $372 million.
For the remainder of 2026, the company has two senior note series maturing: $167 million in principal amount of RILYN senior notes due September 30th and $170 million principal amount of RILYG senior notes due on December 31st. These amounts have been reduced through Section 3(a)(9) bond exchanges since March 31st.
We also have $7 million in scheduled paydowns on a subsidiary lending facility. As previously described, we will continue to use capital actions, cash generated from operations, and investment liquidations to fund market opportunities and the operating companies, while also redeeming the scheduled senior note paydowns.
We look forward to answering your questions. I'll turn the call back to the operator for the Q&A session.
Operator
Thank you. At this time, we will conduct a question and answer session.
If you would like to ask a question, please press star, one on your telephone keypad to enter the queue. Once again, if you would like to ask a question, please press star, then one on your telephone keypad to enter the queue.
We will pause here briefly. Our first question comes from Sean of Cross Lane Capital.
Sean, your line is open. You may proceed.
Hey, congrats on the quarter. Just had a few questions here.
You guys touched on it a bit, but just can you kind of elaborate on your philosophy for kind of harvesting some of these gains that you have and maybe applying them to the debt if that's your preferred use of capital? Hey,
Bryant Riley
Sean. I think, yeah, you touched on this last call.
I think we've done a pretty good job of creating optionality. That's really important, and that means optionality might mean you're buying back bonds in the open market, swapping bonds for other bonds, selling some assets and repurchase bonds.
For us, we are asked often about our largest position. Our head's not in the sand.
We are thinking of all of our portfolio as one. We will make the decisions, I think, that are in the best interest of the shareholders and the bondholders.
I think I said last time, there's no playbook in this business. BDI, which is a big position for us, is trying to go private.
Fact, we have $40 million of that. SpaceX, we didn't really value nearly as high a year ago as it is today.
That's on our books for over $50 million. There's kind of a fair amount of cash and we've got investments.
It is a daily discussion and analysis, but I just can't give you the answer that you want, which is A, B, C, D. We are being very active and I think thoughtful about where do we invest to grow the business, when do we buy back bonds, what's the right price to buy back bonds, when do we swap bonds, and all those things.
Okay. Fair enough.
Then on the merger with the Wealth division, I might have missed it, but have you put out any sort of quantitative synergies that you think you're going to realize out of that?
Bryant Riley
We haven't, and I think from my perspective, and Scott can touch on this a little bit, there's a lot of one-time costs that we have had to deal with as we've got our financials current. Our team has done an amazing job of getting our financials current, but it was just a massive group of people, and we are now at a point, we're on a normal cadence, where we can really focus on that.
Not that we haven't been focusing on it, but when not everything is a mad rush. As we look through our overall corporation and then we look through the subsidiaries of the mergers, what will be more clear now that we can really I don't want to say focus is the wrong word, but maybe there's focus on some of those things and not just a mad scramble to get our financials current.
Scott, anything you want to add on that?
Scott Yessner
Bryant, I think you touched on the important points there. The merger is going to have synergies across revenues and cost lines, and those are in the early parts.
Early on, we're focusing in on the client side and the connectivity between the Wealth retail side and the institutional part of the business. That client focus and that connectivity serves the top part as we in the back office, sort of determine what the right steps are in there.
I'd echo Bryant comments with respect to we're really just in the early innings of evaluating our operating cost structure at the company, and coming out of a very intensive period, and now we're going to have a very normal operating environment. That's going to give us a lot of bandwidth to evaluate our cost structure.
There's some easy wins in this. Our audit fees were high just due to the demands we had put on our auditor, and with the normal timeline that we're going to be able to use this year, that's a pretty easy win for us.
We have several across the entity in different parts of our business and operating expenses. Now we're still staying at the directional, hey, there's a lot of opportunity off the OpEx is, and understand that that's not as easily calculatable into a model.
In the future quarters, when we start realizing those and have more dimension around them, we can share you more specifics.
Got it. Then just lastly, just because you call it out in the release, for the 26 initiations in the quarter, how much of that is attributable to new hires versus kind of increasing coverage for existing hires?
Bryant Riley
I don't have that number handy, but just a general thesis. I think that the world is much more efficient given all the capabilities in terms of everything.
Everything from AI and so, just the ability to gather information, I think a research analyst 10, 12 years ago would have been 12 to 15 companies per analyst. If you can't get to 25, you're just able to distill information quicker.
You don't have to download every 10-K and 10-Q and do your analysis faster. I think that the majority of that is just from analysts that are already on board.
Got it. All right.
Appreciate it, and again, congrats.
Bryant Riley
Yeah. Thank you.
Operator
Thank you, Sean. Our next question comes from Griffin of Owl Creek Asset Management.
Your line is open. You may proceed.
Hey guys, congrats on the good trajectory here. Looks like the clouds are starting to part.
I was hoping you could provide some further clarification on a couple of things. I guess the first thing is, can you kind of walk through the rationale of buying back the minority stake of BRS?
Initially, we thought that this was another lever that you had created to potentially partially monetize to help with the cap structure. Now it seems like you're walking back that.
Can you kind of help us understand the rationale behind that?
Bryant Riley
I think we laid that out when we made the announcement. When we carved that out, it was a different time.
We have to acknowledge it was in the middle of a very unique situation for us. Carving it out and separating it at that time felt like the best thing to do for keeping people and for managing the business and we can start bringing in.
I think as we've gotten through, and as you said, I've seen some bluer skies, we have balance sheets that have been separated and utilized in different ways and now can be utilized in one way. BRS had a lot of money in the money market at 4%, which is a great deal, while we're at corporate utilizing money at much higher rates.
Then there's also operating synergies. We still think that business could be really easily separated if we needed to do that or if somebody came along and determined that that was worth a value that we thought it was worth.
In the near term, just from a cost of capital perspective, from an operating efficiencies perspective, we felt like that was the right thing to do. TK or Scott, anything you want to add to that?
Tom Kelleher
I would just say, again, a year ago, two years ago, different landscape. Again, a big part of the reason was just the optionality.
You heard earlier, that's one of our focuses here, to make sure that we're in the right position to take advantage of whatever situation we find ourselves in. We went down that road.
A year later, a year and a half later, the landscape has changed, and it has proven to be operationally really challenging, among other reasons. Rather than persist with what we're doing, we're going to simplify our lives and put it back to the way it was.
Can I infer that ex a sale of BRS, you think you have all the solutions necessary in-house to solve the '26s?
Bryant Riley
Yes.
Understood. Then I guess one of the statements you made, which I thought was obviously great, is you've seen the most deal activity in five years in BRS terms of capital raising.
Maybe I missed nuance of that, but it doesn't look like that massive increases is showing up in the numbers. Is that because of you're trying to regain market share with lower pricing, or can you just kind of help me out there?
Bryant Riley
If we are 20% of a deal, that's obviously a lot more valuable than being 5% of a deal. I think what I've been super impressed with is that we serve to value our distribution.
The noise that has surrounded us and is dissipating, and actually I'm hopeful turns the other way, but as it surrounded us, those percentages of those deals, we lost economics. Ideally, we would rather be a smaller number and be 100% of the economics.
I think it speaks to our position. I think it speaks to the value that we provide to companies into the markets.
As we've been playing I think with one hand behind our back. We haven't had our financials current.
We've had to spend a lot of time on that. As we are now in a completely different position, I would expect that our percentages of those deals would go up meaningfully.
I would hope. That is the goal.
Got it. Then the last one for me is, you had mentioned that because the company was a delinquent filer, there's certain business that was pulled from you guys.
How are you thinking about, or how are you seeing the cadence of that recovery of former clients returning?
Bryant Riley
It's been strong. We measure it weekly.
We have seen a lot of onboarding with accounts again. It was a big deal for I think some of the bigger institutions that is check a box, and that box was, we're delinquent, let's cut them off for now.
It's been dramatic over the course of the last quarter.
Okay. Good to hear.
Congratulations on the quarter, and that's it for me.
Bryant Riley
All right. Thank you.
Thanks for the questions.
Operator
Thank you, Griffin. This concludes the Q&A session.
Handing it back to Bryant Riley for any final remarks.
Bryant Riley
Thanks, operator. It's been it's been a it's really feels good to report on on the 7th and have a normal cadence, and now we get to go after, as I mentioned, some of these operating thoughts that were were one-time in nature.
None of this would have happened if we didn't have an amazing group that worked 24/7 to get this, spend only our our revenues in line, but also our get get the financials done. Super thankful, and thanks everyone for calling in.
We look forward to talking. Our conference is coming up, hopefully we will see some some of you at our conference on the 20th.
Appreciate the interest. We'll see you next quarter.
Thank you.
Tom Kelleher
Before we conclude, we'd like to inform listeners that today's call may include forward-looking statements. These statements are not guarantees of future performance and involve risks and uncertainties that could cause actual results to differ materially from those expressed or implied.
For discussion of these risks, please refer to our most recent SEC filings, including our annual report on Form 10-K and subsequent 10-Qs. We do not undertake any obligation to update these forward-looking statements.
Operator
This concludes today's EverCall. A replay will be made available shortly after today's call.
Thank you, and have a great day.