Ralph Lauren Corporation
Q2 FY2027 · Earnings Call TranscriptNovember 5, 2026
Corrie
With me today are Patrice Louvet, the company's President and Chief Executive Officer, and Justin Picicci, Chief Financial Officer. After prepared remarks, we will open up the call for your questions, which we ask that you limit to one per caller.
During today's call, our financial performance will be discussed on a constant currency adjusted basis. Our reported results, including foreign currency, can be found in this morning's press release.
We will also be making some forward-looking statements within the meaning of the federal securities laws, including our financial outlook. Forward-looking statements are not guarantees, and our actual results may differ materially from those expressed or implied in the forward-looking statements.
Our expectations contain many risks and uncertainties. Principal risks and uncertainties that could cause our results to differ materially from our current expectations are detailed in our SEC filings.
To find disclosures and reconciliations of non-GAAP measures that we use when discussing our financial results, you should refer to this morning's earnings release and to our SEC filings that can be found on our Investor Relations website. With that, I will turn the call over to Patrice.
Patrice Louvet
Thank you, Corrie. Good morning, everyone, and thank you for joining today's call.
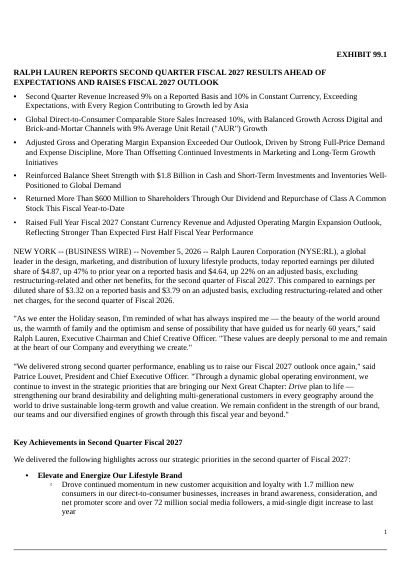
We delivered another strong quarter of progress on our Next Great Chapter: Accelerate plan. In a consumer landscape often shaped by ever-changing trends, the clarity of Ralph Lauren's values and purpose of inspiring the dream of a better life through authenticity and timeless style continues to set us apart.
We stayed true to who we are, and we have a proven ability to evolve with today's consumer. This is a powerful competitive advantage, and it is translating into sustained, broad-based momentum and a resilient core consumer with significant opportunities ahead.
In the second quarter, our top- and bottom-line results exceeded our expectations, enabling us to take up our full year guidance once again. This performance reflects our momentum across markets, channels, and categories.
Revenues increased 10%, led by double-digit growth in Asia. Our retail channels also grew low double digits, with similar comp growth across stores and digital, while wholesale increased at a solid mid-single-digit rate.
Our ongoing investments behind our brand, products, and lifestyle experiences enabled us to stay on offense and continue our long-term elevation journey with further improvement in quality of sales and full-price selling. At the same time, we continued to invest in our long-term capabilities, such as talent and technology, while accelerating cash returns to shareholders through our durable dividend and repurchases.
This balance of investment and shareholder returns reflects the power of the Ralph Lauren model. Our strong balance sheet, cash flows, and culture of operating discipline give us the flexibility to navigate a complex global backdrop while fueling future growth opportunities.
Underpinning this model is a combination only Ralph Lauren can bring together: authentic lifestyle authority, cultural relevance, and timeless brand codes at global scale. We are building on this distinctive advantage through the three strategic pillars of our plan, which, as a reminder, include: first, elevate and energize our lifestyle brand; second, drive the core and expand for more; and third, win in key cities with our consumer ecosystem.
Starting with our efforts to elevate and energize our lifestyle brand. Through our rolling thunder of activations, we are engaging with consumers across the many facets of their lives, from the inspiration of the runway to the biggest stages in sports, entertainment, and more.
This enables us to deepen our connection with existing consumers around the world as we build lifetime value, while also inspiring a new generation with our cinematic storytelling and core values of optimism, quality, and authenticity. Key highlights from the quarter included: first, we continued to strengthen our position as one of the world's leading luxury lifestyle brands in sports, elevating traditionally local events into globally relevant, exciting brand moments.
At Wimbledon, we combined the heritage and elegance of the tournament with Ralph Lauren's spectator style. We activated across our top cities around the world, from our Sloane Square takeover in London, to our Tokyo live viewing party, and Douyin live shopping event in Hong Kong, and our legends tennis exhibition match in New York Central Park with Andre Agassi, Caroline Wozniacki, Eugenie Bouchard, and James Blake.
At the US Open, we built on our long-standing partnership with an expanded 360-degree campaign, including our vintage-inspired collection, specialty pop-ups, and influencer activations. At the Goodwood Revival in the UK, we brought our sophistication to the classic motorsports event for the fourth year, including a preview of our Polo Bar experience ahead of our London restaurant opening slated for 2028.
Together, these sports lifestyle campaigns allow us to showcase the breadth of the Ralph Lauren lifestyle while bringing consumers closer to the brand. They generated a combined 70 billion global impressions and more than $350 million in media value.
Next, we immersed consumers in our vision of timeless style through our Spring '27 Women's Collection fashion show in New York City, along with key celebrity dressing moments including BTS at their Arirang World Tour at MetLife Stadium, and at our Very Ralph documentary premiere in Seoul. Beyond the quarter, we recently hosted our first-ever Polo Fest in Tokyo, bringing polo collectors, brand enthusiasts, and cultural voices together for a three-day experience as part of our year-long celebration of 50 years in Japan.
These activations are driving strong, sustainable growth in new customer acquisition and retention. In the second quarter, we added 1.7 million new customers to our DTC businesses, led by Ralph Lauren stores.
We continued to drive progress across brand equity metrics, including increased awareness, purchase intent, and Net Promoter Score. We're also driving higher lifetime value and recruiting key consumer cohorts led once again by women, luxury, and younger customers.
We increased our social media followers by mid-single digits to more than 72 million, led by Instagram, LINE, and Douyin, with a focus on our summer of sports and fashion show. This diversity of activations enables us to keep the brand fresh and relevant across each of our key markets, staying true to Ralph's vision while finding new ways to bring each generation into our world.
This brand momentum is translating directly into increasing desirability and demand for our products. This takes me to our second key initiative: drive the core and expand for more.
Ralph's vision has always been about a way of living. This quarter, our talented creative teams brought that vision to life through our enduring icons, combined with seasonal newness across men's, women's, and children's.
By reinforcing the core while expanding our lifestyle proposition, we are creating multiple avenues for durable growth and bringing our products to life through increasingly connected consumer ecosystems. Starting with our core, which represents more than 70% of our business, core product sales grew 10% in the second quarter.
Recent highlights include our cotton cable and merino blend sweaters, linen poplin and Oxford dyed shirts, iconic chino caps, sport coats, and fleece. For the Fall '26 season, our Litchfield and Red Rocks collections from Men's Polo resonated particularly well with consumers.
In children's, we delivered a successful back-to-school with our collegiate-inspired Next Gen and New England-themed Middlebury collections, with strength across our sweaters, core mesh polos, sweater dresses, and expanded outerwear proposition. Our high-potential categories, including women's apparel, outerwear, and handbags, grew low double digits for the quarter, ahead of total company growth.
In women's, we drove excitement through our new micro-cable collared cardigan and wool rugby sweaters, corduroy shirts, and polo shirt dresses. Our strong outerwear performance was driven by our lightweight bi-swing and Bayport cotton windbreakers for men, and icon windbreakers and barn jackets for women.
In handbags, we officially launched Polo Blazer, our most elevated foundational collection for Polo to date, marrying equestrian-inspired details with a downtown edge. Special releases this quarter included our US Open collection inspired by the heritage of tennis and the spirits of New York, delivering our strongest sell-throughs around the event to date; and our collaborations with Gee's Bend and second capsule drop with Naiomi Glasses, both part of our groundbreaking Artist in Residence series, focused on empowering and celebrating artisans within the communities that have historically inspired our designs.
As we turn to holiday, we will continue to invite consumers to step into the cinematic worlds that Ralph created, with timeless, high-quality products, a compelling value proposition, and styling that only we can deliver. Turning to our third key initiative: win in key cities with our consumer ecosystem.
We are creating unique lifestyle experiences to immerse consumers in the world of Ralph Lauren, bringing together product, hospitality, and storytelling in our top 30 cities around the world, while also laying the groundwork for long-term growth in our next 20 cities. Within DTC, which comprises the majority of our business, global comps increased 10%, led once again by our Ralph Lauren stores and digital commerce.
By region, Asia increased 28%, driven by 24% comps and growth across all key markets. China sales remained strong, increasing more than 35%, while Japan and Korea were also up double digits as we continued to invest behind localized brand activations and experiences.
Europe delivered low-single-digit growth this quarter, in line with our plan, despite industry traffic headwinds and on top of last year's strong compares. We drove another quarter of strong results ahead of expectations in our largest region, North America, with healthy demand in both our retail and wholesale channels.
With regards to our store base, we opened 22 new owned and partner stores globally this quarter as we deepened our presence in our top cities. Highlights included Seaport in Boston, including our first Ralph's Coffee location in Massachusetts; new men's and women's standalone stores in London's Sloane Square; Saint-Tropez, France; Beijing Hopson One; and Galaxy Promenade in Macau.
On the digital front, we expanded our RL mobile app to Japan, following our successful launch in Korea earlier this year, with early sales performance and downloads exceeding our expectations. We also grew our connected retail and clienteling capabilities across several markets in Asia this quarter, enabling our teams to serve consumers with greater personalization and consistency.
Finally, touching on our enablers. Our business continues to be supported by our five key enablers.
Recent highlights include: first, as part of our focus on advanced technology, AI, and analytics, we are investing in new capabilities that help our teams move faster, create more personalized consumer experiences, and operate with greater precision. In addition to expanding our mobile app and clienteling in Asia this quarter, we continued our journey to enhance visibility on key LLMs.
We also launched a test on WhatsApp Concierge, a digital assistant that allows customers to interact directly with our brand on the WhatsApp platform. Following our initial test with OpenAI earlier this year, we are further scaling advertising on the platform for holiday gifting and cultural moments.
In addition, we are advancing our commitment to the communities we serve. We recently announced a new partnership with the Korea National Cancer Center Foundation to establish a new Ralph Lauren Cancer Center in Goyang, our first in Asia and fifth globally, part of our broader, long-standing commitment to more equitable access to cancer care.
We were proud to be recently named one of the World's Best Employers by Forbes, reflecting the power of the people and culture that make Ralph Lauren so special. In closing, Ralph and I are encouraged by our team's progress in this second year of our Next Great Chapter: Accelerate plan, in the midst of an ever-evolving global operating landscape.
As we head into the important holiday season, our consumer remains at the center of everything we do. With that in mind, we will continue to lean into our long-term elevation journey, investing in our strategic priorities to deliver sustainable growth and value creation into the future, including: developing innovative campaigns that build desirability and engagement and grow lifetime value; creating timeless, high-quality products that offer compelling value and earn consumers' trust; and winning in our top cities through unique brand experiences that immerse consumers in the world of Ralph Lauren.
These diversified engines of growth and our increasingly elevated consumer base, all underpinned by our iconic brand, continue to drive resilience in our business model and consistency in our performance. With that, I'll hand it over to Justin, and I'll join him at the end to answer your questions.
Justin Picicci
Thanks, Patrice, and good morning, everyone. Our second quarter performance underscores our growing brand desirability around the world, with results exceeding our expectations across both revenue and profitability.
This reflects broad-based consumer demand and the strength of our diversified growth model against a dynamic operating backdrop. Revenues increased 10%, ahead of our mid-single-digit outlook for the quarter, with growth across every region.
Our brand and products continue to resonate with consumers globally, and full-price momentum supported gross and operating margin expansion above expectations. Notably, we delivered this performance while continuing to invest in the strategic initiatives that will fuel sustainable, long-term growth and value creation.
This combination of second quarter outperformance and sustained brand momentum gives us confidence to raise our full year outlook once again. First, let me walk you through our financial highlights from the second quarter, which, as a reminder, are provided on a constant currency adjusted basis.
Total company second quarter revenue grew 10%, driven by better than expected performance in both our direct-to-consumer and wholesale channels. By region, Asia led our performance, increasing 28%, followed by North America up 6%, and Europe up 3%.
Total company retail comps also increased 10%, with growth across both our owned digital and brick-and-mortar channels. Total company adjusted gross margin expanded 220 basis points to 70.2%, ahead of our outlook.
The increase was driven by AUR growth, favorable geographic mix, and lower product costs, which more than offset modest pressure from higher labor and non-cotton material costs in the quarter. AUR increased 9%, ahead of our plan and on top of 12% growth last year.
The increase was broad-based and reflected balanced contributions from product elevation, favorable channel and geographic mix, and selective pricing actions and lower promotional activity. For the third quarter, we are currently planning for mid-single-digit AUR growth on top of last holiday's exceptionally strong 18% increase.
Our outlook continues to be supported by our ongoing brand elevation strategy, with the flexibility to further reduce discounting based on consumer demand and selling trends. Adjusted operating expenses increased 11% or 70 basis points as a percentage of sales compared to last year, as higher marketing more than offset leverage in non-marketing expenses.
Marketing increased to 8.6% of sales, up from 7.8% last year, reflecting increased investments to amplify key campaigns, including our New York fashion show and sponsorships of Wimbledon and the US Open. Our multi-year progress in steady new customer acquisition, healthy consumer metrics, and attractive returns reinforces our confidence to continue expanding our marketing programs across our top cities.
We now expect marketing investment to represent approximately 8% to 8.5% of sales in fiscal '27, compared to approximately 8% previously. Even with this higher investment, second quarter adjusted operating margin expanded 140 basis points to 15.5%, ahead of our plan, while operating income grew 21%.
This underscores our ability to expand profitability while continuing to make investments in our brand and capabilities that support durable growth. Turning to segment performance, and starting with North America.
Second quarter revenue grew 6% at the high end of our expectations. In North America retail, second quarter comps increased 6% on top of a double-digit compare last year, with balanced growth across our digital and brick-and-mortar channels.
Digital comps increased 5%, supported by solid traffic, full-funnel marketing activations, and continued merchandising optimization. North America wholesale revenue grew 8%, driven by healthy replenishment and seasonal orders.
Results included approximately 4 points of benefit from planned timing shifts from the second half of the year. We continue to expect North America wholesale performance to moderate in the second half as we lap these timing benefits and accelerate our strategic reduction of off-price sales and lower-tier full-price doors.
Our underlying growth in the channel remains healthy, with strong full-price sellout trends and continued market share gains. Turning to Europe.
Second quarter revenue increased 3%, modestly ahead of our expectations. Europe wholesale increased 4% on top of double-digit growth last year.
Underlying sellout trends remain in line with our full year outlook, and we continue to proactively manage our sell-in to align with consumer demand and maintain healthy inventories in the channel. Europe retail comps declined 1% as we lapped an exceptionally strong 10% compare last year amid a challenging macro environment.
While the region continues to face pressure from weaker store traffic across several of our key markets, we are taking targeted strategic actions to drive stronger consumer engagement, increased conversion, and higher basket sizes in our stores. Looking ahead to the second half of the year, we continue to invest behind our strongest brand and consumer opportunities in the region, including marketing activations and targeted consumer engagement, building on our growing brand desirability to support both near- and long-term growth.
Moving to Asia. Second quarter revenue increased 28%, reflecting broad-based growth across all key markets.
Retail comps grew 24%, with double-digit growth across every channel. Our Asia digital ecosystem also delivered double-digit growth, with strong contributions from our owned digital commerce sites.
By market, China continued to lead our performance, with sales up more than 35% in the quarter, driven by healthy comps and high-quality new customer recruitment. Japan and Korea also delivered strong double-digit growth, supported by localized brand activations and sustained consumer engagement.
Our full-funnel marketing activations throughout the region are building deeper connections with consumers, and we continue to see substantial opportunity to build awareness, deep engagement, and expand our presence across key markets where our luxury lifestyle positioning continues to resonate. Moving to the balance sheet.
Our fortress balance sheet and strong cash flow generation continue to provide meaningful strategic flexibility, enabling us to invest through periods of volatility, pursue compelling growth opportunities, and return capital to our shareholders, all while maintaining prudent financial discipline. During the second quarter, we repurchased approximately $250 million in shares, bringing our year-to-date repurchases to $500 million and completing our buyback plans for fiscal '27.
We remain on track to return over $2 billion to shareholders, including through dividends and repurchases, over our three-year drive plan. We ended the period with $1.8 billion in cash and short-term investments and $1.2 billion in total debt.
We continue to manage inventories closely against demand in each of our regions. Second quarter net inventory decreased 8% in constant currency, reflecting last year's elevated tariff-related inventory base.
Excluding the impact of tariffs, net inventory declined approximately 2%. As we enter the holiday season, our inventories remain healthy, current, and well positioned to support demand across geographies and channels, while preserving flexibility.
Looking ahead, our outlook for fiscal '27 remains based on our best current assessment of the operating environment, including the geopolitical backdrop, foreign currency dynamics, and broader macroeconomic conditions. For fiscal '27, we now expect constant currency revenue growth of mid- to high-single digits on a 52-week comparable basis, centered around 6% to 7%, up from our prior outlook of 5% to 6%.
This increase largely reflects our better than expected second quarter results, along with a modestly stronger outlook for the second half, supported by our continued brand momentum. As previously discussed, we continue to expect first half growth to be stronger than second half growth, reflecting the timing of this year's marketing activations and other investments, the timing of planned wholesale shipment shifts and strategic off-price reductions, and more challenging year-over-year comparisons in certain of our key markets.
Importantly, our outlook continues to assume healthy underlying growth in the second half, in line with our long-term plan. Foreign currency is now expected to negatively impact revenue growth by approximately 40 to 60 basis points this year, based on current exchange rates.
As a reminder, fiscal '27 includes a 53rd week, which is expected to add approximately 1 point to revenue growth and slightly benefit operating margin. By region for fiscal '27, we now expect North America revenue to grow approximately low- to mid-single digits, up from low single digits previously.
We are encouraged by our strong first half performance in the region and the continued momentum across our direct-to-consumer and full-price wholesale channels. We still expect this solid underlying growth to be partly offset by accelerated strategic actions to improve quality of sales and exit lower-tier doors, notably in the back half of the year, as we further elevate and strengthen our long-term position in the marketplace.
We now expect Europe revenue to grow approximately low single digits, compared to low- to mid-single digits previously. This outlook reflects positive underlying growth, partly offset by increased pressure on consumer traffic and broader macroeconomic volatility in the second half of the year.
We remain focused on driving high-quality near-term results while continuing to invest behind long-term brand elevation and margin expansion. We now expect Asia revenue to increase low teens, up from our prior outlook of high single to low double digits, driven by our stronger than expected first half results, along with ongoing brand momentum across our key markets in the region.
We now expect full year operating margin to expand approximately 80 to 100 basis points in constant currency, up from our prior guidance of 60 to 80 basis points, largely driven by our better than expected second quarter results. We are also raising our full year gross margin outlook to approximately 80 to 100 basis points of expansion, compared to our prior guidance of 50 to 70 basis points.
This reflects our stronger than expected Q2 results, along with our updated view on US tariffs, which assumes the prevailing rate of approximately 10% through December, followed by a return to reciprocal rates in the high teens in our fiscal fourth quarter. We continue to expect both gross and operating margin expansion to be weighted towards the first half of the fiscal year, reflecting normalizing AUR growth and the timing of key marketing activations, as well as our previously disclosed timing shifts in wholesale shipments.
Our guidance continues to exclude the benefit of tariff refunds, which are not included in our adjusted non-GAAP results. As part of our long-term capital allocation strategy, related proceeds received will be primarily reinvested in the business, as well as directed toward initiatives that strengthen and advance our purpose and values.
Foreign currency is now expected to benefit gross margin by approximately 10 to 30 basis points and have a roughly neutral impact on operating margin in fiscal '27. For the third quarter, we expect constant currency revenue to increase approximately low- to mid-single digits, centered around 3% to 4%.
This outlook includes approximately 1 point of negative impact from planned wholesale timing shifts and strategic off-price reductions in the quarter, with underlying growth of roughly mid-single digits. Foreign currency is expected to negatively impact revenues by approximately 50 to 100 basis points.
We expect operating margin to expand approximately 50 to 70 basis points in constant currency, with gross margin expansion more than offsetting higher marketing investments in the holiday period. Foreign currency is expected to benefit gross margin by about 20 to 40 basis points and have a roughly neutral to 20 basis point benefit to operating margin in the quarter.
We expect our third quarter tax rate to be in the range of 23% to 24%, while the full year tax rate is still expected to be in the range of 21% to 22%. In closing, our teams continue to deliver against both our near-term commitments and long-term strategic priorities.
This quarter's results demonstrate the strength of our diversified growth model, the benefits of our elevation strategy, and the discipline with which we are investing for the future, underscoring the enduring relevance of Ralph's timeless vision around the world. While the external environment remains dynamic, we are focused on what we can control: continuing to drive brand and product desirability, enhancing quality of sales, operating with discipline, and investing behind high-return growth opportunities.
Together, these actions position us well to deliver on our fiscal '27 commitments while strengthening the foundation for durable, long-term value creation for all of our stakeholders. With that, let's open up the call for your questions.
Operator
Ladies and gentlemen, if you wish to ask a question, please press star, then one on your touch-tone phone. You will hear a tone indicating you have been placed in queue.
You may remove yourself from the queue at any time by pressing star, two. If you are using a speakerphone, please pick up the handset before pressing the numbers.
We ask that you limit yourself to one question per caller. Once again, if you have a question, please press star, one at this time.
One moment, please, for the first question. The first question comes from Matthew Boss with JPMorgan.
Your line is open.
Matthew Boss
Thanks, and congrats on another nice quarter.
Patrice Louvet
Thank you, Matt.
Matthew Boss
Patrice, what does your updated fiscal '27 outlook assume for the health of your consumer in each region? Is the global operating environment getting tougher in your view, or just any puts and takes?
Then Justin, could you elaborate on the progression of demand trends that you saw in North America during the second quarter, and just drivers underlying your full year raise for top-line growth in that region?
Patrice Louvet
All right. Good morning, Matt.
Thanks for your question. I would call out a few points.
Looking collectively across regions, our brand is strong and is getting stronger. We're investing for the long term, and we're well on track toward our three-year targets.
We're actually halfway through our Next Great Chapter: Accelerate phase and progressing really nicely. Now, we're certainly in an environment with a lot of macro noise, and I don't think macro noise is a new phenomenon for this industry, but there's plenty of it right now, including our updated views on Europe.
We have successfully, as a company, navigated through a variety of macro environments over the past many years, and we are well positioned looking ahead. As you saw, we were able to take up this year's outlook once again.
Now, specifically on the consumer. As we're in an exciting elevation journey with our customer base around the world.
Right? We've shifted our customer base to focus on higher quality of sales, lower price sensitivity, larger basket size, and younger cohorts.
Today, our core consumer remains resilient across each of our key markets globally. Zooming out, our growth and value creation model is durable, in part because we have this diversity of drivers.
Our brand is stronger than ever in every region, with record level affinity scores. You heard us say it earlier, we're seeing that across the regions.
We have a culture of agility and operational discipline built over years, and we have a lot of opportunities yet to build the brand in large markets like China, Korea, Germany. Even in North America, what I would argue, we're actually in the very early innings of our elevated journey in North America, with significant growth opportunities ahead around the region, particularly in the West Coast, now that we've established healthy foundations across the entire business model.
Regardless of the macro, we're running our play. We've got an eye on the long term, because we want to make sure we're continuing to build this brand in the right way for long-term success.
Because we have both the diversity of growth drivers and the flexibility to pivot and take advantage of clear opportunities for Ralph Lauren in the marketplace, that's where our confidence comes moving forward. I would call out that we're continuing to invest behind our iconic brand and reinforce our place in culture.
You've heard us talk about the recent Polo Fest event, which I think is a beautiful illustration of how the Ralph Lauren brand has been weaved into the culture globally. We're creating timeless core products that resonate across generations, Gen Z, but also the silver generation, and across geographies.
We're offering lifestyle experiences that consumers want to be part of, and we see that every single day, including the lines at our coffee shops. To summarize, I would say we remain on offense.
We're taking market share across markets. We're building our brand equities and healthy foundations for the long term, and we have significant runway ahead for our unique lifestyle proposition.
Justin Picicci
Matt, the question on North America. As you mentioned, we took up our full year outlook for North America from low single digits to low- to mid-single digits, and we're really encouraged by the broad-based momentum we have in that region across the whole ecosystem.
Our core consumers are performing really, really well. We're seeing that ongoing shift towards a more elevated positioning really, really drive our business across channels, especially, I would say, full-price channels.
In Q2, you saw another balanced, healthy growth delivery across DTC and wholesale. As we think about sort of going forward into Q3, we're really expecting that continued momentum both in DTC and really in that healthy full-price wholesale sellout to continue, partly offset by those deliberate, accelerated quality of sales investments and lower-tier door exits that we've talked about.
When you think about the underlying trend for the region, it's really continues to be on that mid-single-digit trajectory, and we're really encouraged by that brand momentum continuing.
Corrie
Thank you. Next question, please.
Operator
Thank you. The next question comes from Jay Sole with UBS.
Your line is open.
Jay Sole
Terrific. Thank you so much.
Justin, what catalysts or metrics are you looking at to get more constructive on Europe? For the overall business, can you also provide any color around recent performance and quarter-to-date trends?
How should we think about the implied deceleration in your second half guidance? If you can also add a little bit more specificity on how you see gross margin playing out in Q3 and Q4, that would be great.
Then Patrice, if I can just ask you one. Justin mentioned that it's great to be able to meet and exceed expectations and still reinvest in the business.
I think as marketing gets higher and higher as a percent of sales, I think it was 8.6% this quarter, are you interested in actually keeping that number where it is and maybe even driving it higher, and can you do that while still maintaining the ROI associated with that spend? Thank you.
Justin Picicci
Morning, Jay. Thanks for the question.
Listen, we remain focused on driving high-quality, sustainable growth for all three of our regions, and that includes Europe. I would say importantly for Europe, we continue to track ahead of that three-year growth algo that we laid out, and we're delivering growth in the second year of our plan.
You heard Patrice talk about we continue to see meaningful, long-term growth opportunities across key markets, categories, channels in that region. Now, based on what we've seen so far this fiscal year, the trends have generally, I would say, played out as we expected, right, with broader industry traffic pressure remaining the primary headwind.
When we think about in terms of what would make us more constructive on Europe, traffic, and I would say particularly in stores, that remains a key metric that we're watching closely. That all said, our updated guidance doesn't assume a meaningful improvement in traffic or in the macro environment.
Against that challenged backdrop, we continue to expect our brand to gain share and for Europe to deliver positive growth this year, and that includes slight growth in Q3. While the external environment in Europe certainly remains pressured, what we're doing is we're proactively managing our business and focused on the things we can control.
Our consumer, brand metrics remain strong, including record NPS scores. Our teams are focused on driving conversion, basket size to help offset that near-term traffic pressure.
This is all while we continue to invest behind and advance our long-term elevation strategy in the region. To your second part of your question, what I'd do is I'd separate the underlying health of the business from the quarterly cadence.
Our outlook remains consistent with the quarterly growth trajectory we planned as we came into the year. I would say with slightly stronger expectations for the second half than we've previously anticipated based upon our strong brand momentum.
Now that splits our updated full year outlook for both revenue and profitability ahead of our long-term plans, similar to what we delivered last year in year one. The first half of this year reflected stronger top-line growth, including favorable timing shifts in the second half, as well as higher growth in marketing.
As we move to the back half, we'll also begin to lap some exceptionally strong compares in Asia, notably for China, while also executing on those planned strategic pullbacks that I just mentioned in North America off-price wholesale. Now those factors affect the quarterly cadence, but they don't change our view of the consistent, underlying momentum in the business, which remains strong.
As we don't typically comment on monthly or quarter-to-date trends. I would say our third quarter guidance incorporates the recent trends we're seeing in the business, as well as our expectations for the key holiday selling periods ahead.
Just stepping back, when you adjust for timing, planned strategic actions, more difficult compares, we continue to expect healthy underlying growth in the second half, firmly in line with our long-term growth plan. On the second half gross margin outlook, I would say it continues to be supported by structural, durable drivers.
You'll see AUR, of course, durable drivers behind that, our geo, channel, product mix durable drivers behind that. We do have a tariff assumption in there that has the prevailing rate going back to kind of the reciprocal rates, the high teens in the fourth quarter, so that's in there.
We think that's prudent, and we'll see what happens there. We expect our gross margin to remain healthy, albeit with a little bit of normalization on the AUR front off of the strong double-digit first half performance.
Patrice Louvet
On marketing, I would say a few things, Jay. As a company, we're in the dreams business, we're in the storytelling business, marketing is a core element of our business model.
I'm actually really excited to see how, over the past few years, we've gone from, 3% to 4% of our revenue invested in marketing to now north of 8%. There's really no ceiling.
Right? What's important is that as we want to continue to invest in marketing, as long as we get an exciting re- return, which we have, while expanding operating margin.
It's not one at the expense of the other, we're always going to do them in tandem. As we look at the types of activations that we have, right, we have a multifaceted marketing strategy that really focuses on our key consumer targets.
We want to talk across generations, we want to talk across genders, we want to talk across communities, and I think our team has done a fantastic job building a portfolio of marketing activations ranging from sports to fashion presentations to Polo Fest to social media activities that have really helped bring the brand to life in different ways across different cohorts and have been driving our momentum over the past past many years. The strategy is really focused on, one, new consumer acquisition, right, and particularly younger, higher value, higher basket size, more diverse consumers.
You saw this quarter we added another 1.7 million new consumers with fantastic profiles. Our social media followers are up to 72 million now, on our way to 100.
Second is retention rate, which is obviously very important. We have, I believe we can say, the most loyal customer in the industry, for us it's about lifetime value, not just one purchase.
We're driving that through increased personalization, increased clienteling, and of course trading across and trading up with leveraging our full our full lifestyle portfolio. Then finally, to the ROI point, our teams are doing a fantastic job consistently looking for ways to be more efficient in the way we target, to be more efficient in the way we activate, to focus on the bigger opportunities, so that through this journey of 3.5% of revenue to now this last quarter 8.6% of revenue, we all feel very good about the type of return and and effectiveness that we see.
That's, driven by increased digital focus overall, that's driven by increased targeting, that's driven by increased personalization, and you see that across the metrics this last quarter, right? Our awareness is up, our consideration is up, our purchase intent is up, our advocacy is up.
Therefore, the investments that we are making are are delivering and are driving the strong momentum and the strong comp performance that we've been we've been talking about. As you look at holiday, which is obviously a key important moment for us as a company, very excited about the momentum we have going into holiday.
You heard all the activations we had in Q2. We have a number of great things going on in Q3.
We had the women's polo presentation in Paris that got rave reviews. We have the Polo Fest activation in Tokyo.
We have a very strong holiday campaign situated in the Adirondacks that we're very energized by. We are starting our investments earlier from a media standpoint, we expect higher impact.
We launched, I think, ahead of most of our competitive set to really capture the full gifting season, with, media investment up 23% versus last year, focused on our top 30 city ecosystems. That's the first point.
Second point is really making gifting an acquisition engine, deploying a fully integrated 360-degree gifting strategies, because we are one of the premier brands from a gifting standpoint. We we know we have the opportunity to lean into that even more effectively across generations.
Third is we're doubling our global holiday experiences. I don't know, Jay, if you had a chance to experience ours in in LA last year, but we're going from four cities last year to eight cities this year: LA, London, Paris, Hong Kong, Singapore, Tokyo, Sydney, Seoul.
I suspect when we talk next year, that list will even expand, because we've seen very strong response to these experiences. We are at a time with AI and digital and agents where consumers, more and more, they want live, in-person experiences, and these events really deliver that.
The fourth element, sorry, this is long-winded, but I think it's important for for all of you and to understand how we're thinking about this moving forward. Fourth element is really amplifying our cultural and social reach.
Right, we have an incredible network globally of creators, influencers, editorial partners that help us reach new audiences and help us will help us drive demand for key holiday categories like outerwear, like cable knit sweaters, like our handbags across many of the different social media platforms, as well as taking advantage of the LLM capabilities and platforms that are are coming up, and make sure that consumers can discover us on those. Then the final point is really capitalizing on organic holiday momentum.
You'll remember last year that Ralph Lauren Christmas was trending. Here's the good news: Ralph Lauren Christmas is trending again this year, emerging organically as consumers celebrate and share their love for Ralph Lauren's iconic products, particularly the Bear product and our Home collection.
This gives you a sense of the activations we have going into holiday just for this quarter, right? As our strategy is to have a rolling thunder of activations that talk to our different cohorts.
No, 8.6 is not a ceiling, as long as we get exciting returns, we will continue to lean in our diversified portfolio of activations while, of course, delivering attractive value and also expanding our operating margin. Sorry for the long answer, but hopefully that gives you a good sense for where we are.
Corrie
Thanks, Jay. Next question, please, Julie.
Operator
Thank you. The next question comes from Kendall Toscano with Bank of America.
Your line is open.
Kendall Toscano
Hi, thanks for taking my question. I just wanted to see if we could zoom in on Europe a bit more, and so as we think about that region having been challenged for a few quarters now, it does seem like the store traffic for you guys was incrementally more challenging in the second quarter compared to what you saw in the first quarter.
I know you called out a particularly tough comparison in Europe during the second quarter, but how should we think about as you move into the third quarter, you're lapping a flat comp last year versus a plus 10? How should we think about that versus I think you mentioned you're expecting slight growth for the region in the third quarter, and how do you expect that consumer to behave during holiday?
Justin Picicci
Sure, maybe we can tag team this one. Thanks for the question.
As you pointed out, the change in our EMEA outlook is really the external environment has become a bit more challenged than we expected, particularly around retail traffic, consumer confidence, and I would say broader cost of living pressure. There's been a sort of prolonged, I would say, traffic softening that started in to ramp up in Q1, really continued into Q2, and that's reflected in our updated fiscal '27 EMEA outlook of low-single-digit growth.
Yes, we have assumed some, I would say, unit elasticity in the second half given that backdrop, but we're not assuming sort of a broad deterioration across all of the underlying drivers of the business. In fact, our teams are very focused on what they can control, right?
Think driving product desirability, conversion, basket size, targeted consumer engagement, which is going to help mitigate some of that external pressure. We have a proven playbook of strategies there.
Importantly, our updated outlook doesn't contemplate or depend on, I would say, in the near-term, macro recovery in EMEA. I also think the broader context here is important because our Q3 outlook for the company, right, is still for that sort of low- to mid-single-digit growth, which includes about a point of pressure from our wholesale timing and strategic off-price pullbacks, so that incorporates actually a bit more cautious assumptions for EMEA, while, if you think of taking a step back, we're still on that underlying mid-single-digit algo for total company.
We believe we've appropriately reflected the softer Europe consumer and traffic environment in the guide, and at the same time, we're continuing to see opportunities to mitigate those pressures through those strategic actions that I talked about without assuming the environment gets better. The last thing I'll say, we also continue to invest in the region.
In marketing, in new stores, in digital, really to drive long-term growth and continue to strengthen our already strong brand equity. We're going to protect quality of sales and long-term brand equity.
Flexibility doesn't mean walking back our elevation strategy.
Patrice Louvet
I would add a couple of things, Kendall. We've built a strong business over the past few years in Europe that's really fundamentally well positioned and much more elevated than it was a few years back.
Strong base, strong foundation. Second is our brand continues to strengthen.
We saw that in our recent equity scores across the region. It's true across generations, particularly true for the younger generation, so that's actually very promising.
As Justin mentioned, we're on offense, right? We're investing more in marketing.
You heard some of the comments I made earlier relative to media for Q3. We're continuing to invest in store openings in London, in the south of France, and others.
Clearly on offense. Share data isn't great in this industry compared to my old world, but from the share data that we have, we also know that we're growing market share across the business, this is an important time for us to take advantage of the broader challenges to expand our market share.
I think I mentioned earlier on the consumer that our core consumer is resilient, and this is true across the world, and it's true in Europe. I think where we're seeing the pressure is traffic, particularly in outlets, right, which typically will be the consumers that will be more pressured by inflationary considerations.
They've got to drive all the way to the center, etc. As Justin mentioned, we want to be cautious in terms of just recognizing the macro traffic headwind reality, but certainly from a mindset and strategy and investment, we remain clearly on offense in Europe.
Corrie
Next question, please.
Operator
Thank you. The next question comes from Michael Binetti with Evercore ISI.
Your line is open.
Michael Binetti
Hey guys, thanks for taking our question here and for all the detail today. I guess just a quick one, Justin.
Do the initiatives you mentioned to engage with consumers in Europe, drive conversion and basket, does that include promotions? Is that a lever you expect to pull in the holiday while the traffic is tough there?
Then, I guess on gross margins, if you wouldn't mind breaking down the drivers a little more quantitatively for us, the expansion, I know you mentioned the drivers were AUR growth, geomix, product costs. AUR slowed a little bit from the first quarter, not much.
I don't think the geomix was vastly different from first quarter. Maybe a little bit of help on the breakdown of the 250 would be great.
Then, I guess just a longer-term question, a jump ball, you're tracking to a 17% operating margin for the year, and I think the analyst day last year, you contemplated building to something closer to maybe 16% by fiscal '28. Obviously running nicely ahead there.
Would you mind just orienting us around what's driven the upside so far, what's unexpected or exogenous, we can just kind of understand how much you still see from here in the buckets that you laid out in the operating plan?
Justin Picicci
Thank you, Michael. Let's see if my memory is still working like a charm.
I would say your second question on the gross margin. I would say if you think about Q3 and our expectation on our gross margin expansion, and AUR specifically, because that's really the big driver of our gross margin, I would expect sort of equal contributions.
Like we saw pretty much in Q2 for AUR, we saw equal-part contributions from product mix, from geo channel mix, and from pricing and promotional pullback. I would expect that to continue as we think about heading into Q3 from an AUR perspective, which again is going to be our biggest gross margin driver.
I would expect AUR to normalize a bit, as we talked about, getting closer in line with that longer-term sort of mid-single-digit algo, as we continue to close the gap between our AUR growth and targeted unit growth as revenue drivers. From a promotional perspective, we're going to stay disciplined this holiday, and we've got the flexibility, we know, to be targeted where the consumer environment warrants it, without compromising our long-term strategy.
From a promotional standpoint, North America remains relatively stable. Europe, with a challenged consumer backdrop, has become more promotional quarter-over-quarter.
We're on a continuous elevation journey, as you know. That remains the priority.
We'll recognize the environment, particularly in Europe. We have the flexibility to respond selectively where appropriate, but our strategy is not to broadly chase the macros.
We will lean in and be targeted in how we use promotions and present that compelling price-value proposition where that consumer is feeling that the macros tightening up, and that can include adjusting frequency, depth, duration, or breadth of promos without changing our overall strategic direction. We've demonstrated that playbook over many years, and our continued AUR progress and strong price architecture we've built up has given us that targeted flexibility within those brand guardrails to respond to the consumer and the competitive environment this holiday.
On your last point on margin. Yes, we've made really strong progress over our Next Great Chapter: Accelerate three-year plan with margins, really driven by, well, the increased full-price selling, gross margin expansion outpacing our expectations.
What you've seen us do is we've taken some of that gross margin outperformance and reinvested it back behind the brand, marketing, digital, key cities, etc., to really fuel durable, longer-term growth. Our operating margin that we deliver this year is not a ceiling, right?
We contemplate and expect year-over-year margin expansion every year of our long-term plan, and we've got durability behind both our gross margin drivers, right, which including AUR, which is a big piece of that, but also when you think about the favorable structural mix benefits that we have from geo, channel, etc., product, etc. Then on the SG&A expense line, we know we've built out the muscle.
We have a culture of operating discipline. We built out the muscle of leveraging expenses.
Now you don't always see that because we opportunistically reinvest, but we've built out the muscle of leverage, and we do expect more balanced contributions from gross margin expansion and SG&A leverage as we move forward. We certainly feel really good about our continued ability to leverage some of the big investments that we've made, whether that's in new stores, digital infrastructure, etc.
Going forward, I would say fiscal '27 operating margin not a ceiling, year-over-year progress expected, and we've got durability behind the drivers of both gross margin and of SG&A expense that contribute to that expansion.
Corrie
Thanks. Next question, please.
Operator
Thank you. The next question comes from Laurent Vasilescu with BNP Paribas.
Your line is open.
Laurent Vasilescu
Oh, good morning. Thank you very much for taking my question.
I wanted to ask about Asia. Justin, last quarter, I think you explicitly guided for Asia to grow mid-teens for the second quarter.
I'm just curious on how we should think about Asia growth for the third quarter. Then within the full year raise for Asia to grow low teens, how do we think about China?
I think you called out last quarter it was going to grow mid-teens. Is that number going up?
Then within that, I'd love to hear what you're seeing on the ground in China specifically, as we've heard some other luxury players call out weakness in that marketplace. Thank you so much.
Justin Picicci
Thanks for the question, Laurent. Asia remains our strongest growth engine.
We did take up that full year outlook to low teens, and for Q3, we expect high single to low double-digit growth. Again, another strong quarter.
The comps do get tougher for us as we get into the second half. Q4 is our toughest compare of the year, specifically for China.
We feel really good about the momentum that we have in Asia. It's really broad-based.
It's across markets, led by China, but we've got markets like Japan and Korea growing quite nicely. We've got that ongoing brand momentum, and we've got expansion opportunities across all of our key markets in that region.
On the China front, specifically, our latest call on China in this updated outlook is mid- to high-teens growth for the full year, so that's come up a bit. Again, what we see in China is, again, underlying momentum, exceptional.
I would say the fact that the outlook is moderating when you get to the second half of it is really tougher compares and deliberate, strategic pacing of our growth and investments in that region. It's not a change in underlying momentum or a change in confidence.
I don't know, Patrice, if you want to add anything on China specifically.
Patrice Louvet
Sure. In Asia in general and then China in particular, just reiterating Justin's point around the breadth of our momentum across the region.
Obviously China from a absolute number growth rate standpoint is the highlight, but we're seeing great performance in Korea, we're seeing great performance in Japan, we're seeing really strong performance in Southeast Asia. We're going through some interesting transformation in Australia that I think will yield very promising and exciting results for that market as well.
We have an outstanding leadership group running that region. We actually just spent some time with our board in Japan and Korea a few weeks ago.
We're in very good hands there. The Asia is really playing an innovation incubator role for us as a company, and China in particular here, where it's about clienteling, personalization, social media engagement, the new platforms like Douyin, for example, and so much more.
I think, as Justin mentioned, we're pacing our growth. The underlying growth rate is strong and very healthy, but we're pacing our growth to make sure that we're strong three years from now, five years from now, 10 years from now.
We're building the right foundations for the company across these key markets. We've certainly been very excited about the response that we're getting from consumers in China across generations.
Remember, we're only in top six cities. Right?
As you think about opportunities, just like I mentioned earlier in North America, while we've been in this market for a while, there's still significant runway for us. Obviously, that's also true for the Chinese market, it goes back to our diversified growth model, which has many geographic expansion opportunities for the company.
Thank you for your question, Laurent. Given the time, we're going to stop here.
Thank you, everyone, for joining us today. We wish you and your families a wonderful Ralph Lauren Christmas and holiday season, and we look forward to reconnecting in early February to share our third quarter results.
Until then, take care, and have a great day.
Operator
Ladies and gentlemen, that does conclude your conference for today. Thank you for your participation.
You may now disconnect.