Sotera Health Company
NNASDAQ:SHCQ3 FY2026 · Earnings Call TranscriptNovember 3, 2026
Operator
Operator: Morning, and welcome to the Sotera Health third quarter 2026 conference call. All participants will be in a listen-only mode.
Should you need assistance, please signal a conference specialist by pressing the star key followed by zero. After today's presentation, there will be an opportunity to ask questions.
To ask a question, you may press star then one on your touch-tone phone. To withdraw from the question queue, you may press star then two.
Please note, this event is being recorded. I would now like to turn the conference call over to Vice President of Investor Relations, Mr.
Jason Peterson. Mr.
Peterson, the floor is yours, sir.
Jason Peterson
Good morning, and welcome to Sotera Health's third quarter earnings call. Today's press release and earnings presentation are available on the Investor section of our website at soterahealth.com.
This webcast is being recorded, and a replay will also be available on the Investor section of the Sotera Health website shortly after the call. Joining me today are Chief Executive Officer Alton Shader, Chief Financial Officer Jon Lyons, and Executive Chairman Michael Petras.
During today's call, some of our comments may be considered forward-looking statements. The matters addressed in these statements are subject to risks and uncertainties that could cause actual results to differ materially from those projected or implied.
Please refer to Sotera Health's SEC filings in the forward-looking statements slide at the beginning of the earnings presentation for a description of these risks and uncertainties. The company assumes no obligation to update any such forward-looking statements.
Please note that during the discussion today, the company will present both GAAP and non-GAAP financial measures, including adjusted EBITDA, adjusted EBITDA margin, tax rate applicable to adjusted net income, adjusted net income, adjusted EPS, net debt, and net leverage ratio, as well as constant currency comparisons. A reconciliation of GAAP to non-GAAP measures for all relevant historical periods may be found in the schedules attached to the company's press release and in the supplemental slides to the earnings presentation.
The operator will be assisting with the Q&A portion of the call today. Please limit yourself to one question and one follow-up.
For further questions, feel free to reach out to the Investor Relations team. I will now turn the call over to Sotera Health CEO, Alton Shader.
Alton Shader
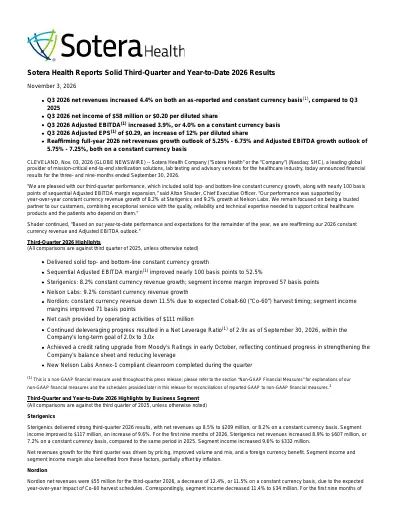
Good morning, and thank you for joining us. Today we reported solid top and bottom-line growth versus the third quarter of 2025, driven by strong execution, and sequential adjusted EBITDA margin improvement of nearly 100 basis points.
For the third quarter, we delivered constant currency revenue growth of 4.4% and constant currency adjusted EBITDA growth of 4% versus the same period last year. Sterigenics continued to perform well, generating 8.2% constant currency revenue growth and 57 basis points of segment income margin expansion, despite experiencing some softness in the med device market during the quarter, which has continued into the early part of Q4.
Nelson Labs delivered another strong quarter, with revenue increasing 9.2% on a constant currency basis, as the team continued to execute on complex projects to support our customers' regulatory needs. As expected, Nordion results reflected the timing of Cobalt-60 harvest schedules.
The Nordion team did a great job delivering critical Cobalt-60 shipments for their customers and expanded segment income margins by 71 basis points. Based on our year-to-date performance and our current visibility into the remainder of the year, we are reaffirming our constant currency revenue and adjusted EBITDA outlook for 2026.
At Sotera Health, we work tirelessly to help ensure the safety and availability of healthcare products that millions of patients rely on every day. Before John reviews the financials in more detail, I want to provide some additional context around an example we shared on our second quarter call that highlights how our teams make a meaningful difference for customers and patients.
As we've discussed previously, customers regularly turn to Nelson Labs when they face time-sensitive and complex challenges. During the second and third quarters, a customer of ours faced an urgent regulatory testing need involving a product used in a significant percentage of surgeries performed around the world.
The Nelson Labs team quickly mobilized its scientific and technical expertise, completed the required testing on an accelerated timeline, and helped the customer maintain the availability of a critical healthcare product. While this was one project, the impact was far broader.
By helping our customer address a time-sensitive challenge, our team played an important role in supporting tens of millions of patients who rely on these critical medical procedures. This is exactly what we mean when we talk about putting customers first and delivering on our mission of Safeguarding Global Health.
I will now hand it off to John, who will walk us through the financials.
Jon Lyons
Thank you, Alton. I'll begin with an overview of our consolidated financial results, followed by performance highlights from each of our business segments.
I'll then review the balance sheet, cash generation, and capital allocation before concluding with an update on our 2026 outlook. On a consolidated, total company basis, third quarter revenues increased 4.4% on both an as-reported and constant currency basis to $325 million, as compared to the third quarter of 2025.
Net income on a GAAP basis for the quarter was $58 million, or 20 cents per diluted share. Adjusted EBITDA improved by 3.9% to $171 million, or 4% on a constant currency basis, while adjusted EBITDA margins expanded sequentially by nearly 100 basis points to 52.5%.
On a year-to-date basis, adjusted EBITDA margins were up 8 basis points. Interest expense for the third quarter was $34 million, a $5 million improvement versus the prior year period, driven by our repricing actions and last year's $75 million term loan paydown.
Adjusted EPS increased to 29 cents per diluted share, an improvement of 12% versus the prior year. Now let's review our segment performance.
Sterigenics delivered revenue growth of 8.5% to $209 million, or 8.2% on a constant currency basis, driven by favorable pricing of 4.8%, increased volume and mix of 3.4%, and a foreign currency benefit of 30 basis points. Segment income increased 9.6% to $117 million, or 9.2% on a constant currency basis, reflecting continued operating leverage and strong execution.
Segment income margin improved 57 basis points year-over-year to 56.1%. In Nelson Labs, revenue grew 8.8% to $61 million, or 9.2% on a constant currency basis.
Growth was driven by strong volume mix of 6.6% and favorable pricing of 2.6%, partially offset by a 40 basis point foreign currency headwind. Revenue growth exceeded expectations as we saw an increase in expert advisory services activity in the quarter.
Nelson Labs segment income rose 2.5% to $19 million, or 3% on a constant currency basis. Segment income margin declined 199 basis points to 32.1%, driven primarily by business mix.
Nordion's third quarter revenue was $55 million, down 12.4%, or 11.5% on a constant currency basis. Favorable pricing of 2.2% was offset by a volume mix decline of 13.7% and a foreign currency headwind of 90 basis points.
I would also like to mention that although Nordion's revenue was down for the quarter, it did come in ahead of our expectations, driven by earlier than anticipated timing of certain shipments. Nordion's segment income decreased 11.4% to approximately $34 million, or 10.4% on a constant currency basis.
Margin performance remained strong with segment income margin improving 71 basis points versus Q3 2025 to 61.3%, driven by operational productivity and favorable pricing. Turning to the balance sheet, cash generation, and capital deployment.
Year-to-date, we have generated $228 million in operating cash flow, including $111 million in Q3, demonstrating solid generation during the period. Capital expenditures totaled $145 million during the first nine months of the year, including $53 million in the third quarter, supporting Sterigenics capacity expansions and EO facility upgrades, Nordion Cobalt-60 development initiatives, and the completion of a new state-of-the-art clean room at our Salt Lake City lab.
We continue to make great progress strengthening our balance sheet. Net leverage improved to 2.9 times as of September 30th, 2026, within our long-term target range of 2 to 3 times.
This progress was recognized with a credit rating upgrade from Moody's in early October. Now I'd like to turn to our 2026 full year outlook.
As Alton mentioned, we are maintaining our 2026 revenue outlook of 5.25% to 6.75% constant currency growth, with reported revenue in the range of $1.233 billion to $1.250 billion. We also remain confident in our full year adjusted EBITDA outlook of 5.75% to 7.25% constant currency growth, with adjusted EBITDA in the range of $632 million to $641 million.
These reported ranges incorporate an estimated 70 basis point foreign currency benefit for the full year, with foreign exchange anticipated to be a headwind of more than 100 basis points in the fourth quarter. We expect full year consolidated adjusted EBITDA margins to be approximately flat versus last year, with anticipated margin expansion at Sterigenics and Nordion offsetting a reduction in Nelson Labs.
Our outlook continues to assume total company pricing for 2026 to be within our long-term range, 3% to 4%. We continue to expect Sterigenics to deliver mid to high-single digit constant currency revenue growth in 2026.
Reflecting recent softness we have seen in the med device market, fourth quarter constant currency revenue growth is anticipated to be approximately 6%. At Nordion, we now expect full year constant currency revenue growth in the mid-single digits, supported by year-to-date performance and our demand expectations through year-end.
At Nelson Labs, based on our year-to-date performance, we now expect full year 2026 constant currency revenue growth in the low to mid-single digits. As we look to the fourth quarter, we expect growth to moderate from third quarter levels, while continuing to benefit from the previously mentioned expert advisory services activity.
We now project full year segment income margins to be similar to year-to-date levels. Turning to several other assumptions underlying our outlook.
Based on market rates, we are narrowing our 2026 interest expense outlook to a range of $137 million to $140 million. Our effective tax rate applicable to adjusted net income remains unchanged at 27% to 28%.
We anticipate depreciation expense to increase in 2026 modestly above the increase experienced in 2025. On a weighted average basis, we continue to expect a fully diluted share count in the range of 289 million to 291 million shares.
Taking these factors into account, we expect to remain on track to deliver adjusted EPS of 95 cents to $1.01 per diluted share in 2026. Capital expenditures are anticipated to be in the $200 to $225 million range.
We continue to expect net leverage ratio improvement compared to 2025. Finally, as usual, our outlook does not assume any M&A activity.
I'll now turn the call back over to Alton.
Alton Shader
Thank you, John. We're pleased with our performance through the first three quarters of the year and remain focused on executing against our priorities.
I continue to be impressed with our team's focus on delivering for our customers and the essential nature of our offerings across the company. With that, operator, let's open the line for questions.
Operator
Thank you, sir. To ask a question, you may press star then one on your touch-tone phone.
If you are using a speakerphone, please pick up your handset before pressing the keys. If at any time your question has been addressed and you'd like to withdraw your question, please press star then two.
As a reminder, we please ask that you limit yourself to one question and a single follow-up. Please follow up with the company's Investor Relations if you have additional questions.
At this time, we will just pause momentarily to assemble our roster. The first question we have will come from Sean Dodge of BMO.
Please go ahead.
Sean Dodge
Thanks. Good morning.
Maybe just on the guidance. Your range for EBITDA this year is a little wider going into Q4 than it has been historically.
Is that just a philosophical change, or does it have to do with something with timing unknowns around Nordion, maybe just kind of why the wider outlook? Then if you could just kind of walk us through what the bigger unknowns are at this point going into kind of late Q4.
Jon Lyons
Hey Sean, thanks for the question. I'll have to go back and look, I pretty sure we haven't narrowed our EBITDA consistently over the years.
I think it's a pretty typical range for us if you look over the last 3 to 5 years. There are some of course moving pieces as we finish up the year here, nothing's changed really that led to this.
Sean Dodge
Okay. Then maybe on Nordion, I know revenue was down because the timing around harvests, but if you can share just a little bit more detail on how you were able to improve margins there despite the lower revenue?
Jon Lyons
No. Thanks Sean.
We had to some good operational execution, really in the quarter and year-to-date. We had a couple of things that we had to work through from last year that the team's been focused on, just in the day-to-day execution of the operation, and we've managed to improve that and that really led to the performance.
Really good work by the team to drive that.
Sean Dodge
Great. Thanks again for the time.
Jon Lyons
Thanks, Sean.
Alton Shader
Operator, can you go ahead and move on to the next question, please?
Operator
Yes, sir. We have Luke Sergott of Barclays.
Luke Sergott
Hey guys, thanks for the question here. I guess to start off, you guys talked about seeing some softness in the med device side.
Excuse me if I missed this, I've been jumping around between calls, but can you talk about the visibility and how that frames into your 4Q, but more importantly, what your customers are saying, like what the bookings at the orders, I know it's more short cycle, but how you're thinking about this flowing through to '27?
Alton Shader
Thanks for the question. I'll take that one.
High level, we performed well in Q3 and continue to have confidence in our full year outlook, and I'll call out really strong quarters from Sterigenics with the 8.2% constant currency growth and Nelson Labs with the 9.2% constant currency growth. As we look to Q4, we do expect some moderation in the Nelson Labs growth versus the 9.2% we delivered in Q3, but we do expect to that business to grow in Q4.
For Sterigenics, we remain confident in our full year outlook for the mid to high-single digits of growth, but we did experience some softness at the end of Q3 and beginning of Q4 here. Based on what we're seeing in the business and what our customers are communicating to us, we are not expecting the sequential Q4 growth that we normally see in Sterigenics, and this really informed our guide.
Luke Sergott
Okay. Then I guess as you think about that lack of sequential growth, look, it's a big question is just how this decel keeps going through, or are we going to bottom out here in the mid of '27 and pick up from there?
Alton Shader
We're obviously in the midst of our planning processes for 2027 now, and we'll communicate what we expect in 2027 during our Q4 earnings call here in February of '27. Obviously, we're staying very close to our customers and doing all we can to understand the kind of the reduction in optimism that they have communicated to us as we head here into Q4.
Luke Sergott
Thank you.
Operator
Apologies for the delay before, everyone. The next question will come from Evie Koslosky of Goldman Sachs.
Please go ahead.
Evie Koslosky
Great, thanks for taking my questions. Wanted to start on Nelson Labs.
I know you mentioned the one large customer in the quarter. I guess, and it sounds like a deceleration is expected next quarter, but maybe if you could help us quantify how much impact that was in 3Q and then what was sort of the underlying growth in that market?
Alton Shader
For Nelson Labs, we're obviously pleased with the third quarter performance of the 9.2% constant currency growth. Team's doing a really nice job of serving their customers and really helping them out with critical testing and remediation needs.
As you mentioned, we do not expect another quarter in Q4 of growth like we saw here in Q3, but we do have a lot of confidence in that business as we move forward. As we increased our guide from low-single digits to low to mid-single digits, and we did see some strength out of the EAS business here in Q3, and we do expect to see additional growth from that business in Q4 as well.
Evie Koslosky
Great. Then on the 4Q guide for Sterigenics, understand the med device comments, I think that's something we've seen on a broad basis, but maybe if you could talk through some of the more idiosyncratic factors, like the X-ray facility coming online, the larger customer that was coming online in the back half, and how those should impact 4Q, and then also on pricing, that came in a bit above our expectations for the quarter.
Maybe just talk through what's baked into that 6% for pricing in fourth quarter.
Alton Shader
Sure. Again, pleased with our results in Q3 here, 8.2% constant currency growth, 120 basis points of sequential growth at the top line, team did a really nice job.
We have benefited from the three factors we've discussed in the past with the favorable shutdown days, the outsource customer that we have, as well as the North Carolina X-ray facility, those did contribute to our growth in Q3 and we expect them to contribute to the growth in Q4. I'll note that, even though we're talking about a 6% constant currency growth in Q4, we are seeing relatively stable demand in this business.
We mentioned that we're not seeing the sequential growth that we normally expect, we are seeing essentially a flat revenue performance in Q4 from Sterigenics versus Q3. Overall, while we have seen a little bit of softness here at the beginning of Q4, we've got a pretty stable environment right now, and this is an incredibly resilient business.
It has been over the years, and we continue to see that here as we finish up the year.
Evie Koslosky
Great, and then just pricing baked into that? Is it kind of still the upper end of the four the 3% to 4%, or is there upside levers to that?
Alton Shader
Pricing in Sterigenics has really been consistent, and it obviously reflects a number of factors at the top of that list is the value that we deliver to our customers every day. We are at the higher end of that range, and we would expect to stay at the higher end of that range here in Q4 as well.
Evie Koslosky
Thank you.
Operator
Next, we have Casey Woodring of JP Morgan.
Casey Woodring
Great. Thanks for taking my questions.
Maybe just to follow up on some of the comments around med device. You said that the softness started at some point in 3Q.
Can we just get a sense of when in the quarter you started to see that and then kind of thoughts around the more recent performance that you called out in 4Q? Is there any sort of I guess chance that things could get worse and things deteriorate further based on some of the medtech prints we've seen so far this quarter?
Thanks.
Alton Shader
Sure. We started seeing some of the softness kind of mid to late Q3, and primarily that softness came from our European customers, so that's been the primary impact that again we've saw at the end of Q3 and here at the beginning of Q4.
Our guide includes what we're seeing in the marketplace and what we are hearing from our customers, and again, in Q4 sequentially we're going to be flat to Q3, we're not seeing anything really much more than a pretty stable demand environment here. Again, as we've gone and really gotten close to our customers here, essentially this is a reduction in some of their optimism for Q4.
It's not uniform across any specific segment or any set of customers, but you bring all the data together and you've got this reduction in optimism. We've included that in our guide, and we're confident in our guide.
Casey Woodring
Got it. Understood.
Then maybe just one more from me, any just update on litigation in terms of number of plaintiffs in California, and anything along those lines? Thank you.
Alton Shader
Absolutely. Regarding litigation, we've got a strategy to defend the company and we are executing against that strategy, and I can give you an update on a couple of the key cases here.
In Georgia, we've got a deadline for an appellate decision in spring of 2027. In California, we've got our first trials are scheduled for January and April of 2027.
In Illinois, we've got all our cases are assigned to a single judge at this point, and we're in the midst of pre-trial proceedings.
Casey Woodring
Thank you.
Alton Shader
Thanks.
Operator
Next, we have David Windley of Jefferies.
David Windley
Hi, thanks for taking my question. I was wondering if you could comment on you've referenced a large customer, the progress of the outsourcing decision and execution.
Has that event, I'll call it, driven or catalyzed any additional conversations of the same ilk?
Alton Shader
I'm assuming you're commenting on the one outsourced customer we've talked about previously, that's all on track. That's going well and that was a contributor to our growth in Q3 and will be a contributor to our growth in Q4.
Our commercial team continues to do everything they can to build our commercial pipeline, and within that commercial pipeline are a number of programs and products that would require customers to outsource. I don't have any specific updates for you around specific programs, projects, etc.
Could
David Windley
I ask on Nelson with EAS having shown some strength for a couple of quarters running now, I think, and you're expecting again in the fourth quarter, how are you viewing the mix evolution in that business? Not EA in Nelson, to be clear, the mix in Nelson.
Alton Shader
Just to clarify, we really saw strength in EAS here in Q3. We did not see strength in EAS in Q2, some of that growth that we saw in Q2 was in our core lab testing.
We did see growth here and more growth associated with EAS in Q3 than we had previously. We do expect growth to be driven in some part by EAS in Q4 as well.
David Windley
How do you expect that to evolve?
Alton Shader
Going forward, obviously, let me take a step back here. We've got a project component to the Nelson Labs business, and within EAS, those tend to be higher concentration of project-based programs and opportunities.
We don't expect long-term EAS to be a larger percentage of the business and have this be a consistent mix shift towards EAS going forward.
David Windley
Got it. Thank you.
Operator
Next, we have Ryan Halsted of RBC. Please go ahead.
Ryan Halsted
Good morning, thanks for taking my questions. Sticking with Nelson Labs and following on the strength in that segment over the past few quarters being somewhat broad-based across the different business lines, can you just confirm how are you viewing that business in the lens of cross-business unit selling?
Do you kind of see this as opportunity to cross-sell and how are you executing on your kind of refreshed strategy to really try to drive that XBU strategy?
Alton Shader
Absolutely. The cross-business unit opportunity is significant for our organization.
We've got approximately 70% of our Sterigenics and Nelson Labs revenue comes from shared customers, and we obviously need to focus on penetrating these accounts with our full offering, and Nelson Labs absolutely will benefit from this work. We would expect over time core lab testing to benefit from the work that we're doing cross-business unit, and we've got a number of initiatives in place now to drive this growth across the overall organization, which again Nelson Labs will benefit from.
Ryan Halsted
Great. Then turning to capital allocation, can you just confirm, are you on track to complete all the facility upgrade investment?
Then just looking ahead, obviously you're now within your leverage range, how are you thinking about capital priorities into 2027?
Alton Shader
Sure. We are on track to complete the EO facility enhancements here in Q1 2027, team's done a very nice job of that.
We're also pleased with our progression of our balance sheet, we're at 2.9 times net leverage today, and we're within our long-term target of 2 to 3 times. Our approach to capital deployment is ultimately driven by where we see the best opportunities to create long-term shareholder value, and we have not materially changed our approach.
We continue to prioritize the organic growth investments, as well as strategic M&A opportunities where we can drive clear value with a focus on sterilization services. We'll continue to work with our board to evaluate the full range of other capital deployment opportunities, including share repurchase, debt paydown, etc., but ultimately we're going to deploy this capital to the areas where we think we can optimize our long-term shareholder value.
Ryan Halsted
Great. Thank you.
Operator
Next, we have Jason Bednar of Piper Sandler.
Jason Bednar
Hey, morning everyone. A couple follow-ups here from us, just on some topics that have been discussed this morning.
First maybe the obligatory question on the med device topic. Alton, you mentioned I think the softness was mostly tied to your European customer base, and hope I didn't hear that wrong, but have you seen any shifts in volume demand from your U.S.
med device customer base, or is that more stable? Then I just want to be clear that what you're seeing is specific to end-market volumes in September that persisted here in the fourth quarter.
It's not a function of channel destocking like one of your peers has been referencing with their business.
Alton Shader
Thanks for the question. Again, we saw the softness starting in Q3 and extending here into Q4, and it is primarily in Europe.
We're seeing the softness more in Europe than we are seeing here in the U.S. When it comes to segments, again I mentioned this before, but it's not uniform.
Within our customer base, we're seeing variability across the segments and end markets, but overall the balance here is we are seeing an overall reduction in optimism from our customers in Q4. I think that's pretty consistent to what we've seen from a number of the medtech companies who have announced their results over the course of the last few weeks, and it's pretty in line with what we're seeing externally here.
Jason Bednar
Got it. Then bit of a follow-up in the prior question, can talk a little bit about your CapEx plans here?
I think in the past, you've referenced a significant or a meaningful step-down in spending now that you're through a lot of these facility investments, you're rolling off some other big CapEx projects. As we think about the magnitude of inflection in cash flow next year, can you give us any guardrails to think about what this actually looks like?
I think the Street's modeling a $50 million step-down in CapEx. Is that a fair number?
Would you have us any lower, any higher than that, just trying to get a sense as we think about '27 cash flow?
Jon Lyons
Hey Jason, thanks. Appreciate the question.
We definitely see a meaningful step-down in CapEx next year. We're well on track to deliver the free cash flow objectives that we laid out in Investor Day, of $500 to $600 million of free cash flow over the period.
One of the moving pieces is just seeing exactly where we land this year, and then finalizing our plans with the board on the different programs. We expect a meaningful step-down.
It's a little premature for me to tell you exactly how much, just given the uncertainty related to just closing out the year. We feel good about the execution, but you can always have a few moving pieces as we close out the year, and then again, finalizing the budget with the board.
Jason Bednar
All right, understood. Thanks, guys.
Alton Shader
Thanks.
Operator
Next, we have Michael Polark of Wolfe Research.
Michael Polark
Hi, good morning. On the topic of the softer medical device customer trend in Sterigenics out of Europe, we've heard labor strikes, war, government budget tightness in Europe, and so we can corroborate that.
It sounds like you're not seeing or saying anything in the U.S. Are you in the guidance for Sterigenics, bracing for any U.S.
softness, or no, this modeling is contained to what you're hearing out of your European customers?
Alton Shader
Thanks. We're seeing relative stability out of the U.S.
at this time, and everything that we again are seeing from our data, we're seeing in the first month of the quarter and what we're hearing from our customers is captured within our guide. Again, that 6% constant currency growth in Sterigenics translates to a relatively stable, flat revenue sequential from Q3 to Q4.
Again, I'll just highlight the fact that, over time, the Sterigenics business and really Sotera Health overall has been incredibly resilient through different economic challenges, and we do see, again, some of this softness here in Q4, but overall we feel like we've got a handle on it and the business remains very healthy and strong.
Michael Polark
On expert advisory services, I'm recalling from a couple years ago when growth was significant, if I'm recalling correctly, it was attributed at the time to some regulatory actions that customers were dealing with, recalls, remediation, stuff like that, that created a tough comp and now we've rebased and growing again. Is there a thematic behind the uptick that you would have us think about, or no, it's a project-based business and you kind of troughed out last year and now you're growing off of that?
Just any more color on what's driving the rebound there, I'd appreciate. Thank you.
Alton Shader
Sure. This is a project-based business, and the team has done a really nice job of responding to the needs of our customers, and again some of these projects did come into the business here in Q3 and we do expect additional business from these customers here in Q4 as well.
We are very focused on having a durable business here in Nelson Labs, and focused on ensuring that we have core lab growth within this business. We've had a number of initiatives in place, including new commercial leadership within Nelson Labs to ensure that we are best-in-class commercially here, and again got a lot of confidence in the team to drive durable growth in the business.
Operator
We will go ahead and proceed to Brett Fishbin of KeyBanc.
Brett Fishbin
Hey guys, good morning. Thank you so much for taking the questions.
Sorry to beat a little bit of a dead horse here, just had one more question on the med device comments. I wanted to ask if the slowdown or softness you're commenting on in Europe, is this fairly broad-based across the customers, or would you say it's more specific to a few different product areas or customers in Europe where you may have more concentration?
Alton Shader
This is more broad-based. Again, we can't say that it's happening with every customer that we have in Europe, but it's not limited to just a couple.
Again, it's not uniform across specific segments, but overall when you add up the information that we have, the conversations we're having with customers, the data that we're seeing, there is softness there overall in Europe.
Brett Fishbin
All right, great. Then just one more question on the X-ray facility project, which I believe is now online.
I was hoping you could just provide a little bit of an update on how the ramp has gone so far, and then how you're doing in just progressing towards filling more of the overall capacity on a longer-term basis there. Thank you so much.
Alton Shader
Sure. We continue to be optimistic with our investment here in the X-ray facility in North Carolina.
We had a really strong Q3. We have seen a bit of softness here in Q4 in that facility.
That said, we've got a very strong pipeline and we are confident that we're going to be able to continue to improve the utilization in that facility.
Operator
This will conclude our question-and-answer session. I would now like to turn the conference call back over to Mr.
Alton Shader for any closing remarks. Sir?
Alton Shader
Thanks, operator. We delivered another quarter of solid financial performance, and I wanted to note that I've enjoyed being on the road and connecting with many of our shareholders, and I look forward to continued engagement in the coming months.
As we move forward, we remain focused on delivering outstanding service, strengthening our customer partnerships, and delivering value for both our customers and the patients that they ultimately serve. Thanks for your continued interest in Sotera Health.
Take care, everybody.
Operator
We thank you, sir, and to the rest of the management team for your time also today. Again, the conference has now concluded.
Thank you all for attending today's presentation. At this time, you may disconnect your lines.
Thank you, take care, and have a great day, everyone.