uCloudlink Group Inc.
NNASDAQ:UCLQ1 FY2026 · Earnings Call TranscriptMay 13, 2026
Operator
Thank you for standing by and welcome to the UCLOUDLINK GROUP INC. First Quarter 2026 Earnings Conference Call.
All participants are in a listen-only mode. There will be a presentation followed by a question-and-answer session.
If you wish to ask a question, you will need to press the star key followed by the number 1 on your telephone keypad. I would now like to hand the call over to Mr.
Xichao Gao, Company Investor Relations. Please go ahead.
Daniel Gao
Thank you, operator. Hello, everyone, and thank you for joining us on UCLOUDLINK's first quarter 2026 earnings call.
The earnings release and our earnings presentation are now available on our IR website at ir.ucloudlink.com. Joining me on today's call are Mr.
Zhiping Peng, Co-Founder and Chairman of the Board of Directors; Mr. Chaohui Chen, Co-Founder, Director and Chief Executive Officer; and Mr.
Yimeng Shi, Chief Financial Officer. Mr.
Chen will begin with an overview of our recent business highlights. Mr.
Shi will then discuss our financial and operational highlights for the quarter. They will all be available to take your questions in the Q&A section that follows.
Before we proceed, please note that this call may contain forward-looking statements made pursuant to the safe harbor provisions of the Private Securities Litigation Reform Act of 1995. These forward-looking statements are based on management's current expectations and observations that involve known and unknown risks, uncertainties, and other factors not under the company's control, which may cause actual results, performance, or achievements of the company to be materially different from the results, performance, or expectations projected or implied by these forward-looking statements.
All forward-looking statements are expressly qualified in their entirety by the cautionary [statements?] statements, risk factors, and details of the company's filings with the SEC.
The company does not assume any obligation to revise or update any forward-looking statements as a result of new information, future events, change in market conditions, or otherwise, except as required by law. Please also note that UCLOUDLINK's earnings press release and this conference call include discussions of unaudited GAAP financial information and unaudited non-GAAP financial measures.
UCLOUDLINK's press release contains a reconciliation of the unaudited non-GAAP measures to the most directly comparable unaudited GAAP measures. I will now turn the call over to Mr.
Chen. Please go ahead.
Chaohui Chen
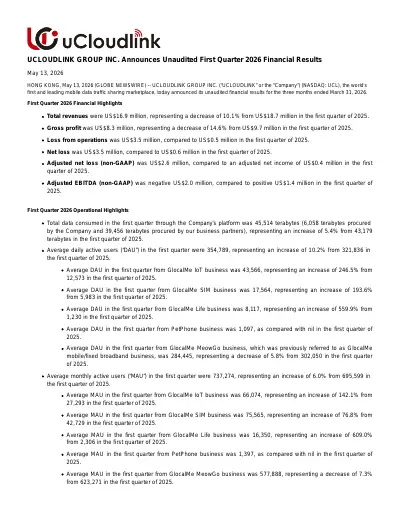
Thank you, Daniel. Good morning or evening, we deliver total revenues of US$16.9 million in the first quarter of 2026.
This result comes despite significant external headwinds, including macroeconomic volatility, weak travel demand, rising energy prices, memory chipset cost increase, and conflict-related supply chain disruption. More importantly, our new product lines have continued to warm up and scale, gradually offsetting the negative impact on our traditional business for these external headwinds.
With the continued ramp-up of new product, such as the PetPhone and UniCore Pro, revenues from our new business lines are increasing following an initial market warm-up period over the past two quarters. Each of these new product continue to make significant strategic progress during the quarter, laying the groundwork for accelerated commercial momentum going forward.
Overall, our three new growth engine, GlocalMe Life, GlocalMe IoT, and GlocalMe SIM, deliver remarkable year-over-year revenue growth of over 400%, 300%, and 170%, respectively. To accelerate commercialization and capture early market leadership, we strategically increase marketing spending during the quarter on the PetPhone and broader PetPals ecosystem.
While these investments will tamp near-term profitability and cash flow, we are confident they will yield substantial long-term payoffs and contribute to sustainable growth going forward. I will now review the highlights for each of our key business lines.
I will start with the PetPals ecosystem. Building on the exceptional global media attention and the market validation received at MWC 2026 and CES 2026 with the unveiling of our PetPals ecosystem and all-new PetCam, we launched the beta version of the PetPals app during the quarter.
This differentiated and pioneering AI-power plus social platform for the pet technology industry leverages AI technologies and the PetPhone to enable pets and their owners to communicate seamlessly, by effectively transforming the pet ownership experience into an interactive, social, and connected community. We are fostering unparalleled engagement and continuous interaction.
PetPals also allow pet owners to manage their pet care journey across three stages: before, during, and after activities. This social platform is expected to complete commercial validation in Q2 2026 and begin driving growth starting in Q3 2026.
During the quarter, average monthly active user, MAU, reached 1,397, and early beta feedback has been overwhelmingly positive, reinforcing our confidence in its user adoption and strong growth potential. Moving on to our GlocalMe Life business line, we continue to drive exponential growth with industry-first innovations.
Our UniCore Pro gained strong traction during the quarter, with the sales volume and the market adoption accelerating rapidly. By enabling a lighter, more convenient lifestyle with secure and reliable connectivity, freeing users from cumbersome device while ensuring seamless, authentic experience, GlocalMe Life solutions saw average daily activity user, DAU, during the quarter increase 559.9% year-over-year.
Turning to GlocalMe Internet of Things, IoT, our forward-looking strategy is already beginning to generate initial result. The business maintained its strong growth trajectory, with user adoption and revenue contribution continuing to expand rapidly year-over-year.
We continue to solidify our strategic position to capture the additional market share in high-growth sector, such as in-car infotainment and security cameras. Average DAU for GlocalMe IoT increased by 246.5% compared to the first quarter of the year 2025.
As of March 31st, 2026, our total IoT solutions install base reached 2.93 million. For our GlocalMe SIM business line, our Roamfree solution continues to gain strong traction and growth momentum, with average DAU increasing 193.6% year-over-year during the quarter.
This validates both our carrier partnership model and its market positioning as a permanent secondary SIM for users. Furthermore, our carrier co-insurance program has began pilot deployment, providing a highly effective, low-CapEx solutions for operators that enhance their global roaming capability.
This model is gaining strong traction and is welcome by both operators and users, confirming a robust product-market fit. Lastly, the launch of our cutting-edge Roamfree G50 Max, the world's first sky-to-ground integrated mobile connectivity hub, is expected to serve as a powerful growth engine for the coming quarter.
The Roamfree G50 Max is redefining the connectivity when it matter most. In conflict-affected market with disrupted terrestrial network, its resilient connectivity is a critical differentiator.
Powered by our AI-driven HyperConn technologies, it seamlessly switch between the terrestrial, in-flight, home Wi-Fi, creating a unique one-hub global freedom experience. It also enables satellite-based two-way messaging and emergency SOS, extending connectivity from ocean to deserts.
We expect this product to reach commercial deployment in the second quarter of year 2026. Looking beyond its market potential, the Roamfree G50 Max not only represent our high-end brand aspiration, but also focus on driving increased sales and elevating our brand across the entire portfolio of mobile connectivity solutions.
Looking ahead, we remain in the early high-growth stages of our transformation. Throughout 20 2026, we will continue investing strategically in our new growth engines.
The strong market validation from MWC 20 2026 and CES 2026, positive PetPals beta feedback, and sustained momentum in GlocalMe IoT demonstrate how our diversified business strategy remain firmly on track. Looking at the coming quarters, we expect our traditional business to gradually stabilize, reaching a level where further downside is limited.
At the same time, our new business line will continue to grow, driven by ongoing product ramp-ups and market adoption. Together, if this dual momentum, our traditional business stabilizing and our new business scaling up, continues as we expect, it is expected to further offset the external headwind that had impact our performance.
As a result, we believe the second quarter of the 2026 will be a turning point in our overall business trajectory with a return to positive year-over-year growth. We are building towards sustainable growth by scaling our user base globally and bridging the digital divide in cross-border connectivities as well as the emotional distance between people and their pets, while creating long-term value for our shareholders.
With that disciplined optimism in mind, we are confident that we have the right strategy in place to drive sustainable growth going forward. For the second quarter of the 2026, we expect total revenues to be between US$19 19.5 million and US$22.5 million, representing an increase of 0.5% to 16% compare the same period of year 2025.
I will now turn the call over to Mr. Shi.
Yimeng Shi
Thank you, Mr. Chen.
Hello, everyone. I will go over our operational and financial highlights for the first quarter 2026.
Average daily active user, DAU, and monthly active user, MAU, represents the average number of unique user engaging with our GlocalMe service on a daily and monthly basis, respectively. Both metrics show strong growth momentum in the first quarter.
Average DAU in the first quarter was 354,789, representing an increase of 10.2% from 321,836 in the first quarter of the 2025. GlocalMe IoT, GlocalMe SIM, and GlocalMe Life all delivered significant gains, with average DAU up 246.5%, 193.6%, and 559.9%, respectively, from the same period last year.
Average DAUs from our GlocalMe Roamfree business decline by 5.8% year-over-year. Average MAUs were 737,274, representing an increase of 6% from 695,599 in the first quarter of 2025.
Average MAUs from our GlocalMe IoT, GlocalMe SIM, and GlocalMe Life business saw increase of 142.1%, 76.8%, and 609% respectively, from the same period last year. Average MAUs from our GlocalMe Roamfree business decreased by 7.3% year-over-year.
In the first quarter 2026, average DATs were 327,615, with 13,414 owned by the company and 314,201 not owned by the company, representing an increase of 6.1% from the first quarter 2025. During the quarters, 58.6% of DATs were from UCLOUDLINK 1.0 international data connectivity service, and 41.4% were from UCLOUDLINK 2.0 local data connectivity service.
In March 2026, the average daily data usage per terminal was 1.57 GB. Average MATs in the first quarter were 702,805, representing an increase of 7.7% from 652,810 in the first quarter 2025.
Growth was driven by strong momentum across our three new growth engine, with average MAT for GlocalMe IoT, GlocalMe SIM, and GlocalMe Life increasings 135%, 74.1%, and 806.1%, respectively, from the same period last year. Average MAT from GlocalMe Roamfree business, which we previously referred to as GlocalMe mobile fixed broadband business, decreased by 4.1% year-over-year.
As PetPhone is a newly launched business, we only just begun to see user adoption and engagement grow during the quarters. In the first quarter, average DAU and MAUs were 1,097 and 1,397 respectively, while average DATs and MATs for PetPhone reached 368 and 789, reflecting the growing traction of this new offering.
As of March 31st, 2026, the company had 212 patents, with 183 approved and 29 pending approval, and a pool of SIM card from 397 MNOs globally. Total revenues for the first quarter 2026 were $16.9 million, representing a decrease of 10.1% from $18.7 million in the same period of 2025.
Revenues from service were $13.3 million, representing a decrease of 6.3% from $14.2 million in the same period of 2025. Revenues from service contributed 78.9% of total revenue during the first quarter of 2026 compared to 75.7% in same period last year.
Geographically speaking, during first quarter 2026, Japan contributed 32%, Mainland China contributed 30.3%, North America contributed 17.3%, and other country and regions contributed the remaining 20.4%, compared to 40.4%, 31.2%, 12.9%, and 15.5%, respectively, in same period 2025. Our gross profit was $8.3 million compared to $9.7 million in same period 2025.
Overall gross margin in the first quarter 2026 was 49.1% compared to 51.7% in same period 2025. Gross margins on service was 54.5% in the first quarter 2026 compared to 57.3% in same period 2025.
Excluding share-based compensations, total operating expenses was $10.8 million compared to $9.9 million in the same period 2025. Net loss in the first quarter 2026 was $3.5 million compared to a net loss of $0.6 million in the same period 2025.
Adjusted EBITDA was negative $2.0 million in the first quarter 2026 compared to a positive $1.4 million in the same period 2025. For the first quarter 2026, we recorded an operating cash outflow of $8.7 million compared to an inflow of $0.2 million in same period of 2025.
For the first quarter 2026, our capital expenditure were $30,000 compared to $300,000 in same period 2025. Turning to balance sheet items, our cash and cash equivalents were $28 million as of March 31st, 2026, compared to $32.8 million as of December 31st, 2025.
We continue to strengthening our financing position and believe we are well positioned to drive continued growth in our business. Operator, let's open it up for Q&A.
Thanks.
Operator
Thank you. We will now begin the question-and-answer session.
To ask a question, you may press star, then 1 on your telephone and wait for your name to be announced. If you wish to cancel your request, please press star, then 2.
If you are on a speakerphone, please pick up the handset to ask your question. Our first question today will come from Theodore O'Neill with Litchfield Hills Research.
Please go ahead.
Theodore O'Neill
Thank you for taking my questions. My first question is about the G50 Max.
In your prepared remarks, you're talking about this being interesting to the market that's in conflict zones. I'm hoping that that's a shrinking market, not a growing market.
Could you talk about some other markets where this G50 Max would be appropriate? I think you mentioned at sea and I'm thinking perhaps the very remote rural areas as well.
Chaohui Chen
I'm Chaohui Chen. Our G Max is our high-end product, is a 5G.
We can roll out 5G in over 100 countries. That's most popular we can offering the 5G in the world.
Compare like the other, our competitor like AT&T maybe just 75. The first advantage is we can provide the maximize coverage of 5G worldwide, that's first.
The second, we can provide about the 35 airline for the in-cabin 4G, 5G connection, the second. That means the business traveler in the air cabin, they can surfing.
Then it's about the satellite SOS and messaging. No matter you are in the outdoor or in the conflict area, you never lost the connection.
Number 4 is if you are in the office and at home, you of course you can get Wi-Fi available, but Wi-Fi sometime is not reliable. Sometime is unreliable.
During this case, we can backup by the 5G and 4G with multi-carrier, that enable your remote work and remote study and remote meeting never fell down. We balanced the best coverage and the best tariff.
That means one device and one account, you can enjoy the global best coverage and the best tariff. That's why we believe that's one device for every scenario, not only at home, at office.
Can solve the people have to bring the multi-device, package, a home Wi-Fi, in-cabin Wi-Fi. We have roaming eSIM or local multi-carrier tariff, then you can get the similar coverage and solution.
Now with our solution, one device, simply the one device, one account, you can get the best coverage and the tariff. That's our purpose.
Theodore O'Neill
Okay. Thank you.
My next question is about the in-car infotainment and security cameras. Can you give us any more detail about the actual market share or the growth of that exposure in that business?
Chaohui Chen
Yes, I think that's about our IoT business. We embed our CloudSIM and HyperConn solution into the in-car infotainment and CarPlay.
This majorly CarPlay devices is come from China. Major top 10 this partner all embed our solution, that means plug our CarPlay device, not only can get entertainment in the car, but also can get the network in the car.
Almost the top 10 these provider all use our solution. That's for car infotainment.
For the camera, I think that car now more and more 4G camera they in the traditional they need to plug a SIM card inside. That means if the carrier network has some problem or coverage adjustment, and you have to go to the high place to replace SIM card for the camera.
It's very inconvenient, but with our solutions, because 4G is more popular, the price similar like Wi-Fi camera. You can see the 4G camera, the volume of the market share in the camera market is bigger and bigger.
For the 4G camera, I think that currently more and more is the top from China provider embed our software solution into their camera. That means the end user still can use the SIM slot to put into SIM card, but it's expensive and coverage is poor.
Use our solution, not only get a benefit from the better tariff, but also can get cross-carrier coverage. That's you can see our market share in this market grows dramatically.
You can see our installation volume is about 2. 2.9 3.9 million pieces for shipment.
In the six year in the six months later, they will turn into the package and with our in the operation. About from shipment to the user and adopt our solution need a six months.
You can see six months later, we will get more users, far more than users than currently.
Theodore O'Neill
Thank you. My last question is about supply chain issues.
You mentioned in the prepared remarks about memory prices being a headwind, but I was also wondering are you seeing any supply chain issues in terms of availability?
Chaohui Chen
Yes, I think compare last year, memory chip is almost 5 to 10 times higher. That had heavily impact the cost of the device.
We think a lot of ways. One side, we try to redesign to reduce the memory size and to lower the cost.
Also we looking the instead of the Chinese local memory. All this we can overcome some part of the memory price going up, but we can't offset the total because the price is too high.
That definitely with some impact to our selling price. You can see our not only 2B and 2C selling price for the device is higher, about 20%, 30% up than compared last year.
Theodore O'Neill
Thank you very much.
Operator
Again, if you have a question, please press star, then 1. As there are no further questions at this time, I would like to hand the call back over to Mr.
Gao for any closing remarks. Please go ahead.
Daniel Gao
Thank you once again for joining us today. If you have further questions, please feel free to contact UCLOUDLINK's Investor Relations through the contact information provided on our website or speak to our investor relations firm, Christensen Advisory.
We look forward to speaking with you all again on our next quarterly call. Thank you.
Operator
That does conclude our conference for today. Thank you for your participation.
You may now disconnect.
Chaohui Chen
Thank you.