uCloudlink Group Inc.
NNASDAQ:UCLQ2 FY2026 · Earnings Call TranscriptAugust 18, 2026
Operator
Thank you for standing by, and welcome to the UCLOUDLINK Second Quarter 2026 Earnings Conference Call. All participants are in a listen-only mode.
There will be a presentation followed by a question-and-answer session. If you wish to ask a question, you will need to press the star key followed by the number 1 on your telephone keypad.
I would now like to hand the conference over to Mr. Daniel Gao, Company IR.
Please go ahead.
Daniel Gao
Thank you. Hello, everyone, and thank you for joining us on UCLOUDLINK's Second Quarter 2026 Earnings Call.
The earnings release and our earnings presentation are now available on our IR website at ir.ucloudlink.com. Joining me on today's call are Mr.
Zhiping Peng, Co-Founder and Chairman of the Board of Directors; Mr. Chaohui Chen, Co-Founder, Director and Chief Executive Officer; and Mr.
Yimeng Shi, Chief Financial Officer. Mr.
Chen will begin with an overview of our recent business highlights. Mr.
Shi will then discuss our financial and operational highlights for the quarter. They will all be available to take your questions in the Q&A section that follows.
Before we proceed, please note that this call may contain forward-looking statements made pursuant to the safe harbor provisions of the Private Securities Litigation Reform Act of 1995. These forward-looking statements are based on management's current expectations and observations that involve known and unknown risks, uncertainties, and other factors not under the company's control, which may cause actual results, performance, or achievements of the company to be materially different from the results, performance, or expectations projected or implied by these forward-looking statements.
All forward-looking statements are expressly qualified in their entirety by the cautionary statements, risk factors, and details of the company's filings with the SEC. The company does not assume any obligation to revise or update any forward-looking statement as a result of new information, future events, changes in market conditions, or otherwise, except as required by law.
Please also note that UCLOUDLINK's earnings press release and this conference call include discussions of unaudited GAAP financial information and unaudited non-GAAP financial measures. UCLOUDLINK's press release contains a reconciliation of the unaudited non-GAAP measures to the most directly comparable unaudited GAAP measures.
I will now turn the call over to Mr. Chen.
Please go ahead.
Chaohui Chen
Thank you, Daniel. Good morning, or good evening, everyone.
Total revenues for the quarter were US$18.2 million, reflecting the continued impact of macroeconomic headwinds, geopolitical tensions affecting outbound travel from China, and a significant surge in memory chip costs. Our UCLOUDLINK 1.0 international data connectivity services remained under pressure from these factors.
However, this impact is increasingly being offset by the rapid scaling of our UCLOUDLINK 2.0 local data connectivity business, which delivered strong growth, particularly from our GlocalMe IoT business. We expect our UCLOUDLINK 2.0 and new business lines to fully offset the continued contraction in our 1.0 international business by the third quarter, as we continue to execute on our strategic priorities.
We continued to see strong momentum across our new product portfolio during the second quarter. GlocalMe IoT and UniCord Pro, in particular, gained solid traction, with revenue contribution steadily increasing as they transitioned out of the initial market warm-up phase.
Each reached key strategic milestones during the quarter, positioning us well for accelerated commercialization going forward. Across our new growth engines, revenues from GlocalMe IoT and SIM increased by 392.4% and 78% year-over-year, respectively.
To drive early adoption and build market leadership, we maintained an elevated level of investment in marketing for the PetPhone and PetPogo ecosystem during the quarter. I will now review the highlights for each of our key business lines.
I will start with GlocalMe IoT, which saw its installed base expand further, with monthly orders now contributing meaningfully to revenue and business operating profitability on a consistent basis. In the second quarter, revenue from GlocalMe IoT grew 392.4% year-over-year.
Our total installed base reached 3.34 million units, and MAU grew 210% year-over-year. User adoption is growing rapidly across key verticals as we further solidify our position in high-growth sectors, including in-car infotainment and security cameras.
Moving on to our PetPhone ecosystem, which has undergone a comprehensive upgrade into a dedicated pet AI agent, building on the AI-power plus social model we pioneered in the fourth quarter. This marked a major step forward in functionality and performance, redefining AI-powered communication between humans and their pets.
The agent can precisely sense a pet's condition and emotional state and intelligently support owners at every stage of care, from prevention through real-time response and engagement, delivering a seamless pet care experience. This powerful agent creates enormous opportunities across pet health, pet housing, veterinary care, pet safety, and pet data analytics, each of which we see a source of new value creation.
As consumer acceptance of AI pet services grows, we expect to build both valuable data assets and a leading position in pet AI. We are now expanding our pet AI capabilities across communication, safety, and health management.
On the marketing front, we have made significant progress in branding and promotional efforts, generating substantial external attention, with select content pieces reaching tens of millions of views in major platforms such as TikTok, Instagram, etc. We look forward to achieving even greater breakthroughs in the second half of the year.
Turning to our GlocalMe Life and SIM business lines, where our strategy is beginning to generate results. GlocalMe Life solutions saw DAU growth explode, increasing by 801.6% year-over-year, reflecting strong market adoption of the new product line.
GlocalMe SIM continued to steadily expand as well, with DAU increasing 132% year-over-year. Our eSIM solution is gaining strong momentum, leading the market in China and building market share steadily across East Asia and the wider Asia-Pacific region.
Together, these results show two product lines at different stages of maturity, with GlocalMe Life growing rapidly with exceptional triple-digit growth and GlocalMe SIM scaling consistently. Our premium NuuGo G50 Max is the world-pioneering sky-to-ground integrating mobile connectivity hub, delivering seamless connectivity across satellite, flight, and ground networks.
It offers the broadest 5G countries coverage in the industry, spanning nearly 100 countries, and perform reliably across wide range of scenario from the urban environment to in-flight travel. Powered by our AI HyperConn technology, the G50 Max has built a market-leading position in the US$500+ premium MiFi segment, and has set a new benchmark for premium mobile connectivity solutions.
While our UCLOUDLINK 1.0 international data connectivity business has been affected by macro headwinds, these same conditions has create new opportunities for the G50 Max and the premium solutions, driving demand for resilient, reliable connectivity in critical environments. We also made solid progress and create new and strong revenue with our newly launched 4G and 5G CPE products during the second quarter for local connectivity services.
Both have demonstrated stable performance and successfully passed small-batch market validation, receiving positive market feedback. Several large orders are currently under negotiation, and we expect to accelerate market deployment and drive stronger growth in Q3.
We also achieved notable recognition during the quarter, winning the Customer Impact Award at the MVNOs World Congress in year 2026, and being shortlisted for Leading Consumer MVNO Super Brand, further validating our technology leadership and market positioning. Looking ahead, we remain focused on strengthening operational management and cost discipline, with a clear priority on improving cash flow.
Together with the ongoing commercial progress of the PetPogo AI and social PetPhone, the ramp-up of NuuGo G50 Max, and the continued expansion of GlocalMe IoT, CPE R50 and R55, we believe these efforts will position us to navigate the current market environment and emerge stronger. We remain committed to bridging the digital divide in cross-border connectivity as well as the emotional distance between people and their pets, while creating long-term value for our shareholders.
With that disciplined optimism in mind, we are confident that we have the right strategy in place to drive sustainable growth going forward. I will now turn the call over to Mr.
Shi.
Yimeng Shi
Thank you, Mr. Chen.
Hello, everyone. I will go over our operational and financial highlights for the second quarter of 2026.
Average daily active user, DAU, and monthly active users, MAUs, represent average number of unique users engaging with our GlocalMe services on a daily and monthly basis, respectively. Both metrics recorded robust growth in the second quarter.
Average DAUs in the second quarter were 376,376, representing an increase of 13.3% from 332,323 in the second quarter of 2025. GlocalMe IoT, GlocalMe SIM, and GlocalMe Life all achieved substantial growth, with average DAUs up 277.3%, 132%, and 801.6%, respectively, from the same period last year.
Average DAU from our GlocalMe Roaming business declined by 7.3% year-over-year. Average MAUs were 744,966, representing an increase of 6.6% from 698,862 in the second quarter of 2025.
Average MAUs from our GlocalMe IoT, GlocalMe SIM, and GlocalMe Life business lines saw increase of 210%, 53.8%, and 599.7%, respectively, from the same period last year. Average MAU from our GlocalMe Roaming business decreased by 10.1% year-over-year.
In the second quarter of 2026, average DATs were 341,511, with 12,763 owned by the company and 328,748 not owned by the company, representing an increase of 7.4% from the second quarter 2025. During the quarter, 56.3% of DATs were from UCLOUDLINK 1.0 international data connectivity services, and 43.7% were from UCLOUDLINK 2.0 local data connectivity services.
In June 2026, the average daily data usage per terminal was 1.5 GB. Average MATs in the second quarter were 706,382, representing an increase of 6.5% from 663,197 in the second quarter of 2025.
Growth was driven by strong momentum across our three new growth engines, with average MATs from GlocalMe IoT, GlocalMe SIM, GlocalMe Life increasing 93.6%, 35.4%, and 843.2%, respectively, from the same period last year. Average MAT from GlocalMe Roaming business decreased by 5.7% year-over-year.
Following the stable growth last year, PetPhone continued to gain traction, with user adoptions and engagement increasing further during the quarter. In the second quarter, average DAU and MAUs were 1,519 and 1,845, respectively, while average DATs and MATs for PetPhone reached 507 and 1,028, reflecting the growing traction of this new offering.
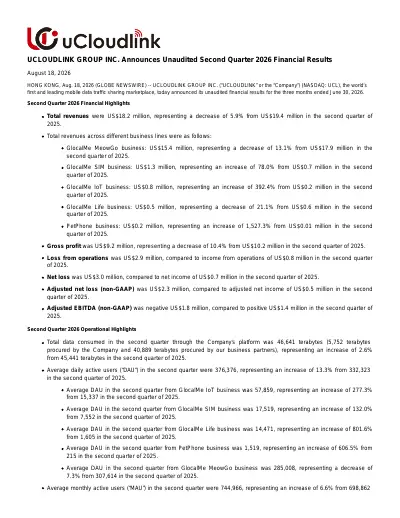
As of June 30, 2026, the company had 212 patents, with 184 approved and 28 pending approval, and a pool of SIM cards from 398 MNOs globally. Total revenue for the second quarter of 2026 were $18.2 million, representing a decrease of 5.9% from $19.4 million in the same period 2025.
Total revenue across different business lines were as follows: GlocalMe Roaming business, $15.5 million, representing a decrease of 13.1% from $17.9 million in the second quarter 2025; GlocalMe SIM business, $1.3 million, representing an increase 78% from $0.7 million in the second quarter 2025; GlocalMe IoT business, $0.8 million, representing an increase of 392.4% from $0.2 million in the second quarter of 2025; GlocalMe Life business, $0.5 million, representing a decrease of 12.1% from the $0.6 million in the second quarter 2025; PetPhone business, $0.2 million, representing an increase 1,527.3% from $0.01 million in the second quarter of 2025. Revenue from services were $13.3 million, representing a decrease of 9.2% from $14.6 million in the same period of 2025.
Revenue from services contributed 72.9% of total revenue during the second quarter 2026, compared to 75.5% in the same period last year. Geographically speaking, during the second quarter 2026, Japan contributed 36%, Mainland China contributed 30.3%, North America contributed 13.5%, and other countries and regions contributed the remaining 20.2%, compared to 33.6%, 33.2%, 15.3%, and 17.9%, respectively, in the same period of 2025.
Our gross profit was $9.2 million, compared to $10.2 million in the same period of 2025. Overall gross margins in the second quarter of 2026 was 50.2%, compared to 52.8% in the same period 2025.
Gross margins on services was 59.1% in the second quarter 2026, compared to 56.6% in the same period 2025. Excluding share-based compensations, total operating expenses were $11.5 million, compared to $10.1 million in the same period 2025.
Net loss in the second quarter 2026 was $3 million, compared to net income of $0.7 million in the same period 2025. Adjusted EBITDA was negative $1.8 million in the second quarter 2026, compared to a positive $0.4 million in the same period of 2025.
For the second quarter of 2026, we recorded an operating cash outflow of $3 million, compared to an outflow of $0.9 million in the same period 2025. For the same period second quarter 2026, our capital expenditure were $0.04 million, compared to $0.2 million in the same period 2025.
Turning to balance sheet items, our cash and cash equivalents were $25.2 million as of June 30, 2026, compared to $28 million as of March 31st, 2026. We continued strengthening our financial position, and we believe we're well positioned to drive growth in our business.
Turning to our outlook, for the third quarter 2026, we expect total revenue to be between $19 million and $22 million, representing a decrease 10.4% to an increase of 3.8% compared to the same period of 2025. For the full year 2026, we now expect total revenue to be in the range of $75 million to $85 million, compared with the range of $85 million to $100 million we previously announced.
We are revising our full-year guidance in light of the persistent macroeconomic challenges and global trade headwinds, which have had and may continue to have a broader impact across industries. This estimate reflects our current view of market and operating conditions and customer demand, which are subject to change.
With that, operator, let's open it for Q&A.
Operator
Thank you. If you wish to ask a question, please press star 1 on your telephone and wait for your name to be announced.
If you wish to cancel your request, please press star 2. If you are on a speakerphone, please pick up the handset to ask your question.
Your first question comes from Theodore O'Neill with Litchfield Hills Research. Please go ahead.
Theodore O'Neill
Oh, thank you for taking my questions. I have two questions this morning.
The first is about memory chips and sort of the supply chain of semiconductors in general. You've cited here, which everyone has been seeing, is memory chip cost increases.
What are you doing to ameliorate that, and are you seeing other supply chain issues in the semiconductor area as well?
Yimeng Shi
I think there are several impacts because I think the supply chain for chipset and the AI volume demand for the supply chain in China. For the memory chip, everyone knows it's almost a 5 to 10 times increase.
It's impact our sales price for the help for our customer. In the early quarter, we increased the more storage, try to offset the price increasing first.
You can see that's why our cash flow was somehow the impact because we increased the memory chip storage first. The second, you can see we have to cover some cost in chipset cost increasing.
In the second half years, several months later, we increase our sale price. We have to consider the I think the customer acceptance for the price.
That's number two. Number three, and also so we have R&D revise.
For some large memory and expensive memory, we try to I think revise our hardware, to reduce the memory requirement. I think that's the number three.
Finally, and also so we also so like a PCB, like all these components extend the period and the cost also is going up. I think indeed this year is worse in supply chain for our product, for like MiFi, like our PetPhone, and our pet cam to the customer.
Theodore O'Neill
Thank you. My other question is about GlocalMe Life business.
Here in the prepared remarks, GlocalMe Life business revenue decreased year-over-year, but the average daily active users increased over the same period. Were they spending less money?
I was wondering if you could explain why one's down, the other one's up.
Chaohui Chen
Sure. As this second quarter's figures, the Life's revenues include two parts.
One part is the hardwares of Life delivery to our customer. The volume hardware delivery in second quarter's a little bit down a bit.
That account for the total revenues a little bit down. We delivered Life products in the past a series of quarters on a stable growth volume.
It's this Life product used to the local scenarios, local mobile broadband scenarios, like our products charge cables. That's very well welcome in Japan's local market.
The MAUs figures reflect the cumulative active historicals sold hardwares of Life. That cumulative MAUs metrics is increased dramatically compared with last year's.
Two metrics: one's revenue reflects the second quarter scenarios, the MAUs reflects the cumulative, the whole historical selling storages. Yeah.
I have more comment about this. Because for Life, at this product, I think because I just mentioned, as you mentioned, the supply chain impact by the AI industry because the memory chip and the and the PCB, etc.
That's why in the first quarter, before the price increase, we asked our customer give more order. Far, I think that's that's the why in the first quarter we get a more bigger order.
The second quarter, order is a little bit a little lower. The second quarter, you can see the order is a little bit lower.
That's because of the supply chain impact and the price increase. The the total, the first half years, we are compare the first half last year is increase dramatically.
Theodore O'Neill
Okay. Thank you very much.
That answers my questions.
Operator
Once again, if you wish to ask a question, please press star 1 on your telephone and wait for your name to be announced. There are no further questions at this time.
I'll now hand back to Daniel Gao for closing remarks.
Daniel Gao
Okay. Thank you once again for joining us today.
If you have further questions, please feel free to contact UCLOUDLINK's Investor Relations through the contact information provided on our website, or speak to our Investor Relations firm, Christensen Advisory. We look forward to speaking with you again on our next quarterly call.
Thank you.
Operator
That does conclude our conference for today. Thank you for participating.
You may now disconnect.
Chaohui Chen
Thank you.
Operator
Thank you.