U-Haul Holding Company
Q2 FY2027 · Earnings Call TranscriptNovember 5, 2026
Operator
Hello everyone, thank you for joining us and welcome to U-Haul Holding Company's second quarter fiscal 2027 investor call. After today's prepared remarks, we will host a question-and-answer session.
If you would like to ask a question, please press *1 to raise your hand. To withdraw your question, press *1 again.
I will now hand the conference over to Sebastien Reyes. Please go ahead.
Sebastien Reyes
Good morning, and thank you for joining us today. Welcome to the U-Haul Holding Company second quarter fiscal 2027 investor call.
Before we begin, I'd like to remind everyone that certain of the statements during this call, including without limitation, statements regarding revenue, expenses, income, and general growth of our business, may constitute forward-looking statements within the meaning of the safe harbor provisions of Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended. Forward-looking statements are inherently subject to risks and uncertainties, some of which cannot be predicted or quantified.
Certain factors could cause actual results to differ materially from those projected. For discussion of the risks and uncertainties that may affect the company's business and future operating results, please refer to the company's public SEC filings and Form 10-Q for the quarter ended September 30th, 2026, which is on file with the U.S.
Securities and Exchange Commission. I'll now turn the call over to Jason Berg, Chief Financial Officer of U-Haul Holding Company.
Jason Berg
Thanks, Sebastian. Good morning to everyone.
I'm speaking to you today from our home or office here in Phoenix, Arizona. Our CEO, Joe Shoen, is speaking at an industry event today and is unavailable for this call.
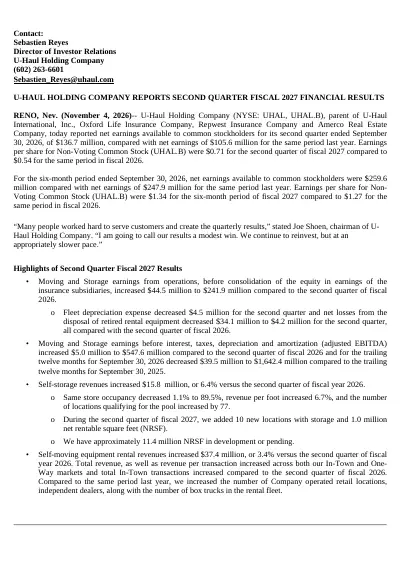
Here in the office with me, in addition to Sebastien, are Sam Shoen and JT Taylor, the president of our U-Haul International subsidiary. Yesterday, we reported second quarter earnings of $137 million compared to earnings of $106 million for the same quarter last year.
In terms of earnings per share, that's 71 cents per non-voting share this year compared to 54 cents last year. From here on out, all of my references in the prepared remarks are going to be for the second quarter of this year versus last year, unless otherwise noted.
Earnings before interest, taxes, and depreciation, what we call adjusted EBITDA, at the moving and storage segment increased $5 million for the quarter to $548 million. Included in our release and the financial supplement that we post on our website is a reconciliation of adjusted EBITDA to GAAP earnings.
Starting off with equipment rental revenue, for the quarter it rose $37 million with gains in both our in-town and one-way markets. Within that, we saw in-town transactions increase, while revenue per transaction improved across both in-town and one-way.
This was driven by more miles per transaction and higher revenue per mile. By the end of September of this year versus last year, between those two dates, we added 63 new company-operated locations and we increased our independent dealer network by a net total of over 500 locations.
October revenue has trended a bit higher than what our second quarter results were. Capital expenditures for new rental equipment were $466 million, that's a $275 million decrease compared to the same period last year.
While proceeds from the sales of retired rental equipment went down by $21 million to a total of $198 million. For the first 6 months of the fiscal year, we are down $223 million now on net fleet capex.
We're still projecting a decrease of a little over $500 million for net fleet investments by the end of the fiscal year. Storage revenues were up $16 million, that's about a 6% increase.
Average revenue per occupied foot for our total portfolio, I'm including both same-store and lease-up locations, improved by just under 3%. Some portion of this year-over-year improvement is going to dissipate now that we're a full year past the cleanup of delinquent rooms.
Our average new customer rental rates have increased by about 2% year-over-year, while rates for customers leaving are still about 1% lower than what the move-in rates are. Same-store occupancy decreased by 110 basis points to 89.5%.
We're seeing net move-in and move-out activity consistent, but remains behind what our goal is. During the first 6 months of fiscal 2027, we invested $432 million in real estate acquisitions along with the development of self-storage and U-Box warehouse.
That's a $94 million decrease over the first 6 months of last year. Just in the second quarter, we added 10 new locations with storage totaling a million net rentable square feet.
We currently have approximately 5.5 million new square feet being developed across 110 projects, and our pipeline of projects not yet started is about 5.5 million square feet as well. To put that in context, last year active development was about 6.5 million square feet and the pipeline was 7.7.
We're making progress in moderating the pipeline of new storage projects. The pace of our development spending is approaching likely our steady state.
Moving and storage operating expenses increased $54 million. Compared to the same quarter last year, our adjusted EBITDA margin went down by about 90 basis points, but we did have an improvement in our operating margin largely due to depreciation.
Personnel, property taxes, and self-insurance liability costs increased by a combined just over $21 million. The issues that arose in the first quarter with freight and shipping costs continued into the second quarter, increasing by just under $24.5 million.
As an industry, I don't see freight carriers lowering costs in the near term. Our U-Box team, which accounts for the largest portion of this variance, is working to make sure that our customer rates reflect the reality of the situation, as well as continuing to advance our load share program that teams U-Box shipments with our one-way truck rental customers.
While we're on U-Box, we saw the program return to revenue growth this quarter. We had an increase in the number of containers shipped as well as the number of containers in storage.
We had fleet depreciation reach an inflection point that we've been talking about for a while now. It decreased by $4.5 million in the quarter, while losses from the disposal of rental equipment decreased $34 million resulting in a loss of $4.2 million for the quarter.
The equipment that we sold had a lower cost, primarily from the additional depreciation that we've recognized over the last 12 months, while proceeds in the resale market have been resilient. The newer cargo vans that we've added to the rental fleet the last 9 months have a lower initial cost, and therefore we're seeing lower depreciation charges.
As of September 30th this year, we had cash along with availability from existing loan facilities at the moving and storage segment of $1,335 million. Quick update on the share repurchase program: during the second quarter, we repurchased 149,927 shares of voting common stock at a cost of $10.1 million, and 1,095,478 shares of non-voting common stock at a cost of $68.2 million.
As of today, the maximum amount that we can still repurchase is just under $224 million. Given the volatility that we're seeing in finance markets, we're balancing our plan to maintain adequate liquidity with our belief that our common stock, and in particular the non-voting shares, continue to be undervalued.
Before I hand the call back to our operator, I wanted to reiterate a couple of very important trends that gave me optimism in the quarter. First, revenue growth, while slower than we'd like to see, has been durable and steady.
Second, the adjustments that we've made over the last year plus to slow our growth capex plans for both fleet and self-storage are showing tangible results in lower spending and depreciation. Finally, on the expense front, our largest expense, personnel, is in line with revenue growth.
We should also run a sizable positive variance on fleet liability costs over the second half of this year. Outside of the freight shipping costs, our other expenses really are not out of line.
With that, I'd like to hand the call back to our operator, Connor, to begin the question-and-answer portion of the call. Connor, are you there?
Operator, I'm not hearing anyone yet.
Operator
Thank you for your patience. We will now continue the call.
The first question is from the line of Steven Ramsey of Thompson Research Group. Your line is open, please go ahead.
A reminder to unmute yourself locally.
Steven Ramsey
Can you hear me at this point?
Jason Berg
Steven, we can hear you. Thanks for all your patience.
Steven Ramsey
Great. Thank you for the color so far.
With self-storage up 6% and U-Box storage growing as well, can you talk about if U-Box storage is growing faster than self-storage, obviously at a lower base, and are there any observations you're seeing on the ground why customers are choosing one or the other when they have the option for both, or is this more reflective of internal efforts to guide customers to one or the other?
Jason Berg
We certainly have efforts in place to try to guide customers towards the U-Box storage product. I would say that still the majority of the storage customers that we're seeing in U-Box are the result of them using the product for a move, and then it goes into storage.
As we increase the number of moves, we're seeing the number of containers in storage increase. Anecdotally, we have some centers across the system that have figured this out and are doing a fantastic job of converting storage customers when they're full on traditional self-storage, converting them into U-Box containers.
I wouldn't say that that's been a meaningful increase across the system yet. That's a big opportunity for us.
Steven Ramsey
That's great. Then, it appears that U-Box covered warehouse space growth continues to outpace U-Box revenue growth, even with both moving and storage usage growing.
Is that the right perception, and if it is, do you expect U-Box investment to also be reduced in the coming quarters?
Jason Berg
Yes, as I look at the pipeline, the projected covered spaces that we're looking to build are probably about half of what they were a year ago or 2 years ago. That's a function of we've been building out this network of warehouses across the country to get them into areas where we have, I don't know if they really want to call it this, but I'll call it a hub-and-spoke type situation where customers can access the U-Box at just about any U-Haul location, but then the storage of it takes place at these larger warehouses that we've been building.
As we work our way through all of the major markets that need warehouses, we're not going to have to go back in and build more warehouses. I fully expect the spend on U-Box related real estate to continue to trend down.
Steven Ramsey
That's helpful. Then last one for me: freight and shipping cost, again, a pressure with U-Box.
Can you talk about where you see that going in the next couple of quarters, or settling out?
Jason Berg
A few things. There's what I've focused on a lot in the calls here is just the increase in cost from an industry perspective.
I think what our team here at the home office and out in the field is focused on is things that they can do a little bit better to make sure that they're not causing a situation where we have to pay more for freight. I think we're making progress on that front, and we're going to optimize the freight costs as much as we can, even though they're going to go up.
First, we're trying to make sure our processes are bulletproof, we're not causing an increase in freight expense. Second, we're then trying to make sure that the realities of the freight cost for shipping these boxes around is appropriately reflected in the rates that we're charging customers, right?
These shipping costs are not unique to us, they're universal to anyone that's shipping containers around the country. Everyone has this same challenge, and we should be pricing appropriately.
Then third, we have a program internally where it was a program that Sam developed years ago, that we group U-Box shipments that are going to markets that we also have one-way customers driving U-Haul trucks to, and the U-Haul customers then, for a deal on their truck rental, take the boxes with them. That's another way of doing shipping for us, and there's a certain amount more that we need to compensate customers for because of the increase in fuel prices, but it's not nearly the same increase that we're seeing in over-the-road carriers.
Steven Ramsey
That's helpful. Thank you.
Jason Berg
You're welcome.
Operator
Thank you. Your next question comes from the line of Steven Ralston with Zacks.
Steven, your line is open, please go ahead.
Steven Ralston
Thank you. Good morning, and congratulations on another record revenue quarter.
Just Thanks, Steve. one question from me today.
I dug into the composition of those total revenues, and I realized I need to get a better gauge on the operating leverage of the self-moving rental business. I noticed that the peak quarter for the self-moving rental revenue was actually the second quarter of fiscal 2022 when moving activity was elevated due to COVID.
Since then, that peak in that segment, self-moving revenue is actually down 2.6%. The growth drivers that contributed to the record revenue quarter this quarter were self-storage, which is up almost 71% over that period since the second quarter of fiscal '22, and other revenue, which is mainly U-Box, is up about 30%.
As a result, together both lines make up now over 25% of total U-Haul revenue. However, it really looks like the self-moving business looks well-positioned for a leverage growth phase.
The fleet is relatively young, and depreciation is at a cyclical peak, much as it was in two other periods when U-Haul stock dramatically outperformed: start one in starting, I think, in 2004, and the other one in 2009. I wish Joe was here to answer this with historical perspective, but are there any similarities between those periods and today, other than the peak in depreciation?
Even if not, what were the drivers then that signaled an earnings growth phase was beginning?
Jason Berg
Great question. I appreciate you going back in history like that.
In both of those situations, I think you can attribute a lot of the success that we had back then to management focus. The 2004 time frame, we were coming out of a financial restructuring process.
There was a lot of noise that kind of took focus off of what the core operations were. The fleet was allowed to age a bit, that was in the early 2000s, and then by 2004, and then '09, and then I also think of '16, it's times where we had the fleet in excellent shape, and then we did something that expanded our reach.
I would say today what we're focused on in order try to create our own catalyst here is this dealer expansion program, right? Because if we look out into the marketplace, I don't think there's anything either on the self-storage front or on the moving front that looks like a structural demand catalyst out with the customers.
Then it's just us having to do a better job of trying to place the trucks, and the dealer program is that. Is it going to result in as big of improvements as we saw back then?
I think the jury is still out on that. We're up a net 500 dealers.
I think we would have liked to have been up more than that by this time. We made comments 9 months ago that we're going to see after the summer months how the dealer program was able to absorb the fleet, and I don't think we made enough progress on the dealer front to really make a final call on the fleet size.
I think that call is going to be pushed out a little bit. Steve, I don't know if I answered the question to your liking.
I'm sure Joe would have done a little bit better job at that, but I think in each of those instances there was a degree of management focus that we were able to get back to, because I don't recall a significant event outside of the COVID run-up that would cause the increase in demand, and that may just be forgetting it.
Steven Ralston
Thank you for reminding me about the catalyst of the dealer expansion program. Could you make any comment on this dichotomy of the growth rates between the core self-moving rental business and those two top-line growth engines?
It personally surprised me when I started looking at the numbers.
Jason Berg
I think what excites us about the evolution of the company is the stickiness of the non-moving revenue, right? If you think about storage, and then part of U-Box, which is the storage component, when you get a customer, there's an ongoing annuity, right?
They stay in the product for a longer period of time, whereas a move, you make the move, and then you're done, and then you get ready to help the next person, whereas in storage they're staying in excess of 30 months on average. I think we're excited about that piece of it, and that's why I have a slide in the investor deck that shows as that ratio of equipment rental revenue declines as a percent of the total, I anticipate our margins continuing to improve structurally.
Steven Ralston
Thank you for taking my questions.
Operator
Thank you. Your next question comes from the line of Jeff Kauffman with Citizens Bank.
Jeff, your line is open, please go ahead.
Jeff Kauffman
Thank you very much, and congratulations on the improvements that are there, I think, despite a slow revenue market. I want to follow a little bit along the last question, I'll throw it out to you, Jason, and Sam and JT.
You mentioned that you don't see any structural demand catalysts like we had in COVID, right? Nobody saw COVID coming.
Yet, it does feel like a lot of other companies that I'm watching are coming off the bottom of a long cycle of slow growth, no growth, mediocrity. We are starting to see depreciation and gains on sale normalize.
You're working to get occupancy a little higher, and that is working, maybe not as quick as we'd hope. If you take a look at previous cycle bottoms and kind of leveling out toward higher growth, are there certain canaries in the coal mine that tend to show themselves when we're getting back to a more normalized growth rate, and absent kind of the big mega-catalysts that are out there, are you seeing anything that convinces you things are getting slightly better or slightly worse in the external environment?
Jason Berg
Sure, the data points that I look at internally to kind of see which direction the ship is headed: one would be just overall transactions, right? The last couple years we've survived a lot on trying to recoup the cost increases that we've faced by passing some of that along to customers, and that's been buoying up revenue.
When transactions begin to turn, I think that that's a sign that business should be improving for us. The last two months or so, we've had pretty good transaction growth, and I look at kind of a trailing 12-month transaction count and compare it to the previous 12 months, and we've been running negative on that measurement here for quite some time, and in October we shifted over to positive.
Now, it's 23, 24,000 transactions on millions, but it's headed in the right direction. I would say anytime that we start to see transaction growth, that has typically been a positive sign for us in the long term.
Another point that I would say is miles per transaction. We've been running now for several years kind of negative miles per transaction numbers on the one-way fleet, and now we've compiled three quarters in a row where we're starting to see small improvements in the average distance of people's moves.
Positively with that is we also saw a little bit of an improvement on revenue per mile for one-way. Typically the longer the move that you get, the harder it is to pick up revenue per mile.
We saw both go up. Those are two internal statistics that we look at that typically would say something right is happening underneath.
Jeff Kauffman
Then just kind of taking that a little further in the extension, and thank you for that granularity. We're getting out of the stronger seasonal quarters, we're heading into the more moderate quarters of the year.
What do you think in terms of when you look at where the company is now, are there hatches to batten down further? Are there projects that you want to engage in that will make things stronger for the upturn?
I know depreciation's starting to settle in the right direction, gain on sale starting to settle in the right direction, we've slowed down growth in the storage business, but as we head into the slower seasonal time of the year, are there opportunities that are out there for you to take advantage of?
Jason Berg
Absolutely. This is the time that our field team starts to get a little bit of a breather from the hectic pace of the moving season, and they can start to focus on a few other things: making sure that the storage product at their location is cleaned up the way that it should be, perhaps finishing some projects, and generally focusing on other items that in the heat of the moment we don't want to laden them with one more thing to do.
This is normally the time that we can get to other projects. Joe and JT are communicating with the team.
I think storage is a big focus of that right now as far as making sure we're reading customer reviews and addressing them at a location-by-location basis, because things just tend to get a little bit behind, especially if the location is heavy on equipment rental. There's things that you maybe just don't get a garage door fixed right away, or there's something else falls behind on the maintenance side.
We can address those items. Then as far as other things we're doing here at the home office, the rollout of our teams here utilizing the AI tools that we have is really exciting.
We haven't handed any processes or procedures over to AI on an autonomous basis where it's doing it itself, but we're working hand-in-glove with the tool, and the output that at least what I've seen is really powerful.
Jeff Kauffman
Thank you very much.
Operator
There are no further questions at this time. I will now turn the call back over to management for closing remarks.
Jason Berg
I appreciate everyone attending. I'm sure that on the next call, Joe will be able to be here for to answer some of the other questions I might not have been able to for you.
Otherwise, our team looks forward to building on the success of this quarter. I think it was a really hopeful quarter, and then we'll report back to you on our progress the first week of February.
Thank you very much.
Operator
This concludes today's call. Thank you for attending.
You may now disconnect.