Ventas, Inc.
Q3 FY2026 · Earnings Call TranscriptOctober 28, 2026
Operator
Hello, everyone. Thank you for joining us, and welcome to Ventas, Inc.
third quarter 2026 earnings call. After today's prepared remarks, we will host a question and answer session.
If you would like to ask a question, please press star one to raise your hand. To withdraw your question, press star one again.
I will now hand the conference over to BJ Grant, Senior Vice President of Investor Relations. BJ, please go ahead.
B.J. Grant
Thank you, Chase. Good morning, everyone, and welcome to the Ventas third quarter 2026 results conference call.
Yesterday, we issued our third quarter 2026 earnings release, presentation materials, and supplemental information package, which are available on the Ventas website at ir.ventasreit.com. As a reminder, remarks today may include forward-looking statements and other matters.
Forward-looking statements are subject to risks and uncertainties, and a variety of topics may cause actual results to differ materially from those contemplated in such statements. For more detailed discussion of those factors, please refer to our earnings release for this quarter and to our most recent SEC filings, all of which are available on the Ventas website.
Certain non-GAAP financial measures will also be discussed on this call, and for a reconciliation of these measures to the most closely comparable GAAP measures, please refer to our supplemental information package posted on the Investor Relations website. With that, I'll turn the call over to Debra Cafaro, Chairman and CEO of Ventas.
Debra A. Cafaro
Thank you, BJ. I also want to welcome all of our shareholders and other participants, including our newest Ventas colleague, Andy [Watula?]
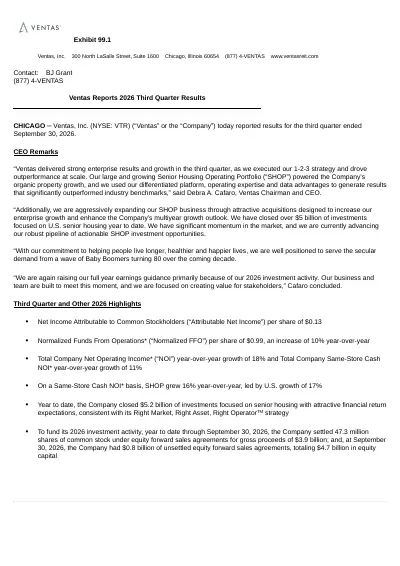
, to the Ventas third quarter 2026 earnings call. Ventas delivered strong enterprise results and growth in the quarter as we execute our 1-2-3 strategy.
Our senior housing operating portfolio, now in its fifth year of double-digit organic growth, powered our results, and our significant SHOP investment activity enhanced our outlook. In an environment of rapid change, the Ventas investment thesis remains consistent and clear.
Our $60 billion enterprise generates performance from nearly 1,500 physical assets serving the need-based secular demand of a large and growing aging population. Ventas is one of the rare growthy businesses that is neither AI-focused nor AI-correlated.
In addition, our strong and improving financial profile provides stability and opportunity amid volatile capital market conditions. As a result, we are well positioned to thrive in a variety of economic environments.
Within that context, our team remains focused on using our high-quality portfolio, differentiated platform, operating expertise, deep industry relationships, and data advantages to fuel our momentum and deliver outperformance at scale. Our excellent results demonstrate the power of our enterprise and our position as the world's second-largest owner of senior housing.
US SHOP same-store cash NOI grew 17% in the quarter, contributing to our 11% total company same-store cash NOI growth. The first prong of our 1-2-3 strategy is capturing organic SHOP growth through rate and occupancy.
Strong rate growth was coupled with SHOP occupancy outperformance in the quarter. Same-store average occupancy grew 120 basis points sequentially driven by Ventas OI.
This continues a multi-year trend of materially outpacing industry benchmarks. In fact, our SHOP portfolio has grown occupancy at twice the pace of the NIC average since 2023, generating nearly 600 basis points of incremental outperformance during that period.
Yet our US SHOP properties remain only 89% occupied, supporting a multi-year runway ahead for durable occupancy, rate, and NOI growth. I want to thank our Ventas colleagues and operators for their strong execution and commitment to outstanding senior care and services in our communities.
Our third quarter normalized FFO per share of 99 cents represents 10% growth year-over-year, and our credit profile continued its significant multi-year improvement trend as we ended the quarter with net debt to EBITDA in the low 4 times. We are pleased to again increase our full-year FFO per share guidance to $3.89, primarily because of our 2026 investment activity.
The Ventas strategy is built to capture unprecedented durable demographic demand. Now more than ever, individuals and their families are attracted by the benefits of safety, socialization, and support provided in our senior housing communities at a cost comparable to aging at home.
The baby boomer generation, a cohort of nearly 70 million individuals and the wealthiest generation in history, began turning 80 this year. We are just now stepping into the period of enormous growth in our customer base as the US senior population is expected to expand 28% over the next 5 years and remain elevated for over a decade.
Yet construction starts of new senior housing units hover at record lows, with a paltry 1,000 units being started in the quarter. With at least a 3-year start-to-finish development cycle and increased construction costs, we should enjoy these powerful tailwinds supporting our growth for the foreseeable future.
Our business and team at Ventas are built to meet this moment, capitalize on these trends, and continue to outperform the industry at scale. The second prong of our strategy, of course, is to aggressively expand our SHOP footprint through attractive acquisitions designed to enhance our enterprise growth rate.
Our investment momentum is strong, and year to date, we've closed more than $5 billion of SHOP investments, which are expected to produce double-digit to mid-teens unlevered IRRs and year-one average yields in the mid-6s. Our pipeline remains robust, and we are actively advancing actionable SHOP investment opportunities to build on our success and expand our SHOP business.
As a long-term industry participant with nearly 1,000 senior housing communities, we have built a significant competitive moat, including our relationships, platform, data, team, financial strength, and operating experiences. These advantages, coupled with our right market, right asset, right operator framework, drive our investment decisions, keep our win rate high, and help our acquired communities and operators outperform after closing.
With the recent global move in interest rates and geopolitical uncertainty, our competitive position has strengthened even further. To close, the entire Ventas team is unified and excited about the opportunities for multi-year growth and value creation ahead.
We remain focused on winning together and delivering outperformance at scale as we help people live longer, healthier, and happier lives. Now I'm pleased to turn the call over to Justin.
Justin Hutchens
Thank you, Debbie. Good morning, and thank you for joining us.
The third quarter reflected continued strong execution across our senior housing operating portfolio and our investment platform. I'll cover four areas: our SHOP results, the OI platform supporting them, the pace and quality of our external growth, and the outlook for the business.
Let me start with the SHOP results. Same-store SHOP cash NOI grew 16% year-over-year, led by our US portfolio 17%.
Revenue grew 8.3%, benefiting from both occupancy and rate growth. This marks the 17th consecutive quarter in a row of double-digit SHOP NOI growth.
Average occupancy increased 120 basis points sequentially and 290 basis points year-over-year overall, and 320 basis points in the US, led by independent living, which is up 340 basis points. Growth was broad-based across markets, community types, and operators.
RevPOR grew 5%. This compares with 4.7% last year and 4.4% the year before.
We continue to achieve stronger pricing in communities with higher occupancy, demonstrating the value proposition to the resident. Operating leverage is also visible in the results.
Same-store cash NOI margin expanded 190 basis points to 30.7%. Incremental margin flow-through was 53%, which has also been trending positively.
As occupancy rises, a greater share of each incremental revenue dollar converts to NOI. This performance reflects how we have built the portfolio in the right markets, with the right assets, and the right operators.
Furthermore, our communities that are currently 95% occupied delivered 7% RevPOR growth. Our SHOP communities across 48 states, Canada, and the UK are weighted toward markets with favorable fundamentals, including Texas, New York, California, Florida, and North Carolina.
Projected uncapped net demand in our US markets is roughly 1,200 basis points over the next few years, and residents in those markets have plenty of resources to cover the cost of their expected stay. The communities are large scale, averaging about 115 units, with a mix of roughly half independent living and the other half being assisted living and memory care.
We have completed nearly 400 community refresh capex projects since 2020, and we work with nearly 50 operators, ranging from emerging regional names to institutional platforms, who are all locally focused. Occupancy and rate working together remain the primary driver of performance.
Within the NIC top 99 markets, our occupancy outperformed the industry by more than double with 130 basis points sequentially. We have consistently beat the market.
Since the first quarter of 2023, cumulative outperformance is nearly 600 basis points. We attribute this to our operators' execution at the community level, supported by the Ventas OI platform.
Our US SHOP portfolio is just 89% occupied, which leaves substantial room to grow. We expect strong performance ahead driven by occupancy gains, rate growth, and operating leverage as price and volume work together.
We see this as a multi-year growth opportunity. Now I want to touch upon the Ventas OI data analytics and insights platform, which has proven to be a significant competitive advantage.
Our competitive advantage rests on our right market, right asset, right operator framework, strengthened by the Ventas OI data analytics and insights platform, which is focused both on driving operational performance and investment execution. We choose operating partners for their market-leading care and service, product expertise, leadership close to the community operations, and collaborative culture.
Our management agreements align our interests and support long-term investment in each community. In a highly fragmented industry, success requires managing at scale across markets, communities, and operators.
Ventas OI enables that scale through collaborative oversight, combining our team's operating expertise with proprietary data and best-in-class analytics to inform operational upside, guide refresh capital, and refine the portfolio, all in support of delivering outperformance. We believe this combination of platform, people, and execution at scale creates a competitive moat that is difficult to replicate and essential in order to successfully grow and operate in the fragmented senior housing industry.
It also strengthens relationships and opens growth opportunities for operators who deliver outperformance. We are growing in terms of number of operators and expanding existing relationships with high-performing operators.
For instance, we have expanded investments and communities under management with three-quarters of our operators. This includes our top five operators, who together represent over 60% of our SHOP NOI.
I'm proud of our team and grateful to our operating partners for their work every day. Now turning to investments.
We continue to scale our senior housing operating portfolio through market-leading acquisitions. Year to date, we've closed $5.2 billion of total investments focused on senior housing across 37 different transactions.
This brings our total external growth since the beginning of 2024 to over $10 billion at cost, which represents more than a 35% expansion of our SHOP footprint. Our recently closed senior housing investments feature an attractive mix of communities that provide various combinations of in-place cash flow, yields, and growth.
There are multiple levers to drive outsized growth in these deals. Examples include: communities with significant occupancy upside, value-add investments with both occupancy and rate upside supported by planned near-term capex investments, and communities that are local market leaders with demonstrated multi-year track records of high rate growth.
These and other factors contribute to generating the projected double-digit to mid-teens 10-year unlevered IRRs underwritten in each of our deals. From an initial pricing standpoint, our expected year-one yields on our senior housing investments are an attractive 6.6% overall.
These investments are expected to benefit from the various growth drivers I've described, contributing to accretive enterprise growth. On average, our senior housing investments year to date have a basis of approximately $346,000 per unit and were acquired at significant discounts to estimated replacement costs.
The US senior housing market is setting new transaction volume records this year, and our pipeline remains very robust. We are one of the largest acquirers of luxury senior housing communities in the US market and are also engaged in numerous off-market discussions with potential sellers and operators on a wide range of attractive opportunities.
Our relationship-based approach to sourcing investments, which accounts for over 90% of our investment volume, provides meaningful competitive advantages as current and prospective partners are attracted to the Ventas OI platform and our way of doing business. Operators want to work with us.
We're also encouraged that the recent movements in the pricing of debt capital should reinforce our competitive positioning and create further investment opportunities. To summarize, we continue to offer an attractive value proposition for our residents.
We are delivering strong organic growth in SHOP, adding to our footprint through market-leading acquisitions with upside, outperforming industry occupancy benchmarks, and continuously elevating the fully deployed Ventas OI platform, and the outlook for new investments continues to be as strong as ever. We are confident in our strategy and our team.
Now I'll hand it over to Bob.
Bob Probst
Thank you, Justin, and good morning, everyone. I'll start with our third quarter financial performance, then discuss our balance sheet, and conclude with our improved outlook for 2026.
I'm pleased to report another quarter of strong enterprise performance. Normalized FFO was 99 cents per share, representing a 10% increase year-over-year.
Driving the growth was total company same-store performance, which increased 11% year-over-year, led by SHOP growth of 16%. I note that the 11% same-store growth rate for the company is a record high and is driven both by the attractive mid-teens growth rate in SHOP and also by SHOP comprising an ever-larger proportion of our overall business, consistent with our 1-2-3 strategy.
Our outpatient medical and research portfolio, or OMAR, delivered 2.5% same-store cash NOI growth in the third quarter, led by outpatient medical, which grew 4%. Outpatient medical occupancy increased 10 basis points year-over-year, marking its ninth consecutive quarter of occupancy growth.
Tenant retention remains strong, supported by tenant satisfaction scores at the 95th percentile. Our research portfolio, which represents a small portion of our NOI, experienced a modest decline in the third quarter, as expected.
Our triple-net portfolio generated over 8% same-store cash NOI growth in the third quarter and was driven by negotiated rent increases. Turning to the balance sheet, our net debt to EBITDA of 4.4 times is our strongest leverage level in well over a decade and represents nearly a full turn of improvement year-over-year.
The strengthening of our credit profile is the result of organic property growth as well as equity-funded investments. I would note that this improvement was achieved while delivering attractive normalized FFO per share growth.
Year to date, we've already closed $5.2 billion in investments focused on senior housing, above the $4.5 billion contemplated in our prior full-year guidance. We have funded this investment activity with $4.7 billion of equity capital, together with dispositions and assumed debt.
We maintain excellent liquidity of $4.5 billion, which gives us flexibility to pursue our robust pipeline of investment opportunities. Last, I'll turn to our updated earnings outlook.
Given our strong year-to-date performance and investment execution, we are once again increasing our earnings outlook for the year. We have raised our net income guidance to 64 cents to 67 cents per share, or 66 cents per share at the midpoint.
We are increasing our full-year normalized FFO per share guidance to now range from $3.87 to $3.90 per share, which represents year-over-year growth of 9% to 10%. The 1-cent improvement in our new guidance midpoint is primarily driven by 2 cents from 2026 senior housing investment activity, partially offset by 1 cent from the impact of higher interest rates and FX.
We are reaffirming our same-store cash NOI guidance for each segment and for the total company. A few comments on our fourth quarter.
Our investment pipeline is strong, and our guidance only includes closed investments at $5.2 billion at this later stage in the year. I would note that our guidance assumes we refinance maturing debt in the coming months, and finally, we expect the majority of our disposition and loan repayment guidance of $700 million at a 7% yield to close in the fourth quarter.
For additional assumptions supporting our guidance, please refer to our Q3 supplemental and earnings presentation posted to our website. To close, we are very pleased with our performance year to date.
Our strategy is producing consistent growth, and we remain focused on creating long-term value for our shareholders. With that, I'll turn the call back to the operator.
Operator
We will now begin the question and answer session. Please limit yourself to one question and one follow-up.
If you would like to ask a question, please press star one to raise your hand. To withdraw your question, press star one again.
We ask that you pick up your handset when asking a question to allow for optimum sound quality. If you are muted locally, please remember to unmute your device.
Please stand by while we compile the Q&A roster. Your first question comes from the line of Nick Joseph with Citi.
Your line is open, please go ahead.
Nick Joseph
Thank you. You talked about the robust acquisition pipeline.
Obviously, we've seen that come through in the activity year to date, as well as the current pipeline. I was hoping you could touch on competition and, as interest rates have moved, how that has actually changed, kind of your expectation of competition going forward.
Justin Hutchens
Hi, it's Justin. We've had a really active year, and that's representative of our existing pipeline as well.
Our approach has really been to, first of all, we have very intensive screening of the pipeline. Secondly, we tend to lean in where we have competitive advantages.
Those advantages are often times relationship-driven. We have a very, very high growth rate with repeat sellers, we have a high growth rate with repeat operators, and that's led to some really attractive acquisition opportunities of luxury senior housing.
That's how we've been winning. There's certainly competition in the market.
Not everything's the right fit for us, and it may be a better home for it. There is the impact of interest rates that you mentioned.
That could slow down private buyers, that would put us in an advantaged position. Then we'll also just see how cap rates settle over time.
Thanks.
Nick Joseph
You mentioned the relationship-driven deals. How much do changes in interest rates impact those conversations?
Justin Hutchens
The interest in sellers to transact is ongoing. One of the things that happens, and it tends to lag a bit, we're not really seeing a lot of activity around these types of discussions yet, is there'll be discussion around price, and what the right cap rate is in the current market, but it's still pretty early.
Nick Joseph
Thank you.
Operator
Your next question comes from the line of Farrell Granath with Bank of America. Your line is open, please go ahead.
Farrell Granath
Good morning. Thanks for taking my questions.
First, I wanted to just circle back on the comment that you made about the 7% RevPOR growth in your 95% occupied units. I was curious how much of the NOI or which segments do currently stand at that 95 level?
Justin Hutchens
It's a lot. We have a large portion of our portfolio in that category.
We have NOI growth, really across the operating metrics that 95% band outperforms the broader portfolio. We also look at it in another way, which is communities that are 100% occupied.
We talked about in the last quarter that we had 10% of our portfolio that were at or near 100%. That number now is 15% of the portfolio.
That group of communities has outsized RevPOR growth as well. We're particularly excited about our hypothesis playing out, which is that communities can go all the way to 100% occupied, they can deliver higher pricing opportunity at the high occupancy levels, and that we can do it at scale.
The movement in the underlying portfolio is really exciting. I think it's also really important to note that we've built our portfolio to have a long runway of occupancy opportunity.
The US occupancy is only 89% occupied, we have this runway ahead, and into the demand that Debbie mentioned, that really hasn't even played out yet, where we can continue with strong occupancy and rate growth.
Farrell Granath
Great. I guess on that point also, I think that I'm just trying to bridge between, especially now obviously at that 95, we're seeing 7%, or you're seeing over 7% RevPOR or around 7%, but where the about 92% same-store occupancy and RevPOR is still around 5%, can you just bridge between expectations for rate growth, I guess moving forward, as maybe that occupancy continues to grow, as you fill up more of your communities?
Justin Hutchens
Yeah. Yep.
You have all the kind of levers of rate, include the in-house rent increases, you have street rates as well, and then ultimately what your move-in rents are. We've seen really good trending in both in-house rent increases and in move-in rents.
They've been favorable. That's been supporting the 5% RevPOR growth.
I mentioned my prepared remarks that RevPOR growth over the last few years, it was 4.3, then it was 4.7, it was 5% this year. We're on this accelerating trend of RevPOR, and that's a direct result of having higher-occupied communities, and also just managing price opportunity in what is very, very strong underlying affluent markets.
We think that opportunity continues as we continue to pull those levers and outperform in a very strong market backdrop.
Farrell Granath
Thank you.
Operator
Your next question comes from the line of Jim Kammert with Evercore. Your line is open, please go ahead.
Jim Kammert
Good morning, thank you. Kind of building perhaps on those prior comments, Justin, what do you think for your portfolio your best estimate of ExPOR versus RevPOR delta being?
Because that seems to be a big driver, right? Delta is very important.
Justin Hutchens
That's a good question. Both metrics are a function of occupancy growth.
In this environment, as revenue has been growing, it's been driven by rate and occupancy. RevPOR is around 5%.
We've been consistently under 2% on the ExPOR side of things. We're expecting continued occupancy growth.
It's really 89% occupied in the US, and so that opportunity continues. What's unique now is that we have more communities in the higher-occupied categories, that's driving rate.
That's an exciting opportunity. I don't know if I have the exact answer to your question in terms of a particular target in mind, but we expect that there's opportunity for that spread to widen.
We also expect to see further incremental margin as we move into the upcoming years as well.
Jim Kammert
Now, thank you. No, I think I phrased it wrong.
The opportunity to widen, that's what I was looking for. Thank you.
Then just back to the acquisition environment. Just being a skeptic, wouldn't the cap rates still continue to compress given there's so much money out there chasing this?
I don't know, just what are you seeing that affirms your view that you can still attain these low to mid-teens double-digit IRRs? I'm missing something.
Justin Hutchens
We've had a really, really good run for 3 years straight now of acquiring luxury senior housing that has unlevered IRRs of low double-digit to mid-teens. We've been achieving our underwriting, which is obviously an important component, and gives us the confidence to keep going.
Cap rates will move around a bit. Certainly, with the debt cost of capital going up, that could have some impact to kind of normalize cap rates.
There has been a lot of competition. We'll see how that plays out in the upcoming months.
In any event, our pipeline is really active and robust. We're excited about continue to work on those opportunities and continue the external growth.
Jim Kammert
Terrific. Thanks for your comments.
Operator
Your next question comes from the line of Jamie Feldman with Wells Fargo. Your line is open, please go ahead.
Jamie Feldman
Great. Thank you for taking the question.
I guess just still focusing on the expense side. Your margins expanded 190 basis points year-over-year, they slipped 20 basis points sequentially, despite occupancy increasing.
Just can you talk more about the line items specifically? Maybe more importantly, as we think about next year, it sounds like fundamentals are still very strong, occupancy should be growing, revenue should be growing, but is there something on the expense side we need to be focused on that might be a bigger drag than we're thinking about or just what is your outlook over the next 12 months or so on the expense side?
Justin Hutchens
Thanks for the question. I'm going to start with you mentioned the quarter there was a little bit of slip in margin in the quarter.
Our incremental margin has been running kind of low to mid-50s. 2 years ago, that was 43%.
We've had the advantage of occupancy growth and operating leverage playing out for us. It's a multi-year opportunity.
It's never a straight line. The quarter was impacted by there's an extra day in the third quarter, and we had utility costs were a little bit high, so that impacted margin.
The hypothesis remains very much in place, and that is that operating leverage benefits margin and delivers strong incremental margin growth, which, all things considered equal, should only improve as we move forward in this
Operator
Ladies and gentlemen, please hold while we evaluate the technical difficulties.
Justin Hutchens
Can you hear us? Can you hear us now?
Operator
Yes.
Justin Hutchens
Where'd I cut out?
Operator
We can hear you now, if you'd like to continue answering the question.
Justin Hutchens
Let me go back.
Debra A. Cafaro
Jamie, what was the last thing that you heard Justin saying?
Justin Hutchens
I'm just going to summarize what I said first. Are you there?
Jamie Feldman
I'm here. I think you had just started to answer, maybe if you want to start over.
Justin Hutchens
Okay. All right, we'll see if I do better this time.
Let's talk about incremental margin opportunity in the portfolio, and that's been running kind of low to mid-50s this year. 2 years ago, that was low to mid-40s.
The hypothesis is playing out, as occupancy grows, we're benefiting from operating leverage, we've seen incremental margin improve. You mentioned the quarter specifically, we had a little bit of slip in margin sequentially.
That was driven by an extra day in the third quarter, is also higher utility costs. One thing that I can tell you, even in our 17 quarters in a row of double-digit NOI growth, I don't think it's ever been a perfect straight line.
This is a multi-year opportunity. All the levers that we're pulling are working, and we're looking forward to continue those in revenue and expense and ultimately margin.
I don't have any comments on '27 at this stage.
Jamie Feldman
Thank you.
Justin Hutchens
You bet.
Operator
Your next question comes from the line of Austin Wurschmidt with KeyBanc Capital Markets. Your line is open, please go ahead.
Austin Wurschmidt
Great, thank you. Could you just give us an update on the performance of the Brookdale transition assets and kind of an update on the growth outlook there and when those start to enter the same-store pool?
Thank you.
Justin Hutchens
Sure. We have, in non-same-store pool that includes 234 communities.
That includes 130 acquisitions. There's 104 communities that are in some sort of repositioning action that will set up future growth.
Types of actions you'll see, in that group are transitions to new operators, redevelopments. That the the whole non-same-store the US portfolio, by the way, in SHOP, including non-same-store, is 89% occupied, we have a long runway ahead of growth.
The the portfolios in the non-same-store group that, excluding the acquisitions, are are on a like-for-like basis are growing around 120 basis points. That's everything in non-same-store that's like-for-like quarter-to-quarter, they're growing 120 basis points, which sequentially, which is consistent with the same-store.
The portfolio you asked about, the former Brookdale transition, is on the better side of that. We're encouraged by the momentum we're seeing in that portfolio.
Austin Wurschmidt
Then just going back to kind of the step function in RevPOR, has more of that step function occurred from in-place rent increases or from street rates? Can you give us a sense how you expect in-place rent increases for the upcoming year to stack up relative to how they stacked up at the beginning of 2026?
Thanks.
Justin Hutchens
Yep, good question. The primary driver of our RevPOR has been in-house rent increases.
We have seen move-in rents lifting as well, and so we're seeing both in-house and move-in rents working together, particularly recently, on the move-in rent side, we're really encouraged by that trending. In terms of in-house rent increases, we were around 8% last year.
It's a little early, but we would expect next year to be around the same or better.
Austin Wurschmidt
Great, thank you.
Operator
Your next question comes from the line of Dave Rodgers with Raymond James. Your line is open, please go ahead.
Dave Rodgers
Good morning. Wanted to shift to investment and acquisition opportunities.
I know in your prepared comments, you did describe some of that opportunity, but can you give maybe a little bit deeper in terms of the range of opportunities between occupancy recovery versus value-add and some of the capex-oriented assets that you could acquire and what that range looks like? It seems like you're buying assets that on average look just like the portfolio today, but what's that range look like and I guess how much more volume could you do if you were to expand out into one direction or the other?
Justin Hutchens
Let me I think maybe the best way to frame that up is to describe what we're buying now and what we have been buying and and and that can give you a a flavor for the range within that. If we just look at this year, this year, we've had, about 70% of our our acquisitions have been luxury local market leaders, 20% ultra-luxury premium product, and then 10% I'd characterize as mid-market leaders.
If you're wondering what luxury senior housing means, this is highly amenitized communities that are in the top decile of their local market, they have high private pay, high net worth, high home equity, high-barrier markets, and a concierge-level service in a resort a resort-style setting. We've been buying large communities with a continuum of care that offer all of these all of these amenities and high-quality options for for seniors in the markets.
The types of markets we're entering, I'll just throw out a few: Chestnut Hill, Newton in Boston, The Woodlands and Spring in north of Houston, Tucson, Scottsdale, Palm Beach, Naples, Denver, Marietta, Georgia, which is Cobb County, the wealthiest part of Atlanta. We're we're we're we're buying communities that are really well positioned.
They have they're 89% occupied, they have a runway of occupancy ahead, and particularly well positioned for rate growth. That's been the opportunity.
The range within that, yeah, there's been, we mentioned a a portfolio earlier this year called Revel, there's several kind of smaller one-off communities that are similar that that have occupancy runway. We have some that are in between that that we would probably consider a value-add just because they're still in the mid-80% occupancy range, and then we have others that are squarely in the 90% and already delivering rate growth.
Our pipeline, what let me let me just say one other thing. Let me tell you what we're not buying.
What we're not buying is value-oriented senior housing, and we're not buying turn-key, development opportunities. We've seen a lot of those.
We've seen them in the UK primarily. The problem with turn-key, it it does offer some growth in your portfolio, but you're paying a stabilized value for it.
The returns are much worse. They just don't make sense.
We've been focused on a better risk-adjusted return, we've been focused on an opportunity to drive these, low double-digit to mid-teens unlevered IRRs. To get to your your your exact question, we want to do more of everything I've just said.
We're seeing those opportunities in our pipeline, and and we're encouraged by that, and in particular encouraged by the SHOP investment thesis playing out through our operating fundamentals in our own portfolio. It it is a, with with better demand in the future.
Dave Rodgers
Thank you.
Operator
Your next question comes from the line of Ronald Kamdem with Morgan Stanley. Your line is open, please go ahead.
Ronald Kamdem
Hey, great. Just the first one, just wanted to talk a little bit more about the duration of same-store NOI growth, because there's this interplay between sort of occupancy upside and pricing.
If I look at the US portfolio where occupancy has been growing faster than 300 basis points every year, and you talked about being 89% occupied, a lot of runway, I guess so my question is how should we expect this to play out? Is it you stay at this 300 level for a couple of years, then you start pushing pricing, is it some sort of a mix?
What's the experience been, and how does that play out? Thanks.
Justin Hutchens
The high-class problem is we get there faster. It all depends on how the lease-up progresses over time.
We know from recent history that in an environment that had less demand, we've had very strong occupancy and rate growth. We're in a period now where we're at the very beginning of the peak demand, and we're encouraged by what we're seeing.
We're seeing improvement and our move-in rent run rate, we're seeing pricing power in our high-occupied communities, we're also seeing strong occupancy growth. If you look forward, all things considered equal, you would expect a similar runway ahead, but with a better demand backdrop.
As certain communities, in particular the profile that we have, we have an opportunity in our markets as market leaders to offer the value proposition to our residents and to drive pricing over time.
Ronald Kamdem
Helpful. Then my follow-up was just as you think about just sort of the dispositions side, any updates on maybe monetizing some of the non-senior housing assets either faster or so forth?
Thanks.
Debra A. Cafaro
Ron, this is Debbie, I'll take that. Yes, as Bob said, we have about $700 million of dispos in our guidance this year.
We're continuing to opportunistically prune the portfolio and recycle capital into SHOP investments, and we intend to continue doing that.
Ronald Kamdem
Great. Thanks so much.
Debra A. Cafaro
Thank you.
Operator
Your next question comes from the line of Mike Mueller with J.P. Morgan.
Your line is open, please go ahead.
Mike Mueller
Hi, thanks. Is there any distinction to know today between AL and IL, either as it relates to acquisition opportunities or RevPOR, NOI growth potential?
Justin Hutchens
Generally in our existing portfolio, we've seen stronger occupancy growth in our independent living portfolio. Our footprint, both existing and in what we're buying, tends to be about half independent living, and then the rest is assisted living with a small portion of that serving residents that have memory care needs.
There's been strong demand really across the board. We're seeing it in each product type and across all of our markets.
Obviously, we've put a lot of work to make sure we're in the right markets, but our preference, though, is generally to have a continuum of care. That's our preferred product, offering independent living, assisted living, memory care on a campus, or large-scale campuses, and that might include all independent living, for instance, and it's all tracking really well.
Mike Mueller
Got it. Appreciate it.
Thank you.
Operator
Your next question comes from the line of Jyoti Yadav with Mizuho. Your line is open, please go ahead.
Jyoti Yadav
Thanks for taking the question. I had a question on Canada.
Do you see any opportunity to JV assets there? On the UK, how do you view the opportunity there?
If you can talk about the sequential RevPOR decline there.
Justin Hutchens
I didn't quite hear you. Did you ask about Canada?
Bob Probst
JV in Canada and UK.
Justin Hutchens
Okay. The UK?
Thank you. Thanks.
I couldn't quite hear you. The US has been our main priority.
That's where we have most of our footprint in SHOP, and that's where our acquisition activity has been directed. We have a really high-performing portfolio in Canada that has high occupancy and has delivered consistent growth.
We really haven't focused on expanding there. The growth profile in that market isn't as attractive as the US over time, we've been steering clear of Canada.
Then the UK is of interest, but it just hasn't been as big of a priority.
Jyoti Yadav
Got it. Is there anything in the life science segment that you would like to call out from the quarter?
Debra A. Cafaro
It's the smallest part of our business, and it's been very consistent.
Jyoti Yadav
Got it. Thank you.
Debra A. Cafaro
Thank you.
Operator
Your next question comes from the line of Julien Blouin with Goldman Sachs. Your line is open, please go ahead.
Julien Blouin
Yes, hi. Thank you for taking my question.
Justin, I think you mentioned that you're planning for similar or better in-house rent increases over the next year versus 2026. I guess why could the range of outcomes include similar in-house rent increases?
I would have thought as we sort of get to these higher levels of occupancy, we might be able to push a little bit more. Is the Ventas OI sort of platform indicating any specific factors sort of limiting your ability to push pricing further?
Debra A. Cafaro
It's early, Julien. This is Debbie, sorry to jump in for Justin, but it's early, and we'll be happy to talk in more specifics about it as we know more.
Julien Blouin
Great. That makes sense.
Then maybe moving back to the incremental margin discussion. I guess I wanted to know, is there a meaningful difference between the incremental margins on the 95% plus occupancy portfolio versus the rest of the portfolio?
Are you seeing signs that in the higher-occupancy parts of your portfolio, you're, in fact, able to move up towards that 70% incremental margin that I think you've mentioned in the past for nearly full properties?
Justin Hutchens
We kind of referred to it as a rule of thumb at one point in time. That was talking about really the 50% incremental margin we're seeing now is consistent with what we expected.
As you get into the higher 90% occupancy range, you start seeing higher margin opportunity. We know that it's not a big sample size of communities that are kind of in that occupancy band that had no occupancy change, because we're still growing occupancy within that group, which is consistent with what I said about having more 100% occupied communities now.
We know that even in that group, we're seeing around a 70% incremental margin, and obviously, in those that are growing occupancy, it's even better. It's certainly proving out, and that's going to help lift our overall incremental margin over time.
Julien Blouin
Thank you. If I could fit one more in, I was wondering how do you think a more challenging home-selling environment will impact the demand from move-ins in IL specifically?
I get AL probably a little bit more urgent, sort of need-motivated move-ins, but I was wondering specific to IL.
Justin Hutchens
We've had a really consistent year in terms of move-in volume and occupancy growth. You can argue that there was a lot of potential impacts in the macro environment, obviously, in every way: geopolitical, home market, consumer confidence.
We've just been operating straight through that. We have confidence in the demand and the value proposition that we offer and the resilience that senior housing has, and really haven't seen any impacts yet.
Julien Blouin
Great. Thank you.
Operator
Your next question comes from the line of Juan Sanabria with BMO Capital Markets. Your line is open, please go ahead.
Juan Sanabria
Hi, good morning. Just on the expense on SHOP, just hoping you could talk a little bit about Ventas OI and any initiatives that you have there to maybe lower the ExPOR growth, which I think is trending around 2% inclusive of management fees, and kind of what the next opportunities that you're working towards may do or help with that ExPOR growth.
Justin Hutchens
Sure. It's a good opportunity just to remind everybody what Ventas OI is and how we're set up.
The framework of right market, right asset, right operator is the starting point. All the decisions we make around markets, assets, and operators are supported by our data analytics platform, and the experience that we have here at Ventas and the experience of our operators to make good decisions.
It guides our capex decisions, our decisions to expand assets. We always have some pruning we're doing in our portfolio, and that helps to lead to some of those decisions as well.
The part that I think we believe is most powerful is the support on the operating side. We're able to take data that most of our operators don't have any visibility into and bring to life for them opportunities on many fronts, and that's sales, all the various revenue drivers, sources of leads including digital leads, benchmarking on an anonymized basis and in like products.
That's helped to really bring focus to our communities and help make it easier for operators to prioritize where they can really create value. Expenses are part of that.
We definitely have a line item review that occurs regularly with our operators. We're always looking for any opportunity to become more efficient, but we are also very focused on the fact that we have a luxury product that we're supporting.
Our residents and customers have a certain expectation from us. There's no interest whatsoever in shortcutting our service delivery and our care delivery, and that's a balance that we take as we're approaching the expense side of things.
There is certainly an intense focus on it.
Juan Sanabria
Maybe just a bigger picture strategic question. There's a lot of opportunities out there both on the acquisitions and sales side.
Sounds like you're less enthusiastic about Canada and more focused on the US for SHOP. There's seemingly a growing SHOP opportunity in the UK, and then there's the ability to maybe deemphasize MOBs further by sales or joint ventures.
Just curious on what you'd have as a key priority for the company or what you're focused on thinking strategically about different moving pieces.
Debra A. Cafaro
Juan, this is Debbie, good morning. Since the inception of our 1-2-3 strategy and our actions in acquiring $10 billion of SHOP assets and growing organically, 1, 2, and 3 are basically aggressively expanding the percentage of our business at SHOP, and managing that optimally, as we've talked about, outperforming at scale.
The whole company really is focused and driven around those because that's what we believe will deliver the multi-year growth and value creation opportunity.
Juan Sanabria
Thank you.
Debra A. Cafaro
Thanks.
Operator
Your next question comes from the line of Rich Anderson with Cantor. Your line is open, please go ahead.
Rich Anderson
Thanks, good morning. I had a little bout of PTSD when your phone lines went out earlier.
Question Hey, Rich,
Justin Hutchens
if it happens again, it was not on purpose.
Rich Anderson
This is admittedly splitting hairs, but I'm going to ask it because I think it's having an effect on people's perception of the print this morning. For the third quarter, you did 17% same-store NOI growth out of SHOP, last quarter it was 18.
For the third quarter, your year-over-year increase in margin is 190 basis points, last quarter it was 210. My point is if the third quarter is supposed to be the best quarter, and Justin, to your point, things move around, it's non-linear, I get all that, and I am kind of more the messenger here on this question, but does this sort of indicate that this is where we're plateauing in terms of organic growth potential, margin expansion, all that sort of stuff, that's given that this third quarter should be the best of all quarters, or is that a little bit simplified?
Thanks.
Justin Hutchens
I say I'm so happy you asked that. It was a good quarter.
Like I said, in the 17 quarters where we had double-digit NOI growth, I think there is always something we thought could have been better. 17 quarters in a row we've done this.
I described really how the portfolio is built, the runway ahead, the demand that's coming, the way pricing's playing out in incremental margin. It's all really as we expected.
We're on this journey, this growth journey that we're on. There's a long way to go.
We're not even at all bothered about this quarter. What we're focused on is where it's going, and the trajectory is really positive.
The macro environment's solid, and the levers we can pull are proven, and we have a great team, great operators.
Rich Anderson
Related to that. Hypothetically, let's say your occupancy gain cadence isn't 300 basis points anymore, but it's 200 or 150 or even 0 eventually, because you can't go over 100%.
If that means that your rate growth is better in a higher-occupied portfolio, can you still maintain that level of bottom-line same-store NOI growth or does it naturally come down because if the only lever from a revenue point of view becomes rate over occupancy? I'm just curious how that math works when you consider incremental margin on new rate increases and all that sort of stuff.
If you could just sort of comment on the interplay of all that, that would be great. Thanks.
Debra A. Cafaro
Yeah. I do want to remind you that as we sit here today, we've had 17 quarters under our belt of double-digit NOI growth.
We have 89% occupancy in the US. We have rate and occupancy working together to drive NOI, and there is this multi-year runway ahead as we're just not even fully into the over-80 population starting to boom.
That's what gives us the confidence really about this multi-year growth and value creation opportunity ahead. I think you're kind of way down the path, even though we do know that at higher occupancy levels, as Justin said, RevPOR growth is significantly higher, and that's a lever that we can use as we look forward.
We're in it to win it at this period of time, and as we look forward, we're very optimistic about the setup for us and the competitive advantages and capabilities that the team and the platform bring to continue to try to outperform in senior housing.
Justin Hutchens
I'll just say that I'm not in the business of rating questions, but the second question was better, because I think that's a more relevant question. It's like where is this going, and I think it's a great question.
When we get there down the road, we can have some great discussion around how that's all played out.
Rich Anderson
Fair enough. Thanks very much.
Debra A. Cafaro
Thank you for raising it. It's a good conversation.
Rich Anderson
All right, I'll keep doing it.
Debra A. Cafaro
Yep.
Operator
Your next question comes from the line of Michael Carroll with RBC Capital Markets. Your line is open, please go ahead.
Michael Carroll
Thanks. I wanted to circle back on the margin flow-through.
I guess, Justin, where is the break line that pushes that margin from 50 to 70%? I was under the impression that was closer to the low 90% range, not the high 90% range, and if you kind of look at the presentation, it looks like Ventas' flow-through marginally increased from 49% in 2025 to about 52% from the past 12 months, even though you saw occupancy kind of jump from the high 80s to the low 90s.
Is there anything unique in that number? Are you seeing more occupancy gains in the US portfolio that's kind of in the mid-80s, and that's why that increase in that margin flow-through has been a little bit lower than expected?
Justin Hutchens
There's a couple things. There's not a bright line.
It really depends on the product type you're talking about and its relative price point plays a big role. There is a distribution in our portfolio, we have a lot of runway in occupancy.
That portion of our portfolio that has the long runway is not delivering the stronger margin. The part that is is the highest-occupied communities.
I do want to clarify one point, though. I think it's playing out exactly as we expected.
We said low 90s into the 50s. That's happening.
We would expect as more communities move up in terms of occupancy and our portfolio grows more in terms of occupancy, that we'll see the incremental margin to continue to play out. Within the portfolio, we can see it so clearly.
The incremental margin flow-through is so clearly happening at various occupancy levels. We have a wide variety of types of communities and markets and etc.
I don't really have a bright line for you.
Michael Carroll
That's helpful.
Debra A. Cafaro
Then That's part of the opportunity ahead.
Michael Carroll
Great. Then just switching to the same-store portfolio, can you kind of give us some color on how that could potentially change next quarter?
Do those deals that is rolling into same-store, do they have better occupancy comparison numbers? I'm just trying to understand how you can hit that roughly 300 basis point occupancy gain in 2026.
Is there some benefit in there that we can see in the current same-store pool?
Bob Probst
Hey, Mike, it's Bob. I'm going to take that one.
I feel like a potted plant over here, so. Look, you saw an increase in our same-store pool, second to third, to 600 assets.
Call it three-fourths of our NOI is in same-store. Justin earlier talked about the non-same-store pool and the composition.
We would expect as we move forward to have more and more assets coming into same-store, including in the fourth. That's contemplated when we give the guide overall to get to the average for the full year.
You'll see that number continue to increase from a very large proportion already.
Michael Carroll
Great. Thanks.
Operator
Your next question comes from the line of Michael Stroyeck with Green Street. Your line is open, please go ahead.
Michael Stroyeck
Morning, thanks for the time. Maybe one more question on the flow-through margin topic.
All else equal on the occupancy front, how does that flow-through compare on some of your more luxury-type assets relative to maybe some lower price point properties? Is there a meaningful difference?
Justin Hutchens
I'll say that our luxury independent living has very high margin. Independent living has really high operating leverage, you would see probably your strongest incremental flow-through there.
We have very high price point assisted living as well, but some of it also delivers really high levels of care, there's cost associated with that. Generally, you're going to see better margin with higher RevPOR.
There's certainly a relationship there. The ultimate driver across the board is operating leverage.
I'll also say that I mentioned earlier that what we're buying being 70% luxury and 20% ultra-premium luxury, there's a meaningful RevPOR uplift that's coming through the acquisitions as well.
Michael Stroyeck
Got it. Okay.
Then one just on maybe the regulatory environment in the US. Have you seen any legislation arise across your markets, either on rent regulation or anything on the labor side?
I guess how do you think about the long-term risk of the space becoming incrementally more regulated as just the sheer amount of seniors utilizing senior housing grows?
Debra A. Cafaro
One of the things we've always appreciated about senior housing is that it's a consumer-driven product in that seniors and their families are choosing to live there because of the valuable benefits that it provides, and are relatively comparable to what a senior would pay living at home and having some amount of services. We are obsessively focused about our operators delivering kind of quality care, providing a great value proposition for seniors and their families.
This is the wealthiest generation in history, the baby boomers, as they start to enter our markets. It's a state-by-state matter.
There really hasn't been anything that's gained material traction around really limiting access or revenue opportunities at our communities. We are very conscious of making sure that what we're delivering is worth the price that people are paying, and that's what's really important in a consumer-driven product.
Michael Stroyeck
Understood. Thanks for the time.
Debra A. Cafaro
Thank you.
Operator
Your next question comes from the line of Alec Feygin with Baird. Your line is open, please go ahead.
Alec Feygin
Hey, thanks for taking my question. Just one for me.
Can you kind of talk about the opportunity for more expansion projects and how Ventas is positioning itself to participate in the next development cycle?
Debra A. Cafaro
Good one. Justin?
Justin Hutchens
Absolutely. We have a lot of opportunity.
We've been evaluating our own portfolio over the past year or so, and we have expansion projects that are planned. Some of those you're just adding a structure.
We have one, I think it's highlighted in our supplemental somewhere, at Quincy Place. That's a pretty big project, $30 million or so, where we're adding cottages next to a community that is now 100% occupied.
High-demand opportunity to really just expand a winning product in what's already proven to be a strong market. There's dozens of opportunities across our portfolio where we've found that opportunity and that we're making plans to proceed.
Alec Feygin
Got it. Thanks for the time.
Justin Hutchens
You bet.
Operator
Your next question comes from the line of Rich Hightower with Barclays. Your line is open, please go ahead.
Rich Hightower
Hi, good morning, everybody. Just one for me as well, to keep things tight here.
Justin, I think in your prepared comments, you sort of briefly alluded to the debt market potentially creating opportunities for more transaction volume in '27. I assume that has to do with sort of the 2021 vintage of loans on a lot of these assets.
Just given the growth in NOI in SHOP, what's the likelihood that really you'd be competing against the market for refinancing where the equity is still good, and there's no sort of compelling reason to sell necessarily next year?
Debra A. Cafaro
I'm going to grab that one, just the point that we want to make is that we have, as significant competitive advantages that we won't reprise here in the investment market. A lot of our deals are relationship-oriented, among other things, and, of course, we have significant financial strength and flexibility.
What we're saying is the global move in rates and the volatility in the capital markets makes us an even more desirable counterparty in an acquisition because we do have that financial strength, people know we know what we're doing, we can close, they don't have to wait for someone, a different buyer, to get a mortgage or line up their financing. Coupled with all of our other existing advantages, being a long-term, very knowledgeable counterparty and actor in the space, That just adds to the competitive advantages that have given us the momentum to close $5 billion so far this year.
It just makes us incrementally more popular, if that were possible. That's how I would describe what we were getting at.
Rich Hightower
All right. Thanks, Debbie.
Appreciate that.
Debra A. Cafaro
Thank you. Operator, do we have any other questioners in the queue?
Okay. All right.
We appreciate everyone's time this morning, and as always, we appreciate your interest in the company. We're really glad that we were able to deliver a strong quarter, and we very much look forward with the opportunities we have ahead and to see you in the fall.
Thank you.
Operator
This concludes today's call. Thank you for attending.
You may now disconnect.