V2X, Inc.
NNYSE:VVXQ3 FY2026 · Earnings Call TranscriptNovember 2, 2026
Operator
Good day. Thank you for joining us for the V2X third quarter 2026 earnings conference call and webcast.
Today's call is being recorded. My name is Chris, and I'll be the operator for today's call.
At this time, all participants have been placed in a listen-only mode. Following management's presentation, I will open up the lines for the Q&A session.
To ask a question at that time, you may press * then 1 on your telephone keypad. To withdraw your question, please press * then 2.
Now, I'll pass the call over to your host, Mike Smith, Vice President of Treasury, Investor Relations, and Corporate Development at V2X. Please go ahead.
Mike Smith
Thank you. Good afternoon, everyone.
Welcome to the V2X third quarter 2026 earnings conference call. Joining us today are Jeremy Wensinger, President and Chief Executive Officer, and Shawn Mural, Senior Vice President and Chief Financial Officer.
Slides for today's presentation are available on the Investor Relations section of our website, gov2x.com. Please turn to slide 2.
During today's presentation, management will be making forward-looking statements pursuant to the safe harbor provisions of the federal securities laws. Please review our safe harbor statement in our press release and presentation materials for a description of some of the factors that may cause actual results to differ materially from the results contemplated by these forward-looking statements.
The company assumes no obligation to update its forward-looking statements. In addition, in today's remarks, we will refer to certain non-GAAP financial measures because management believes such measures are useful to investors.
You can find a reconciliation of these measures to the most comparable measure calculated and presented in accordance with GAAP on our slide presentation and in our earnings release filed with the SEC, both of which are available on the Investor Relations section of our website. At this time, I would like to turn the call over to Jeremy.
Jeremy Wensinger
Thank you, Mike, and good afternoon, everyone. Thank you for joining us today.
Please turn to slide 3. Today, we will review our third quarter results and discuss our outlook for the remainder of 2026 and share early thoughts as we look to 2027.
Before I go through the highlights, I want to thank our global team for their focus and dedication, which continues to drive our performance. Our people enable us to deliver for our customers' missions every day.
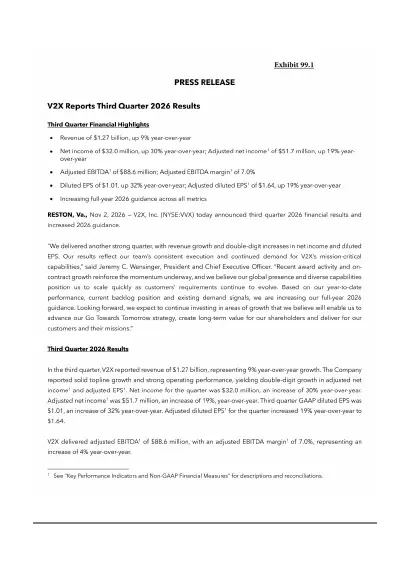
In the third quarter, consistent execution, recent contract wins, and continued alignment with national security priorities drove strong growth. Third quarter revenue increased 9% year-over-year.
Year-to-date revenue increased 16%. The value of our end-to-end solutions was reinforced by approximately $1.6 billion of awards, bringing our quarterly book-to-bill to 1.2 times.
These awards span our capability areas and reflect the continued demand for our diverse product and service offerings and the benefits of our global presence. We are demonstrating the right solutions for the right environment around the globe.
We can move quickly to meet our customers wherever they are and scale when mission requirements change. Together, these are clear differentiators for V2X.
We experienced another quarter of strong cash generation and maintain a healthy balance sheet. With this flexibility, we are continuing to invest in priority growth areas, including expanding capacity in engineering and product capabilities.
We are also investing in our facilities, our infrastructure, and research and development. Overall, it was another solid quarter for us, and with current demand signals, we are increasing our full-year 2026 guidance.
We have a clear line of sight into 2027, and from where we sit today, we expect growth across revenue, margins, EPS, and free cash flow. Shawn will provide more detail later in the call.
Our financial results and the momentum underway underscore our continued ability to deliver for our customers and drive value for our shareholders. With that, let's move to slide 4, which summarizes our performance for the third quarter.
In the third quarter, revenue increased 9% year-over-year to $1.27 billion. Adjusted net income was $51.7 million, representing an increase of 19% year-over-year.
Adjusted EBITDA was $88.6 million, with a margin of 7%. Adjusted diluted EPS was $1.64, representing an increase of 19% year-over-year.
These results show the strength of our business model. They also reflect the progress we are making against our strategic priorities and highlight our position as a leading provider of mission capabilities.
Turning now to slide 5. Our robust backlog, funding, and pipeline of high-quality awards continue to support our positioning and outlook for the remainder of the year.
We booked approximately $1.6 billion in awards in the third quarter, spanning our capability areas and reinforcing the demand for our solutions. Importantly, these bookings are margin accretive to our current profile, and we see margin expansion opportunities in 2027.
Bookings in the quarter yielded a quarterly book-to-bill ratio of 1.2 times and a trailing 12-month book-to-bill ratio of 1.4 times. Our total backlog now sits at $12.8 billion, $2.6 billion of which is funded.
This supports our visibility heading into 2027. Our organization is aligned to the demand we see in the market.
We are putting investments behind the areas where customers are investing and where we see the best growth opportunities. In turn, this is delivering results.
Please turn to slide 6. V2X's differentiated offerings and proven approach across the business enable our continued growth.
Our right to win starts with our proximity to the mission. We understand our customers' operating environments and can anticipate and meet their future requirements.
We combine that understanding with our diverse capabilities, track record of consistent performance, and strong partnerships across our offerings. Once we capture an opportunity, we quickly turn to execution.
We stay close to the customer, deliver in difficult environments, and build trust. That combination creates opportunities for on-contract growth, and our proven execution creates a strong foundation for us to capture additional new awards.
This is evidenced by our on-contract growth bookings, which are approximately $800 million year-to-date. Looking ahead, our focus remains on growth and where customer demand is strongest.
That is why we are investing behind the capabilities that can create the most value for our customers and for V2X. Turning to slide 7, our strategy in action.
I want to highlight a few examples of how we are meeting our customers where they are across our offerings. First, in engineering and rapid prototyping, we can move from an immediate need to fieldable solution in just months.
Tempest is a strong example. A customer presented an urgent need for counter-UAS solutions that could be produced at scale.
We went from concept to live fire in 4 months and fielded the solution in 6 months. In less than 18 months, Tempest has completed more than 1,000 successful engagements.
This demonstrates how we can develop, integrate, and field extremely cost-effective and capable solutions at the speed of need. As a direct result of Tempest's speed to market and success, we have expanded to additional customers with similar needs.
Next, in mission readiness, we are leading in aircraft availability and pilot readiness. We have the assets to support the full mission.
These include an instrumented runway and FAA Part 145 repair stations. We continue to execute.
Today, we continue to lead in first-time quality, averaging more than 96% across approximately 1,700 aircraft. On the TH-73 advanced helicopter training system, first-time quality is a record 96.45% in September, which is well above the 92.5% target.
V2X's contract with the Navy T-45 CLS program is another strong example of our execution in action. Throughout fiscal year 2026, the T-45 fleet flew more than 62,000 mishap-free hours, the highest flying hours recorded.
Operational efficiency was a key factor in the successful execution of this contract, and our team beat all Navy standards for availability. This shows that work done right the first time reduces repeat maintenance.
It lowers maintenance downtime and keeps more aircraft ready for training. The results of this contract show the value of process discipline, technical expertise, and strong execution.
It is just one example of many. Finally, in global logistics, it is our presence that makes the difference.
We are literally on the ground in areas of importance around the globe. We have the people, the supply base, and the operating knowledge to support our customers as requirements change.
As customers look to establish operations across multiple geographies, our presence gives us an advantage. We can stand up capability quickly and support distributed operations.
Currently, we support customers at scale in 47 countries, leveraging best-in-class partnerships to deliver secure and reliable mission capabilities and technology. In Asia-Pacific in particular, after just returning from a trip to visit customers in the region, it is clear that demand is strong, and we are well positioned to support deterrence and operational requirements.
We expect the region to be a growth driver in the fourth quarter and into 2027. Taken together, these examples showcase how V2X is effectively delivering tailored solutions for our customers around the globe for the moments that matter most.
Please turn to slide 8. An important part of being able to meet our customers' needs today is investing in the capabilities that they'll need in the future.
For example, we see continued momentum in engineering and rapid prototyping. Strong global demand is driving increased customer-funded R&D and follow-on production awards.
As a result, we are expanding capacity to meet anticipated requirements through investments that support current program execution and increase our capacity and speed for future work. To put that into perspective, customer-funded and internal R&D spending in 2026 is expected to be 2.3 times the spend in 2025.
Importantly, these internal investments remain within our annual capital expenditure plan. What's more, our customer relationships give us visibility into changing requirements.
We are integrating our capabilities in new ways to improve innovation and speed. This helps us solve customer problems faster and strengthens our platform for continued growth.
I am optimistic about the future and the increasing role V2X will play in our customers' missions of importance. With that, I'll turn the call over to Shawn for a more detailed review of the financials.
Shawn Mural
Thanks, Jeremy, and good afternoon, everyone. Please turn to slide 9.
Our third quarter financial results reflect the continued momentum across the business and ongoing healthy demand for our solutions. Revenue in the third quarter increased 9% year-over-year to $1,271 million.
Revenue growth was driven primarily by expansion in engineering and mission readiness programs and support for national security activities. During the third quarter, we saw continued growth supporting discrete national security activities.
These activities contributed approximately $130 million of revenue in the quarter and approximately $334 million year-to-date. From a geographic perspective, we saw continued growth in the Asia-Pacific region, with revenue increasing 8% year-over-year in the third quarter.
This reflects an increase in activity in the region, which we believe will continue in the fourth quarter. Based on current demand signals and customer priorities, we see several opportunities for future growth in the region.
Our revenue associated with the US also continues to grow, increasing 31% year-over-year, driven primarily by recent program awards and continued national security support. As it relates to the Middle East, consistent with our outlook and prior comments about evolving customer requirements and shifts within the region, revenue was down 30% year-over-year.
Importantly, as it relates to our recent contract to support activities in Israel, we are seeing revenue build as the program continues to ramp up. Overall, our solid top-line growth in the third quarter demonstrates our ability to rapidly deliver integrated product and service capabilities across multiple geographies and customers.
The ability to meet our customers where they are with relevant solutions and strong past performance is a differentiator, which we believe positions us well for future growth. Turning back to our performance for the quarter.
Adjusted EBITDA in the quarter was $88.6 million, increasing 4% from the prior year. Adjusted EBITDA margin was 7%, driven by the timing of program productivity.
We anticipate adjusted EBITDA margin in the fourth quarter to accelerate on both a sequential and year-over-year basis. Interest expense in the third quarter was $15.5 million.
Cash interest expense was $14 million, reflecting a 24% improvement year-over-year. Net income for the quarter was $32 million.
Adjusted net income was $51.7 million, up 19% year-over-year. Third quarter diluted EPS was $1.01, based on 31.6 million weighted average shares.
Adjusted diluted EPS in the quarter increased approximately 19% year-over-year to $1.64. Net cash provided by operating activities was $67.3 million in the third quarter.
Adjusted operating cash flow improved significantly to $61.8 million in the quarter compared to $35.8 million in the prior year period. Please turn to slide 10, where I will discuss year-to-date results.
Year-to-date revenue was $3,782 million, up 16% year-over-year, driven by new programs and on-contract growth. This growth was partially offset by volume on certain logistics programs, specifically in the Middle East.
Adjusted EBITDA on a year-to-date basis was $264 million, increasing approximately 13% year-over-year, with a margin of 7.0%. Year-to-date interest expense was $50.4 million.
Cash interest expense was $45.6 million, improving approximately 18% compared to the prior year period. Year-to-date net income was $76.5 million.
Adjusted net income was $151.4 million, increasing 29% year-over-year. Diluted EPS for the nine-month period was $2.42.
Adjusted diluted EPS was $4.80, up 30% compared to last year. Year-to-date net cash used in operating activities was $41 million.
Adjusted operating cash flow was $111.5 million, reflecting a $135.6 million year-over-year improvement. This impressive performance reflects our focus and underscores the company's core ability to generate strong, predictable cash flow.
Please turn to slide 11, where I will further discuss our cash flow and balance sheet. Our focus on cash generation is continuing to yield positive results, which is reflected in three-year cumulative adjusted operating cash flow of approximately $500 million.
It also further demonstrates the solid and sustainable cash return characteristics of the business. The positive cash flow attributes of our business are also evident on the balance sheet, with net debt improving approximately $140.3 million year-over-year.
Additionally, with approximately $750 million in capacity, V2X has significant flexibility to strategically invest for growth. Putting it all together, with high cash flow and a low CapEx business model, V2X is uniquely positioned to deliver enduring value creation and capital deployment optionality.
Please turn to slide 12. Our team is continuing to deliver, bringing all of V2X to meet our customers' critical mission requirements, which is driving our year-to-date performance.
Given our momentum and current trends, we are increasing our 2026 guidance. Revenue is now expected to be between $4.95 and $5.1 billion.
Adjusted EBITDA is expected to be between $352.5 and $367.5 million. Adjusted diluted earnings per share is expected to be between $6.15 and $6.55.
Adjusted net cash from operations is expected to be between $175 and $195 million. Please turn to slide 13.
While we are still in the planning process, we wanted to share some preliminary perspectives about what we are seeing as it relates to 2027. With solid bookings in 2026 and minimal recompete exposure, estimated to be approximately 6% of revenue next year, we are confident in our ability to grow.
From a top-line perspective, the orders and demand we see in Asia-Pacific and the continued momentum in engineering and rapid prototyping are expected to yield incremental revenue growth. Performance on T-6 will also drive additional revenue as it will contribute a full year in 2027.
These items will be partially offset by scope changes in the Middle East, with total revenue in the region estimated to be down for the full year. As it relates to national security, we see continued demand through mid-2027.
The net of these items are expected to drive top-line expansion in 2027. We expect the increase in revenue to be accompanied by margin expansion and drive growth in adjusted diluted EPS and adjusted operating cash flow.
Overall, the execution of our strategy is driving strong performance in 2026, and we are well positioned moving into 2027 to continue delivering on our commitments. Jeremy, back to you.
Jeremy Wensinger
Thanks, Shawn. As you've heard, we are delivering for our customers, investing in priority growth areas, and building a stronger platform for the future.
I want to again thank our global team for its continued focus and dedication. Their work keeps our customers ready and gives us the foundation to pursue V2X's next phase of growth.
With that, I'll open it up for questions.
Operator
Thank you. We will now begin the question-and-answer session.
To ask a question, you may press * then 1 on your telephone keypad. If you are using a speakerphone, please pick up your handset before pressing the keys.
If you would like to withdraw your question, please press * then 2. At this time, we will pause momentarily to assemble our roster.
Today's first question comes from Ken Herbert with RBC Capital Markets. Please go ahead.
Ken Herbert
Hi. Good afternoon, Jeremy and Shawn and Mike.
Nice results.
Shawn Mural
Thanks.
Mike Smith
Thanks, Ken.
Jeremy Wensinger
Thanks, Ken.
Ken Herbert
Maybe just to start off, I wanted to first ask the increased guidance for 2026 reflects a fairly significant slowdown in growth in the fourth quarter, sort of low single digits based on our math. Can you talk about some of the puts and takes as we think about the fourth quarter in particular and anything you'd call out in terms of projects rolling off or maybe what could just be some conservatism as we think about what sounds like some Middle East pressure and a few other moving pieces?
Shawn Mural
Thanks for the question, Ken. Absolutely.
At the midpoint, you're exactly right. It's low-single-digit growth year-over-year in Q4, and it's largely the Middle East.
As you heard in the prepared remarks and see in the materials, we're down 30% in the third quarter. There's probably a little bit more headwinds than that in the fourth quarter.
What I will say that the company is extremely dynamic and prepared to respond at a moment's notice to our customers' needs. That region is been an interesting scenario that we've played out for the year, and we appreciate all of our employees' support.
We're in constant communication with our customers, and certainly things can change there as we've seen throughout the year.
Jeremy Wensinger
I agree with you, Ken, also. I don't think we've seen the full effect of the Israeli award yet.
I also see opportunities in Balad as well. Again, it's a very fluid situation in the Middle East.
We'll see how quickly those ramp in both areas. Again, I think the resiliency of the portfolio on a global basis is what's carrying the water at the end of the day across the portfolio.
Ken Herbert
Perfect. If I could, as we think about '27, I can appreciate the puts and takes you outlined and how we should think about sort of growth across the key metrics.
Are you prepared to be a little bit more specific in terms of how we should sort of model or think about top-line growth? It sounds like you're in a pretty good position considering just 6% recompetes and obviously some of the dynamics, but I can appreciate there is some uncertainty.
Any more finer point, Jeremy or Shawn, you're prepared to put on that?
Shawn Mural
I don't think we want to give guidance yet. We did feel it was very important that we tell you what we know as we round the bend here in 2026.
We're in our planning cycle. We certainly do feel good, right?
The 6% recompetes next year, that's a continuation of a theme that we've seen for a while. That results in the company putting out more and more bids.
Jeremy's spoken about this repeatedly in terms of what our bid volume and velocity is, and I think we see that continuing into next year.
Jeremy Wensinger
I do. I think what it comes down to, Ken, is how long does it take for them to adjudicate awards, and does a change in the election cycle influence that?
We're just trying to be prudent. I love the bid velocity.
I love the bid volume. We're thrilled with that.
Again, it's very hard to predict whether we see the awards occurring when we expect.
Ken Herbert
Yeah. All right.
Thanks, Jeremy, Shawn. I'll pass it back there.
Shawn Mural
Thanks, Ken.
Operator
Our next question comes from Andre Madrid with BTIG. Please go ahead.
Ned Morgan
Hey, this is actually Ned on for Andre this afternoon. Thanks for taking the question.
I just kind of wanted to dive into counter-UAS and the potential there. I know it's a small portion of sales today, but just curious on how quickly that's growing and when and what it will take to become a more material contributor to the business?
Jeremy Wensinger
Thank you for the question. It's a very good question.
I had the opportunity to participate in AUSA and look at customer interest for our Tempest family of programs. A year ago, I would have said we had one customer; today, we have five.
It has proven its worth to many customers, and so I'm excited about the opportunity here. I'm also excited about the fact that our overall IRAD investment from '25 to '26 is up 123%.
That's a combination of us investing and also our customers investing in us. I think that shows their willingness to see the value of what we're doing, and also we see the value of the road map for many of these systems.
When I look at that family of systems, what I saw at AUSA was we are a proven solution versus a one that is coming up the curve to prove a solution. I think that's what most customers are seeing, and that's why I think the demand pull's been so strong across not just one customer, but now five that a year ago I would not have foreseen that five customers would be at our door looking for this.
I'm very excited about the platform.
Ned Morgan
Got it. Thanks.
Then I just wanted another on the national security work you guys are doing. Do you just go into a little more detail about the puts and takes into '27?
I see it's flat year-over-year through the first half. I just want to know what's recurring and what's not.
Shawn Mural
In '27, or
Ned Morgan
So,
Shawn Mural
what we said for the national security activities, what we have line of sight to today, under contract to perform, is through the third quarter of next year. We see volumes in the first half consistent with how we performed in the first half of '26.
Maybe not as robust as what we just delivered in Q3 at $130 million, but certainly an ops tempo that carries us through the first half of the year. To be honest with you, at this point, that's about as far as we're going to go because it's not dissimilar to a lot of our programs, dynamic.
The teams do a wonderful job of executing and supporting that mission around the globe in multiple locations. We're happy to be able to support our customer in that way.
Ned Morgan
Thank you, sir.
Operator
Our next question comes from Tobey Sommer with Truist. Please go ahead.
Tobey Sommer
Thanks. I wanted to ask about Asia-Pac specifically.
Growth year-over-year was kind of been in line with the corporate average in the quarter itself. Do you have line of sight into that sort of growth rate maintaining, or would you expect it to perhaps improve as you head into next year?
Jeremy Wensinger
Hey, Tobey. A great question.
I had the opportunity in the last month to go to Hawaii and visit our program teams there, and also the team in Kwajalein hosted me for several days. I walked away from that experience being very impressed not only with the program execution and the team's commitment to the customer, and also the customer's understanding of the need that they have going forward.
It was a good visit, and I can't thank the teams enough for allowing me to interrupt their day. I see the demand pull very strong, and I think our team is well positioned to support the customer and their missions.
I think in 2027, as you look at them doing some training in that region and also some additional build-out of capability in that region, we are exceptionally well positioned. We view that as our backyard.
We view INDOPACOM as our backyard, and being present, as I've said, time and time again, it is hard to really appreciate when you're standing shoulder-to-shoulder with a customer how much they rely on you for the support of their mission and also as they get more demand pull for their mission requirements, that we're in a position to support them. It was a good visit in both locations, and I can't thank the team enough again for their commitment to our customers' mission.
There are times when you're on the ground, you get a true appreciation for the mission requirements and how well we're positioned to support them.
Tobey Sommer
I appreciate that. I look forward to your Investor Day in the former rather than the latter location of your visits.
Could I ask a question about the margin expansion that you alluded to in '27? Won't ask you to quantify, 'cause it's too early, but maybe you could give us a sense for whether it's predicated upon revenue growth and SG&A leverage, and/or a mix shift, and if a little bit the latter, what sources of growth do you think would provide you lift?
Shawn Mural
Tobey, when we've thought about margin expansion and have said this before, it will be incremental over time. We're beginning to see mix shift changes.
If you look at the cost-type volume that we had in the quarter, it's actually down a bit from where it had been at, was around 60%. It's slightly less than that, 54%, 55%, I believe.
We see more fixed-price. We're clearly seeing more T&M.
We think, to the extent that those trends continue, that that's favorable for us from a mix standpoint for some margin expansion.
Tobey Sommer
Thanks for answering my questions.
Shawn Mural
Sure.
Operator
The next question comes from Peter Arment with Baird. Please go ahead.
Peter Arment
Thanks. Good afternoon, Jeremy, Shawn, Mike.
Nice results. Hey, Shawn, maybe just a follow-up on kind of the margin question.
In your prepared remarks, you talked about margins expanding in the fourth quarter. Maybe you could just give us a little more color of what's driving that, and then I have a follow-up when you're done.
Thanks.
Shawn Mural
Sure. Yeah.
Productivity. We always have productivity improvements and that type of activity in the fourth quarter, some timing of expenses between Q3 and Q4.
Part of the reason obviously we raised the guide across the board in all metrics, the strength of the portfolio. We're feeling very confident.
I think the implied Q4 margin will be about 7.7 at the midpoint. We have good line of sight visibility to be able to deliver that.
Like I said, mostly productivity, some mix changes, that sort of stuff also contributing, but feeling very good about it.
Peter Arment
Got it. That's great color.
Then Jeremy, just if you could just give us a little more color on the Middle East. It sounds like it's tracking to what you kind of expected, but what are you viewing for the offsets of that?
Are there other opportunities in the Middle East that maybe we're not seeing? Thanks.
Jeremy Wensinger
No, it's again, a very good question. It's a very fluid situation, Peter.
We're trying to be careful about how we couch it. I love the work we're doing in Balad.
I love the work we're doing in Israel. I love the work we're doing in various countries in the Middle East.
As you can see in the front page of the paper, it's a very fluid situation. I do see FMS as being an opportunity that is expanding in that region as a result of the current conflict.
I have people in region last week and this week that are talking to various people about some FMS opportunities. Again, it is extremely hard to predict in the region right now, but I love our position with our customers.
I love the missions that we're supporting. I think our team does an exceptional job in supporting, whether it's an FMS job or whether it's direct to the US government, the team is doing a great job on execution.
Again, you can't read a paper these days where it's not a very fluid situation, and so we're just trying to be prudent in terms of how we talk about it and make sure that we don't get in front of our skis.
Peter Arment
Got it. Appreciate all the details, guys.
Thanks. I'll jump back in the queue.
Shawn Mural
Thanks, Peter.
Operator
Our next question comes from Greg Parrish with Morgan Stanley. Please go ahead.
Greg Parrish
Hey, guys. Good evening.
Congrats on the results. Thanks for taking my question.
Just want to ask high level, how should we think about your growth profile maybe over the next couple of years? You're starting to set a pretty high bar for yourselves just given how strong your performance has been as of late.
How should investors think about your top-line algorithm over the next couple of years just from a high level?
Shawn Mural
I'd say a couple years out is difficult to predict, right? You just heard Jeremy talk a little bit about the Middle East, the support for the national security mission that we do.
It's dynamic, to say the least. I would say the strength and the positives of the business and its resiliency is around having the right capabilities, the right contract vehicles to support missions around the globe consistently.
That strategy won't change. Jeremy talked before about increased bid volume.
We see plenty of addressable market for our products and services. We've tried to highlight some of that earlier today in the prepared remarks around Tempest that Jeremy walked through, highlighted that at AUSA.
We think that's a clear differentiated capability that will bring to a variety of customers around the globe. I'd be remiss to try to throw a number out there, I probably won't, but I think the strength of the portfolio, that top-line growth that has been, we think exceptional is a testament to the capabilities and the strategy that we've had.
Jeremy Wensinger
No, I would agree. I think I've talked about it now for maybe four quarters in a row now about this recompete holiday that we're in, and it's continuing into '27, which means I'm bidding new work at bid volumes that this company's never done before.
I'm excited about the fact that we're able to put what I call differentiated offerings on the street, and the customers are recognizing that, and they're giving us a nod towards that additional work. Again, as I look into the future years, I love the fact that we're doing exactly what we said we would do, and that is resulting in growth profiles that I think the investor is benefiting from.
Greg Parrish
That's all great color. Maybe just to continue this point, you mentioned bid velocity again a few times this evening, and that's been a big driver of your recent uptick in growth.
I think you planned 30% higher bids this year. Maybe is that still the right number?
Then thinking ahead to next year, can you continue to expand that at the same pace? It gets harder and harder just mathematically, but you're expanding your capability, too.
Maybe just help me with your thinking.
Jeremy Wensinger
It does. I look at bid velocity in really two buckets.
One, the new stuff that we're actually putting and competing on, and I also look at it as on-contract growth. Our team does an outstanding job on our on-contract growth, and that has to do with the global, resilient presence that we have.
I think the new stuff that we're putting on the street is differentiated. I've talked at length in the prior calls about us adopting AI and creating differentiated solutions with AI both internally and externally.
When I look at this, I look at the team's accomplishment on on-contract growth, which I think is outstanding, and then our ability to put new on the street. I think those are two two areas of growth that I get excited about.
Greg Parrish
Great. Thanks, guys, very much.
Shawn Mural
Thank you.
Operator
The next question is from Trevor Walsh at Citizens JMP. Please go ahead.
Trevor Walsh
Great. Hey, gents.
Good afternoon. Thanks for taking the questions.
Maybe rotating back to APAC a little bit. Jeremy, can you just give us a sense of understanding that that's going to be a good source of growth for '27.
Do you see the same risk to operational, I guess, disruptions from hostilities that we've seen in Middle East? In other words, are there lessons learned that you can take from what's been happening in that region to applying those to APAC to just better prepare yourselves for if and when kind of the bad things sort of happen that you're able to kind of continue operating?
Or the environments are obviously very different, but just curious how much of that kind of plays into kind of what you're expecting for that region and if things kind of go sideways a little bit?
Jeremy Wensinger
No, I pray that that doesn't happen. We've had a, as a very difficult year in the Middle East.
I'm thoughtful and care for our employees as everybody does every day, and I'm praying that doesn't happen in APAC. I love the position we're in there.
I think we're in a very good position with regards to locations we're at, also contract vehicles that we support, and the customers' reliance upon us in that region. As I said, when I was in Kwajalein, that customer on that specific location relies on us for everything.
We are a great mission partner, and it's a very important mission that they support there with multiple assets. I love what we do, and I love the resiliency we have on a global basis.
I think it's hard to predict what's going to happen in APAC, but we can all hope and pray nothing like that in APAC occurs as that has occurred in the Middle East.
Trevor Walsh
Great. Thanks for the perspective.
Shawn, maybe for you, but Jeremy, feel free to chime in too on this one. With respect to that 2.3 times metric for both IRAD and the customer-funded R&D, can you just give us a sense of kind of the I guess maybe the ROI on that?
Is that really for things that are future planned type of opportunities, or things that we've already sort of gotten the benefit from? Just trying to get a sense of kind of where, just even high level, where those investments should kind of lead to from an opportunity perspective.
Shawn Mural
Sure. We delineated on one of the earlier charts kind of some capability areas, and the CRAD and IRAD dollars are largely going towards engineered solutions for products that we iterate on.
I think the thing that both our customer and V2X's commitment is to work through things very, very quickly, almost a fail fast, meaning if it's going to work, move it to fielding. Jeremy talked about that a lot in the prepared remarks.
That's the area where we're seeing those demand signals. We also put it out there because I'm not sure folks have an appreciation for the activities of doing customer-funded development work.
Now, I don't want folks to think that there's no risk associated with it financially with that type of work for us. It's cost-reimbursable.
We work with these customers very closely, and move in a very expeditious manner from white paper to fielded design. They have a very high ROI, and getting assets into the field.
We think it's a hallmark of what this business does in its engineered products and solutions. I'd
Jeremy Wensinger
add one thing to that, which is our product business is the fastest-growing part of our company at this point, which would tell you that that customer-funded IRAD plus our internal IRAD is resulting in top-line growth.
Trevor Walsh
Awesome. Terrific.
Super helpful. Thanks both for the questions.
Operator
Our next question is from John Godin with Citi. Please go ahead.
Jeremy Jason
Hi, guys. This is Jeremy on for John.
Just considering the fact that the midterms are tomorrow, I wanted to get a sense of what portion of the 2027 guidance is susceptible to whatever outcome we end up with, just want to get an idea of which growth vectors are particularly resistant or vulnerable.
Jeremy Wensinger
It's a very good question, which would be very almost impossible to answer other than to say we have had shown resilience across many administrations because of the work we do. I think of the global nature of our portfolio, the resiliency of our revenue, the resiliency of our people, and the business is, I think, demonstrated itself for decades in the sense that we are probably, it's hard to predict.
Look, but I love the work we do. I love the global nature of it, and I love the resiliency of the work we do because it is stood the test of time.
Jeremy Jason
Gotcha. That's really helpful.
I'll just keep it to one. Thank you.
Operator
The next question is from Jonathan Siegmann with Stifel. Please go ahead.
Jonathan Siegmann
Hey, thank you for fitting me in, and great results. Jeremy, you spoke very positively on on-contract growth.
I don't recall you guys quantifying that, the $800 million year-to-date, impressive, bigger than we thought. Can you frame that relative to historical levels?
Then second, just how much of that upside is a function of this dynamic environment that we're seeing? Is there concern that that kind of normalizes?
Thank you very much.
Shawn Mural
Hey, John. This is Shawn.
It is certainly higher this year than historical levels. World events have dictated that, and that's fine.
Again, it's a product of having the right strategy and the right vehicles in place, and our team's ability to then go execute in very short orders to fulfill those missions. I don't know if we'll see it at similar levels.
Those things tend to come about. The line of sight that we get into that work to frame it up for you is, it could be a quarter out.
It could be 6 months out. I can give you an example in some on-contract growth areas where we've submitted multiple I think 5, 7, 10 different proposals that we've iterated on to get work under contract and get going.
That speaks to the customer intimacy that we have in developing those, and the multiple capabilities that we're able to offer to our customers.
Jeremy Wensinger
I'll give you one example. When I was in Kwajalein, while I was on the ground, we got two RFPs for on-contract growth.
It was just because it was an urgent need, a requirement, and an unmet requirement from our customer. We were there, present, and able to respond to those while I was on the ground.
I think it goes without saying, this global presence and the fact that you're with the customer gives you that intimacy to solve their current problems. When I look at on-contract growth, our team is exceptionally well positioned to support our customer as these evolving needs come.
Jonathan Siegmann
Thank you.
Operator
The next question is from Joe Gomes with Noble Capital. Please go ahead.
Joe Gomes
Congrats on the quarter.
Shawn Mural
Hey, Joe. Thanks.
Jeremy Wensinger
Thank you.
Joe Gomes
I wanted to start out, maybe try and attack the margin expansion in a different way. Shawn, I'm not sure you can parse this out, but what percent would you say that margin expansion is coming from new programs at higher-than-average margins versus existing programs where you're moving up the margin curve, to speak, as you've talked about that in the past?
When a brand new programs typically come in at lower-than-average margins, and over time it's moves up.
Shawn Mural
Yeah. Great question.
I would say the bulk of what we will see will be from new programs awarded at higher margins and the ramp on those things in the back half of next year as I sit here today, right? I see it coming later in the year, not dissimilar to the profile we're demonstrating this year, but I see it being program contributions.
I spoke earlier today about productivity improvements in the fourth quarter, that sort of stuff. We see it, like I said, back half of the year, new programs.
We have highlighted the bookings that we've had on a year-to-date basis are higher margins than the company composite adjusted EBITDA margin today. As those things ramp up and become a higher percentage of the total revenue of the business, they'll contribute more absolute profit dollars.
Joe Gomes
Great. Thanks for that.
Then Jeremy, maybe you can talk a little bit about this one. Historically, given the company's business a lot in the O&M, having the continuing resolutions have not had a significant impact on the company.
As you've moved in, I think you just said that products are now your fastest-growing part of the business. How much more sensitive is the company to ongoing continuing resolutions would you say?
Jeremy Wensinger
Obviously, as you move more into that domain, you're going to have that typical exposure. I don't see that given the funding profile that we have on these programs to date.
We're well funded going through for a period of time. I don't see that as a big issue.
Again, continuing resolutions are always a potential. I look at what we do and who we're doing it for, and those are missions of essential requirements.
I think cooler heads will prevail, and we'll continue to move down a path with these programs regardless of whether it's services or products. That's where I'm at.
Joe Gomes
Great. Thanks.
I appreciate it.
Shawn Mural
Sure.
Operator
The next question is from Noah Poponak with Goldman Sachs. Please proceed.
Noah Poponak
Hey, good evening, guys.
Shawn Mural
Hey, Noah.
Noah Poponak
In the pieces of 2027 that you outlined, when you mentioned continuing to see demand through mid-2027 in national security, can you just elaborate a little bit on what you mean there? Is that just the normal duration of visibility in that business, or what did you mean by that?
Shawn Mural
It's exactly I'll say the typical duration based on what we've seen so far this year. We see it continuing and extending.
Our customer in the third quarter did extend activity, which is why we wanted to provide insight into what we're seeing now, Noah. They gave us some insight into, call it through mid-2027, and we wanted to make sure that we shared it.
We took an incremental booking on that in Q3. Feeling very good about the support that our teams do for that customer to support that mission.
Noah Poponak
Excellent. Understood.
On T-6, can you quantify, or even if roughly or directionally, what that looks like on a full year '27 versus a partial year '26?
Shawn Mural
I'll tell you on a year-to-date basis, since we've talked about it before, we've done a little over $100 million on that program. You should think that the ramp on that predominantly occurred in the third quarter.
When we were awarded the program, I think we said it was somewhere between $250 and $300 million a year on a full run-rate basis. As I sit here today, again, we're in the planning stages.
I don't have any reason to think that it'd be different than that right now. We will certainly provide more clarity around it when we issue the guide.
That's where we are on a year-to-date basis now, and I think it's consistent. We're seeing consistency based on what we said earlier this year.
Jeremy Wensinger
Yeah. I will say the teams did a fantastic transition on that program, and the program team is executing that program exceptionally well, hats off to that team.
Noah Poponak
Okay. Then the Middle East revenue you've cited as potentially seeing scope change, while I fully understand your point that it's difficult to predict where that's going, can you size the sort of base of revenue in 2026 that potentially has some scope change in 2027?
Shawn Mural
I think the scope changes that we're seeing in the back half of '26 simply persist into '27. I don't know that we see incremental to that.
If we're down 30%, we did roughly 240, $245 million in revenue in the region in the third quarter. I think continues to be a slight step-down, specifically around Kuwait, where we're doing, I think, in the whole back half of the year, no, it's like $25 million for us.
It's very, very modest. When I think about '27, I don't look and think of incremental changes.
I just look at probably a different run rate, if that makes sense.
Jeremy Wensinger
Yeah. I would echo that, and also echo that we continue to see opportunities in Balad, and we continue to ramp up Israel.
I think there is some backfill of what Kuwait is drawing down, but again, we'll share more of that as we go into the '27 planning.
Noah Poponak
Great. Then Shawn, just last one on cash flow.
The full year would require the fourth quarter to have pretty different seasonality than the last two years. If you could just maybe elaborate on what's behind that, or what's normal?
Then within that, the capital plan is, I think, actually down year-to-date with the expectation that the full year would be up a lot. Is that more efficient, or just different timing?
Shawn Mural
I'll start with the capital. We're making some investments in our modernization sustainment business, our engineered products and solutions business in Indianapolis, Noah.
We made those decisions around the middle of the year, and so we see a step-up in CapEx here in the fourth quarter for that. Relative to the cash, I think we're really happy with where the cash has been on a year-to-date basis.
I think I said in my prepared remarks, we're over $100 million better through the first three quarters. I think at the midpoint, you're looking at $70 to $75 million of adjusted operating cash flow in the fourth quarter.
Very good performance throughout the year, and again, a hallmark of what we expect the business to continually perform.
Noah Poponak
Okay. Thanks very much.
Shawn Mural
Sure. Thanks, Noah.
Operator
This concludes our question-and-answer session. I would now like to turn the conference back over to Jeremy Wensinger for any closing remarks.
Jeremy Wensinger
Thank you all for joining today. Again, I just want to give a sincere thank you to the teams we have around the globe.
It is very eye-watering to show up at a site and see what they do every day. They do mission excellence every day, and it was just an honor to be with them in Hawaii and Kwajalein and anywhere else I can get to.
My hats off to them and thank them, and thank you for joining the call today.
Operator
The conference is now concluded. Thank you for attending today's presentation, and you may now disconnect.