Western Union Company (The)
Q3 FY2026 · Earnings Call TranscriptNovember 4, 2026
Devin McGranahan
We are encouraged by the momentum we have built through this program, and I look forward to updating you on our continued progress in the coming quarters. Long-term success for our shareholders depends on transforming Western Union from a predominantly retail, cash-to-cash consumer remittance company into a digital-first, omnichannel consumer financial services company.
We have many of the assets and capabilities needed to make this possible. However, a transformation of this scale at a large public company is neither easy nor seamless.
We experienced challenges earlier this year as the disruption to our legacy business model outpaced our ability to transform our cost structure. Following this past quarter, I believe we are moving our cost structure back into alignment with the pace of change in our business.
Our three platforms for future growth are our global digital remittance business, our omnichannel consumer services business, and our US dollar payment token, or USDPT, stablecoin platform and related initiatives. Our digital payout remittance business continues to perform well.
Transactions originated and paid out digitally grew 20-plus percent, with revenue up double digits compared to prior year. Transactions and revenue originated at retail and paid out digitally grew about 20%, albeit from a smaller base.
Our branding, pricing, and payout network enables us to succeed in this growing and competitive market. We are confident that this is the future of the remittance business and believe we are well-positioned to continue to win.
Success will depend on how effectively we manage our business as the market continues to move away from cash transactions. For example, non-cash funding accounted now for more than 20% of our North American retail transactions in the quarter, putting us in what we believe is a leading position as retail also evolves towards digital funding and digital payout.
As we accelerate our digital transformation, a key to success is ensuring that our customer-facing experiences are, and remain, best-in-class. This is an area where we have historically lagged.
I am therefore pleased with the continued pace of the rollout of our Beyond digital platform, which we believe will put us at the forefront of digital remittance experiences. We have launched the platform in Canada and are now accelerating the rollout across other markets.
The platform is now live in Argentina, Panama, and Peru, and is in the family and friends phase of rollout in Chile. We plan to launch in Denmark, Norway, Sweden, and Finland in the coming weeks, followed by Mexico, Australia, and US in the first half of 2027.
The Beyond platform is expected to improve customer onboarding and the user experience while enabling us to deploy updates and make changes much faster. It simplifies our technology footprint from the more than 40 applications we have today to a small number of regional applications, creating a more scalable and efficient platform as well.
In addition to improving our customer-facing applications, we are focused on digital delivery. Payout to account is by far the fastest-growing part of our business.
Expanding our network to reach the endpoints where customers want as efficiently as possible is one of our highest priorities. On a recent call, we discussed the rapidly evolving payout market in Colombia, where we believe it is a microcosm of the global market.
It illustrates the power of digital delivery when a real-time payments network, an active banking market, and a well-funded digital wallet coexist in the same ecosystem. Speed and access are and will remain competitive differentiators.
We need connections to the right partners on economically favorable terms so that we can price transactions competitively, deliver them in real time, and earn attractive margins. When done correctly, revenue per transaction is indeed lower, but so is the cost of delivery, allowing us to offer a compelling consumer experience while still earning an attractive margin.
Managing the difference in unit economics between cash payouts and account payouts as the market transitions will be important to our success. Our goal is to ensure that we emerge with a strong position in this evolving market.
It would be easy for us to rely on cash payout economics for as long as possible, but we believe doing so would risk ceding the future of the market to newer, more digitally focused players. This is the lesson we learned from our US domestic money transfer experience over the past decade.
I would now like to discuss our third growth engine. In the last three months, we have made significant progress and are now gaining traction in the market with our USDPT platform.
We currently have about $20 million in USDPT in circulation and are seeing approximately $150 to $200 million in transaction volume every 30 days. As a reminder, our objective is straightforward: use regulated digital assets to improve how Western Union settles with its agent network, connect digital value to real-world liquidity, and give customers practical ways to hold and spend dollar value.
We believe Western Union is uniquely positioned to address the core challenges in this space: cross-border settlement, last-mile access, trust, compliance, and distribution. We launched USDPT in May as a US dollar-denominated payment stablecoin, fully backed by US dollars, issued by Anchorage Digital Bank, and built on Solana.
Its first purpose is institutional: to create a near-instant, 24/7 settlement layer between Western Union and our agents. Over time, we expect that this can reduce the latency and fragmentation of traditional correspondent banking, lower idle cash balances, and allow us to deploy liquidity more dynamically across our network.
In June, Bybit became the first major crypto exchange to integrate USDPT, creating an on- and off-ramp in select Latin American markets that allow our agents to convert USDPT into local currency. Two agents are now using our USDPT settlement capabilities in that region, and several more are in the onboarding process.
In August, we launched StableCard by Western Union, which combines a USDPT account with a Visa secured card. It allows consumers to receive Western Union transfers, hold USDPT, and spend wherever Visa is accepted.
If you've not done so already, I encourage you to search for StableCard by Western Union in the App Store and download the Western Union USDPT app and give it a try. This product is particularly relevant in markets where consumers face currency volatility or limited access to dollar-denominated value.
The goal is not to ask customers to become crypto experts. It is to give them a simple, compliant experience that lets them preserve value and use it immediately for purchases or cash access.
Receiver Redirect, which we plan to launch before the end of the year, brings these pieces together. A sender can initiate a transfer through Western Union, the value can move on the blockchain using USDPT, and the recipient can receive and hold that value.
It creates a direct connection between our global money movement network, our digital asset ecosystem, while expanding customer choice in how funds are received and used. Our near-term focus is disciplined scaling.
This means expanding our availability market by market, adding high-quality partners, building liquidity and reliability, and embedding compliance at every step. We will move deliberately because trust is central to our brand and regulatory requirements differ by jurisdiction.
We will measure progress by adoption and utility, not headlines. Key indicators will include settlement volumes, receiver redirects, market expansion, customer engagement, and the economics of these new transaction flows.
As these capabilities scale, we expect to learn quickly, refine the customer experience, and prioritize the use cases with the clearest path to sustainable returns. Stepping back, digital assets reinforce the broader transformation of Western Union.
We have global reach, a trusted brand, deep regulatory capabilities, and a differentiated ability to connect digital and physical channels. USDPT gives us a settlement foundation, the digital asset network extends access, and StableCard creates everyday consumer utility.
We are still in the early stages of this initiative, and execution remains the priority. The strategy is tangible, the products are launching, and the partner ecosystem is developing.
Our goal is to make digital assets useful on a global scale: faster and more efficient behind the scenes, simple and practical for customers, and grounded in the trust and compliance that have defined Western Union for generations. Before I conclude, I would like to give a quick update on Intermex.
We have now passed our second HSR review window, which expired on November the 2nd, again clearing us of the HSR review requirement as laid out in the merger agreement. We are actively engaged in discussions with California regulators around their change of control approval, a requirement needed to close the transaction.
We have recently received feedback from the DFPI and are actively working to determine an acceptable path forward. November 10th, 2026, is the outside date included in the merger agreement, at which point either party has a right to terminate the agreement.
In closing, our financial results this quarter better reflected our underlying business, and we remain confident in our ability to continue to improve performance and unlock the value that exists within this franchise. We are focused on driving growth through our digital initiatives, improving efficiency throughout the organization, allocating capital with discipline, and executing against a well-defined strategic plan.
We recognize that rebuilding momentum requires both patience and execution. However, we believe the actions that we are taking today will position the company for a stronger future.
We appreciate the continued support of our shareholders and the dedication of our employees, who remain committed to serving our agents and our customers and advancing our strategy. While there is significant work ahead, we are focused on delivering the results that drive long-term value for our shareholders.
Thank you, and I will now turn it over to Matt to review our financial results and outlook.
Matthew Cagwin
Thank you, Devin. Good afternoon, everyone.
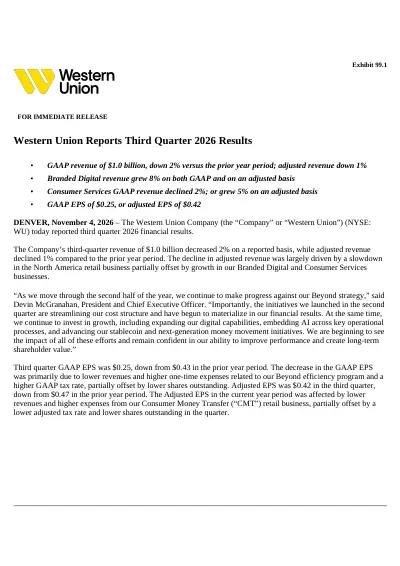
I'm going to provide additional color on our third quarter results, as well as update you on our 2026 financial outlook. In the third quarter, GAAP revenue was $1 billion, which on an adjusted basis was down 1% compared to the prior year period.
The decrease was driven by continued slowdown of our Americas retail business, partially offset by growth in our branded digital and Consumer Services businesses, which grew 8% and 5% on an adjusted basis. Adjusted revenue was slightly lower than our expectations, mainly due to ceasing account payout transactions for one of our larger Saudi partners, as Devin mentioned earlier.
Adjusted operating margin was 18% in the quarter, down from 20% in the prior year period, which was mainly impacted by revenue mix and higher agent signing bonuses. That said, adjusted operating margin improved substantially relative to the first half of the year, reflecting the early benefits of our Beyond Efficiency program.
We are beginning to see the results of our efforts come through, with cost reductions across the organization helping to offset revenue pressures and support margin performance. Compared to the first half of the year, we have demonstrated improved cost discipline, with the benefits of these actions contributing to stronger sequential margin performance while we continued to make progress towards our longer-term efficiency goals.
As Devin mentioned, there remains significant opportunity ahead as we continue to execute our Beyond Efficiency program across the business. I'm pleased to say that we're ahead of our plans of achieving $50 million of the annualized run rate savings by the end of this year, driven by the actions executed to date.
We believe that this outperformance is setting us up well to deliver against our 2027 Beyond Efficiency targets. These actions have resulted in almost $40 million in restructuring costs related to our Beyond Efficiency program, primarily related to severance and early retirement costs.
We expect the benefits from these actions to flow through our financial results over the next several quarters. These actions are expected to further improve our cost structure, enhance our operating leverage, and drive sustainable margin improvement.
Adjusted EPS came in at 42 cents in the current quarter, which was better than expected due to the timing of expenses, accelerated benefits from our Beyond Efficiency program, and a lower tax rate. Our adjusted effective tax rate in the quarter was 9%, compared to 12% in the prior year period.
The decrease in our adjusted effective tax rate was primarily due to discrete expenses in the prior year period, partially offset by proportional impact of lower forecasted full year pretax income. Now turning to Consumer Services business, which contributed 15% of total revenue this quarter.
Consumer Services adjusted revenue grew 5%, consistent with our expectations, driven by growth in our bill pay business. As mentioned last quarter, we expected Consumer Services adjusted revenue growth to slow as we lapped the acquisition of Eurochange and exited unprofitable product lines.
Now transitioning to our Consumer Money Transfer, or CMT, business. CMT transactions grew 2% in the quarter, compared to a year ago.
This was driven by continued strength in our branded digital business, which delivered 21% transaction growth in the current quarter. CMT adjusted revenue declined 2% year-over-year, which was a 100 basis point improvement from the second quarter.
Retail trends in the Americas remain under pressure, although the strength of our digital business enabled us to deliver improved revenue growth, demonstrating the resilience of our franchise and progress that we're making on our strategic initiatives. In the third quarter, our branded digital business grew adjusted revenue by 8% and transactions by 21%.
This marks the 12th straight quarter of solid revenue growth. Our Middle Eastern partnerships have contributed meaningfully to digital transaction and revenue growth over the past year.
Beginning in the fourth quarter, we expect both branded digital transactions and revenue to be lower, as we have made the decision to move away from one of our partner's account payout business due to low profitability per transaction. While we anticipate a near-term impact on revenue, we remain confident in the strength of our broader digital strategy and growth opportunities across the platform.
To help everyone with modeling, this partner contributed about 50% of branded digital revenue growth this quarter. Turning to our retail business, overall performance in our retail business was in line with previous quarter on both a transaction and revenue basis.
The business remains challenged in the Americas as US immigration policy continues to weigh on our operating results. New migration is the lifeline of our retail business, and current migration trends have limited our ability to replenish our Americas customer base.
Due to these pressures, we're focused on retaining and expanding our strategic partner base. As discussed earlier this year, we won the Canada Post partnership, and I'm happy to share that they went live in September, and they're already making a difference.
Now turning to our cash flow and balance sheet. We have generated $321 million of operating cash flow year-to-date.
This is down 21% versus last year, driven by our lower net income. Year-to-date, capital expenditures were $130 million, or roughly 30% higher than prior year, due to signing bonuses associated with recent agent wins and renewals.
As discussed earlier, we expect capex to be roughly $190 million this year, due to the new strategic partnership wins as well as a higher renewal cycle. Moving to our balance sheet, at the end of the quarter, we had cash and cash equivalents of $1.1 billion and debt of $2.9 billion.
Our leverage ratios were 3.3 times and 2.0 times on a gross and net basis. Our debt and cash balances include a $400 million in commercial paper that we took out in July in anticipation of closing Intermex.
Without this balance, our gross leverage ratio would have been roughly 3.0 times. In the quarter, we've returned over $70 million to our owners via dividends.
As we mentioned last quarter, we have paused our buyback activity to support our goal of maintaining a debt-to-EBITDA ratio of 2.5 times to 3 times. Now moving on to our 2026 outlook, which assumes no macroeconomic changes.
Today, we're presenting our guidance this quarter both with and without the acquisition of Intermex closing by November 10th. Based on our performance to date, our views in the remainder of the year, and if the acquisition of Intermex is able to close on November 10th, we expect adjusted revenue to be in the range of flat to +1%, inclusive of the Intermex acquisition.
Excluding the Intermex acquisition, our organic business is expected to be down in the range of -2% to -1% this year, with Q4 slightly lower than the first nine months of the year due to the impact of exiting the account payout transactions with one of our Saudi partners, which will affect our branded digital business. We also expect softer Consumer Services revenue in the fourth quarter due to softness in our travel money business and our retail money order business.
Our adjusted EPS for the full year, we believe will be in the range of $1.28 to $1.38. This is an improvement over our original guidance of 3 cents.
Before turning the call over to the operator, please understand that we will be limited in what we can say in regards the Intermex transaction. We are actively working with the State of California regulators to continue to try and reach a resolution.
We do not plan to give any additional color other than what was stated in the prepared remarks. Thank you for joining the call today, and operator, ready to take questions.
Operator
We will pause momentarily to compile the Q&A roster. As a reminder, each person is allowed one question with one follow-up question.
All participants will be in listen-only mode. Our first question comes to us from Darrin Peller at Wolfe Research.
Please ask your question.
Darrin Peller
Hey guys, thanks. Let me ask you first just a bigger picture question just post the election, obviously.
I suppose we'll see what may change from a legislative standpoint, whether it's immigration related or not, but do you believe you have the infrastructure prepared in case we do see a greater influx from an immigration standpoint? Anything you would have to change from that standpoint to see the tailwinds that could come?
Then just as a side question, I'll put them both in one, the digital side of the business, when I look at trends, it continues to show obviously the impacts of some of the white-labeled offerings. I'm curious if you could just characterize the strategy on the core westernunion.com branded offering, what the latest developments are there to see that growth really moving in the right direction.
Thanks.
Devin McGranahan
Hey, thank you very much for the question. The first one's quite easy.
The good news is, as it turns out, we have relatively significant excess capacity, particularly in the Americas, particularly in our retail business, given the mid-teens declines that we've seen in that business over the course of the last 18 to 24 months. We stand ready for any change that might happen, and tough for us to say, but any change that might happen that would lead to a different stance on immigration and potentially a different flow of migrants and immigrants.
As Matt was talking, the net negative immigration that's transpired over 2025 and 2026 has been difficult for our business, particularly our retail business. With regard to our core digital business, our core digital business continues to be focused on serving our customers across the 54 countries around the world where we are licensed and have a digital presence.
We are in the process of rolling out a much more digital-native, digital-first platform and application, as I highlighted in the prepared comments. We're also thinking about how we rethink potentially our stance in the Middle East.
We recently made an investment in a minority share of a partner in a Middle Eastern country so that we can gain greater control and launch a digital wallet in the region. We're also looking at other partnerships, potentially in Saudi Arabia, where again it could be less of a transactional model that we exited and more of a partnership model, given the strength of the Western Union brand and payout network that some other partners might see value in.
We remain optimistic about the overall strategy and the approach and expect to see the benefits of the rollout of the Beyond platform here as we go into 2027.
Operator
Our next question comes to us from Tien-tsin Huang at J.P. Morgan.
Please go ahead.
Tien-Tsin Huang
Hi, thanks so much. Good afternoon.
You're working really fast on the cost side, if I heard correctly, now $80 million in run rate savings from the original $50 million you targeted. Just curious where those savings were found, any revenue risk that might come with the changes, any other detail you could share would be great.
Matthew Cagwin
Hey, Tien-tsin. Hey, thanks for joining the call.
Thanks for the question. That $80 million split across a couple different fronts.
As Devin talked about in the prepared remarks, we have done an early retirement program, which really touched a small portion of lots of different teams across the North America platform that helped folks accelerate their retirement. That's providing a fair bit of that number.
The other big chunks that we have is we did a restructuring program where employees are currently leaving in the last six weeks and through the remainder of the year that's got a heavy impact on the technology and product departments. When we look at those functions, we're seeing a meaningful impact and benefit of AI and the ability to streamline that work and some further benefits coming, as well as our operations center.
You've heard Devin talk now for the last probably three, four years of that we continue to improve on our operations centers and how many calls we get per transaction, and that's continued to provide volume and benefits. We don't expect any meaningful impact on our ability to build forward.
We ring-fence all the investment areas, and that's our objective when we move forward.
Devin McGranahan
The one place, and we talked about this on the last quarter, we did make the decision as we transition now to the Beyond platform to shut the last-generation digital wallet platform that we had in Europe. There is a small amount of revenue associated with that that Matt can delineate, but it really was a way to get ahead of the rollout of the new platform, consolidate, and save a lot on the tech infrastructure side.
The trade-off on that for the little bit of revenue that we were going to lose, I think we deemed as worthwhile.
Tien-Tsin Huang
Perfect. Understood.
Just my follow-up question, just thinking about what's coming in and coming out. I understand the Saudi change, you got the Canada Post ramping that started in September.
Can you remind us of any other additions, subtractions in terms of agents or deals, partners that can change things sequentially or month-to-month here as we exit the year?
Matthew Cagwin
There's no other big rocks. We are proud that we've been able to renew Publix here in the last couple months, which is a continuation.
From a things coming in or things going out other than just macro and continue improvement in our business, there's no other big rocks in Q4.
Devin McGranahan
We did win Deutsche Post, which is still scaling. As we had left Deutsche Post three or four years ago.
We won them back as an exclusive agent in Germany, which is one of the opportunities for us as our footprint was quite reduced after the exit of Deutsche Post. We're now building that back much more in an independent agent model with actual local post offices, it's a little slower to scale, but it'll be more sustainable over time as kind of an independent network in Germany.
Tien-Tsin Huang
Right. It's a ramp, not a light switch.
Got it, thank you.
Devin McGranahan
With Verizon's Total Wireless, Verizon has 3,000 locations in their Total Wireless brand, it's a value brand, we went live with them both there and in a digital offer, we're being included in new Verizon Total Wireless value packages with a fee-free transaction for Western Union. I believe, and I'll look to Matt, I think we've gone live with about 850 retail locations through the end of October with the goal to get to 1,000 by the end of the year and then continue to ramp that across their network in 2027.
Operator
Our next question is from Timothy Chiodo at UBS. Please ask your question.
Timothy Chiodo
Great, thank you for taking the question. I was hoping we could just circle back a little bit to the large Saudi partner that you mentioned, the exiting of the business, just to make sure that that's a completely unique situation.
Maybe you could just put a little more color around maybe some of the unique aspects of either the variable costs in that market or the competitive landscape, just to get comfort that this is more of a one-off than something that there might be a few others that are similar. Thanks.
Matthew Cagwin
Hey Tim, thanks for joining the call tonight. Saudi Arabia is a very unique market.
As Devin talked about in the prepared remarks, it's a very thin margin, there's lots of tie-ups between agents and directly to countries. We have our investment in that country with the partner there called STC, which we've talked about now for the last five, six years.
We've got a couple small partners, and in this one we've been talking about for probably five or six quarters highlighting the benefit to our branded digital business. For most of that time, it was low margin, but very successful and ramping, and we were happy with the partnership.
That started to change here as we got into Q3 with the FX change, the incremental working capital challenges that ultimately made them pivot to being more of a something that doesn't make sense to go forward. Don't have any others that would fall in that same spectrum of very low-margin businesses that are large that we're watching and worrying about.
Devin McGranahan
I think the other thing that's relatively unique about Saudi, it's true in much of the Middle East and it goes to my prior comments, these are countries where it's quite difficult for a player like us to have a license. Where we don't have a license, we're much more dependent on partners, and therefore sharing economics with those partners in some way in which to, as they actually own the compliance risk and the customer account given it's their license.
That's not true in most of the rest of our digital footprint in the world. I actually can't think of anywhere outside of the Middle East it's true at all.
Again, it's a very limited business model in that region and particularly dominant in that country, which is what led us to the investment partnership with STC, because it's just a tough problem to solve.
Operator
Our next question comes to us from Nate Svensson at Deutsche Bank. Please go ahead.
Nate Svensson
Hi guys, thanks for the question. Wanted to ask on North America and the US in particular.
I guess first part of the question, I get the point that the top of funnel and migration flows into the country is still pressured, but you've talked a lot about retention and improving that over time. I was hoping for an update on how retention in North America and the US specifically has trended in the third quarter.
Then the follow-up related to that, you had mentioned some corridors that maybe were starting to look a little bit better, and talked about the potential for this return to growth in 2027. Could you give just more detail on that and what you need to see to get more confident on a return to growth in '27?
Devin McGranahan
I would characterize the return to growth based on three things: one which is obviously it would be helpful if immigration flows changed, that would have probably the most meaningful and short-term impact. The second is to continue to grow our competitive presence in the important corridors of which we're competing and doing well in a number, which I highlighted some of, as mostly at that point it is competing for share, whether it's in retail or digital, if the net quantity of new customers in the country is flat to slightly declining.
Then the third is continuing to win strategic partnerships. When we talk about what we were able to do with Canada Post, when we talk about what we were able to do with Verizon Total Wireless, we view ourselves as the leading player in large partnership-based remittance partnerships.
That pipeline looks pretty good for us, and we've got a great team working to drive more of those deals in, which will help us continue to do well in North America. The corridors where we're seeing stability, and in some cases growth, tend to be more out of the LATAM region: Philippines, Jamaica, the Pacific Islands.
We continue to see pressure in Latin America: Nicaragua, Honduras, Venezuela, Haiti, and I think that will continue to be pressured while we have these immigration challenges.
Matthew Cagwin
Hey Nate, just to build on Devin's point with a little math for you. If you just go back to last year and think about Q2, Q3, Q4, our business for North America, or the outbound, was down high-single digit, very low-double digit on a revenue basis.
That has improved now to the point of we're about 500 basis points better sitting here today in Q3. You say what corridors are really driving that, Devin highlighted a few of the ones, examples, but even the biggest one in the world, Mexico, we've seen it where it was shrinking, call it high-teens in the high point last year, to now it's more of a mid-single digit, low-single digit range, we're seeing meaningful improvement in that space.
Nate Svensson
Thanks, guys. Appreciate it.
Operator
Our next question comes to us from Rayna Kumar at Oppenheimer. Please go ahead.
Rayna Kumar
Good evening. Could you talk a little bit about the transaction trends you're seeing into the fourth quarter, and if you're starting to see that stabilization in US retail?
Then secondarily, could you discuss the pricing trends you're seeing in a competitive market, both in your digital and physical retail positions? Thank you.
Devin McGranahan
I think on the transaction trends, we've before seen ups and downs. I think we saw a bit of a slowdown at the end of the third quarter, and we've seen a little bit of a pickup here at the beginning of the fourth quarter in October, and then we've seen a little bit of pickup kind of in late October and early November.
I would say Matt had the overall trends right is any given month can go up and down, but over the last six months and over the last 12 months, we've seen steady progress towards stability and in some cases improving, to the point of us believing that at some point in next year, particularly in North America, we could see this thing stabilize and maybe turn into growth. With regard to digital pricing, look, we see different players acting very differently.
I'd say the major players continue to maintain some discipline in the market. We have not seen, as you can see in the RPTs date-to-date, we have maintained a strategy of remaining market competitive, which was one of the important strategies in '23 and '24 was to go back to being market competitive.
I would argue that in general the markets are behaving reasonably rationally, and we've seen the stability in our RPTs while we continue to compete.
Operator
Our next question is from Vasundhara Govil at KBW. Please ask your question.
Vasundhara Govil
Hi, thank you for taking my question. Maybe I'll ask one on the travel money business.
I know when you guys made the Eurochange acquisition, that was seen as a pretty attractive growth opportunity, and now we've kind of seen some softness in that business. Just curious what's changed and do you view this softness as just cyclical and something that might rebound here in the near term, or something else going on?
Matthew Cagwin
Hey Vasu, thank you very much for the question. We feel good that we've gotten to the $150 million revenue base, as we talked about earlier this year and late last year.
This business does come with some higher fixed cost coverage needs than a lot of other parts of our business. As we've cycled through this year, we've seen some pressure with the macros within Europe.
As this business is largely a European business for us. We're still happy with the acquisition, it still surpassed what we expected it to, but the growth rates have slowed.
We're still open and interested and excited about it, but it will have its ups and downs as the economy moves and people have more discretionary spending.
Devin McGranahan
As one of the things that worked out well for us earlier is winning, again, it's a business that's a little bit like normal Western Union business in which strategic partners, particularly strategic distribution partners, play an important role, and so we had won a large grocery store chain in the UK, which enabled us to have organic growth on top of the acquisition. The team is focused on continuing that, and there's a pretty good pipeline of incremental partnerships that we can add both in the UK and across Europe.
We continue to expand the travel money offering across our retail footprint, and so outside of the macro, we see the combination of being able to have travel money and remittance in the same location, carrying some of the fixed costs, as Matt has described, across two product lines instead of one product line, as again one of the rationales for the acquisition so that we could take the platform and the capabilities. We are close to launching a next-generation travel money point-of-sale platform, which will integrate travel money and remittance into the same platform, we will be able to offer the product across a much broader footprint of Western Union locations.
That platform, which will then sunset the Eurochange platform, I believe, Matt, should go live first quarter of next year, maybe, which will allow us then to expand the product offering at a more rapid rate than we've been able to to date.
Operator
Our final question is from Jack Evans at Goldman Sachs. Please go ahead.
Jack Evans
Hi guys, thanks for taking the question. I guess a quick follow-up to Vasu's question.
Obviously, you called out several headwinds, obviously talked about Eurochange, and obviously the media network headwinds as well, and then some of the divestitures or some of the pulling back of several non-core initiatives there. I guess how should we be thinking about the growth profile of CS over time, and do you still see that segment as a double-digit grower over time?
Just any commentary there would be helpful.
Matthew Cagwin
Hey Jack, thanks for the question. We are still very bullish about the Consumer Services business.
Our aspiration is still to have double-digit growth within that business. Let me talk about a couple of the things we're working on that we expect to have some benefits as we go into '27 and beyond.
There's two primary ones: Devin spent probably 5, 10 minutes of his prepared remarks on the digital asset strategy. Our StableCard and our DAN network both are things that are going to drive overall revenue and help the Consumer Services business, as well as we're right now in the process of working on cross-border bill payment.
You heard us talk about earlier today on the call that bill payment by itself is a very beneficial business for us, but the ability to take that and make it cross-border so that people can, rather than sending your family member €300 or dollars, whatever part of the world they're in, and then they pay their bills and spread it around, this will enable the sender to actually ensure the money goes where it's supposed to go to be able to do that. We're hoping to have that out early next year, or the first half of next year.
Both those things should provide some tailwinds as we start to move forward.
Jack Evans
Got it. Super helpful.
Then just a quick follow-up. Obviously, a number of pretty impressive partnerships, and it's great to hear that the obviously Deutsche Post and Canada Post are going well.
Just out of curiosity, any more of these deals potentially on the come, how you're thinking about partnerships, obviously in the near to the medium future? Anything else that this would seem like another huge future growth lever for you guys.
Any incremental color there would be helpful.
Devin McGranahan
Jack, I would say we've got a strong pipeline, we've got a great team working on it. We have a compelling value proposition.
We've made significant investments in what I would consider to be our partner platform. We actually refer to it as PartnerOS.
It allows much more seamless integration, a much quicker ability to connect capabilities such as payout to account, and so we think we are in a pole position for having a modern, up-to-date offering and a compelling package with a great value proposition. We remain bullish about our opportunity to win more, some cases de novo, like it was with Verizon, in some cases it'll be takeaways.
You can look forward to hearing more from us about that in the quarters going forward.
Operator
Thank you for joining the Western Union third quarter 2026 results conference call. We hope you have a great day.