Aebi Schmidt Holding AG
NNASDAQ:AEBIQ4 FY2025 · Earnings Call TranscriptMarch 19, 2026
Operator
Good day, and thank you for standing by. Welcome to the Aebi Schmidt Group fourth quarter 2025 earnings call.
At this time, all participants are in a listen-only mode. After the speakers' presentation, there will be a question-and-answer session.
To ask a question during the session, you will need to press star 1 and 1 on your telephone. You will then hear an automated message advising your hand is raised.
To withdraw your question, please press star 1 and 1 again. Please be advised that today's conference is being recorded.
I would now like to hand the conference over to your first speaker today, Simone Grancini, Investor Relations Director. Please go ahead.
Simone Grancini
Thank you, Sharon. Good morning, and welcome to the Aebi Schmidt fourth quarter and full year 2025 earnings call.
I'm Simone Grancini, the company's Investor Relations Director. Joining me on the call today are Barend Fruithof, Group CEO, who will provide the fourth quarter and full year highlights, outlook, and concluding remarks; Steffen Schewerda, CEO North America, and Henning Schröder, CEO Europe and Rest of World, who will detail the performance in the respective segments; and Marco Portmann, Group CFO, who will provide a financial overview.
Before I turn the call over to Barend, I remind you that today's comments include forward-looking statements subject to the safe harbor language contained in this morning's press release and in Aebi Schmidt's filings with the SEC. With that, I hand the call over to Barend.
Barend Fruithof
Good morning, everyone. 2025 was a historical year for Aebi Schmidt, marked by the acquisition of the former Shift Group and our listing on Nasdaq.
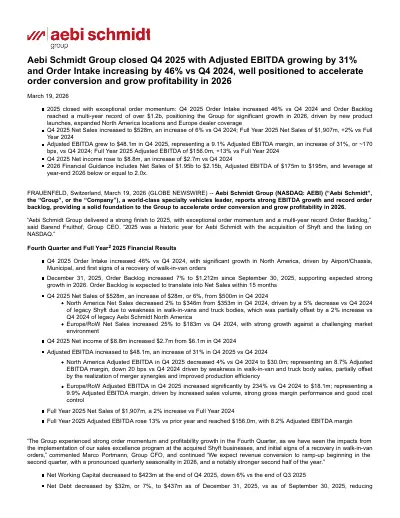
I'm extremely proud of our fourth quarter performance. As we see on page 5, our order intake increased 46% in the fourth quarter versus 2024, and we ended 2025 with a record high order backlog.
Our adjusted EBITDA increased 31% year-over-year for the fourth quarter, delivering a significantly higher adjusted EBITDA margin of 9.1% versus 7.4% in the prior year. Our strong cash flow enabled us to reduce our leverage to 2.8 times, strengthening our balance sheet heading into 2026.
I thank our employees for their exceptional contribution, and our customers for their continued trust. On page 6, I provide you with some more details on these outstanding achievements.
Our exceptional order momentum was driven by strong orders in airport and municipal, and especially by a recovery in the walk-in van orders. We believe this reflects a structural recovery in demand.
On the other hand, we expect a continued softness in truck body and commercial markets, with only a slow recovery in 2026. In terms of net sales, our fourth quarter grew 6% versus prior year.
A 5% decline in legacy Shift was more than offset by the rest of the group. Europe and the Rest of the World was a strong contributor to this performance, with substantial organic growth in almost flat market.
We also accelerated and increased the cost synergies from the acquisition of Shift with an additional procurement and revenue synergies expected to materialize in the second half of 2026. Ultimately, our adjusted EBITDA improved by 31% in the fourth quarter 2025 compared to the fourth quarter of 2024.
Europe contributed to this with an outstanding 234% increase year-over-year. Continuing on page 7, we look at the foundations we have built that will deliver our 2026 growth path.
First, our M&A strategy continues to deliver, and this goes beyond the Shift acquisition. Both our smaller acquisition, LWS in the US and Ladog in Germany, continue to provide outsized growth to the group, and we see further opportunities for small bolt-on acquisitions.
Second, we have launched multiple new products. This includes the first service body jointly developed by Monroe and Royal presented last week at the NTEA, the launch of new compact airport products to enlarge our addressable market, and we are exploring to design a more cost-competitive offering of our Blue Orca truck.
Finally, we opened new locations and secured major first-time customers, which will support revenue and profitability in the second half of 2026. Let's also briefly look at our brands on page 8.
We're simplifying our brand architecture, sharpening our market presence, and sending a clear signal that we are one powerful group. This makes it easier for our customers to navigate the group's broad range of solutions, simplifies customer engagement, and allows us to communicate in a more meaningful and cost-effective way.
Now, I turn the call over to Steffen.
Steffen Schewerda
Thank you, Barend, and good morning, everybody. Thanks for having me.
We're on page number 10. To put it in one sentence, 2025 was an outstanding year, especially in terms of order momentum.
Our airport business is seeing very strong order entry, also supported by the launch of our new products. These products are gaining really nice traction, and first deliveries have been made to customers already.
On the walk-in van side, we see a recovery of the market, combined with what we believe is market share growth. On the commercial side, we see some softness, which we are able to partially offset by stronger fleet demands.
Our municipal segment shows very strong quoting and order entry, and that confirms our strategy to expand our geographical footprint. Slide 11, please.
As you can see, our backlog increased by 25% in the fourth quarter versus prior year. That was driven by a 63% increase year-over-year in order entry.
Net sales and adjusted EBITDA in Q4 were slightly below the fourth quarter in 2024. This was mainly driven by the softness in walk-in van and truck bodies and included ramp-up expenses for walk-in van production and additional locations.
Looking at these KPIs, it is clear what the focus points for 2026 are: it is order conversion and profitability. I will explain this a little bit more in detail on the next slide, number 12.
Based on our strong backlog, we are positioned to deliver growth in 2026, which we expect to accelerate throughout the quarters. On the market side, we expect that we will continue to realize strong order entry.
This is driven by market recovery, market share expansion, and also the introduction of new products. On the sales conversion side, our new location in Chicago is now fully operational.
We are starting to deliver the first municipal snow and ice trucks to a major DOT starting in April. The new outfit centers in Minneapolis and Toronto are also gaining traction.
On the walk-in van side, we are already starting to increase output, which we expect to accelerate in the second quarter. On the profitability side, we are executing on vertical integration in our commercial segment.
In addition, we expect to realize material cost savings in the second half of the year, and our cost structure is being aligned as we speak. Our increased output will also result in higher plant efficiencies, of course.
On top of that, we are planning to consolidate some of our warehouses in the Midwest to gain efficiencies in logistics and net working capital. With that being said, thank you, and I hand it over to Henning.
Henning Schröder
Good morning. I describe 2025 as a landmark year for Europe and the Rest of the World in terms of order intake growth and strong profitability development throughout 2025.
As written on page 14, our markets are gaining strong traction, particularly in airport, municipal, compact sweepers, and agriculture. The airport segment is entering a pivotal year with multiple large tenders expected, fueled by rising defense budgets driving military-related demand and increasing local content requirements.
The municipal sector continues to be powered by compact sweepers, delivering double-digit growth for our core products in 2025. Ladog products have exceeded expectations.
We are accelerating our capacity expansion plans, while winter products show a mixed performance due to limited snowfalls across many European countries. Agricultural products showed strong momentum in 2025, growing more than 30% versus 2024, supported by the rollout of the new generation of Aebi Combicut motor mowers.
Slide 15, please. In Q4, we sustained growth in order intake and delivered a significant 25% per year percent year-over-year sales increase, driven by airport, municipal, and spare parts.
I'm especially proud of the team for delivering an exceptional 234% year-over-year increase in profitability, an outstanding achievement powered by strong volumes, solid gross margin performance, and disciplined OPEX control. Proceeding to page 16, our strong 2025 performance provides the foundation for positive year-over-year quarterly and sequential improvement throughout 2026.
On orders, we expect to leverage our expanded dealer network to accelerate the Europe-wide Ladog rollout, build on strong municipal and agricultural momentum following successful product launches, and capitalize on our centralized airport tender team to secure large global deals and increase win rates. On sales margin, we expect to implement factory efficiency programs and finalize production relocations to reduce material costs.
We will utilize our EU pricing engine to optimize margins in spare parts and realize the benefit of implemented price increases across new business and aftermarket segments. On cost control, we expect to capture the benefits of regional back-office consolidation, further leverage our Eastern Europe Corporate Center, and convert disciplined OPEX management into tangible cost savings.
That concludes my comments, and I turn it over to Marco.
Marco Portmann
Thanks very much, Henning, and good morning, everyone. As you have heard already, 2025 ended with significant order momentum as we captured many market opportunities following the acquisition of the former Shift Group.
On page 18, we see this exceptional order performance resulting in a very healthy order backlog of over $1.2 billion, up 21% year-over-year and providing good visibility into 2026. We expect to see significant improvements in net sales materializing in the second quarter, and especially the second half of 2026 out of that backlog.
On the topic of seasonality, our demand cycles generally lead to a strong year-end with a comparatively slow start into a new year. For 2026, we expect this quarter-by-quarter seasonality throughout the year to be even more pronounced than in an average year.
More on this later by Barend. Moving on to slide 19, net sales in the fourth quarter reached $528 million, representing a 6% year-over-year increase and bringing full-year sales to $1.9 billion, a 2% increase compared to 2024.
Looking at our fourth quarter net sales in a bit more detail, sales in North America decreased 2% versus the fourth quarter 2024 due to the pronounced weakness in the acquired Shift businesses with a 5% decline, which could not be fully compensated by the 2% growth in the legacy Aebi North American businesses. Sales in Europe and the Rest of the World increased by a notable 25%, contributing to over 1/3 of total net sales in the fourth quarter.
Looking at profitability on slide 20, on a full-year pro forma basis, we turned a 2% net sales increase into a strong 13% increase in adjusted EBITDA year-over-year, delivering $156 million in full-year 2025 or an 8.2% adjusted EBITDA margin. In our fourth quarter specifically, we converted a 6% net sales increase into an impressive 31% growth in EBITDA versus prior year fourth quarter, delivering $48.1 million of adjusted EBITDA in that fourth quarter 2025, equal to a 9.1% margin.
North America's EBITDA margin was flat on the back of that 2% net sales decrease, while Europe and Rest of the World delivered a significant EBITDA growth with over 600 basis points improvement. Finally, having a look at our balance sheet on slide 21, net working capital decreased by $29 million, or 6%, since September to $423 million as of December 2025.
This decrease was driven by a $38 million lower inventory, reflecting both improved efficiency and the seasonal decrease at year-end. On the back of a strong cash flow in the fourth quarter, our net debt decreased to $437 million as of December 31st, 2025, a decrease of $32 million compared to September.
With this, we have also delivered a first significant step to reduce our leverage, improving almost half a turn to 2.8 times as of year-end 2025, with our communicated targets to improve to below 2.0 times by year-end 2026. That includes my comments, and I hand it back to Barend for closing remarks.
Barend Fruithof
Thanks, Marco. Let me start my concluding remarks with a summary of the key achievements in 2025 shown on page 23.
We're outperforming on synergies, expecting to deliver over $40 million versus our initial $25 to $30 million target. Our intake increased by 22% versus 2024, and adjusted EBITDA improved by 13%, reflecting strong operational execution.
At the same time, we launched new products and opened new locations, further strengthening our foundation and positioning the company for sustainable growth. Continuing on page 24, looking at 2026, we expect a pronounced quarterly seasonality mainly driven by market conditions and geopolitical uncertainty.
Q1 will start slow, as our strong walk-in van orders will convert into revenue beyond the quarter, while the commercial market remains very soft despite some signs of recovery. In Q2, we expect order conversion to accelerate, supported by our ramp-up of production and upfitting capacity.
By Q3, we expect improving market conditions in the commercial and fleet markets, and the realization of procurement synergies. Finally, in Q4, we expect to benefit from the usual seasonal strength, especially in Europe and the Rest of the World.
Moving on to page 24 for the outlook, let me conclude with our 2026 guidance and priorities. We expect net sales between $1.95 and $2.15 billion, and adjusted EBITDA between $175 and $195 million, and a leverage at year-end 2026 at or below 2.
To deliver this, we expect to maintain strong order momentum and accelerate backlog conversion into net sales through better production efficiency. We expect to drive profitability through efficiency gains at legacy Shift, optimized footprint utilization, and delivering our synergies.
At the same time, we will maintain our strong focus on leverage and balance sheet. In short, our 2026 focus is on disciplined execution to sustain and build on the strong momentum achieved in 2025.
That concludes our presentation. I now turn it over to our operator to open up the line for questions.
Operator.
Operator
Thank you. To ask a question, you will need to press star 1 and 1 on your telephone and wait for your name to be announced.
Please limit yourself to one question and one follow-up only. To withdraw your questions, please press star 1 and 1 again.
We will now go to our first question. The first question comes from the line of Gregory Lewis from BTIG.
Please go ahead.
Gregory Lewis
Yes, thank you, and good morning and good afternoon, and thanks for taking my questions. I was hoping you could talk a little bit more, clearly it looks like we got finished and started with some order momentum in the walk-in van market.
Kind of as you see that playing out, what's kind of some of the things that customers are talking about in driving that? One of the things that we had heard last week was around just hey, that the fleet it's just time for some renewal.
Any kind of sense for how much of this is renewal, how much of this is demand, how can you kind of frame that, just giving your confidence in the potential increases in walk-in?
Steffen Schewerda
Right. Greg, good morning, this is Steffen.
I'll take that question. What we are seeing and believing is that it is both.
We are entering a phase of renewal at this point in time, and one market participant is buying more than the other one. We know who the two big players are.
We believe it is a combination of renewal and additional demand, and we see this going forward, not just a blip here over one or two quarters. When we talk to the customers, there is structural and sustainable demand here.
Gregory Lewis
Then I was hoping you could talk a little bit about the backlog. You called out that the backlog points to about 15 is spread out over 15 months.
Is that something where is the duration of the backlog increasing, decreasing versus maybe where it was a year ago? Is part of that a mix of what is being ordered?
Barend Fruithof
Greg, thank you very much for this question. We were able to increase our backlog on a pro forma basis if you compare it with 2024.
There is a bit of a mixed picture, we have a very strong backlog in our municipal business, as well as in our airport business, for example. We were also able to increase our backlog in Europe versus previous year, which is a very good development given the market circumstances.
At the same time, we were also able to massively increase our backlog in the walk-in van business. We're having some challenges in the commercial market, as well as in the truck body market, there we need to do some more work.
We expect that the market will improve, and we see already first signs in that area.
Gregory Lewis
Super helpful. Thank you very much.
Operator
Thank you. We will now take the next question.
The question comes from the line of Mike Shlisky from D.A. Davidson.
Please go ahead.
Mike Shlisky
Yes, hello. Thanks for taking my questions.
Follow up on some of your truck body comments that you made. You mentioned that it's been slow, but there was some excitement about the new truck bodies that you introduced at the NTEA show last week.
Do you think that your truck body business will outperform the broader market in '26 just on that new product? You tell us about how it may have been received out at the show.
What are customers telling you about the new product there?
Steffen Schewerda
Mike, good morning, this is Steffen. I'll take that one.
What we introduced on the show was a new service body on the commercial side. Basically that is part of our committed integration here, more vertical integration.
We talked about this in numerous occasions here. The service body on the commercial side has very, very good feedback.
On the truck body side, the new product we showed was, you could see this on the Isuzu stand, this is a cooperation together with Isuzu. It's called the AdvantIQ.
We are the exclusive partner for Isuzu, getting this into the market. To answer your question, I do not really believe that we will outperform the market here in 2026, but I truly believe that we will put a strong foundation here into place over the next quarters then to accelerate in 2027.
Mike Shlisky
Great. Thanks for that comment.
Secondly, a large e-commerce company has announced in the last couple of days that they plan to scale back or stop using the USPS for a lot of their deliveries. They're one of USPS's biggest customers.
Presumably they kind of have to take some of that delivery volume in-house as well as farm out to the other large delivery providers. If they're using their own vehicles, and I know that they have some of their own kind of custom-made vehicles, but they are a mixed fleet.
If that changes away from the USPS, is that a positive for Aebi Schmidt going forward as far as mix of how much business you can capture now, or was the USPS a pretty big customer and there won't be much of a change here?
Steffen Schewerda
Mike, I believe that this is an advantage for Aebi Schmidt. In this context there was also the notion of, hey, we do it within one-hour delivery or three-hour deliveries where customers pay a little bit more, talking about the same article here, and the same announcement.
I believe it will drive additional demand. The question is what kind of vehicle, what kind of concept will this be, but I believe in our product portfolio we have something to participate in that market and we are in active discussions.
Mike Shlisky
Great. Thank you so much.
Operator
Thank you. Your next question today comes from the line of Matt Koranda from ROTH Capital.
Please go ahead.
Matt Koranda
Hey, guys. Good morning.
I guess I wanted to hear on the midpoint of the adjusted EBITDA guide for '26. Looks like about nearly $30 million in improvement, but I guess you guys have said synergies in total are north of $40 million from the combination.
Obviously that gets realized over a couple of years, just wanted to hear a little bit about how much gets realized in '26 and what's built into the full-year guidance.
Marco Portmann
Hi, good morning, Matt. This is Marco speaking.
Yes, midpoint $185 [million?] of our adjusted EBITDA guidance.
To reiterate in 2025, right, we always said we're going to deliver at least $40 million total now, and out of that we have realized in '25 somewhere in the mid-teens, that's predominantly cost synergies, and we expect the same amount to realize also in 2026 on top of that, keeping in mind that specifically the procurement synergies, they will kick in in the third quarter 2026. Again, that's relating also to what we just talked about is the service body.
We have also revenue synergies which are predominantly kicking in in the second half of 2026 as well, before we will then see the full realization by summer 2027 as we have initially announced pre-merger. We're still fully on track to that, but also keep in mind it's not just the synergies.
If you look at the difference between 2025-'26, there's also one-off expenses that we have to account for. 2025, we faced some additional stuff that isn't part of the adjusted, some ramp-up expenses that are operational, some SOX compliance topics, couple of these things, and also in Q1 now '26, we'll still have some ramp-up expenses specifically in the walk-in van
Matt Koranda
business. Got it.
I wanted to hear a little bit more about the seasonality commentary that you gave in the prepared remarks. It sounds like you said first quarter usually your lower quarter in terms of seasonality, but might be a little bit more pronounced this year.
Could you unpack some of the factors that they're causing the more pronounced seasonality? Is that more pronounced in one of the two segments, in North America or Europe, or is it both?
Just wanted to hear a little bit more about how to think about it.
Marco Portmann
As we commented, right, generally speaking, we do have quite a bit of seasonality, a bit more than maybe typically would be expected, coming especially a little bit from the ordering cycles we see in Europe, but also generally the snow business or snow-related business that we have. As we said, in 2026, this is going to be quite a bit more pronounced, we will see, of course, a slower start in Q1, because these walk-in van orders, while we do have the backlog now, while we still see the good momentum, it will materialize only beginning in Q2 really, and we still have some one-off expenses associated with that ramp-up in the first quarter, we don't have the revenue yet, but also some costs already flowing in.
Now also from a segment view will hit us, of course, in the US, you will see that if you compare Q1 US or North America, as the segment officially is called, versus last year. In Europe, you will see quite a good improvement, Q1 over Q1, but of course, keeping in mind that Europe has had a slow start in 2025.
You see that basically coming in out of the order backlog that wasn't there in Q4, that now leads to that lack of revenue basically in Q1 walk-in vans. Again, commercial truck body, we commented on that, it is a soft market, we still see that, and that will persist through Q1 or does persist through Q1, we can say that as of today.
Of course, the geopolitical environment also didn't really really help in the last couple of weeks, you feel that as well. Then you have basically Q2, Q3 of ramp-up, as we explained, and the fourth quarter really will be, I would say, similar to what you have seen now in the dynamics in 2025, but again more pronounced that this is really the strong quarter where we bring the year together.
We just wanted to be precise on that, to right-size expectations on our quarterly momentum of 2026.
Barend Fruithof
Matt, just to add one point, as we have built the new outfit center in Chicago, and that will help to accelerate our backlog in the municipal area into more sales. We will see already an improvement in March, and that will then go up already in the second quarter.
That's also a good thing then to reduce our backlog and turn it into sales in the municipal area.
Matt Koranda
Very helpful, guys. Thanks.
Operator
Thank you. This concludes the Q&A for today, and I will now hand back to Simone Grancini for closing remarks.
Simone Grancini
Thank you, Sharon. I thank everyone for joining today's call and your interest in the Aebi Schmidt Group.
As always, please reach out to [email protected] if you have any follow-up questions. With that, Sharon, please disconnect the call.
Operator
Thank you. This concludes today's conference call.
Thank you for participating. You may all disconnect.