HubSpot, Inc.
Q3 FY2026 · Earnings Call TranscriptNovember 4, 2026
Operator
Good day, everyone. My name is Ryan and I will be your conference operator today.
At this time, I would like to welcome you to HubSpot's third quarter 2026 earnings call. All lines have been placed on mute to prevent any background noise.
After the speakers' remarks, there will be a question and answer session. If you would like to ask a question during this time, and if you have joined via the webinar, please use the raise hand icon which can be found at the bottom of your webinar application.
At this time, I would like to turn the call over to Vice President, Investor Relations, Geoff Koegler. Please go ahead.
Geoff Koegler
Thanks, operator. Good afternoon, and welcome to HubSpot's third quarter 2026 earnings conference call.
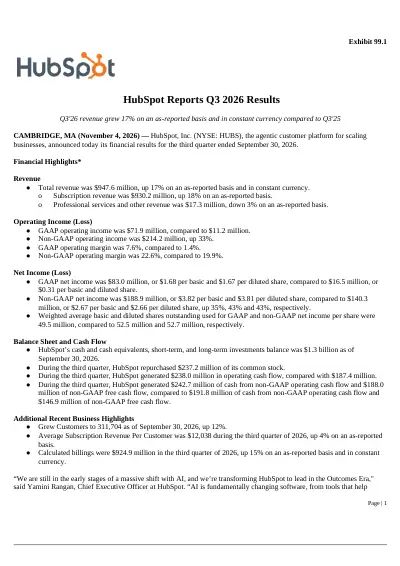
Today, we'll be discussing the results announced in the press release we issued this afternoon. With me on the call this afternoon is Yamini Rangan, our Chief Executive Officer, Dharmesh Shah, our co-founder and CTO, and Kate Bueker, our Chief Financial Officer.
Before we start, I'd like to draw your attention to the Safe Harbor statement included in today's press release. During this call, we'll make forward-looking statements within the meaning of the federal securities laws that are subject to risks and uncertainties, including statements regarding our financial guidance for the fourth fiscal quarter and full year 2026, future financial performance, business outlook, and strategy.
These statements reflect our views only as of today, and except as required by law, we undertake no obligation to update or revise them. Please refer to the cautionary language in today's press release, our Form 10-Q, and our other SEC filings for a discussion of the risks and uncertainties that could cause actual results to differ materially from expectations.
During the course of today's call, we'll refer to certain non-GAAP financial measures as defined by Regulation G. Reconciliations to the most directly comparable GAAP measures can be found in today's press release.
Now, it's my pleasure to turn the call over to HubSpot's Chief Executive Officer, Yamini Rangan. Yamini?
Yamini Rangan
Thank you, Geoff, and welcome, everyone. I'll start with our Q3 results, what drove our performance, and how we are responding to the headwinds we're seeing in the market.
Then, I'll share our progress transforming HubSpot for the AI era. Q3 revenue grew 17% year-over-year in constant currency.
We delivered 3 points of non-GAAP operating margin expansion, bringing our operating margin to 23%. Our total customer count reached over 311,000 globally, with 5,300 net additions in the quarter.
We're still in the early stages of a massive shift with AI, and Q3 reflected that reality. The headwinds we saw in Q2 continued and became more pronounced in Q3.
Let me unpack the two underlying trends, how we are responding, and the early results we're seeing. First, customers are evaluating AI differently.
They want to see AI work with their data in their environment. They want proof before they buy.
We saw the shift early and leaned into it in Q2. We introduced free trials and pricing tied to value and outcomes.
We knew this would extend buying cycles and create near-term headwinds, but we believe it's the right long-term trade-off. We're seeing encouraging early results.
Agent trials grew 64% quarter-over-quarter in Q3, but we're also learning that customers need hands-on support to turn AI trials into real outcomes. Our focus is on improving the trial experience and leveraging our partners and solution consultants to help more customers move from trials to paid adoption.
Second, we are seeing a shift in demand with increased budget sensitivity. AI is changing how customers discover HubSpot and how they make purchasing decisions.
Inbound demand remains under pressure, and we are diversifying to new sources of demand through intent-based marketing, LLM connectors, and AEO. At the same time, tighter budgets are making buying decisions more complex.
Up-market, we're seeing larger buying committees, more CEO, CTO, and board involvement, and therefore, longer sales cycles. Down-market, customers are more price-sensitive and focused on optimizing costs.
We are adapting our playbooks to these new buying patterns. We're engaging the C-suite earlier, involving more stakeholders, and bringing technical expertise into complex deals.
We're seeing early evidence that this playbook works. Win rates are nearly 3 times higher in deals with 5 or more buying committee members when we engage multiple stakeholders.
We're also seeing higher close rates on larger deals with C-suite involvement. Together, these early signs give us confidence that we have the right initiatives in place to address these headwinds, even though it will take some time for them to show up in our results.
Despite the near-term headwinds, we continue to see clear momentum in AI and progress across our core and emerging growth drivers. Multi-hub adoption remains strong as customers consolidated their go-to-market tools on HubSpot.
62% of new Pro+ customers landed with multiple hubs, up 2 points year-over-year. Up-market continues to be a growth driver, with deals over $120,000 growing 19% year-over-year as larger customers turned to HubSpot to consolidate their data and build the context needed to drive AI outcomes.
More importantly, AI adoption is accelerating and credits is emerging growth driver. Monthly credit consumption is up nearly 2.5x since the beginning of the year, with usage diversifying across our agentic use cases.
Active core seats grew 34% year-over-year. These trends reinforce our conviction in accelerating our AI transformation.
At Analyst Day, we laid out how we're transforming HubSpot to lead in the outcomes era. AI is fundamentally changing software from tools that help people do work to agents that do the work and deliver outcomes.
We are moving with urgency to transform our product, pricing, go-to-market, and how we operate to capture this opportunity. In Q3, we made meaningful progress in all of these areas.
We've transformed HubSpot into an agentic customer platform with 4 connected parts. HubSpot agents and custom agents deliver outcomes across marketing, sales, and service.
Breeze Assistant is now the gateway to the power of HubSpot, shifting the experience from how do I do it to do it for me. We believe this is the future of how people work, and we are investing heavily to make that experience exceptional.
Our headless strategy brings HubSpot into leading LLMs through connectors, and enables agents to run HubSpot through APIs. Growth Context makes it all work, giving AI the understanding of a business, its customers, and its teams to take the right actions.
Together, these 4 parts make HubSpot the platform where AI understands the business, does the work, and delivers outcomes. We're making meaningful progress bringing this vision to life.
At INBOUND, we doubled our portfolio of HubSpot agents. We launched Campaign Agent, Content Agent, and Nurture Agent to help marketers build campaigns, create content, and personalize engagement at scale.
We also enhanced Customer Agent, Prospecting Agent, and Data Agent to help businesses resolve support issues, generate pipeline, and enrich customer data. We're seeing strong growth in both reach and depth of adoption.
20% of Pro+ customers now use HubSpot agents, up 11 points since the start of the year. Depth, measured by the total number of monthly agentic actions across our Pro+ customer base, has increased 5x since the start of the year.
More importantly, agents are delivering measurable outcomes. Customer Agent resolved over 2 million support issues in Q3.
Data Agent enriched 68% more contacts quarter-over-quarter. Customers using Prospecting Agent are seeing 76% more qualified leads and 80% more meetings than those who don't.
We're also making it easy for customers and partners to build their own agents and workflows on HubSpot. In July, we launched Agent Builder and Agent Hub, allowing them to build, deploy, and manage custom agents powered by HubSpot's Growth Context.
Since launch, Pro+ customers have deployed over 5,600 custom agents, and partners have deployed nearly 700 in Q3, more than doubling quarter-over-quarter, and we're providing incentives to accelerate this motion. This is an important shift.
Customers are building their own agents to solve problems specific to their businesses, with partners helping scale that innovation. Next is Breeze Assistant, which we believe will fundamentally change how customers work with HubSpot.
At INBOUND, we launched an all-new Breeze Assistant that goes beyond answering questions to taking action. Customers simply describe what they want to accomplish, and Breeze builds workflows, creates reports, and gets work done for them.
We're seeing rapid growth in adoption and customer satisfaction. 61% of Pro+ customers now use Breeze Assistant, up 24 points since the start of the year.
Customer satisfaction has improved 15 points to 69% since the start of the year as well. Take Kaplan Early Learning, a company with hundreds of employees.
Their HubSpot admin previously relied on developers to build and update workflows, which could take weeks. With Breeze Assistant, he rebuilt key workflows himself in under 4 hours, and now uses Breeze every day.
We believe this is the future of work, a conversational experience powered by AI that understands your business and takes action. We're combining that experience with HubSpot's go-to-market domain expertise and Growth Context to make Breeze the gateway to our platform.
To round it out, our headless strategy extends HubSpot wherever customers choose to work with AI. We're building the best CRM connectors for leading LLMs like ChatGPT and Claude, and we are opening up our APIs and MCP capabilities so agents can run HubSpot.
We were the first CRM to connect with all 4 leading frontier models, and today, we are the most popular CRM connector on both ChatGPT and Claude. What is important is what happens when customers connect HubSpot to their preferred LLMs.
They're not just pulling data out of HubSpot. They're doing more work in HubSpot.
They're analyzing reports, managing pipelines, creating CRM records, and taking action, all through conversations. In Q3, customers created over 22 million CRM objects through connectors within HubSpot, up 157% quarter-over-quarter.
The more they work with HubSpot, the more value they get from it. Customers using connectors have 13 points higher gross revenue retention and upgrade paid seats at 3 times the rate of non-connector users.
This reinforces our conviction that headless is additive to HubSpot. As customers use AI to analyze data, manage deals, and take action, they're doing more in HubSpot.
That deeper engagement creates more opportunities for seat expansion, stronger retention, and long-term growth. Now, as we transform our product, we are also transforming our pricing to drive long-term growth.
Our vision is simple, a hybrid model of seats and credits. We began simplifying pricing in 2024 by lowering seat prices, removing seat minimums, and introducing core seats.
While this initially lowered ASP, it has led to healthier customer cohorts with higher retention. Now, we're taking the next step to give customers greater flexibility and predictability in how they spend on AI.
Our pricing pilot simplifies HubSpot in 3 ways. It provides access to all HubSpot capabilities through a go-to-market seat, removing hubs.
It reduces the price jump from Starter to Pro across Marketing, Content, and Data Hubs. Brings all usage-based features under a single credit mechanism.
Early results from our Nordics and Benelux pilots are encouraging. Compared to regions outside the pilot, credit usage is 2 to 3 times higher, Pro+ customer volume is higher, while average selling price is lower.
We're seeing early evidence that this is working: more customers, greater credit consumption, and stronger new ARR. We've expanded the pilot across EMEA in Q4 for new customers, and we will use those results to determine the timing of the continued rollout.
Our goal is to make HubSpot easier to buy and AI easier to adopt. We believe this is the time to remove friction, accelerate AI adoption, and gain market share early in the AI platform shift.
Now, let me just close out with the bigger picture. AI is reshaping our industry, and we are moving decisively to position HubSpot for the next era of growth.
We recognize the near-term headwinds, and we're taking actions to address them. Our core growth drivers remain intact, AI adoption and usage are accelerating, and we're seeing evidence that our product and pricing transformations are beginning to work.
We're making deliberate trade-offs to build a stronger, faster-growing, and more profitable HubSpot for the longer term. We have a clear strategy, we're executing with urgency, and we're confident in the opportunity ahead.
With that, I'll turn it over to Kate to walk through our financial and operating results. Kate?
Kate Bueker
Thanks, Yamini. Let's turn to our third quarter and full year 2026 financial results.
Q3 revenue grew 17% year-over-year in both constant currency and as reported. Q3 subscription revenue grew 18% year-over-year, while services and other revenue decreased by 3%, both on an as reported basis.
Domestic revenue grew 16% year-over-year in Q3. International revenue growth was 18% in both as reported and in constant currency, representing 49% of total revenue.
We added 5,300 net new customers in Q3, bringing our total customer count to over 311,000, growing 12% year-over-year. Our Q3 net additions reflect continued demand pressure and increased buyer hesitancy, particularly down-market.
Average subscription revenue per customer was $12,000 in Q3, up 4 points year-over-year in both as reported and in constant currency. Customer dollar retention remained stable and healthy in the high 80s.
Net revenue retention was 101%, down about 1 point quarter-over-quarter, driven by a step-up in budget sensitivity, which was also more pronounced down-market. Q3 calculated billings were $925 million, growing 15% year-over-year in both constant currency and as reported.
Non-GAAP operating margin was 23%, up 3 points compared to the year-ago period. This expansion reflects our disciplined hiring approach, partially offset by AI costs.
GAAP operating margin was 8% in Q3, up 6 points compared to the year-ago period. This expansion reflects our non-GAAP operating income expansion and a more than 3 point reduction in stock-based compensation as a percentage of revenue.
Non-GAAP net income was $189 million, and non-GAAP net income per diluted share was $3.81, up 35% and 43% year-over-year, respectively. GAAP net income was $83 million in Q3, and GAAP net income per diluted share was $1.67.
In the third quarter, the company generated $188 million of free cash flow, or 20% of revenue. Our cash and marketable securities totaled $1.3 billion at the end of September.
During the quarter, we bought back more than $237 million of stock under our share repurchase program, bringing our 2026 year-to-date repurchases to nearly $1 billion, reflecting the continued confidence we have in our future growth opportunity. Before we dive into guidance, let me share some perspective regarding the headwinds we experienced in Q3, the reorganization we announced in October, and our expectations on the near-term performance of our KPIs.
As Yamini shared, we are seeing shifts in demand and customer buying behavior as customers navigate the AI transition. Up-market, we're seeing more decision-makers and longer sales cycles.
Down-market, we're seeing greater price uncertainty and budget optimization. Both headwinds emerged in Q2 and became more pronounced in Q3.
Our Q4 and full year guidance reflects our expectation that these increased headwinds will persist throughout the remainder of the year and into 2027. Given the transition we are driving across product, pricing, and go-to-market, we are prioritizing setting the business up for long-term growth rather than solving for short-term net adds.
As a result, we are not providing a net adds estimate for Q4, but expect to be below the 5,000 level we achieved in Q3. We expect low- to mid-single digit ASRPC growth in constant currency in Q4.
We now expect full year 2026 net revenue retention to be down about 2 points year-over-year. We expect customer dollar retention will remain strong and stable in the high 80s, but continue to expect net upgrade rates to be pressured as a result of customer budget optimization.
We now expect net new ARR to decline year-over-year in fiscal 2026. On October 6th, we announced a reorganization of our people around customer outcomes, which flattened the organization and created agile teams with clear ownership.
This leaner structure will allow us to operate faster and with more focus on our biggest opportunities, and reinforce our commitment to profitability. We will invest a portion of the savings in employee retention, AI talent, and platform.
We remain confident in delivering our 2027 non-GAAP operating margin target of 23% to 24%, and our long-term profitability targets we shared at our Analyst Day at INBOUND. With that, let's dive into our guidance for the fourth quarter and full year of 2026.
For the fourth quarter, total as reported revenue is expected to be in the range of $945 to $947 million, up 12% year-over-year on an as reported and constant currency basis. Non-GAAP operating income is expected to be between $216 and $217 million, representing a 23% margin.
Non-GAAP diluted net income per share is expected to be between $3.85 and $3.87, representing growth of 25%. This assumes 48.9 million fully diluted shares outstanding.
For the full year of 2026, total as reported revenue is now expected to be in the range of $3.685 to $3.687 billion, up 18% year-over-year on an as reported basis and 16% in constant currency. We expect non-GAAP operating income to be in the range of $772 to $773 million, representing a 21% margin.
Non-GAAP diluted net income per share is now expected to be between $13.59 and $13.61, representing growth of 40%. This assumes 50.4 million fully diluted shares outstanding.
As you adjust your models, please keep in mind the following: Q4 GAAP operating income will include an expected $60 to $70 million charge for severance costs in connection with our October reorganization. We continue to expect capex, as a percentage of revenue, to be 5% to 6% for the full year of 2026, and now expect free cash flow to be about $720 million.
With that, I will turn the call back over to the operator for questions.
Operator
We'll now move to our question and answer session. As a reminder, if you have joined via the webinar, please use the raise hand icon which can be found at the bottom of your webinar application.
When you are called on, please unmute your line and ask your question. Please limit yourself to only one question today.
We will now pause a moment to assemble the queue. Your first question will come from the line of Samad Samana with Jefferies.
Please unmute your line and ask your question.
Samad Samana
Hi, good evening and thanks for taking my questions. I'm going to squeeze in a two-parter here.
I guess first, maybe could you comment on when you started to see trends get worse in 3Q? I guess maybe more specifically, into 4Q has that continued to deteriorate, has it stabilized?
I guess any early green shoots that we can hang our hat on? Then maybe Kate, for you, I would ask, given the exit rate of 12% for 4Q, is that a good starting point for 2027?
I know the company doesn't normally give an early outlook into the forward year, but just given the slowdown, I was wondering if we could get some contours. Thank you both so much for taking my questions.
Yamini Rangan
Hey, Samad. Thank you so much.
This is Yamini. Look, I'll talk about the trends that we saw in Q2, Q3, and what we are assuming for Q4.
The simplest way to describe what we're seeing is that customers are navigating a major AI platform shift. That is changing how they evaluate software, how they discover HubSpot, and how they make purchasing decisions.
That's what we've been seeing. Let me unpack each of those trends.
First, customers want to see AI work in their own environment with their own data. They want to see the proof of AI before they buy.
As we talked about it in the last earnings call, we recognized this shift early, we introduced trials, and we tied our pricing closer to the value and the outcomes that customers seek. Now, trials are growing.
That's the green shoot: 64% quarter-over-quarter growth. They're converting requires hand-holding.
You can't just turn an agent on. Therefore, we are improving the trial experience, we're bringing partners and solution consultants to help the customers get the value faster.
We believe this is the right long-term approach, even though it extends the buying cycles in the near term. The second big trend that we're seeing is the demand environment is changing with greater budget pressure.
It's a couple of different things here, let me break it down. Inbound demand, which we've talked about for a number of quarters, it remains under pressure as AI changes how buyers discover software.
We've been diversifying through the top of the funnel through intent-based marketing, we're now doing LLM connectors as a source for sign-ups as well as leads as well as AEO, but these new channels are nascent, and they don't really meet the changes in the inbound demand. Now, at the same time, buying decisions are very complex.
We've talked about this for a couple of quarters. Up-market, there are larger committees with more CEO, CTO, board involvement.
That's because it's no longer just a technology decision, this is a strategic choice. We are responding by engaging senior decision-makers earlier, we're involving multiple stakeholders, and we're bringing partners and technical expertise earlier within the deal cycle.
Now, again, the green shoot that we're seeing is that in deals with 5 or more buying committee members, win rate is nearly 3 times higher when we engage multiple stakeholders. We're also seeing higher win rate with C-suite involvement.
Finally, down-market, customers are just more price-sensitive because AI is a new line item, and they are looking at controlling the spend across all the experiments and the tools that they're running. We are leaning into it by simplifying our own pricing, we're lowering barriers to entry, and making it easier to adopt AI.
Now, all of these trends, we started seeing in Q2, which is when we shared all of those. It became more pronounced in Q3, and it is reflected within our Q4 outlook.
We're moving very quickly, early indicators of our plays are encouraging, but this is going to take time for the changes to translate into stronger growth.
Kate Bueker
Thanks, and some-- Oh,
Operator
sorry, go ahead.
Kate Bueker
Sorry. I'll follow on Samad to your specific question on the guidance and some of the factors that you should be considering as you think about next year.
Unsurprisingly, I'm sure, we are not providing formal 2027 guidance at this time. As we are early in Q4.
Q4 is our most important quarter, and we are focused on executing a very strong Q4. We are also still early in our 2027 planning process.
That said, I will share a few of the dynamics that might be helpful as you start to think about your 2027 outlook. The first is that in Q3, our revenue grew at 17% in constant currency.
It's down about a half a point from our constant currency revenue growth in Q2. The decrease was a result of the pressure that we've seen this year, which became more pronounced in Q2.
We also expect that these more pronounced headwinds will continue in Q4 and into 2027. Our Q4 guidance obviously implies a more significant step-down in constant currency revenue growth, and the deceleration from Q3 reflects the impact of the more pronounced headwinds on our Q4 results.
In addition, we shared that we now expect that net new ARR to decline year-over-year in 2026. Those are the factors that I would consider as you think ahead into next year.
Finally, I'll remind you that we took the same approach to guidance this quarter as we have always done. Our approach has not changed.
We will obviously share 2027 guidance when we report our Q4 results in February. Until then, we're going to remain focused on executing a very strong Q4.
Operator
Your next question will come from the line of Brian Peterson with Raymond James. Please unmute your line and ask your question.
Brian Peterson
Hi. Thanks for taking the question.
Yamini, I wanted to see if I could get more detail on some of your trial pricing and packaging. I know you said that maybe the upfront ASPs are down, but you're seeing some encouraging dynamics for customers that have ramped.
Is there any color that you can share there, because I think that would give investors confidence that maybe that's good for HubSpot over the long term?
Yamini Rangan
Brian, thank you so much for the question. Let me break it down in terms of the pricing evolution, but also what we are seeing in terms of the pilot that we have in Nordics and Benelux.
Many of you who have followed us for a while know that in 2024, we took a set of steps to simplify pricing. What we specifically did is that we lowered seat pricing, we removed seat minimums for Sales Hub and Service Hub, and we introduced core seats.
That made it easier to buy and expand across our seat-based hubs. Initially, we saw the ASPs decline, but then we attracted more customers, and we saw stronger retention of those cohorts.
That was phase one. Now, we're doing phase two.
We want to further simplify pricing with AI, and our vision is a hybrid model of seats and credits. Seats because it provides access to platform, AI, and data for anybody within a go-to-market team, and credits because it scales with the AI value and the customer outcomes that we deliver.
That's the pricing evolution. Now, specifically for the pilot that we mentioned in Nordics and Benelux, we're doing three things: we're removing separate hub-based subscription, customers can access HubSpot capabilities through a go-to-market seat, no hubs, and that is a simplicity that customers like.
Second, we're actually reducing the price jump from Starter to Pro for Marketing, Content, and Data Hub. This is going to lower ASPs initially, but it is going to do something really important: it's going to remove the friction in pricing, and it's going to lead to more Pro+ customer volume.
This is exactly what we're seeing within the Nordics and Benelux pilots. We're seeing ASPs go down, but we're seeing the number of Pro+ customers go up, which is encouraging.
Third, we're bringing all of the usage-based features into credits. That means emails sent, tickets resolved, data enriched, APIs, all in credits.
That means it's a simpler mechanism, it reduces the friction of adopting credits, and that simplification is something that customers like as well. In fact, we've seen 2 to 3x more credit consumption in the pilot cohorts that we just talked about.
Look, it's early days, but our focus is very clear: we want to remove pricing friction, we want to remove packaging friction, and we want to remove AI adoption friction as we go through this process. As we do that, we have the confidence that over the long period of time, we're setting up for durable growth.
Operator
Your next question will come from the line of Jackson Ader with KeyBanc Capital Markets. Please go ahead.
Jackson Ader
Hey, guys. Thanks for taking our question.
To follow up on the pricing, it's pricing and it's AI adoption, Yamini. When you talk about trying to solve some of the AI adoption with lowering the friction and changing the pricing and packaging with this pilot program, but then on the other side, you're also talking about needing more solution consultants and partners to be hands-on in order to drive, again, more AI consumption and usage in your core customer base.
I'm just curious, is it more about friction in the products and the pricing, or is it more about people just not getting the value that you'd expect them to the first time around when they see Breeze or when they see some of these agents that you're rolling out? Thank you.
Yamini Rangan
Jackson, thank you. I really appreciate the question, and the question is, you're making changes in pricing packaging, and then you're also putting more consultants and partners, and what is the thing that you're actually trying to accomplish?
It really comes to the segmentation that we have. Look, overall, if you really step back, people are trying to navigate a huge platform shift, and they need to have confidence that it is going to work in their environment.
Second, they want to have the predictability in cost. Let me now unpack the dynamics in up-market versus down-market.
In up-market, customers really want to drive the outcomes. They want to drive more pipeline with Prospecting Agent, they want to drive more tickets resolved through the customer support agents, and there, when we introduce the trials, it's not just enough.
We want to be able to hold their hands, which is where our partner ecosystem comes in. We also are putting our solution consultants, and we've always deployed pre-sales and post-sales consultants in the up-market segment.
What we're finding is that when we turn the trials on, checking back in a week, making sure the outcomes are clear, and being able to follow up with some hand-holding is really important to drive that AI adoption. When we do that, we begin to see a lot more uptake.
There are tons of examples of those customers, but Eventus is an example that we talked about. They started with the Data Agent and Prospecting Agent, they did a trial, during the trial their pipeline improved, but we actually put some help in order for them to get those value, and then as they've done that, they've continued to expand.
Now, the dynamic is quite different down-market, because down-market, we're not going to put solution consultants and that's not where our partners focus on. The biggest lever that we have in removing the friction is make the product and the experience for trials really easy and simple.
We've invested pretty heavily on agentic onboarding, which means you give your email, you give your calendar, and you start getting the outcomes as quickly as possible. That's what we launched at INBOUND for the down-market segment.
The bigger problem there is that friction point in pricing that I talked about, Jackson, which is the jump between Starter and Pro for Marketing Hub and Content Hub is high, which is what we're solving. That solves it specifically for the down-market segment when someone is looking to go from a Starter edition to a Pro edition, and that's the set of changes that we're doing.
Look, if I step back, pricing transformation plus product transformation plus go-to-market, all of it is aimed to get our customers, and the segment that we serve, small and medium businesses, really navigate a pretty big shift while being very clear in delivering the outcomes in the way that they want.
Operator
Your next question will come from the line of Elizabeth Porter with Morgan Stanley. Please unmute your line and ask your question.
Elizabeth Porter
Great, thank you so much for the question. Kate, on profitability, just Q4 was a little bit light, and was wondering if you could help us understand what's driving the incremental spending or pressure on profitability?
Following the October restructuring, where specifically are you choosing to reinvest those savings, and how should we think about the linearity of investments relative to the 23-24 margin target that you have for 2027? Thanks.
Kate Bueker
Thanks, Elizabeth. Let me just maybe start by taking you back to the conversation that we had at Analyst Day, which was very much around the transformation that we have been going through as an organization for a number of years now, right?
We have been focused on becoming a more efficient and effective organization enabled by AI, and we have done that in such a way where you've seen us really invest in some places and hold back in other places. Specific to your question on Q3, our Q3 margins really benefited from that disciplined hiring approach that we have been deploying now for a number of years.
If you look at our head count ending in Q3, it's actually down quarter-over-quarter, and that created some positive margin momentum going into Q3. Now, in terms of Q4, the head count reductions that we made as part of our October reorganization will benefit our Q4 operating profit, but we are reinvesting a significant portion of that in employee retention along with selective hiring in AI and some AI product investments.
There's a bit of a seasonal shift in what we're seeing in profitability in 2026, but we continue to expect that we will deliver nearly 2.5 points of margin expansion this year. You also asked about our 2027 and longer-term guardrails for operating profit margin, and we remain confident that we will deliver that 23% to 24% non-GAAP operating margin that we talked about at Analyst Day, as well as our long-term profitability targets that we shared at INBOUND.
Operator
Your next question will come from the line of Billy Fitzsimmons with Piper Sandler. Please unmute your line and go ahead.
Billy Fitzsimmons, please unmute your line.
Billy Fitzsimmons
Hey guys, thanks for taking the question here. With net revenue retention at 101%, and it was flagged that it was under a little bit of pressure from budget optimizations, how much of that NRR pressure reflects fewer upgrades versus customer churn, and are trends meaningfully different between smaller and larger customers or vertical to vertical?
Thank you.
Kate Bueker
I appreciate the question. You're right, net revenue retention was down about a point quarter-over-quarter.
The component trends are very much the same as the ones that we have been talking about for some time. They're just more pronounced in Q3 than what we've seen in the last couple of quarters.
Just to reiterate, customer dollar retention, which is our gross churn, remains very strong and stable in the high 80s. It's the net upgrade that remains under pressure.
Specifically, though, we are seeing the core persona, core seat and persona seat upgrades continue to be a tailwind to net revenue retention, but they are now being more than offset by headwinds elsewhere, which includes cross-sell, contact tier upgrades, edition upgrades, and other cost optimizations that we're seeing our customers do as they come up for renewal. We do expect that these trends will continue, which is why we have updated our view or our expectation for our net revenue retention for 2026 to be down approximately 2 points.
That said, and we talked about it explicitly in some of the pricing discussions that Yamini just had, the seats and credits model really does set us up for stronger net revenue retention over time by lowering the barrier to entry to get started and making it easier to grow AI use cases on HubSpot.
Operator
Next up will be Tyler Radke with Citi. Please unmute your line and go ahead.
Tyler Radke
Thank you for taking the question. My question's just on the timing of some of these changes you're making.
As you think about the rollout that you saw in the Nordics and Benelux, with the trade-off of lower ASPs, how long are you expecting that to take to roll out and sort of the impact on the rest of the business, and how should we just think about that from a timing and revenue impact thinking about 2027?
Yamini Rangan
Tyler, let me take this, and I'll say that in terms specifically of the timing of the rollout, Nordics pilot, we started in April, Benelux, we started in June, and those have been ongoing for new customers on this flexible seats and credits model. In Q4, we expanded it for all of EMEA for new customers only.
That is what is going on. That's now four weeks into that process, and we will use the results to validate customer adoption, credit usage, retention, and the impact on new ARR before we finalize the timing of the broader rollout.
As you can imagine, this is still early within Q4, and we want to see the pilot run through all of EMEA for new customers before we decide the full timing. As Kate mentioned, we'll come back and talk to you about 2027 when we finish out the year and start with the new year.
Operator
Next question will come from Samik Chatterjee with J.P. Morgan.
Your line is now open. Please go ahead.
Samik Chatterjee
Hi, thanks for taking my question and good to get an opportunity to talk to you guys. Maybe on the visibility into the net adds, you're sort of talking about a less than 5,000 customer add into Q4.
Understand some of the industry-wide headwinds you're facing at this point, but when you think about sort of the lower visibility there, can you just flesh that out in terms of how the pipeline looks for new customers, what you're seeing in terms of engagement, and is there a function in terms of maybe more of your resources being diverted towards upsell with the existing customers or the pilot programs where maybe you're sort of seeing the pipeline on the new customer side drop off at the same time? Any sort of more insights on what's going on with the lower sort of numbers there into Q4?
Thank you.
Kate Bueker
I appreciate the question. Maybe I will try to first talk about what happened in the quarter, talk about the underlying drivers of net additions, and then talk about the expectations and guidance that we put forward for Q4.
I'll just start with Q3. We added 5,300 customers in the quarter, which was in line with the 5,000 to 6,000 range that we shared on our last call, but down from the 7,000 net adds we delivered in Q2.
This reflects the demand pressure and the pricing sensitivity that we're seeing down-market. I'll spend just a couple minutes talking about the dynamics that drive net additions, because I think it will help with understanding of what really is going on under the hood.
As we've talked about in the past, our net addition KPI is really disproportionately impacted by down-market customers specifically using our Starter and Pro tiers. The customer acquisition motion for this segment is an inbound product-led motion.
As demand shifts, like Yamini's been talking about, and customers become more price-sensitive, it shows up in net adds in a really outsized way. We're making changes across product, pricing, and go-to-market to address the challenges that we are seeing down-market.
We relaunched our Starter product with a self-updating CRM and agentic onboarding. We're continuing to diversify our sources of demand, including into social, LLM connectors, into partnerships, and also AEO.
We're piloting our seats and credits pricing model to address some of that key pricing friction, especially in the down-market segment. We think these are the right steps to transform our down-market business, but they're going to take time to impact the results.
In the meantime, we expect the level of uncertainty in the metric to be elevated, right? We're not providing a specific expectation for Q4.
That said, we will provide Q4 actual results as part of our February earnings call. We're going to make the right choices to drive long-term growth rather than solving for the short-term metric of net adds.
Operator
Your next question will come from the line of Kirk Materne with Evercore. Please unmute your line and go ahead.
Kirk Materne
Thanks so much for taking the question. Yamini, just maybe a higher-level question for you, which is, you guys have done a lot on product and packaging.
Is there just more to be done in an AI world from a go-to-market perspective with you all? I guess, how are you thinking about that going into '27 in terms of the need to hand-hold perhaps at the higher end of your customer base?
Thanks.
Yamini Rangan
Kirk, yeah, thanks a lot. I think it's all of the above.
This is a pretty massive shift. The way we've thought about it on the product side is product is all about delivering outcomes.
The way we've thought about it from the go-to-market side is putting the resources in the right roles with the right incentives to drive those outcomes. That is broadly how we've thought about it.
Now, it shows up differently up-market and down-market. In up-market, as one of the things, we brought sales and CS together under one organization.
The reason is we want that handoff between starting your first trial to closing the first AI use case to expanding on top of it to be very, very seamless. That is what that organization is focused on, and that's where we're putting the resources.
The second is, I talked a little bit about the trial motion. That's a go-to-market change, right?
We are landing with trials, which means our reps need to be very focused on making sure that during the trial period, there is clear and fast outcome. During the same trial period, we got to bring the partners as well as some of the pre-sales consultants in to deliver the value.
There is just much more closer coordination that's happening from the go-to-market perspective. Then the expansion becomes very, very obvious in AI, because once you land and once you start getting the value, the expansion becomes almost natural.
The kinds of things that we're doing in go-to-market is really tied to how do we land with smaller AI use cases, how do we show value during the trial period, how do we show compounding returns, as AI and agentic use cases begin to drive impact, and how do we make pricing super simple and predictable for the segment that we're really focused on? Those are the sets of changes that we're doing in go-to-market.
Operator
Your next question will come from Siti Panigrahi with Mizuho. Please unmute your line and go ahead with your question.
Siti Panigrahi
Thanks for taking my question. Yamini, I think at a high level, what investors trying to figure out, this transition seems like not a year or two, probably a multi-year transition.
How do you see this, should we expect this growth to stay below this level as you transition, or how should you think about as you try to roll it out, new versus existing, how do you trying to balance growth and profitability?
Yamini Rangan
I think there are two parts of your question. The first part is, it seems multiple quarters, how should we think about the growth trajectory of the company and what gives confidence?
Then the second part is, as you do that, how do you balance growth as well as profitability? Look, I think we've been very clear that this year, we are seeing headwinds, and the headwinds are how are customers evaluating AI, as well as who's making the purchasing decision, and that has impacted both Q2 as well as Q3, and we are facing the same kind of headwinds in Q4.
The short answer is we expect the headwinds to continue into Q4. Now, the path for us back to stronger growth is transforming our product, pricing, go-to-market, which is what we are accelerating.
We've done a number of deliberate choices that creates near-term pressure, but is the right thing for the company and the right thing for our customers as they go through this. Trials is an example, the pilot of seats and credits that we just talked about is an example, and a number of other things where we are investing to help our customers grow.
Now, we are seeing early evidence that the product transformation is working, and we've provided a framework for how you all should be evaluating our product transformation, which is, first one is reach, what percentage of our customers are actually using our AI products and agents? 64% of Pro+ customers are using AI features, and 20% are using agents, and that's up quarter-over-quarter.
Second part of that framework is depth: how many actions are they taking, and are they doing it frequently? Pro+ customers are taking 5x more actions than the beginning of the year, and that means credit consumption is up nearly 2.5x.
Those are the early indicators that the product transformation is beginning to work. We would love to see that accelerate, but we're not satisfied with that, and we're also making sure all of the pricing friction is removed.
Look, the green shoots are there, we have a very clear strategy, but this is not going to be a single quarter or a two-quarter transformation. We are going to take all of the right actions to set HubSpot up to be able to capture the broader opportunity that is ahead.
Then, I want to make sure that I capture the second part of your question, which is you asked, how are you going to balance growth and profitability? The transformation is not just on the product and pricing side, we are transforming HubSpot internally, and that is what has given us the ability to increase our profitability.
Kate just walked through the commitment for this year, she walked through the commitment for operating margin for 2027, as well as the long-term target that we have. We are very focused on balancing both as we go through this transformation.
Operator
Your next question will come from Raimo Lenschow with Barclays. Your line is now open.
Please go ahead.
Damian Cogen
Hey guys, this is Damian Cogen on for Raimo. Thanks for taking the question.
Just a quick one on the win rates comment being 3 times higher when you engage with 5 or more buying committee members. Is there a sense of what share of up-market customers get that treatment today?
What does that multi-threaded playbook do to sales cost and payback period? Thank you.
Yamini Rangan
That's a good question. When we talk about multiple stakeholders, we're talking about up-market customers.
What we are noticing with up-market customers is that they're not doing technology purchase, they're actually making a strategic choice for the AI platform that's ahead, which means they're bringing in CEOs, CTOs, sometimes even the board for approval. That is the shift that's happening within up-market.
The comment that I made about win rates is that our playbooks are changing to accommodate for how buyers are changing and who becomes the decision-maker. Therefore, our sales teams are now really focused on making sure that any large deal that they're working on, they are multi-threading.
They are talking to multiple stakeholders, they're involving our C-level executives and making sure that we have a complete buy-in from up-market buyers for the decision that they're making. Specifically, when they do that, we see the win rates improve, which means that the playbook that we have put in place for our up-market is beginning to work.
We want to double and triple down on that during Q4, but also consistently do that as we go further ahead into next year.
Operator
Next question will come from Terry Tillman with Truist. Please unmute your line and go ahead.
Giancarlo Valle
Hey guys, Giancarlo on for Terry here. Thank you for taking the question.
What AI products do customers see the highest ROI from, and how quickly do they typically see that value? Thanks.
Yamini Rangan
Can you please repeat that question? I think I didn't get the first part of the question.
Oh
Giancarlo Valle
yeah. I guess, what AI products do customers see the highest ROI from, and then how quickly do they typically see that value?
Yamini Rangan
Great. Thank you for that question.
Look, if we step back in go-to-market, the buyers really care about four outcomes. In marketing, they want to build demand, and in sales, they want to be able to win deals and close the pipeline that they have.
In post-sales, it is about delighting customers, and then overall go-to-market is about driving efficiency by scaling growth. If you think about the outcomes, those are the consistent set of outcomes.
Now, in terms of the AI products where we're beginning to see a ton of traction, first is actually creating your TAM, and the Data Agent, and the combination of Data Agent and Prospecting Agent with intent signals is really high value. We've given number of examples, but the easiest way to think about it is take your data in CRM, whether it is company data or contact data, enrich it so that you can prepare the right audiences for campaigns, enrich it so you can drive the right prospecting conversations, and so the consistent one is really Data Agent plus intent plus prospecting.
That is what is driving immediate value, and we begin to see that. The other one, and we've had this as a long-standing one, is Customer Agent.
Customer Agent resolves support tickets, and we are consistently seeing the quality of the resolution of the tickets is high. If customers have knowledge base and they have very clear kind of documentation of the processes, it begins to work pretty immediately.
Now, those are early. One of the things that we have seen from Q2 to Q3 is the diversification across all of these agents.
We now have a fleet of about 8 agents, and there is a diversification in terms of all of these agents, and that shows the value that many of them are beginning to deliver for our customers.
Operator
Your next question will come from Keith Bachman with BMO. Please unmute your line and ask your question.
Keith Bachman
Yes, many thanks for the opportunity to ask a question. I wanted to go back to go-to-market for a second, and the focus is really on trying to understand strategic decisions.
What I mean by that is you're rolling out Nordics and Benelux, and as Yamini, you indicated, you're going to make some evaluations as you roll broader Europe. When you think about the pricing to new customers, I'm trying to understand what would be the criteria to roll it out to existing customers or not?
Because of the implications, I think, on the duration of the transition are remarkably different. Would it be possible to have two-tier customer pricing, one to new customers, one to existing customers?
Because if I'm a new customer and I see lower ASPs, I think I want that. Maybe just help me understand the decision-making criteria, because again, it would have meaningful implications, I think, on the duration of transition.
Love to hear your feedback here.
Yamini Rangan
Sure. Thanks a lot for that question, Keith.
Just to simplify it, we want to be in a world where our growth drivers are credits and seats. That's it.
That is the future world that we want to be in, and there are multiple steps within that process. The first is, in Q4, all of EMEA is now in this new pilot for new customers, and we want to see the impact in terms of adoption for new customers, we want to be able to look at the adoption of AI and how this is removing friction, and based on the results for the new customers, the first step in the decision-making process is how quickly we will roll it out for the rest of the world.
That's the first step in the process. We want to get a complete handle in terms of how this is removing friction for new customers before we get into the installed base of customers.
The next step in the decision-making process, once we get high degree of comfort that this is driving AI adoption, it's removing friction, it's driving more Pro+ volume of customers, once we do that and once we have the new customer rollout, then we'll actually think about the migration. At this point, we're not really focused.
To your earlier question, yeah, this is not one where there is a timeline for a migration. We don't need to have everybody in one.
In the longer duration of time, we want it to be a hybrid model of seats and credits. I understand the question, and we'll continue to be very transparent as we go through pilots and we learn from those pilots.
Operator
Your next question will come from Ken Wong with Oppenheimer & Co. Please unmute your line and ask your question.
):
Ken Wong
Great, thank you for taking my question. I wanted to maybe dig in on what Keith was just asking.
I realize there's no timeline to push this out to the installed base, but based on what you guys have seen in the Nordics, do you get a sense that there is a desire to maybe push that model down to the installed base? What kind of feedback are you getting from customers in terms of that pricing dynamic?
Yamini Rangan
Look, let me just explain the pricing dynamics and the feedback that we're getting from customers. The first thing is that we're just removing the seat lines, and you can just buy a go-to-market seat, which means, if a customer is trying to figure out, do I need Sales Hub Pro with a Service Hub Enterprise, they don't need to do it.
The overall feedback from new customers is that they like the simplicity of just use HubSpot and just use it with a go-to-market seat. Now, that's completely different for existing customers who've already bought hubs and who understand it.
The first part of it is actually much more beneficial for new customers who just want the simplicity of starting with all of HubSpot capabilities. I think the second one is really how do we reduce the friction of going from a low bundled product for Starter to a very high Pro for Marketing Hub, Content Hub, and Data Hub?
Again, that is beneficial for new customers as they navigate their choices that are there. What we're seeing is the volume of Pro+ customers is high, even though the ASP, as you can imagine, is initially lower.
The combination of that means that they will continue to upgrade over time. Then there is a psychological thing that we're seeing, which is if all of your add-ons is just in one usage-based mechanism, which is credit, then there's somehow an easier way in which customers are adopting.
Credit does not become a friction point for new customers. They understand what credits are.
They understand it's for all usage-based mechanism, and therefore they are adopting that more, which is why we see 2 to 3x more credit consumption. Again, this has been tested with the new customers.
It's in all of EMEA. As we complete this fiscal year and come back to you in February, we'll share a lot more details about what we saw in EMEA and therefore the timing of future rollouts.
Operator
This concludes today's call. You may now disconnect.