First Internet Bancorp
Q3 FY2026 · Earnings Call TranscriptOctober 29, 2026
Operator
Thank you for standing by. My name is Trevor, and I will be your conference operator today.
At this time, I would like to welcome everyone to the First Internet Bancorp earnings conference call for the third quarter 2026. All lines have been placed on mute to prevent any background noise.
After the speakers' remarks, there will be a question-and-answer session. If you would like to ask a question, please press star one to raise your hand.
To withdraw your question, press star one again. Please note that this event is being recorded.
It is now my pleasure to turn the call over to Julia Ferrara from ICR. You may begin your conference.
Julia Ferrara
Thank you, operator. Good afternoon, everyone, and thank you for joining us to discuss First Internet Bancorp's third quarter 2026 financial results.
The company issued its earnings press release earlier this afternoon, and it is available on the company's website at www.firstinternetbancorp.com. In addition, the company has included a slide presentation that you can refer to during the call.
You can also access these slides on the website. Joining us from the management team today are Chairman and CEO David Becker, President and COO Nicole Lorch, and Executive Vice President and CFO Ken Lovik.
David and Nicole will provide an overview, and Ken will discuss the financial results, and then we'll open up the call for your questions. Before we begin, I'd like to remind you that this conference call contains forward-looking statements with respect to the future performance and financial condition of First Internet Bancorp that involves risks and uncertainties.
Various factors could cause actual results to be materially different from any future results expressed or implied by such forward-looking statements. These factors are discussed in the company's SEC filings, which are available on the company's website.
The company disclaims any obligation to update any forward-looking statements made during the call. Additionally, management may refer to non-GAAP measures, which are intended to supplement, but not substitute, for the most directly comparable GAAP measures.
The press release available on the website contains the financial and other quantitative information to be discussed today, as well as the reconciliation of the GAAP and non-GAAP measures. At this time, I'd like to turn the call over to David.
David Becker
Thank you, Julia. Good afternoon, everyone, and thank you for joining us.
Let me start with the headline. The fundamental earnings power of First Internet Bancorp continues to improve.
We generated record revenue in the third quarter. We expanded net interest margin for the fourth consecutive quarter.
We grew adjusted pre-provision net revenue 14% from the second quarter. We continued to improve the mix of loans and deposits while deploying capital efficiently.
At the same time, the overall credit normalization we discussed last quarter is on track, with net charge-offs and delinquencies declining meaningfully. For the third quarter, we are reporting earnings of 54 cents per diluted share.
Excluding non-recurring expenses, adjusted earnings per share rose to 57 cents, more than double what we reported last quarter. We also had one significant credit relationship move against us late in the quarter.
I want to address that one directly. Earlier in the quarter, we were working with a franchise finance borrower on a forbearance arrangement.
It was intended to give the borrower time to refinance with another lender. Late in the quarter, the borrower's financial condition deteriorated, and it became clear that refinancing was no longer viable in the near term.
We moved the relationship to non-accrual, we established a $2.6 million specific reserve, and reversed $600,000 of interest income. For this relationship, we believe there remains a path to repayment.
However, based on what we knew at quarter-end, including the delinquent status of the related loans, the prudent course of action was to recognize the deterioration, and we did. That's the bad news in the quarter, but it is important not to lose sight of what happened everywhere else in the business.
Provision expense declined sequentially, net charge-offs fell by more than half, delinquencies fell to 48 basis points from 78 in the second quarter. That includes a significant drop in franchise finance delinquencies.
Those are meaningful improvements, and they show the broader credit trends are moving in the direction we expected. More importantly, our operating performance gave us the capacity to absorb the impact of this relationship.
We produced record revenue, record net interest income, and continued margin expansion, and we still grew adjusted pre-provision earnings by double digits. That's what I mean when I say the fundamental earnings power of this company is improving.
We are confident in the direction of the business as we execute on our strategy with foresight and discipline. Nicole will talk about how that strategy is changing the economics of our business for the better, and then Ken will walk through the financial results and what we expect in the fourth quarter.
Nicole?
Nicole Lorch
Thanks, David. The way I would characterize this quarter is simple: the business model is working.
We're seeing the benefit of decisions we've made over multiple quarters about where we deploy capital, how we fund the balance sheet, and which businesses can generate attractive returns without requiring traditional balance sheet growth. Start with lending.
We continued to move capital out of lower-yielding or exited portfolios and into businesses where we see stronger risk-adjusted returns. New funded originations came onto the balance sheet this quarter at a weighted average yield of 7.51%.
That is the strategy in action. As lower-yielding loans pay down, we redeploy that capital into opportunities with better returns.
Quarter by quarter, that is changing the economics of the portfolio. This quarter, the overall portfolio yield increased another 8 basis points to 6.42%.
The point isn't simply that loans grew, it is what is growing and what is shrinking. Construction and investor commercial real estate, single-tenant lease financing, wealth advisory lending, and embedded finance grew during the quarter.
At the same time, healthcare finance, franchise finance, and residential mortgage continued to run off. That remixing lets us grow interest income faster than the balance sheet.
We don't need outsized balance sheet growth to grow earnings. That's exactly what we've been working toward.
Our fintech partnerships business adds another dimension to that model. Fintech deposits increased just over $1 billion during the quarter to $4.7 billion, including $2.9 billion held off-balance sheet at quarter-end.
Average on-balance sheet fintech deposits increased 40%, giving us additional capacity to replace higher-cost CDs and brokered deposits with lower-cost fintech funding. The value of the fintech franchise goes well beyond funding.
Fintech fee revenue increased 13% from the second quarter and is up more than 190% on a trailing 12-month basis. We added two partners during the quarter and have additional partners in the onboarding pipeline across payments, deposits, and lending.
Fintech is doing multiple jobs for us: it is improving our funding mix, it is generating fee income, and through embedded lending, it is creating another avenue to deploy capital and grow interest income. Those pieces reinforce one another, making the business more valuable as we scale it.
Now, SBA. Production here has been softer than we expected.
Originations increased 14% sequentially, but overall activity did not reach the level we anticipated. Industry volume has been weaker, and we've also deliberately tightened our own underwriting standards over the past several quarters.
Let me be clear about the trade-off we're making. We are not going to manufacture loan growth by compromising credit discipline.
The SBA changes that became effective October 1 reinforce several of the underwriting principles we've been applying for the last year. With industry activity subdued and our underwriting standards tighter, we expect SBA originations and gain-on-sale revenue to remain lower in the fourth quarter.
We can live with that on a short-term basis. Yes, we want the volume, but we want the right volume.
The credit trends David discussed tell us the changes we've made in underwriting, servicing, and portfolio management are having the intended effect. This quarter illustrates something important about the company we have built.
SBA production was below our expectations, and yet we generated record revenue. That does not mean SBA matters less to us.
It demonstrates that our sources of revenue are steadily diversifying. Finally, I want to spend a moment on operating leverage because this is just as central to where we're taking the company.
Our technology strategy is not about implementing AI for the sake of AI. The objective is straightforward: use technology to support more customer activity, more revenue, and more growth without requiring expenses to increase at the same rate.
We're beginning to see tangible evidence of that. During the third quarter, we completed a multi-phase project to automate significant portions of SBA origination.
At current usage levels, we estimate that work creates approximately 620 hours of annual lender and processor capacity. Manual data entry has been reduced by more than 80%, and median SBA approval time in the measured comparison improved by roughly 10 days.
We're now looking at how to apply similar capabilities elsewhere in the company. Step back and the picture is clear.
We're generating higher returns from the loan portfolio, we're lowering our funding costs through fintech deposits, we're growing fee-generating businesses that don't depend entirely on balance sheet growth, and we're creating operating capacity to support growth without a commensurate increase in expense. We have more ways to generate revenue, more ways to fund growth, and more places to put capital to work at attractive returns than we did just a few years ago.
That diversification matters. We are building a company with multiple sources of revenue and growth that build on one another.
The result is a broader, more durable revenue engine and a business model with more levers for creating value. That is what we mean when we say the business model is working.
Ken will now tie these strategies into our financial results and what they mean for the fourth quarter. Ken?
Ken Lovik
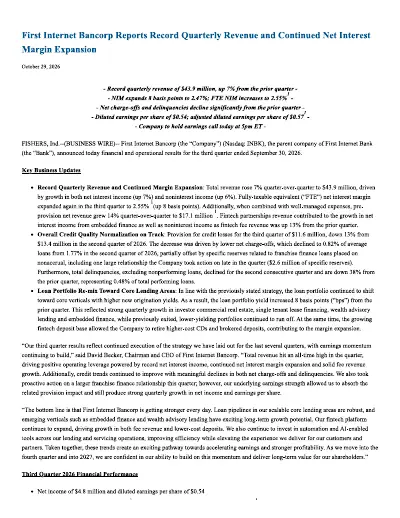
Thanks, Nicole. We reported third quarter net income of $4.8 million or 54 cents per diluted share.
Excluding $400,000 of non-recurring severance expense, adjusted net income was $5.1 million or 57 cents per diluted share. Total revenue reached a record $43.9 million, up 7% sequentially.
Combined with well-managed expenses, adjusted pre-provision net revenue increased 14% from the second quarter to $17.1 million. Net interest income was also a record at $34.7 million or $35.9 million on a fully taxable equivalent basis, up 7% sequentially and 14% year-over-year.
Net interest margin expanded 8 basis points to 2.47% or 2.55% on a fully taxable equivalent basis. Strong growth in net interest income was achieved despite $1.2 million of interest reversals associated with franchise finance loans moved to non-accrual status, which reduced net interest margin by approximately 9 basis points.
Half of those reversals are related to the relationship David discussed. The underlying margin drivers remain favorable on both sides of the balance sheet.
Loan yields increased 8 basis points sequentially to 6.42% as we continued to redeploy capital from lower-yielding portfolios into our core and emerging lending businesses. At the same time, the cost of interest-bearing deposits declined 6 basis points to 3.32% as fintech deposits replaced higher-cost CDs and brokered deposits.
That's the balance sheet strategy David and Nicole described, and you're now seeing it flow through the income statement. As we look at the interest rate environment going forward, we remain modestly liability-sensitive, but materially less so than we were two years ago.
Our loan portfolio is now 57% fixed rate, 43% adjustable rate, compared with 75% fixed and 25% adjustable in September 2024. We have also emphasized shorter-duration securities as we reinvest cash flows.
We analyzed several rate scenarios on a static balance sheet assuming two more Fed rate increases over the next several months, ranging from parallel and ramped rate shocks to a bear flattener scenario with rate increases in December 2026 and March 2027. The most punitive scenarios indicate about a negative impact of 2.5% to 3% on forecasted net interest income over the course of 2027, which we do expect to be up substantially over 2026.
Importantly, though, these are static assumptions. Continued execution of our lending and deposit strategies significantly reduces the modeled effect.
Turning to credit, provision expense declined to $11.6 million from $13.4 million in the second quarter, reflecting lower net charge-offs, partially offset by higher specific reserves on franchise finance loans. That large relationship accounted for $2.6 million of specific reserves.
Including the associated interest reversal, actions taken on this relationship reduced pre-tax earnings by approximately $3.2 million or 29 cents per diluted share. Outside of that relationship, the broader trend improved.
Net charge-offs and delinquencies both declined materially during the quarter, while non-performing loans increased as additional franchise finance balances moved to non-accrual, including $6.6 million related to the large relationship. Now let me turn to our outlook for the fourth quarter.
We continue to expect fully taxable equivalent net interest margin of 2.75% to 2.80% and fully taxable equivalent net interest income of around $38.5 million, driven by continued portfolio optimization and stable deposit costs, assuming a 25 basis point increase in the fed funds rate in December. We expect non-interest income of around $7.5 million, incorporating our revised expectation for lower SBA originations, but offset by continued growth in fintech fee revenue.
Additionally, non-interest expense should come in around $26.5 million. Based on the improving delinquency trends and the franchise finance actions taken this quarter, we expect provision expense of $7.5 million to $8 million.
Those assumptions lead us to expect fourth quarter diluted earnings per share of approximately $1.02 to $1.07. In the second quarter, we reported diluted earnings per share of 27 cents.
This quarter, operating earnings per share more than doubled. We believe it will nearly double again in the fourth quarter.
We believe that outlook demonstrates the underlying earnings trajectory we have been discussing today: continued growth in net interest income, continued margin expansion, growing fintech fee revenue, disciplined expenses, and moderating credit costs. With that, I'll turn it back to the operator for questions.
Operator
We will now begin the question-and-answer session. If you would like to ask a question, please press star one to raise your hand.
To withdraw your question, press star one again. We ask that you pick up your handset when asking a question to allow for optimum sound quality.
If you are muted locally, please remember to unmute your device. Please stand by while we compile the Q&A roster.
Our first question comes from the line of Brett Rabatin with StoneX. Brett, your line is open.
Brett Rabatin
Hey, good afternoon, everyone. Thanks for the questions.
Wanted to start with Ken, maybe just some color around the guidance. When I think about the margin guidance for the fourth quarter, you can kind of do it a couple different ways, but essentially, you're kind of implying a 15 basis point increase in earning asset yields and a 15 basis point decrease in funding costs.
Operator
My apologies, Brett. Sorry to interrupt.
This is Trevor, the Q4 moderator. We're just having a technical issue on our end.
We're going to pause the podcast briefly for technical issues. Please stand by while we resolve the issue.
Thank you. Hello, everyone.
This is Trevor, your Q4 moderator. Thank you for your patience.
We have resolved the issue. Brett, if you wouldn't mind starting your question over again, please.
We will move on to the next question. If Brett would like to redial in and join the queue, that would be great.
Our next question comes from the line of Tim Switzer with KBW. Tim, your line is open.
Tim Switzer
Hey, good afternoon, guys. Thanks for taking my questions.
I appreciate all the color on the potential impact of rate hikes on NII. I just want to make sure I heard it right.
Did you say one 25 basis point rate hike would have about a 2% to 3% impact on annualized NII in '27? Was that the right number?
Ken Lovik
No, it was two rate hikes, Tim. We assumed that we would get a rate hike in December, and we would get a rate hike in March.
Tim Switzer
That
Ken Lovik
is 2%
David Becker
to 3% impact to '27 NII?
Ken Lovik
I would also add to that that also captures kind of the fully baked-in impact of the rate hike that we had back in September as well.
Tim Switzer
Okay. That's very helpful.
If we think about I guess the path of this rate hike cycle, it's obviously a little uncertain right now, but we continue to get several rate hikes at a gradual pace, does that impact change over time or is it pretty consistent?
Ken Lovik
No, the further we get out, I guess as more time elapses, each rate hike becomes less impactful. One thing we did analyze, we looked at another rate hike in September, and that was significantly less, call it 50 basis points.
It kind of ratchets down because if you think about it, we continue to have lower-yielding loans continue to pay down. Those get redeployed into variable-rate channels, such as construction, investor commercial real estate, SBA, or get originated in a higher-rate environment.
We continue to kind of have some of the CDs pay down as well. Over time, the impact of rate hikes get muted.
Tim Switzer
That makes sense. In the scenario with a hike in December, a hike in March, do you think we can have a higher NIM in Q4 '27 compared to Q4 '26?
Ken Lovik
Absolutely. I think the way to think about it, too, Nicole talked about this in her comments.
We get an incredibly powerful bump from just redeploying cash flows from, say, the healthcare portfolio, the residential mortgage portfolio, public finance, and maybe one way to look at it is over the next 12 months, we'll have about, call it $200 million of principal cash flows from those portfolios, as well as throw franchise finance in there as well, at kind of call it a blended 4% to 4.5% rate. Those are being redeployed 300 to 350 basis points higher.
I guess the way to think about a rate hike for us is if we didn't have a rate hike, if we had no rate hikes in the model, understanding that we're going to get less deposit leverage as more CDs roll off, let's just say NIM would be up 20 basis points fourth quarter of '27 versus fourth quarter of '26. That increase gets cut in half.
That would go to perhaps 10 basis points of NIM increase. Our expectation is to continue growing NII, and we do expect NIM expansion.
It'll just be a little bit muted because of the impact of rate hikes.
Tim Switzer
That's very clear. Appreciate it.
Then the other follow-up I have is as we look into 2027, I know that's a little uncertain, but how can we think about the trajectory of some of the key credit metrics and provision costs as we move throughout the year?
Ken Lovik
I think the way that we're looking at it, we gave some outlook on what we think fourth quarter is going to look like. I think a conservative approach would be to say take our fourth quarter and run-rate that for the year.
I think we hope that we can come in better than that, but I think that might be a conservative way to model it as you look at '27.
Tim Switzer
Got it. Okay.
Thank you, guys, for taking my questions.
Ken Lovik
Yep, thanks, Tim.
Operator
Our next question comes from the line of Brett Rabatin with StoneX. Brett, your line is open and thank you for your patience.
Brett Rabatin
Hey, everyone. Can you hear me okay?
Ken Lovik
Loud
David Becker
and clear this time. Yes, we can, Brett.
Brett Rabatin
Okay.
Ken Lovik
[laughter]
Brett Rabatin
Yeah, I don't know what happened, so, anyway, wanted to just go back to the guidance and just thinking about the various numbers. The margin guidance for the fourth quarter, Ken, essentially, we're kind of looking at 15 basis points up on average earning asset yields and 15 basis points down on funding costs.
Is that a fair way to think about the fourth quarter dynamic with the margin, and then the NII guide related to that would kind of suggest flat-ish earning assets in 4Q relative to 3Q? Are those two things kind of in your ballpark of thinking or any thoughts on those two line items?
Ken Lovik
No, you'll probably see on average some growth in interest-earning assets. Again, it kind of comes back to the thing you need to think about and as I explained to Tim and Nicole talked about was just the redeployment of cash flows coming from lower-yielding portfolios.
One thing, too, in the fourth quarter in terms of the impact of the September rate hike, certain of our fintech deposits all kind of reprice in different cadence. While we will get a benefit of a full pretty much across the board on all of our assets, the impact on fintech deposits kind of has to get layered in over the course of a few months.
We don't really feel the full impact of a rate hike immediately on all of our fintech deposits. I do think deposit costs will probably be flat-ish, but the earning asset yields should be up, should continue to grow as they did last quarter.
I think one thing you probably need to think about when you do the math on that is the large relationship that David talked about and some other interest reversals, those did impact margin in the past in third quarter by 9 basis points. They impacted loan yields by 12 basis points.
From kind of period-over-period, the growth might seem like a lot, but when you take into effect what we had to reverse out, I think it's strong because of the assets we're putting on the books today, but it might not be as eye-popping as if you're just doing the math right now.
Brett Rabatin
Okay. That's helpful.
Then on credit, wanted to ask, obviously, you had the franchise finance issue this quarter that would seem to be a bit unexpected, but just wanted to see if there were underlying trends with franchise finance or the SBA portfolio relative to maybe a quarter ago, and then just wanted to get an update, I know that the 2Q substandard or special mention loans were higher due to those commercial real estate loans, those four properties in the non-owner-occupied bucket. They're going to go through stabilization.
Just wanted to see how that was trending for those credits as well.
David Becker
Two of the four credits have been, I guess, raising the ratings on them. They're back to performing and everything's according to plan.
We did have a couple of others. The regulators have made it pretty clear if they're slow on construction, slow on lease-up Obviously, there's some crazy weather going on all across the United States and right now, we have very few construction projects 100% on target and on time that they want us to change the ratings on them because they're not performing to the original plan.
We've had loans move in and loans move out, but we're not worried about credit on any of those loans at the current time. There's no big change other than things are getting better in the SBA and the franchise pool.
The one loan that we had to by policy take the hit on at the tail end, it was literally the Friday afternoon at 4:00 or 5:00 when we got word that the loan refinance was not going to come through before quarter-end, and we made that adjustment. It's a great customer.
He's talking with us, working with us. He's got a business person, he's a multi-franchise owner of different franchises and stuff, and he's got an outside counsel working with him to kind of stabilize his organization, and we think we're going to recover.
We had credit committee this morning. Nobody's sweating that.
We feel at the current time we've more than reserved for that loan and issues, but overall, as the delinquency fell, third quarter versus second quarter, going into fourth quarter, we're starting off with a pretty clean slate and we're looking good for year-end. As Ken said, if you take the charge-offs we did have first and second quarter, take where we're going to be anticipated in the fourth quarter, we've definitely moved the needle by millions over the course of the year.
We think that's a conservative estimate. If you just take that number, run it forward into '27, that we can even do better than that.
No fear on this side. Like you say, we've had an incident with the one loan, but everything else is right on target, doing exactly what we thought it would be doing.
Brett Rabatin
Okay. If I could sneak in one last one just on SBA, thinking about that business into '27.
You've obviously taken a more measured approach to it this year. You've ratcheted down on the underwriting standards, and so that's kind of led to reduced originations and gain-on-sale trends.
Is there more ratcheting still to happen that could reduce that further in '27? Do we grow in '27 on SBA?
Just any thoughts on where you see that business trending relative to the fourth quarter?
Nicole Lorch
Sure. Thanks for the question, Brett.
We are looking forward to 2027 being stronger in terms of origination volume than it has been in 2026. The SBA across the country, production has been off.
SBA recently issued new SOPs that were effective October 1st that changed some of the parameters for business acquisition lending, which is a key component of our SBA program. Much of what SBA is now requiring were things that we had like quality of earnings reports, for instance, on certain size deals, we were already doing that, have been doing that for a year.
I think the largest and most tightening that we did in underwriting guidelines was about a year ago this time. We are getting back to normalizing our volume as our lenders have pivoted, have reached out to new referral sources, and in some ways have even been trying to diversify the types of deals.
We're also seeing that the loan size on average is coming down a bit. Even if they're a little softer, but you're going to see a bigger impact on production volume because the average loan size has gone from little over $2 million to, year to date, it's been more like $1.8 million.
Some of that is because we were seeing disproportionate credit struggles with the larger-size loans, and so we've put more scrutiny on those new loans as they're coming through origination for approval. The loan size has been coming in over the last two years, which has also been going to impact volume.
Brett Rabatin
Okay. That's helpful, Nicole.
Thanks for all the color.
Nicole Lorch
Thank you.
Operator
Our next question comes from the line of Nathan Race with Piper Sandler. Nathan, your line is open.
Nathan Race
Thanks. Good afternoon, everyone.
Thanks for taking the questions. Just going back to the margin discussion a bit, just curious kind of what the deposit growth expectations are for the fourth quarter and thinking about just the size of the balance sheet and earning assets, and to what extent kind of that margin guide contemplates cash coming down.
It looked like it was a bit elevated in the quarter relative to 2Q. Ken, not sure if you could share some thoughts on those topics.
Ken Lovik
I think at quarter-end, our cash balance was elevated. It happens probably more frequently than not because of month-end, quarter-end payment activity from one of our fintech partners, their clients.
The period-end balance was up. Even if you look at the quarter balance in cash, it was elevated relative to where it has been.
We do expect that cash balance to start coming down. Maybe the average balance hopefully will be down about $100 million or so if we look into the fourth quarter and into next year.
A little hard to predict that, but that's what we're forecasting right now. As you're putting that cash to use, right, it's kind of the same thing as redeploying the cash flows from the lower-yielding portfolios.
We got a little bit of earning asset growth. We will have some scheduled larger paydowns in construction happening in this fourth quarter, the period-end balance may be certainly lower than what the average is going to be.
It'll be deposit growth to support that, a little bit unpredictable just because of the timing of when fintech deposits come on, but we do try to push as much of that off as we can to kind of try to start to increase that loans-to-deposit ratio. Kind of all in all, loan growth should be higher than deposit growth because we are putting excess cash to work.
Nathan Race
Okay. Got it.
Then, can you just remind me I apologize, I hopped on late, just kind of what the loan growth expectations are for the fourth quarter and then as you get into 2027 as well?
Ken Lovik
For the fourth quarter, like I said, period-end will not be down, but period-end might be flat-ish because we, as I said, we do have some large payoffs occurring later this quarter in the construction bucket, but the average balance should be up, kind of maybe low- to mid-single digits. I think as we look into next year, we're obviously still working on our forecast for next year.
Again, kind of coming back to a comment Nicole made, we don't have to grow the loan portfolio at a high rate to drive what we would call continued significant growth in NII. If we're thinking about loan growth for next year, let's just call it 10 to 10%, but we fully expect NII to be up much higher than 10% next year.
Nathan Race
Got it. Okay.
Just kind of unpacking the margin drivers around Fed rate hikes or just kind of the key factors that I think you alluded to earlier, just can you just update us in terms of kind of your index deposit levels, maybe on a dollar or percentage basis of total deposits? Then, I think you mentioned the floating-rate loans as well and how that proportions increased, but could you just give us maybe the breakdown more specifically between prime and SOFR just given that SOFR moved ahead of the Fed rate hike at September?
Ken Lovik
I guess the way to look at it is probably everything in the investor commercial real estate and the construction bucket is SOFR-based. Everything in the SBA bucket, the small business lending, that's prime-based.
I think where we feel good on the front end of the curve heading into, again, a potentially rate-hiking cycle is that, as I said, the period-end deposits were elevated, cash was elevated, but if we kind of normalize some of the payments programs we do for our fintech borrowers, you could probably say in the third quarter, normalized deposits from fintech and others that were tied to Fed funds were, call it $1.9 billion. If I look on the other side of the balance sheet, though, we have, as we said on the call, we're 57% fixed, 43% variable or adjustable rate today.
That 43% translates into call it somewhere between $1.6, $1.7 billion. If you extend that to our securities portfolio, where we have been buying variable-rate bonds as well that are generally, again, those are tied to SOFR or prime, that's another $400 to $500 million, we got $2.1 billion of assets that reprice immediately as well, or immediately or within the next 3 months.
Again, I think we've done a lot of things on the balance sheet side to make the asset side far more variable rate, and obviously gives us a lot of protection going into a potentially tightening rate cycle.
Nathan Race
Yep, indeed. Gotcha.
I'm sure it's kind of middle innings of your budget and planning process for next year, but you're tracking for, with the 4Q guide, 10% expense growth this year. Any kind of early thoughts on kind of what the expense growth outlook looks like for next year, particularly if you're growing loans kind of 10%-ish, as you alluded to?
Ken Lovik
No, I think we'll come in lower than that. I think it'll speak to some of the comments that Nicole made about operating leverage and our increasing use of AI to streamline.
I'll tell you, I don't think we have any brand-new positions to hire for next year. We might replace some people, but certainly any headcount, any increases in the compensation line item is really going to just have to do with merit and truing up bonuses.
Again, as Nicole talked about, SBA production is expected to be up next year, we'll have higher commissions there. Our construction business does well, there's incentive comp there.
I think across the board, other than perhaps, as our fintech programs begin to grow, especially on the lending side and paid program management fees, there'll probably be some increase in that loan expense line item there. Most other line items are expected to be either flat to just modestly up.
When you boil all that together, it's much less than a 10% expense growth.
Nathan Race
Great. Then, maybe one last one for David.
Is there a specific TCE or capital ratio target you're looking for to maybe re-enter the market and start buying back shares? [laughter]
David Becker
From my perspective, rather than buying back shares, I'd rather throw out some more loans and make some more money. I think from the capital standpoint, we're good and we're operating within the right parameters.
If we can grow capital, I think we'll grow balance sheet and add more loans and activity. We've got an awful lot of cash sitting on the sideline.
If we can put it to work, NIM goes up, earnings go up, everything works to our favor. Rather than buyback, I think we'll use it to expand the balance sheet.
Nathan Race
Got it. I appreciate all the color.
Thanks, everyone.
Ken Lovik
Thanks, Nate.
Operator
There are no further questions at this time. I will now turn the call back to David Becker for closing remarks.
David Becker
Thanks, Trevor. Thank everybody for joining us today and all your thoughtful questions.
We're sorry for the little snafu we had, but apparently, what worked out great on your end, it was a little choppy on our side. As just discussed here that particularly during the Q&A, we're really pleased with the progress that we made this past quarter.
We're even more optimistic about fourth quarter and where we're going into '27. We appreciate your continued support and look forward to updating you again at the end of next quarter.
Have a good evening.
Operator
This concludes today's call. Thank you for attending.
You may now disconnect.