LCI Industries
Q3 FY2026 · Earnings Call TranscriptNovember 5, 2026
Operator
I would like to remind you that certain statements made on today's conference call regarding LCI Industries and its operations may be considered forward-looking statements under the securities laws and involve a number of risks and uncertainties. As a result, the company cautions you that there are a number of factors, many of which are beyond the company's control, which could cause actual results and events to differ materially from those described in the forward-looking statements.
These factors are discussed in the company's earnings release, Form 10-K, and in other filings with the SEC. The company disclaims any obligation or undertaking to update forward-looking statements to reflect circumstances or events that occur after the date the forward-looking statements are made, except as required by law.
In addition, during today's conference call, management will refer to certain non-GAAP or adjusted financial measures. Reconciliations of these non-GAAP financial measures to their most directly comparable GAAP financial measures are available in the company's earnings release and investor presentation, which have been posted on the Investor Relations section of the company's website, and are also available on Form 8-K filed this morning with the SEC.
On the call from management today are Johnny Sirpilla, Interim Chief Executive Officer; Lillian Etzkorn, Chief Financial Officer; and Kip Emenhiser, VP of Finance and Treasurer. Later in the call, we will conduct a question-and-answer session, at which point you can register to ask a question by pressing *1, and you may withdraw from the queue by pressing *1 again.
With that, it is my pleasure to turn the call over to Johnny Sirpilla. Please go ahead.
Johnny Sirpilla
Thank you very much, operator, and thanks everyone for being with us today. Before we begin, I want to take a moment to express my sincere appreciation to our more than 12,000 Lippert team members around the world.
The financial performance we are proud to be reporting this quarter is a direct reflection of their hard work, commitment, and passion for winning. I also want to speak directly about our proposed merger with Patrick Industries and the recent news you may have heard.
As many of we received a proposal from Monomoy Capital a few weeks ago. Our board took that proposal seriously and gave it careful consideration, consistent with its responsibilities, and ultimately concluded that it was not superior to the proposed merger with Patrick, we declined it.
We are excited for the merger with Patrick and believe strongly in what LCI and Patrick can build together. This combination brings together two companies with complementary strengths, deep customer relationships, and a shared commitment to service.
We expect it to deliver approximately $150 million of net run rate cost synergies within three years of closing. Just as importantly, it gives our shareholders the opportunity to participate in the future growth of a fundamentally stronger company, a company with creativity and flexibility to keep investing in growth while continuing to return capital to shareholders.
At the same time, our stand-alone strategy is active and executing every day, and we see this combination as a natural way to build on that momentum. I'm genuinely proud of our product portfolio, our people, our culture, and the partnerships we've built with customers across the markets we serve.
I like the energy inside the company right now, the teamwork, and the unending desire to win every day. As I challenge this team, they continue to dig deeper and come out stronger.
We are going to stay on offense, and I truly believe the best days of our team, our customers, and our shareholders are still ahead. Now moving to the quarterly results.
Despite the continued economic headwinds facing our industries and the broader economy, our teams have remained focused, engaged, and motivated to deliver. What makes me particularly proud is not just what we are accomplishing, but how we are accomplishing it, through teamwork, accountability, operational discipline, and a shared commitment to continuous improvement.
Our leaders have done an outstanding job of keeping our team members aligned, energized, and focused on the opportunities ahead. That combination of strong execution and a positive winning culture gives me tremendous confidence in our ability to navigate today's challenges while positioning Lippert for an exciting future.
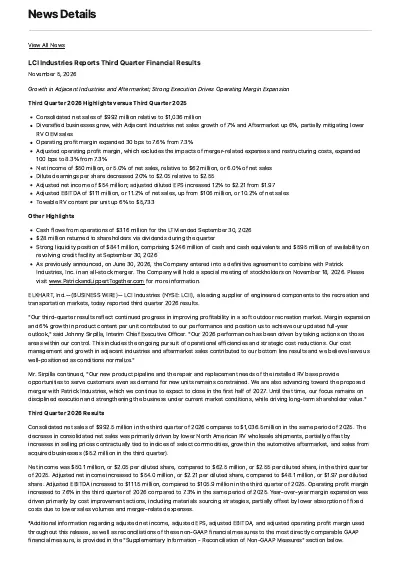
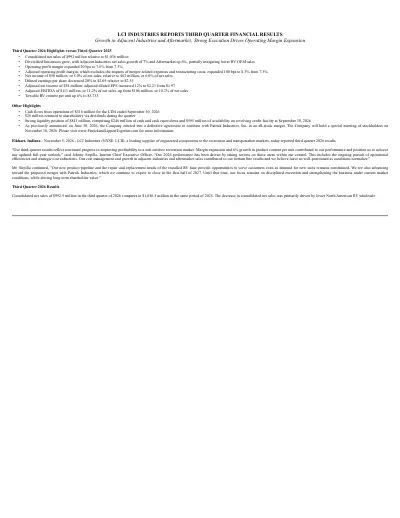
We continued to execute consistently in the third quarter, building on the progress we've made throughout 2026 against the backdrop of continued soft demand across several markets, and with adjustments for restructuring and transaction costs. We expanded our operating profit margin by 100 basis points year-over-year to 8.3%, and grew our towable RV product content per unit by 6%.
Additionally, our diversified business grew, with aftermarket net sales growth of 6% and adjacent industries up 7%, partially mitigating the 17% decline in RV OEM sales. We continue to expand our presence in the transportation markets, launching heavy-duty bus seats and supplying windows in off-road vehicles.
These results show that our strategy is working. We are strengthening profitability at today's industry levels while expanding the drivers of our future growth.
As we approach year-end and look towards 2027, our priorities are clear and consistent with what we've outlined throughout the year. First, we are earning additional opportunities with our customers by delivering innovative products and solutions that create meaningful value for them and their end consumers.
Second, we are diversifying our growth opportunities by expanding our aftermarket presence and our offerings across adjacent OEM markets, further enhancing our well-balanced portfolio. Third, we continue to build on the progress we've made throughout 2026 with our self-help actions and are actively streamlining our operations and cost structure while selectively pursuing accretive M&A.
We continue to leverage our expanding product and content pipeline, while engineering capabilities and our deep customer relationships continue to build on that momentum. As we move forward, our team, led by Ryan Smith and Jamie Schnur at the segment level, remain focused on executing these priorities and advancing the growth opportunities already underway across our businesses.
Our aftermarket business illustrates how we are expanding growth opportunities beyond new RV production. Over the years, we have placed some $20 billion in replaceable parts into OEM products, and nearly 2 million RVs on the road are entering the repair and replacement cycle over the next few years.
By partnering closely with dealers to help consumers repair and replace complex products, we are building another durable growth platform for LCI. Our aftermarket business has grown to nearly $1 billion in annual revenue, and the growth trajectory is bright.
Together with our continued expansion in the automotive aftermarket and RV adjacent OEM markets, this growth underscores the impact of our diversification strategy, reducing our reliance on new unit production and supporting profitable growth across a broader range of market conditions. In summary, we remain confident in LCI's positioning for profitable growth.
We are increasing content through creativity, expanding our aftermarket and adjacent market presence, and improving operating efficiency, with much-improved leverage just since the start of the year, as Lillian will discuss. Our focus is on strengthening performance at current demand levels while positioning the business to create long-term shareholder value.
Thank you to our entire team for its continued commitment to our customers and our business, and I look forward to keeping the investment community updated on our progress. With that, Lillian will now provide a detailed review of our quarterly results and our full-year outlook.
Lillian?
Lillian Etzkorn
Thanks, Johnny, and thank you, everyone, for joining us. During the third quarter, we again delivered solid results despite what continues to be a weaker demand environment for outdoor recreation, specifically RV.
Even with much lower industry-wide RV OEM sales, our revenues were off just 4% over the past year, supported by the growth we were able to achieve in our diversified businesses. Specifically, we grew aftermarket net sales by 6%, and we delivered 7% growth in adjacent industries.
We were also able to grow our operating profit margin by 30 basis points to 7.6%. Adjusted for restructuring, transaction costs, and tariffs, we delivered an adjusted OI margin of 8.3%, which is an expansion of 100 basis points over prior year.
These accomplishments are a testament to the durable, diversified platform that we've built over the years and, of course, the tremendous efforts day in and day out by our skilled colleagues. Combined, the LCI platform is able to not only weather the storm, but deliver enhanced shareholder value creation once conditions normalize.
With this goal in mind, this has been a year of sharp focus on the many self-help initiatives we've outlined, which include thoughtful cost reduction, striving for operational efficiencies, and steadily expanding product offerings. Let us now walk through our consolidated results for the third quarter.
Our net sales came in just under $1 billion and consistent with the prior quarter. This was a 4% year-over-year decline.
The decrease in consolidated net sales was primarily driven by lower North American RV wholesale shipments, partially offset by increases in selling prices contractually tied to indices of select commodities, growth in the automotive aftermarket, and sales from acquired businesses. We continue to focus on providing our customers quality products they want that leverage our creativity and our advanced manufacturing abilities.
By executing on this strategy, we were able to increase RV towable content per unit 6% year-over-year to $5,733. Moving on to aftermarket, as I mentioned, we grew adjusted net sales by 6% over the past year.
The increase was primarily driven by increases in volume in the automotive aftermarket, reflecting growth in towing and truck accessories. From a profitability standpoint, our team was able to deliver consolidated operating profit of $83 million on an adjusted basis, which equates to an 8.3% adjusted operating margin, up 100 basis points over prior year.
Year-over-year margin expansion was driven primarily by increases in selling prices contractually tied to indices of select commodities and cost-improvement actions, including material sourcing strategies, partially offset by lower absorption of fixed costs due to lower sales volumes. In terms of adjusted EBITDA, we produced $111 million on an adjusted consolidated basis, up from $106 million a year earlier, and reflecting a margin of 11.2%, up a full percentage point.
Our GAAP net income was $50 million, with diluted GAAP EPS of $2.05. On an adjusted basis, our diluted EPS of $2.21 was up significantly from $1.97 in the prior year period.
In terms of our balance sheet, we maintain a very solid financial foundation, with cash and cash equivalents of $246 million as of September. With $595 million available under our revolver, we have total liquidity of $841 million.
We ended the quarter with an outstanding net debt balance of $607 million, suggesting a net debt-to-adjusted EBITDA ratio of just 1.4 times, which has improved from 1.8 times at the beginning of the year and places us at the conservative end of our targeted range of 1.5 to 2 times. Our capital expenditures during the third quarter were $13 million, and we paid out $28 million in dividends, or $1.15 per share.
As always, we intend to remain disciplined and balanced with our capital allocation in the quarters ahead. Lastly, I'll provide our updated outlook, which includes October adjusted net sales of approximately $341 million.
For full year 2026, we expect RV industry wholesale shipments to be in the range of 285 to 295,000 units. We look for adjusted revenue to be $3.9 billion to $4.0 billion, and continue to expect to achieve our range of 7.5% to 8% for adjusted operating profit margin, despite the softness across the industry.
This is thanks to our self-help strategies and the incredible dedication of our talented team. As for adjusted EPS, we have tightened the range to $8.25 to $8.50.
We continue to expect full year capex in the range of $55 to $65 million. We are now ready for Q&A, and similar to last quarter, I'll mention that we're understandably limited in what we can say regarding the proposed merger beyond what has already been publicly disclosed.
We're eager to see the benefits come to life for our valued partners and end consumers, given, as Johnny mentioned, the compelling strategic benefits for our industry. With that, if you could please open the lines, we'd be happy to take questions.
Operator
We will now begin the question-and-answer session. Please limit yourself to one question and one follow-up.
If you would like to ask a question, please press *1 to raise your hand. To withdraw your question, press *1 again.
We ask that you pick up your handset when asking a question to allow for optimum sound quality. If you are muted locally, please remember to unmute your device.
Please stand by while we compile the Q&A roster. Your first question comes from the line of Dan Moore with CJS Securities.
Your line is now open. Please go ahead.
Pete Lukas
Hi, good morning. It's Pete Lukas for Dan.
Just looking at your revised outlook of approximately flat for RV demand and shipments next year, what gives you the confidence that this year is the bottom, and how are you thinking about potential for upside or downside to those projections? In other words, is the risk skewed higher or lower in your view?
Johnny Sirpilla
That's a good question, Pete. Being in this industry for 35 years, I've seen the cycles, and one of the ways that we really gauge it is listening to our customers and listening to the dealers on the RV side and hearing directly from them what they're doing in order to manage the business.
One of the things I can tell you is that we've been really happy with what we've heard from dealers in terms of their inventory that they have in stock. We think the OEMs have done an outstanding job of managing inventory with their dealer partners.
As we look at what we see today and what we feel on the market by watching the numbers, we feel good about this range that we're putting out today. Year after year in doing this, I understand that we can only make decisions off of the data that we have in front of us today.
We continue to prepare. As you see with the impact that we delivered on the OI side and being up 100 bips for this quarter, again, and consistent with this year, we've managed to those expectations or the realities that come even if we were a little bit below plan for wholesale production this year.
Lillian Etzkorn
Pete, it's Lillian. Just to clarify, because I think when you started the question you were referring to our outlook for 2027.
The outlook that we put out there for wholesales reflects 2026. We'll provide more details for the 2027 outlook for wholesales and retail when we do our fourth quarter call, just to be clear on that.
Pete Lukas
Very helpful, thanks. Then just last one for me.
Can you talk about your expectations for organic content growth in both RV and marine over the next several quarters?
Johnny Sirpilla
Our customers continue to choose us. We see that in meeting after meeting, that our sales and ops teams work closely with our customers, and so we're confident of what we saw this year in the 6% increase on the RV side, and great results as well on the marine side with them choosing us.
We feel really good about that. Our good, better, best product offering is one of the things that is really a great process that we've worked together with really creating innovation and new products for our customers that fall into those good, better, best categories where they can choose and decide what works better for their various price points that they offer.
We have good confidence in that.
Pete Lukas
Great, thanks. I'll jump back in the queue.
Operator
Your next question comes from the line of Craig Kennison with Baird. Your line is now open.
Please go ahead.
Craig Kennison
Hey, good morning. Thanks for taking my questions as well.
Wanted to follow up on the content per unit trend. I think in towables, it was up 6%, and there was also a note on a shift towards more single-axle trailers, if I'm not mistaken.
Curious if you could sort of reconcile that trend, and I'll have a follow-up.
Johnny Sirpilla
Thank you, Craig, for the question. Quite simply, we've seen consistency on that trend on the single axle and expect to see more of that into next year.
Craig Kennison
Thanks. Just thinking about the content per unit growth in the context of the merger, I know you're limited in what you can say, but have you seen any behavior shift among your OEM partners who are saying maybe it's an important time for them to diversify to protect their strategic interests?
Johnny Sirpilla
I would say that our OEM partners have asked all of the right questions, and we've really appreciated the opportunity to engage with them. Our teams develop such close relationships with our customers that we've really had good open dialogue.
What we've heard is that they are wanting to see the statements that we've made in terms of what we believe that we can do for affordability for the industry and what we can do together with this merger, that they're looking forward to seeing us do that. I believe that they have confidence that we can, but of course, for them, they need to see the proof of that, and that's what we're here to do as this merger gets to a close and deliver that to them.
Craig Kennison
Thank you.
Operator
Your next question comes from the line of Scott Stember with ROTH Capital Partners. Your line is now open.
Please go ahead.
Scott Stember
Good morning, and thanks for taking my questions as well. Just focusing on the cost cutting and facility rationalization process, which has had a great impact on your margins.
In past quarters, you've given an update of how many facilities have been consolidated, and just basically giving us a line of sight of how long that will positively benefit margins. Can you potentially do that?
The other part of that, to the extent that you can talk, is if the merger does take place, does the narrative or the line of thinking for some of those consolidations change?
Johnny Sirpilla
Great question, Scott, and thank you for asking that. We remain on pace and on target for the 8 to 10 facility consolidations that we talked about, and right now in Q4, we're in the heat of that in this quarter, wrapping those up into Q1.
We have been on target for that throughout the year in the planning, and feel really good about where we are and being on pace for that. I would tell you as well that at Ranch Hand, that facility consolidation in Texas is going into a new facility that's absolutely amazing.
This new facility will increase our capacity by about 2.5 times. We currently are going into that facility with 20 weeks of backlog, which this is going to help us very strongly by that, and we will have that consolidation move completely finished and up and running fully by the end of the year.
As you said with the merger and what's ahead, it really creates more opportunity for footprint optimization. It does not impact negatively in any way all that we have planned because we've done a lot over the last 12 months.
We still have, in this next quarter, the final execution of the 8 to 10 that are in play. The merger creates a wide-open field for more opportunity for footprint optimization.
Scott Stember
Got it. Then just on the aftermarket, last question.
Lillian, you made some comments. It sounds like the CURT side of the business probably did a little bit better.
Could you parse out the legacy pure RV side versus CURT?
Lillian Etzkorn
Good morning, Scott. Thanks for joining.
I'd say really across the aftermarket business, the team performed quite well. We highlighted the towables and the CURT side just because we have been seeing exceptional growth there, and it also leads into the strength that Johnny was just talking about in terms of the strategy with Ranch Hand and opening the new facility.
On the OEM aftermarket side, we are still seeing nice growth there and penetration. We've talked in the past around the addressable market and as we've increased the content over the past several years, as those units are now coming into the service and repair cycle, we have the opportunity to capture those sales, the business, and to support the customers as they continue to enjoy and utilize their RV going forward.
Scott Stember
Got it. That's all I have.
Thank you.
Lillian Etzkorn
Thanks, Scott.
Operator
Your next question comes from the line of Tristan Thomas-Martin with BMO Capital Markets. Your line is now open.
Please go ahead.
Tristan Thomas-Martin
Good morning.
Johnny Sirpilla
Good morning, Tristan.
Tristan Thomas-Martin
Johnny, I think you referenced good, better, best product offerings. Which of those buckets are your customers favoring as they start to think about model year '28?
Johnny Sirpilla
It's in the good range. Continue to look for affordability and value to the customers right now, those goods stand out.
Tristan Thomas-Martin
Thank you. Then just on the kind of the ongoing cost inflation, how are you thinking about that?
Then how should we think about kind of the index pricing plus and takes in 4Q and maybe early into next year? Thank you.
Lillian Etzkorn
Sure.
Johnny Sirpilla
Go ahead. You start, I'll jump in after.
Lillian Etzkorn
Perfect. Tristan, as with the commodities, most of that is on an index-based pricing.
That continues, and that specifically addresses steel and aluminum. If you recall, there's a little bit of a lag on some of that, maybe up to one to two quarters in terms of being able to pass that through.
I should note, it passes through both if costs go up, and the prices reduce as commodities come down, which hopefully they will at some point. Clearly, at this stage, we're not seeing that relief, but the index pricing does work both ways.
Johnny Sirpilla
Tristan, I want to add to that, I meet twice a week with our Chief Supply Chain Officer, Scott Meiner, who just does an outstanding job. Yesterday, we had in-depth conversations about steel and aluminum and the work that our team is doing to continue to look to bring procurement value to our customers.
The commitment that he has, and it's a tough market right now in steel and aluminum, and so he's working hard to mitigate, especially on the conversion costs that we see. He's doing a really nice job on that, he and his team.
We're super proud of. That's something that we continue to focus on and look to work with our customers the best way possible.
When you look at the improvement that we've seen in operating margin this year, again, procurement has been a big part of that in terms of helping to us to be able to mitigate some of the price off to our customers, as well as ensuring that we're doing the best job procuring the products and working to drive our margin in those positions as well.
Tristan Thomas-Martin
Got it. Thank you.
Operator
There are no further questions at this time. I will now turn the call back to Johnny Sirpilla for closing remarks.
Johnny Sirpilla
Thank you. This has been a really good quarter that, again, I'm so proud of our team, and I spend a fair amount of time each week in our plants, and what I see there is clearly the results that we did not deliver this quarter's results by chance.
It's really thousands of people that are showing up every day with a commitment to excellence and supporting one another, and serving our customers, and just finding better ways to drive the business. When I see in our plants, our leadership action plans and the continued investment in the professional development of our team members, it's really great to see not only their personal goals being set, but their professional goals where they're attending local colleges and strengthening their capabilities and expertise in human resources, and safety, and quality, and lean manufacturing, maintenance technology.
What we're really doing is building the bench of leadership depth and the technical capabilities that are really essential to our long-term performance. I really wanted to highlight in my closing remarks and share these observations with the investment community because it's this continued development of our team members that directly influence our financial performance.
The quality improvements that we've seen that costs can be reduced happen at their hands, and the operational efficiencies that expand our margins, again, all of this happens on our plant floors through the dedication and the capability of those team members. Again, I just want to give a shout-out to the team, 12,000 strong across the world, very proud of them.
Proud of everyone as well for working through this time of change as we work towards our planned merger with Patrick, and I appreciate everyone's commitment to that. With that, I want to thank you all for joining the call, and thank you very much for your continued interest in LCI Industries, and Lillian and I look forward to more conversation as you need us.
Thank you.
Operator
This concludes today's call. Thank you for attending.
You may now disconnect.