Prysmian S.p.A.
Q3 FY2026 · Earnings Call TranscriptOctober 29, 2026
Operator
Welcome to Prysmian 9-Month 2026 Integrated Results webcast and conference call. At this time, all participants are in listen-only mode.
After the speakers' presentation, there will be question-and-answer session. To ask a question during the session, you will need to press *11 on your telephone.
You will then hear an automated message advising your hand is raised. To withdraw your question, please press *11 again.
Please be advised that today's conference is being recorded. I would like to hand the conference over to Massimo Battaini, Chief Executive Officer of Prysmian.
Please go ahead.
Massimo Battaini
Thank you. Welcome, everyone.
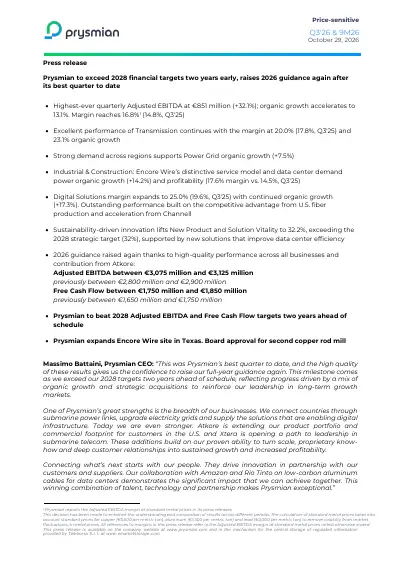
This is again our best quarter yet. We had a great quarter in quarter two 2026, but we've beaten that record with €120 million EBITDA additional in quarter three 2026.
€851 million marks a new level of profit for this company. It's well ahead of quarter three last year '25 with €200 million additional.
You see the numbers are very good from every angle. You see the EBITDA sequentially over last year.
The EBITDA margin close to 17%, two percentage point higher than what it was two one year ago. What is particularly interesting and is not yet visible in the numbers, but it will be visible through the rest of the presentation, is the outstanding, unique performance of INC United States, where we've beaten all expectations in terms of absolute EBITDA and in terms of EBITDA margin, well above 24%, 25% in that quarter.
I'd like to move to the second page, where you see the trajectory of what we've done in the last 3 years. €1.6 billion was the starting point at our Capital Markets Day '23.
3.1 is a milestone, it's not the end of the journey. The end of the journey is much better in 3, 4 years according to what will be disclosing at the Capital Markets Day 2027.
You see the acceleration of the company from an 8% CAGR over '22-'23 to a 3 times higher CAGR over this period '24-'26. Then you can sum up the numbers of EBITDA coming from the five acquisitions or let's say the four that are listed in part in 2026, you find a €1.5 billion incremental EBITDA from '23-'26.
The great news for us, and also for you, I hope, is that half of the number came from inorganic moves, acquisitions, half of it came from organic decisions. Obviously we made the right choices on both fronts, for M&A and for CapEx and for deployment of capacity increase to support the growth of the market, to support our customers, and capture as many opportunities as possible to make this growth sustainable in the long run.
Lastly, you see we've beaten already, as usual I should say after a few years, the target of '28, Capital Markets Day target, we've beaten it in 2026. Atkore has been added to last relevant acquisition, relevant because they are all playing an important role in driving the growth of Prysmian towards this solution provider objective.
We sit now on a 45%, 48% revenues of the company that we can consider solutions, not just pure cable. This is relevant because the more you shift to solution, the higher your EBITDA margin becomes.
This was pretty well visible in the trajectory of the EBITDA margin that you've seen in the prior page, finding three page. Atkore gives us additional components to make the installation of cable possible.
Xtera gives us the repeaters that combined with cables make us a real players in the submarine telecom data business, which is growing faster, which is a space that we would like to own some important share of. Investment in Xtera and the organic capacity increase in cables and the organic capacity increase in installation vessels will open us to an important role in this space.
Transmission continue with a strong growth, which has actually accelerated. 22% is the growth year-over-year.
€60 million is additional EBITDA in this quarter versus last year, quarter three. EBITDA margin is extremely solid, 20%.
We will have a further enhancement of the margin in quarter four, and the organic growth for the full year will be in the high-teens level for the full year. And €213 million is the highest ever EBITDA delivered by this business in a quarter, but the remarkable number will be the full year result 2026, which is says another important sizable improvement above the already outstanding €580 million that we deliver full year last year.
Power Grid, middle single-digit, high single-digit growth. We are a little bit constrained by our decision to reallocate some of the medium voltage capacity that we have in Power Grid to INC because the demand of data center is so overwhelming that we didn't want to miss that opportunity.
The organic growth is limited by this. EBITDA margin continue this trend, the journey to catch up with the original 14.5%, 15% as soon as the inflation will stop growing so fast, the formula will recognize the full price impact of the cost so that we will be able to restore the 14.5%, 15% EBITDA margin in Power Grid business.
Demand is strong across the segment, across all geographies, and you will see this in the coming quarters. This is the star of the quarter.
You see €304 million, €100 million higher than last year. 17.6% EBITDA margin for the INC business is totally unprecedented.
Even more unprecedented is that inside this €304 million there is Encore, legacy Prysmian plus Encore business in U.S., which outperformed all historical numbers of this business with a 27% EBITDA margin in quarter three. The organic growth at the group level marks a 14% increase, but North America grew 24% in this quarter year-over-year.
Behind the growth, you've seen the prior page, there are choices, decisions we made in the past years. Of course Encore Wire is the most evident reason for making Prysmian a leader in this space, but last year we invested in capacity in metal-clad cables, special cable for data center.
We invested in medium voltage capacity, and this capacity will come online in quarter one, quarter two, quarter three for the next eight quarters will be one additional line per quarter coming online to serve data center, electrification, and partly Power Grid. It's also the result of the choice we made in the past to vertically integrate Encore with the rod capacity and compounding capacity.
Never has the rod capacity in-house been so critical to the expansion, to the growth. The market in U.S.
is super tight. Copper rod imported from outside is charged with a tariff of 50%, making the rod coming from imports not accessible to local players.
Market is tight. Having a rod capacity in-house is essential.
Adding a second rod, this is the decision we made last night at the board, is crucial to avoid to constrain the growth of the business because we lack raw material. The rod in-house will allow the chance to buy more cathode to serve this rod equipment and buy more waste that is available in U.S.
to make this rod cheaper and also friendly from an environmental point of view. With the medium voltage capacity I mentioned, eight lines coming, there's a new investment in metal-clad, specific cables to serve data center that's going to become live towards the end of '27.
This investment approved again last night by the board. We are deploying more or less €700 million over €700 million of capacity increase, vertical integration, medium voltage, and specific cable for data center because the demand is overwhelming, and because Encore, Macomb, and Prysmian U.S.
is best suited than anybody else to serve large project with our scale and our best service. This is what data center want: scale, volume, and lead time as short as possible.
We outperform everybody else with regards to these two KPIs, super critical. Specialties, here we enjoy stability per se is moderate organic growth, €60 million-€70 million EBITDA per quarter, decent profitability.
The market is not growing fast in this segment, but part of these products are going to be redirected to data center. I expect to see some additional better growth in the coming quarters thanks to this combined opportunity of expanding our portfolio inside data center also with special cables.
Digital Solutions is also outstanding in terms of performance, no? We had this 19.6% EBITDA margin last year, which was the result of the first quarters coming after the acquisition of Channell.
Before then, the EBITDA margin has been hovering around 12%, 13%, 14% max. We are now twice as much that number, 25%.
Our journey will bring the 25% to 28%, 29%, 30 points probably. Of course we need more volume, which is what we will unlock with the new capacity in U.S.
and outside U.S. and thanks to the agreement that we sign.
That numbers is written in a stone. We'll have 28% to 30% EBITDA margin thanks to the backlog of revenues in our hand.
Outstanding performance also in terms of innovation and sustainability. You see all the KPIs.
Recycled content is not just a matter of green products, is also a matter of making us able to deliver more volume to the market thanks to the ability to recycle waste in a situation where the market is tight, especially in U.S., but in general across all geographies due to this geopolitical situation when it comes to aluminum and copper. We have signed important agreement with Amazon to provide them with green cables, low-carbon aluminum.
Hollow-core fiber has almost finished the industrialization phase. We have some volume, produced some volume ready for sales.
We'll start selling this product to the market as early as January next year. The long-term agreement with our copper supplier speak for itself to provide solidity to our supply chain in this constrained world in terms of geopolitical tensions.
Let me hand over to Francesco for more financial insights and free cash flow, working capital trends.
Pier Francesco Facchini
Thank you, Massimo, and good morning to everybody. A quick wrap-up of the profit and loss.
Organic growth has been very strong the third quarter, plus 13%, a very sharp acceleration from the first half, mainly across Transmission, INC North America, as Massimo said, and definitely Digital Solutions. Best quarter yet in adjusted EBITDA.
You see on the right part of the slide, 851, growing more than €200 million from last year, and an outstanding margin, very close to 17% for the quarter at standard metal. You see that the progression is quite spectacular, I would say, in Transmission.
You see the progression over the quarters. In Electrification, driven by INC, specifically North America, and also in Digital Solutions.
Going to the bottom line, same message, I would say. The group net profit is very close to €1 billion.
It is outstandingly in line with last year if you think that last year, 9 months 2025, was impacted by more than €350 million gain on the disposal of our YOFC stake. Despite this huge positive impact last year, we are in line with that.
This will translate into an estimate of earnings per share for the full year, which will be my estimate around €4.6 per share, which is, very similarly to the EBITDA, in line with our 2028 targets two years earlier, two years in advance. A very similar trajectory.
Massimo Battaini
Maybe we are setting targets too easy for the future. We'll have to harden at the next Capital Markets Day.
Pier Francesco Facchini
Could be! [laughs] Okay, let me move quickly to the free cash flow.
Over €1.4 billion free cash flow in the last 12 months, boosted obviously by the inflow of the Molex down payment for approximately €550 million in euro equivalent. Of course boosted by the very strong third quarter in terms of cash from operations driven by EBITDA, but also impacted by a sharply rising metal prices, which kind of reached the peak in terms of impact in the third quarter compared to the prior year.
Let me hand back to Massimo for the guidance.
Massimo Battaini
Simple and easy numbers here. €3.1 billion is the midpoint of the new EBITDA.
You see on the right-hand side the bridge that explain that this number doesn't come from Atkore. It comes from Atkore for a minor part, namely €50 million.
The rest of the €250 million uplift is business performance, is business growth, and you see it in Digital, in Transmission, and in INC. Free cash flow enhanced from 1.7 to 1.8 is €100 million out of €250 million additional EBITDA.
You have to know that apart from the metal costs that has impacted adversely our net working capital, we want to invest more. We want to invest more because we see a huge spectrum of opportunities in front of us in U.S., but also in other regions.
Those investments will help us pave the way for a solid and robust growth in the next 3, 4 years, which, again I repeat, we will disclose you more about it in quarter two I think '27 at the next Capital Markets Day. To conclude, solid growth achieved in quarter three, but high-quality growth.
It didn't come from one-off, it came from something that is what we focus on is something that is paying off for the investment, for the relationship with customers, for the M&A that we've done in the last 3 years. Return on what we've done so far.
Atkore will help us additionally strengthen U.S. position.
Xtera gives us the opportunity to expand a submarine telecom business that for us has been negligible for years. Beating the '28 target, the Capital Markets Day target, 2 years ahead of schedule is a big big reward for the work done by the company in the last 3 years.
Thank you, and we'll hand over to you for your Q&A.
Operator
Thank you. To ask a question now, please press *11 on your telephone and wait for your name to be announced.
To withdraw your question, please press *11 again. Once again, that's *11 for questions.
A moment for our first question. We will now take our first question from the line of Daniela Costa of Goldman Sachs.
Please ask your question, Daniela, your line is open.
Daniela Costa
Hi, good morning, everyone. Thank you so much.
I have three questions, I'll ask them one at a time. First, just digging into the Transmission backlog, which went down slightly sequentially.
Just wondering, as you look at the coming next 12 months, do you see that going back up? How does it look basically in terms of contracts for '27, I guess, especially on the face of the recent regulatory shift in Germany from underground towards overground?
How do you see the progression?
Massimo Battaini
Thank you, Daniela. You're correct, backlog went a little bit softer this quarter due to the lack of order intake.
The market is not as strong as we anticipated during the first 9 months. There have been one important driver of reduction in order intake is some delays in Terna delays, nothing to with performance.
Delays in some projects coming from Italian TSO. We expect those projects not to be awarded this year, they will probably be awarded in quarter one next year.
That's why if you read the order intake of the market in '26, you'll find slightly down on the expected €10 billion-€12 billion level. There will be the catch-up next year as due to the phasing of this specific order.
Then don't forget that our €16.5 billion is still a bit higher than what we like to have given the fact that in some instances, due to the saturation of the current assets and the additional asset that come live in the next 12 months, we can still not participate to some of the bids. So €14 billion backlog is the healthy level.
Now we are building a new backlog inside this €16.5 billion, the backlog coming from submarine business with Xtera. We won a €200 million project to connect New Jersey to the UK even before we sign the closing with Xtera.
We are going to build on these capabilities, adding cable capacity and vessels to become a real player in the space that is growing fast.
Daniela Costa
Thank you. That was actually going to be my third question, I'll ask them as the second.
When you see submarine telecom, is there scope to do more inorganic activity there to get bigger? Is this mainly an organic journey?
How large can this be for the group in a couple of years' time or what's your desired position there?
Massimo Battaini
Yeah. Today until now this business been a €50 million-€60 million revenue business.
We're planning to grow it to €200 million-€250 million thanks to the Xtera acquisition and the organic expansion. Inorganically, yes, is an option, but there are three large players in this space.
We are working and we will see. It's not simple because the three large players are pretty large, and also they enjoy the moment.
Market is booming on the back of data center expansion. The oceanic interconnection needed to connect European data center to U.S.
data center. Organically we'll achieve a very good level.
If we are able to do something else, we will see in the coming months.
Daniela Costa
Got it, thank you. Then a final one is just in the new capacity additions that you have in medium voltage.
Can you talk a little bit about sort of what's kind of the certainty on the payback on those investments? Do you have all those lines already, some business committed for it, for how long, what's the visibility?
I guess what are the risks to margin of opening new capacity? I imagine you're not running at 100% from day one, does that delay a bit when the margins can get above 15%?
Thank you.
Massimo Battaini
When you read the medium voltage, we need to start learning that you need to read the two segment of business: Power Grid and INC. As said, we preferred in the last two quarters, certainly in the last one, when we were overwhelmed by this huge demand for large project from data center, we were bound to shift medium voltage capacity to data center.
Eight lines will come to fruition in the next eight quarters, one per quarter starting from the end of quarter one '27. We've been pretty fast in approving and executing this expansion.
The approval came in early '25 the first phase, the second phase in '26. In few quarter, two quarters from now, you see this volume mounting.
Most of this volume will serve data center because we see strong demand there totally unsatisfied. We are the first to invest in medium voltage capacity for data center.
Also combined with medium voltage investment in Macomb for INC for data center with the metal-clad, those are special cables, reinforced cable for data center application, the two things goes hand in hand. This would be the additional portfolio and additional capacity available to serve data center.
We don't have written agreement for long term, we have strong demand, a strong commitment. We see this commitment really solid.
The level of prices today even higher than what it is in Power Grid due to the tightness of the market. This level of pricing we expect will continue for a few quarters.
Then for sure there will be some normalization. Of course you cannot expect to have 28% margin in INC business in North America as a normalized margin.
There will be some normalization, but we are the only one which gain the dominant position in data center. We will defend this position, and we will leverage this strength having more assets, having more capacity, having the full portfolio to serve them.
That would be our way to make this margin long-term sustainable, alongside the stronger partnership, Meta, other hyperscalers, that we signed with data center in the telecom space.
Daniela Costa
Got it. Thank you very much.
Massimo Battaini
Thank you.
Operator
We will now move to our next question from the line of Vivek Midha of Citi. Please ask your question, Vivek, your line is open.
Vivek Midha
Thank you very much, everyone, and good morning. My first question is a follow-up from the second quarter, where you've commented there was potential to sign further deals in Digital Solutions in the subsequent quarters given ongoing requests for more capacity from customers.
Could you maybe give us an update on the progress of these discussions? Thank you.
Massimo Battaini
Thank you, Vivek. We are in negotiation, in this case, directly with a couple of hyperscalers for additional volume and commitments, similar deals as the one that we signed with Molex, take-or-pay down payment to secure the margin for long term.
We feel like we will be able to sign and finalize those two major deals by December, January the latest. Those deals will require additional capacity, deployed again in U.S., in fiber and cables.
Vivek Midha
Thank you very much. My second question is just following up on the comments around Power Grid margin and medium voltage.
The margin is only stable sequentially versus your prior commentary there would be an improvement in margins in the second half. Just following on from the prior question, should we think that some of this was because of this diversion of capacity towards data center?
It would just be helpful to understand what the drivers were in the quarter and what's going on going forward. Thank you.
Massimo Battaini
Thank you, Vivek, a very pertinent question. The organic growth is the reflection of the volume shifted to INC, the organic growth was only high single digit because the volume went to other direction, to other segment of business.
EBITDA margin at 13.8% and not 1 percentage point higher or 150 basis points higher, is because we are still in an inflationary situation, and formulas work that we can pass on today to the price the costs that we've seen in the last three months average. When we produce today products, we have the current costs.
If the current costs continue to go up, we continue lagging behind the level of price that we need to have to stabilize the margin at 15%. As soon as this soaring costs curve normalized, we will catch up with the 15% because the drivers of everything is that the market demand and the tension on capacity is there.
There is pricing benefit, there is volume demand from all customer. Power Grid is an essential element of the electrification expansion in Europe, in North America, in all the other regions.
Vivek Midha
Perfect. My final question is just a follow-up on submarine telecom.
You've announced already the €200 million EXA Meridian deal. How many such deals of similar size do you see in the pipeline in submarine telecom which could maybe convert in the next year or so?
Thank you.
Massimo Battaini
There are similar deals. The one we signed is one or two deals that the same customer would like to award to the market.
Now we became visible. We have capabilities that don't just go back to our cable asset that we have in Germany, it goes back to the long history of performance of Xtera in this space.
We combine two champions. We have cable experience, we have installation experience with energy submarine business, Xtera is a champion in repeaters.
The combination of the two make us a strong player. Of course we don't have yet the scale of the three main one, ASN, SubCom, and NEC.
There are room in a market growing fast for us to be in the share of wallet in that market. How far can we go, we will see in few quarters.
There are additional options and projects that we are working on to add a portfolio and backlog to the submarine telecom business.
Vivek Midha
Thank you very much.
Massimo Battaini
You're welcome.
Operator
Thank you. Our next question comes from the line of Uma Samlin of Bank of America.
Please ask your question, your line is open.
Uma Samlin
Hi, good morning, everyone. Thank you very much for taking my question.
I first want to follow up on the additional fiber contract you just mentioned. I guess it seems like you are planning to have two or a couple of additional relatively large fiber contracts.
What are the current capacity ramp-up timeline? Has anything changed, how should we think about in regard to your capacity planning into the end of the decade, especially if you get these two deals done by January next year?
Massimo Battaini
Thank you, Uma. If you take 100%, consider 100% the current capacity, we will almost double it based on the current agreement signed within June '26.
The new deals will add something on top of this doubling of the volume. Additional volume will start kicking in from second half '28 through 2030, we'll have run-rate level of new capacity fully deployed by 2030.
Both the one assigned to the agreement that we signed already, and the one related to the new agreements.
Uma Samlin
That's super clear, thank you very much. Another one on Digital Solutions.
I guess you mentioned, if I heard correctly, 28% to 30% EBITDA margin in the backlog for Digital Solutions. How should we think about that translating into the divisional margins into 2027, 2028?
Also that for the new deals, given fiber prices continue to be very strong, should we expect similar kind of margin profiles there or should we think there could be some potential upside there?
Massimo Battaini
Sensitive question, Uma, the second part. I will love to answer the second part, but here I give you some hints.
The market is tight, you're right. Level of prices today is better than what we had three months ago.
It's likely to be the case that we will be more profitable in the new deals than what we had in the current backlog. Appreciate that this is something that we are still discussing with our customer, and we can't give you more details.
In terms of the EBITDA margin profile, the journey from 25% today to 2030 to 2028, sorry, to 28%, 30% implies additional volume. The additional volume will bring operational leverage, will bring a larger portfolio of business at a very high margin.
You should take a kind of linear line from 25% today to 28%, 30% by 2029, 2029. Maybe next year will be at 26% plus, in '28 could be between 27% and 28%, and certainly meeting the 28% by 2029, 28% margin by 2029 and 2030.
Uma Samlin
That's super clear, thank you so much. My last one is on the U.S.
listing. I guess after Atkore, especially after closing Atkore, the group's exposure is now increasingly weighted towards the U.S.
What are your thinkings there? Is there any sort of timeline you're expecting into next year?
Massimo Battaini
We're not ready to issue any timeline. We continue working on it.
We need to find the right moment, and we see the value, and we will disclose the timeline at the proper moment once ready to go ahead with the official decision.
Uma Samlin
That's all for me, thank you so much.
Massimo Battaini
Thank you, Uma.
Operator
Thank you. We will now take our next question from Akash Gupta of J.P.
Morgan. Please ask your question, your line is open.
Akash Gupta
Yes, hi. Good morning.
I have three questions as well, and I'll ask one at a time. My first one is on guidance.
When we look at the midpoint, 3,100, that would imply 918 for Q4. Then if you take out 30 million from Atkore, then organically we have 888 million, which means 37 million sequential growth.
Now if you look at historically in your business, Q4 has been weaker than Q3. Maybe if you can talk about what is driving this sequential growth in Q4?
Do you see this data center growth being not as cyclical as we have in other part of business? Maybe first one on the guidance.
Massimo Battaini
Thank you, Akash. Your math capability are fantastic.
You are absolutely spot-on. There will be, for the first time I think in our life, a quarter four stronger than quarter three.
Drivers is the usual Transmission, which is normally higher in quarter four than quarter three. What the exception is that while in the past year we've seen seasonality impact in INC space seasonality impact means normalization of demand in November, December, weaker months compared to quarter three we have now a completely unpredictable situation until few months ago, driven and skewed by the data center needs in U.S.
It INC, the one that will support the growth in quarter four, making quarter four, if we continue with this pace, again the best quarter yet.
Akash Gupta
Thank you. Then my second one is on Atkore deal.
I think you closed the deal ahead of what you communicated at the time of announcement. Maybe on the financing side, when you announced the deal, you have said you expect the debt financing to be below 4% with higher cost on hybrid and lower cost on senior debt.
Given since the announcement interest rates in Europe has moved quite a bit, I'm just wondering if there is any update on financing cost that we should assume for Atkore? Maybe another one on Atkore is that you've closed the deal couple of months early, does it change the timeline for synergy realization?
Massimo Battaini
I leave Francesco for the first part of the question, then I take the second, Akash.
Pier Francesco Facchini
I think there is no big change on the financing in terms of timeline. We completed the equity raise in September.
We will go for the hybrid bond component in the coming months. Then, following that, we'll certainly go for senior bonds take-out.
Of course you are right, interest rates are a bit higher, we cannot deny this, but I was reviewing some indications in terms of pricing from the team, I don't think that realistically this will make a big impact for instance on our EPS, just to mention the key metric which will be impacted.
Massimo Battaini
Thank you, Francesco. The second part, yes, we are ahead of the original schedule in terms of closing, and we are moving very fast.
We broke another record here because we've been able to establish and define a new agents base. When I say agents, I don't read people, these are companies representing Atkore and Encore and Prysmian in the market and selling products to the final distributors.
We had already implemented a new organization of agents from day one. The 19th of October was the closing, on the 20th we had the new structure in place.
That means exactly what you are alluding to: we are going to be faster in achieving commercial synergies because the sales force is in place already. They know that they have to sell both cables and components from Atkore.
Some of them have already used to having this capability of selling cables and components. This is what we will leverage to accelerate the commercial synergies.
As far as the operational and procurement synergies concern, we have to do some fixing. Consolidate the cable activity that used to be produced in Atkore into Encore, and also to fix the service level, which is essential to support the business model of Encore.
It is essential to allow Atkore to have access to data center. We need the scale, Atkore has the scale, we need also the service to be a player of Atkore components inside data center.
This is probably the largest and fastest opportunity from a commercial perspective that we have, opening Atkore to this use case, data center. On the commercial side, we set it already.
We had to improve the service and reorganize the supply chain to achieve this as fast as possible.
Akash Gupta
Thank you, Massimo and Francesco. Last one is on potential U.S.
listing. I think this is a topic that always comes on table, and I think there was some comment you made earlier on the press call.
Given you closed Atkore deal and now North America is by far your even larger exposure than before, what's the latest thoughts, and should we expect something in 2027 on this? Thank you.
Massimo Battaini
You're right, the U.S. now represent more than 50% of the results of the company, we have even more than before a strong entitlement to do a list in U.S.
We will continue working on the case, and we will announce as we are ready to move forward with the final actions.
Akash Gupta
Thank you.
Massimo Battaini
Thank you, Akash.
Pier Francesco Facchini
Thank you.
Operator
Thank you. Our next question comes from the line of Alasdair Leslie of Bernstein.
Please go ahead, your line is open.
Alasdair Leslie
Oh, thank you. Good morning.
I had a few questions on the new copper mill at Encore. Firstly, I was wondering whether you could kind of clarify how you're securing the kind of raw material, the additional copper cathode.
Is the majority of that from expanded domestic supply agreements, maybe more recycling of copper scrap, or what does it also rely on some imports too? I guess security of supply is going to become even more of a competitive advantage here.
Is that something that could potentially trigger a kind of framework agreement with a data center customer on the power cable side as well going forward? Then maybe just a simple question: in terms of the incremental extra rod output from this second mill, do you kind of expect to double capacity, triple it, any numbers there?
Thank you.
Massimo Battaini
The rod mill require cathode and waste, scrap. We already have agreements with the number one supplier of cathode in U.S., is a U.S.-based company.
The fact that we have the ability to recycle waste up to 40%, 50% of the metal value is a big plus because we don't depend only on cathode. The market is opening anyway in terms of cathode, it's not that tight, it's loose because there's no import tariffs on cathode.
While there are on rods. That is why the market became tight on rod.
Rod is imported from abroad, but the market as a whole is importing cathode from outside. We signed agreements with this supplier to secure the volume.
On the power side, we don't have agreement in place, we are working on them. We have companies committing in a serious way, we can tell you more about this soon, why?
To buy medium-voltage cable from us, to buy the MC cable from us. Beside the commitment, what matters that there's no alternative.
We are the only one with this scale and the service level and the portfolio breadth. Even if they didn't commit, they cannot find the whole product range at scale with short lead time from anybody else.
That's why we are so much convinced to go ahead with the €700 million additional investment to strengthen our supply chain, product range, vertical integration to serve data center expansion. Not only data center, but the investment will also play a role in the non-residential business space, excluding data center.
Incremental output of the rod mill will be basically 1.2 times the 1.3 times the current output of the existing rod mill. We will add additional volume to Macomb to serve Macomb and support the growth of Macomb, also to replace what we buy rod-wise for our legacy Prysmian plant from other supplier.
Is a make versus buy project, but the main driver behind this is not the saving in itself of the tons produced inside versus the same cost, is the service. Again, with the equipment in-house fully connected to the rest of the value chain, you can serve the market with the best service and, again, amplify the benefit of the additional demand coming from data center.
Alasdair Leslie
Thank you very much. Thank you.
Massimo Battaini
You're welcome.
Operator
Thank you. Our next question comes from the line of Max Yates of Morgan Stanley.
Please ask your question, Max, your line is open.
Max Yates
Thank you. Good morning.
I've got two questions. Just the first one is around the data center exposure within INC.
Could you just give us a feel for how big will that be as a share of revenues in 2026 roughly? How fast has it grown so far year-to-date or maybe year-to-date and in the third quarter would be helpful.
Thank you.
Massimo Battaini
If you take North America INC, data center now represent 25%, 30% of that demand. If you take the global company, this 25%, 30% goes down to 15% more or less in INC space.
Max Yates
Sorry so sorry, just just be clear just to be
Massimo Battaini
clear,
Max Yates
yeah sorry, how far just to be clear, it's so 25% of your North America business in INC or 25% of INC?
Massimo Battaini
25% to 30% of the North American INC is exposed to data center, is revenues coming from data center.
Max Yates
How fast?
Massimo Battaini
How fast did it grow? Let's qualify this 25%, 30%.
You should call it $1 billion, $1.4 billion worth of revenues is a data center business in U.S. In '24, when we acquire Encore Wire, that number was $250 million.
Max Yates
That's helpful.
Massimo Battaini
Thank you. Just
Max Yates
secondly, just thinking through your Digital Solutions business. Your organic growth has been kind of relatively stable this quarter.
I guess my question is, given the kind of prices and renegotiations that you're putting in place, would you expect to see this division accelerate in terms of organic growth as we effectively get that kind of better-priced sales coming through? Should we see the 17% organic growth that we're seeing now is kind of the right level or should we see an acceleration from that level, maybe over the next two to four quarters?
Thank you.
Massimo Battaini
I think two considerations here to be made. When you see the organic growth there, is the organic growth of the entire Digital Solutions division.
The repricing opportunity is applied to the optical space, which equates to one-third of the total Digital Solution business. The rest of the business is connectivity, where the level of price this is really the Channell is really pretty high with a 40% plus EBITDA margin.
The third bucket is made of MMS, multimedia solution cables, data cables, which are pretty stable. This 17% at the group level Digital Solution equates to call it 35%, 40% at the optical level.
It's pretty high when you read it from this perspective. It will continue along the same line until we add additional volume.
The additional volume will not come too far. In second half towards mid '28, second half '28, it would be additional volume kicking in and adding volume growth to the repricing benefit.
Max Yates
Okay. Just very very final one, just thinking through your kind of plans for M&A.
I guess how would you frame where you would need to see leverage get back to before you start thinking about M&A again or do you look at opportunities out there? Would you continue to do deals and utilize equity?
Maybe then when you think about your divisions, what would be the obvious white spots to you where you would be very keen to kind of add an acquisition?
Massimo Battaini
We continue working on M&A. We don't have particular issue in terms of leverage.
Of course it all depends on the size. We are looking at bolt-on, mid-size, and large-size acquisition.
We're not holding back any opportunity because of the leverage or the equity. We have the power to do it.
What matters is to identify and land the right target. The strategic fit, and when I say strategic fit, I mean the possibility to give us the value that we created with the last five acquisitions, namely to make us more robust in terms of right to win in some businesses, enhance the leadership, open us to new trend of growth.
These are the levers, these are the directions, these are the guidance that we apply to the assessment of the market when it comes to M&A in U.S. and outside the U.S.
I really tell you we are really working hard, scouting, working, negotiating, reaching out to companies to pursue our growth and support it with M&A.
Max Yates
Thank you very much.
Massimo Battaini
You're welcome.
Operator
Thank you. We will now take our next question from the line of Chris Leonard of UBS.
Please ask your question, your line is open.
Chris Leonard
Hi there. Hopefully you can hear me.
Please can I go in with two questions as well? Focusing still on the fiber opportunity in Digital Solutions, and following on from your comments now just in terms of optics going up by sort of 35% to 40% on revenue growth in Q3, how should we think about how far through you are in terms of repricing the existing portfolio within the optics, and whether or not we can see further pricing momentum there or it's close to sort of 100% done in terms of your repricing?
Thank you.
Massimo Battaini
Let's say that we are at 75% of the repricing opportunity. In some cases, we cannot reprice because we have a relationship, a strategic partnership that we don't want to hurt, but across the board we reprice everyone.
Some company that we reprice with a significant price increase fully reflected and gone beyond the level of pricing in the market. In some cases, we are holding back this ambition.
Repricing is happening across the board. There's still a 25% where we can go for a second or third or fourth round because the repricing is a dynamic process.
We started repricing as early as March of this year, and the market was at that around $10 fiber price in the market. Then fiber price went up in quarter two, went up in quarter three, we are continuously reaching out to customer and say, listen, the fiber is not available, I need to add additional price.
To a certain extent, we've done what we wanted to do, but there's still a continuous need that we think will remain in place for the next 2 years given this lack of capacity or short or large imbalance between capacity and demand. Is a never-ending process to a certain extent.
Chris Leonard
Thank you. Also the follow-up maybe on the further longer-term fiber contracts you might look to be signing.
As you said, there's a couple in the pipeline here. You're hoping to do by sort of December, maybe into January.
Is there any update you can give from where you were in Q2, where I think you said this pipeline is maybe worth €10 billion and you've secured 5.5? Has that €10 billion now changed relative to the pricing you've seen in the market?
Massimo Battaini
Sorry, the €10 billion of the agreement you're referring to, the one that we signed, yeah, the €10 billion is related to the agreement with Molex and hyperscalers. The new deals will add firm revenues to the €10 billion that I mentioned at the end of quarter two.
Chris Leonard
Sure, and I was just checking. There's been no additional guidance change on that €10 billion.
You don't think there's further upside to the 10 versus where the fiber prices headed to recently?
Massimo Battaini
The €10 billion is firm in terms of pricing and in terms of margin. The €10 billion can grow because there are cost-plus adjustment formula in the existing contract, the €10 billion, as the cost goes up, will go to 10, 11, from 10 to 11 to whatever.
What is relevant is not that because the margin inside the €10 billion or whatever the number will be as a result of the cost-price adjustment is firmed up in our contract. On top of this €10 billion, as we said today, there will be additional billions coming from new deals.
That is what we like to sign the next two, three months. Great.
Chris Leonard
Thanks so much.
Operator
Thank you. We will now take our next question from Monica Bosio of Intesa Sanpaolo.
Please ask your question.
Monica Bosio
Good morning, everyone, and thanks for taking my questions. I will ask one at a time.
The first question is on the Industrial and Construction business. Would it be possible to break up the adjusted EBITDA between NAFTA and the rest of the regions, mostly Europe?
Massimo Battaini
Yes, for sure it's possible, Monica. [laughter] It's very possible.
Monica Bosio
Just rough.
Massimo Battaini
[laughter] You probably should see this 27%, 20 27% in North America coupled with an average of around 10%, 11% in the other regions. Again, the other regions has some different level.
LatAm pretty high with a 13%, 14% EBITDA margin, some European country pretty low, some Nordic country in Europe pretty high. If you want to split between North America and the rest, I would say the 28%, 27% North America and 10%, 12% the rest is a good proxy of these numbers.
Monica Bosio
Perfect, thank you very much. The second is on the investment plan.
Just for housekeeping, can you please quantify the yearly total CapEx for 2026 and, above all, for 2027
Massimo Battaini
for 2027?
Monica Bosio
Thank you. Monica,
Massimo Battaini
I can tell you more about '26. We started with a budget of, let's call it, €850 million more or less, and we're going to beat the €1 billion €1.1 billion this year.
Part is due to the Molex and hyperscalers agreements, part is related to what we discussed before and what we discussed prior quarters. We are expanding capacity mostly in U.S.
to serve the strong demand from customers across the board. '27 beyond, we would like, if you don't mind, we keep this for the Capital Markets Day next year.
The CapEx of '26 have been fully reflected in the guidance. That's why I mentioned before it is a €100 million increase in free cash flow in spite of the metal increase and the significant additional CapEx deployed to support the growth in '27, '28.
For the future, please if you can hold back until quarter two next year when we can give the full picture of the growth, the driver of growth through 2030, the EBITDA, the EBITDA margin, the investment, the free cash flow, and all the other important KPIs.
Monica Bosio
Got it. I will wait.
Just if I may squeeze in a final one. Looking at the capacity increase across Transmission, I've read somewhere that it could be possible to add another vessel, and I was wondering if you can just give us an update of your plan in capacity increase in Transmission.
Thank you.
Massimo Battaini
The plans that we approved will come to full completion by end of '27 with the final implementation of the capacity expansion in Arco Felice, Naples, and in Pikkala, and in Gron, especially in Gron. The other vessel would be a transformation of one of the vessel that we currently use into a more performing vessel in terms of dynamic positioning, standing still when there are stronger weather conditions.
There will be an upgrade, an important upgrade, serious upgrade on an important vessel. The current fleet is fully balanced with the current production capacities so that we can still confirm that all the cable we produce are installed by our assets.
We will further invest in assets for burying cables. The plowing, the jetting, all this machinery, we are launching a new wave of investment to upgrade the capability of this asset because burial, that becomes essential.
Essential in terms of execution speed, in terms of efficiency, in terms of winning new opportunities. This is where we're going to invest the money, not in vessel in itself, but in burial equipment.
Monica Bosio
Perfect. Thank you very much, Massimo.
Massimo Battaini
More about Transmission will be disclosed at the Capital Markets Day for future plans of capacity expansion. Thank you,
Monica Bosio
Monica. Thank you.
Thank you very much.
Operator
Thank you. We will now take our next question from the line of Sean McLoughlin of HSBC.
Please ask your question, your line is open.
Sean McLoughlin
Thank you, good morning. If I can just return to the submarine telecom opportunities.
You mentioned in the press release that you would be considering a new installation vessel. Is this dependent on more awards?
Is this enough also to get you to the €250 million revenue ambition, and what kind of CapEx would we be talking about? That's the first question.
Massimo Battaini
Thank you, Sean. The vessel is an essential part of the turnkey business, and submarine telecom is a turnkey business.
The crucial part of this business are cable and repeaters. For the time being, we are focusing in expanding capacity in repeaters and cables.
The vessel, we'll use a market vessel for the installation of the first project, that is New Jersey-UK project, we can still resort to the market for the installation. The plan is that as we advance our position in this market, second quarter, third quarter next year, we'll make a decision about a vessel owned by us.
It will be not as expensive as a submarine power vessel, it will be in the range of €150 million investment to consider for a telecom submarine cable vessel in this space.
Sean McLoughlin
Fantastic, thank you. The second question on you mentioned hollow-core fiber industrialization.
I was interested to understand where you believe you are in the industrialization path compared to peers, and what kind of timeline to revenues? I think more longer term, I suppose, what is the appetite for this product?
Is this accretive to volumes? Does this help you get hyperscaler lock-in over the long term, and just thinking about long-term margin opportunity on this technology?
Thank you.
Massimo Battaini
We are at the early stage of the commercialization. As said, we will start selling these products.
We've produced in the last few weeks, and we continue producing through December and January. We have customers very keen on having these products both for interconnectors, but also for inside the campus.
The appetite is there. The product is pretty difficult in terms of process, and that's why the industrialization took almost 1 year.
We are now at the stage where we can further expand capacity to make the production at scale for this product. It will become visible late '27 with more volume when we'll have more capacity devoted to the hollow-core fiber.
It is seriously visible in terms of profitability because the level of price is not comparable to that of standard fiber, is tenfold, and even more, no? It's a very visible and appreciated segment of business.
We think we are ahead of the others in terms of readiness to commercialize it. The volume will be becoming more visible from quarter three, quarter four '27 onwards.
Because as I said in the past, this solution serves a one important need: to further spread out data center without losing the power of the signal. This helped data center avoid the famous cooling, water, energy constraints that currently affecting the deployment and the expansion of data center build-out.
Sean McLoughlin
Understood, thank you.
Massimo Battaini
Thank you, Sean.
Operator
Thank you. We will now take our next question from the line of Alessandro Cecchini of Equita for his questions.
Please go ahead.
Alessandro Cecchini
Hello, everybody, and thank you for taking my questions. The first one actually is on the Transmission business.
If you can add some color on your expectation for margins next year, looking at the current corridor that we are running at 20%, just to understand with the additional capacity in 2027 if you expect further improvements in term of margins. This is my first.
My second is just a clarification on the Digital Solution top-line growth expectations. Just to check if I understood correctly that you expect mid-teens organic growth, 15%, 16%, 17%, the current growth rates to continue without, I would say, additional volumes capacity that will come starting from second half 2028?
Just to check this. Thank you.
Massimo Battaini
Thank you, Alessandro. We will answer pretty fast.
The Transmission question, the trajectory is to bring us to 24%, 25% EBITDA margin in 2, 3 years. The 20%, 21% is a level that we already consolidated in '26.
The backlog with high margin will help us enhance this level. The additional vertical integration, HVDC is part of it, will help us also there.
The expansion in submarine telecom, again, is a very accretive addition, the submarine telecom business with Xtera. Our goal is to reach a 24%, 25% by 2030, and having said that, I already disclosed the Capital Markets Day target.
Let me stop here. Digital Solution top-line growth, yes, is 15%, teens digit is the growth that we expect.
In the next 2 years, the price will be the driver of the growth. Beyond the next 2 years, the price will not represent any more the driver of the growth, the driver of growth will become the additional capacity.
You can take this 15% to 20% for the next 5, 6 years, but with a different shift: price in the first 2, 3 years and volume from '29 onwards.
Alessandro Cecchini
Many thanks.
Massimo Battaini
You're welcome, thank you, Alessandro.
Operator
Thank you. We will now take our next question from the line of Nabil Ahmed of Deutsche Bank.
Please go ahead, your line is open.
Nabil Najeeb
Good morning, thanks for taking my questions. I've got three.
I'll just ask them one at a time. The first one's on Digital Solutions, just coming back to the margins for more short term.
I know you kind of touched on this a little bit, but I'm just wondering if you're confirming the margin guidance for Digital Solutions for 2026, which I think was 24% to 25%, because that implies a sequential uptick in margins in Q4, and Q4 is typically somewhat weaker seasonally. I know you said Q4 will defy the typical seasonality, particularly at INC, this time around.
Should we expect the same for Digital Solutions?
Massimo Battaini
You should expect this 24%, 25% 24% full year, even if remember that quarter one was still prior to the pricing benefit and the additional demand benefits, but this is what we expect to see at the end of this year.
Nabil Najeeb
Got it. Just to follow up again on Digital Solutions on the hyperscaler deals that you are currently negotiating, do you think you can give us any indication of roughly how big these deals are going to be, the two deals that you're talking about, maybe relative to the €5.5 billion Molex deal that you signed?
Massimo Battaini
Let's say that the sum of the two can become similar. The sum of the two, there are two major one and a few small ones, the sum of this packet would be pretty close to the size of the Molex in itself.
Nabil Najeeb
Very clear, understood. Then in terms of cash flows, Francesco, I think the new free cash flow guide implies a pretty strong performance in Q4.
Just wondering what the drivers are here. Just wanted to confirm if you got the down payment related to the Molex deal already in Q3 or is that for Q4?
Pier Francesco Facchini
No, it implies what we commented in terms of sequential growth of the EBITDA, first of all. It implies the fact that the metal price impact is still there in Q4, but maybe softer than it hit the Q3 because of the dynamic of the metal price through the quarters.
It implies the fact that we are running very fast on achieving further efficiencies on all the lines of our working capital, and this is well on track. Then, of course, it embeds also some little contribution coming from our new colleagues of Atkore.
Nabil Najeeb
Thanks, Francesco. If I can just squeeze one last one in just on Atkore.
Just wondering if you can give us an update on the stand-alone performance there. I know Encore Wire has reached a record EBITDA margin.
How about the margins at Atkore, do you see an improvement there as well in Q3?
Massimo Battaini
The Atkore margin in Q3 is in line with the full year year-to-date margin at 14%, 14.5%. It is, again, a big room for improvement, especially given the fact that we have now a serious opportunity to expand Atkore presence inside data center given that they have a scale, and what we just had to work on is the bundling with our cables.
The bundling will happen as we speak because the agents are in place already with these capabilities, the service level is the last bit that we have to fix. The potential is very high.
Give us few months to improve the supply chain and make this happen.
Pier Francesco Facchini
Of course, Nabil,
Nabil Najeeb
Molex
Pier Francesco Facchini
Molex is already included in our cash flow in Q3, eh? Got it, thanks.
Thanks for clarifying. I missed the last part of your question.
Apologies for that.
Nabil Najeeb
Thanks for that.
Operator
Thank you. We'll take our next question from the line of Alessandro Tortora of Mediobanca.
Please go ahead, your line is open.
Alessandro Tortora
Yes, hi. Good morning to everybody.
I have three questions, okay, fast questions. The first one, if you can help me a little bit to reconcile the year-end net debt, considering also your comment on the hybrid bond, because as you can get, you're going to issue the bond by year-end, to understand the year-end net debt and leverage.
That's the first question. The second question is on let's say about the terms and conditions for the new potential frame agreements.
Compared to Molex agreement, do you see significant differences or let's say, do you see the possibility, for instance, to improve the terms and conditions of let's say new agreements? That's the second question.
The last one, I recall it in the past that you still have, let's say, huge portion of underground corridor and projects into the Transmission business. Is this a kind of technology where do you see some application in some other countries?
Because after Germany, basically had zero zero project related to that. Thanks.
Pier Francesco Facchini
I take the first part of your question. Ciao, Alessandro, on the debt.
The debt is quite simple, I would say. Let me say that without considering Atkore acquisition, our net debt would be in the region of €2.3 billion.
You should add approximately €1.7 billion debt to that for the impact of the acquisition of Atkore. The assumption here is the same assumption that we have done we presented the deal of Atkore, to have a part of the financing in a hybrid bond in the region of €750 million.
That's an important assumption because the €4 billion, if you add up 2.3 plus 1.7, the €4 billion, which is a realistic estimate of our net debt, is of course IFRS net debt, is excluding the hybrid, which is treated as equity, as according to IFRS.
Alessandro Tortora
Perfect. Then
Massimo Battaini
the terms and conditions, the contract we signed with Molex and the others is what we call a watertight contract, super strong in terms of guarantee and security of the margin in absolute value per volume delivered with commitment supported by take-or-pay. What could change in this contract is that the current level of price is higher than what we had in the market back to quarter one or quarter two this year.
We would like to represent the same T&Cs when it comes to volume, take-or-pay, down payment, buying component, all the rest. We hope we'll be able to have a better price, which is likely to happen.
In underground high voltage, Germany is the first country where the HVDC 525 has been deployed, and we are in the advance installation phase for the famous German corridor. 525 technology is the standard now in the market, no?
We are not selling any longer the 320 kV for all interconnectors, be they submarine or land. This is the prevailing technology.
It's not just the 525 kV, as we innovated here with a 20% power upgrade on the 525 standard technology so that now we can transmit with our solution from the 2 GW power, typical of a standard 525, up to 2.4 GW power. This will be giving us a competitive edge over the others.
More power means that you pay less per megawatt transmitted, which is an important KPI for TSO client. Grazie.
Thank you, Alessandro.
Operator
Ciao, Alessandro. As a reminder, before we move to our next question, please press *11 on your telephone keypad if you wish to ask a question.
We will now take our next question from the line of Jean-François Granjon of ODDO BHF. Please ask your question, your line is open.
Jean-François Granjon
Yes, good morning, thank you to taking my question. I have three questions, please.
I just want to come back on what mentioned for the data center, I don't well understand what you mentioned, the amount of the data center you made currently and the percentage of the sales for the group. The second question concerned the new investment expected, you mentioned that more than €700 million for the medium-voltage business, when to expect this new investment should be operational for the company?
The last question, I would like to the INC excellent performance for the Q3. We saw a very surprising gross margin, I would say, more than 300 basis points compared to last year and 400 basis points sequentially compared to the Q2 2026.
I just wondering, can we come back to explain why it's so huge improvement for the margin, and do you expect this margin is sustainable for Q4 and for sure for 2027? Thank you.
Massimo Battaini
Thank you, Jean. I'll give you a comprehensive answer on the data center.
When I answered before, the question was the size of data center revenues inside INC. Now give the size of data center revenues out of the total revenues that we make at the group level.
We do sell to data center across the business: Transmission, Power Grid, Electrification, Digital. We can say that 2.
2.5 billion today in '26 is the level of revenues through data center across all the segment of business. Let's call it 10% plus, 12% of the company revenues is in the data center space.
This €2.5 billion were, I said it before, less than €200 million 2 years ago. Significant growth, significant uptake.
The medium-voltage CapEx that we presented, €700 million, will become operational in different moments. The rod mill will be fully in place by the end of '28, January '29 namely.
The medium-voltage capacity will come in one line per quarter from quarter one '27 onwards, and there will be eight lines added to our capacity. Over the next 2 years, you will see those eight lines coming live.
The metal-clad, the specific investment for Macomb products for data center, will become available from the end of '20 second half of '28 onwards. Again, all those investments are to ensure when we combine those investment with the relevant investment in Digital Solutions space, we ensure that we follow and support data center expansion throughout the whole value chain: power and optical business.
Be back to the quarter three excellent performance, it is certainly driven by INC North America with the upgrade of EBITDA margin in U.S. from a standard to this historical 20% to 27%.
It's also supported by the expansion of margin in Digital Solutions. It's the first quarter, quarter three, in Digital where you see more depth in execution of the repricing on the customer base.
This we expect to remain sustainable in quarter four and to continue next year as long as this demand from data center that we see growing week after week continue to remain strong in the market.
Jean-François Granjon
Thank you so much, very clear. Thank you.
Massimo Battaini
Thank you, Jean.
Operator
Thank you. There are no further questions.
I will now turn the conference back to the room for closing comments.
Massimo Battaini
Thank you, all. Thank you for your time today.
I hope we've been able to explain how successful the last 3 years has been and this quarter three outstanding record result speak for itself. We continue supporting the growth in the future with M&A, organic growth, and we'll give you more visibility of those ambitions at the next Capital Markets Day.
Thank you, you all for your time. Thank you.
Thank you.
Pier Francesco Facchini
Thank you.
Operator
Thank you for your participation in today's conference. This does conclude the program.
You may now disconnect your lines.