Pagaya Technologies Ltd.
Q3 FY2026 · Earnings Call TranscriptOctober 29, 2026
Operator
Greetings, and welcome to the Pagaya third quarter 2026 earnings call. At this time, all participants are in a listen-only mode.
A brief question-and-answer session will follow the formal presentation. Should anyone require operator assistance during the conference, please press *0 on your telephone keypad.
As a reminder, this conference is being recorded. It is now my pleasure to introduce your host, Craig Smyth, Investor Relations.
Thank you. You may begin.
Craig Smyth
Thank you, and welcome to Pagaya's third quarter 2026 earnings conference call. Joining me today to talk about our business and results are Gal Krubiner, Chief Executive Officer of Pagaya; Sanjiv Das, President; and Jon Dobres, Chief Financial Officer.
You can find the materials that accompany our prepared remarks and a replay of today's webcast on the Investor Relations section of our website at investor.pagaya.com. Our remarks today will include forward-looking statements that are based on our current expectations and forecasts with respect to, among other things, our operations and financial performance, including our financial outlook for the fourth quarter and full year 2026.
Our actual results may differ materially from those contemplated by these forward-looking statements. Factors that could cause these results to differ materially from our expectations include, but are not limited to, those risks described in today's press release and our filings with the US Securities and Exchange Commission.
We undertake no obligation to update any forward-looking statements as a result of new information or future events. Please refer to the documents we file from time to time with the SEC, including our 10-Ks, 10-Qs, and other reports, for more detailed discussion on these factors.
Additionally, non-GAAP financial measures, including adjusted EBITDA, adjusted EBITDA margin, adjusted net income, fee revenue less production costs, or FRLPC, FRLPC as a percentage of network volume, core operating expenses, and core operating expenses as a percentage of FRLPC, will be discussed on the call and included in the accompanying materials. We also provide an outlook for the fourth quarter and full year 2026 on a non-GAAP basis.
Reconciliations to the most directly comparable GAAP financial measures are available, to the extent available without unreasonable efforts, in our earnings release and other materials, which are posted on our Investor Relations website. We encourage you to review the shareholder letter, which was furnished to the SEC on Form 8-K today, for detailed commentary on our business and performance, in conjunction with the accompanying earnings supplement and press release.
With that, let me turn the call over to Gal.
Gal Krubiner
Thank you, everyone, for joining us today. We had another outstanding quarter.
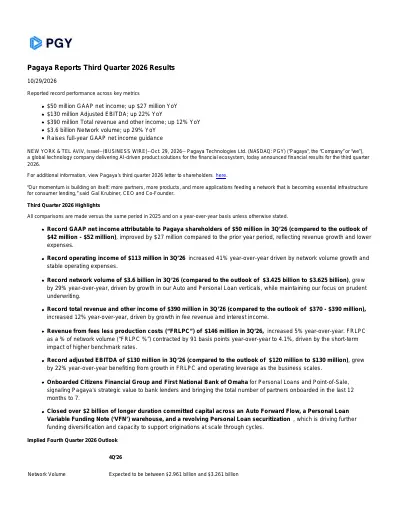
We delivered record GAAP net income of $50 million. We grew network volume by 29%.
We held costs flat, driving nearly 100% to the bottom line. Today, I want to discuss the key drivers of the quarter, and then to discuss the progress we have made on our partner-and-product strategy that led us to become a profitable company in 2025, puts Pagaya on a path to generate $172 million of GAAP net income in 2026, and sets us up for a record year in 2027.
Higher rates increase our cost of capital in Q3, and therefore reduce our FRLPC margin, driving us to a lower end of our 4% to 5% range. We have taken action by raising APRs in September and October, and this will result in a higher FRLPC percentage as we close out Q4 and enter into 2027.
On credit, our performance is strong and in line with expectation in both auto and personal loans. We have been laser-focused on credit performance through market cycles, as reflected in the profile of the borrowers we underwrite, and that continues to pay off.
Funding availability is very robust. In fact, it is stronger than ever.
We raised $3 billion in ABS this quarter to support our network production, and we are using that availability to strengthen our long-term funding stability. We also executed on the funding diversity we discussed last quarter, with a focus on long-term committed capital.
More of our funding now come through revolving structures that can be drawn, repaid, and reused. That capacity carry forward, it does not have to be rebuilt every quarter, and it gives us more stability across market environments.
Now to what excite me most: 2027 and the long-term vision behind it. Pagaya is really becoming an important part of the infrastructure for lenders.
To gain and retain valuable deposit customers, banks need to meet product demand. Multiyear lead time for product development or conflicting balance sheet strategies is no longer an excuse to forego that path to deposit growth.
We are that solution. We are this partner that gives banks the product, the decisioning, and the capital network to move faster.
This is precisely the demand that is reflecting in our pipeline. Citizens and FNBO are the latest proof points of this momentum.
These two banks joined the network this quarter, bringing our new partners count to six this year. Their integration is a signal that we are becoming a utility for financial institutions.
More partners and more product bring more applications. More applications data widens our moat and improve decisioning.
Better results deepen those relationships and bring more volume back into the network. With the operational expenses held flat, that growth increasingly reaches the bottom line.
We enter the fourth quarter with the largest partner pipeline in Pagaya's history, and we are still in the early innings of enabling lending outside of the bank balance sheets. Consumer credit in the US represent nearly $1 trillion in annual originations, compare with our current annualized volume of about $14 billion.
We have substantial room to grow. Banks can count on our infrastructure through every part of the cycle, and that infrastructure only gets stronger as we grow and scale.
Thank you to our team for executing this quarter. The result definitely belongs to them.
Sanjiv Das
Thanks, Gal. We delivered another quarter of disciplined execution.
We stayed focused on our three growth pillars: signing new partners, expanding flow from existing ones, and deepening product adoption across the network. By staying focused on these fundamentals, we drove 29% network volume growth year-over-year and reached our highest profit ever.
We also kept our credit posture strong, with application to conversion holding steady at approximately 1%. This is the network growth strategy we've been talking about, and it is now compounding as a repeatable playbook rather than a series of one-off wins.
I want to start by talking about our bank and partner adoption. This quarter, we are pleased to welcome two new bank partners: Citizens Financial Group for personal loans, and FNBO for home improvement point-of-sale financing.
That brings us to six new partner onboardings over the past three quarters, well above our annual target of two to four. Our pipeline remains strong, and we expect to announce more significant partnerships in the coming quarters.
Offering personal loans and other credit products helps banks deepen customer relationships. It improves deposit retention and drives adoption of additional products, which supports higher customer lifetime value.
This matters even more when banks face capital constraints on growing their lending programs. That is the main reason banks are leaning into our network at record levels, particularly in personal loans and auto.
It's driving the strongest bank pipeline in Pagaya's history. Importantly, we are also deepening product adoption among current partners.
Our flagship personal loans business keeps delivering strong, stable performance. We use a selective multi-product approach to capture stronger applications higher up the funnel.
The affiliate optimizer engine remains a key growth driver. We onboarded two new partners into Experian and Credit Karma this quarter.
We also keep equipping partners with tools and insights to perform better in these channels. On average, partners that launch on Pagaya's affiliate optimizer see a 60% increase in issued volume compared to the prior year.
With demand strong and more partners in the pipeline, we expect further launches in the coming quarters. Our direct marketing engine continues to perform exceptionally well.
To date, we have executed approximately 70 campaigns, and we remain on track to achieve our half a billion annualized volume goal by the end of the year. These campaigns have enabled partners to add more than 20,000 customers to their ecosystems.
This demonstrates our ability to advance further up the application funnel while supporting partners in acquiring and cross-selling customers. Now turning to auto.
Last quarter, we introduced Pagaya's auto flywheel. By continuously improving our auto product and features, we enhance the dealer experience with our lending partners.
Higher dealer engagement drives more application volume and expands Pagaya's flow. That volume fuels further product innovation and reinforces our data moat.
This self-sustaining loop drives steady, disciplined growth. We saw a 40% increase in top-of-funnel application volume year-over-year.
As our partners become dealers' first choice, our application mix and origination profile keep getting stronger. In auto, we are strengthening our counteroffer and dual-look products.
They help lenders convert more dealer applications into approvals. Our internal analysis shows these products help partners meet customers' full requested amount 70% of the time.
They expand approval opportunities and deliver tailored offers, our lending partners compete better and generate higher loan volume. As a result, Pagaya's issuance mix is evolving, with a growing share of applications coming from higher up the funnel.
Additionally, we are in the process of building a real-time optimization product that allows dealers to simulate loan terms without resubmitting applications. Our data shows that deals with multiple submissions convert at a significantly higher rate compared to single submissions.
Next on point-of-sale. Sezzle and FlexPay continue to scale nicely.
We remain committed to building out and scaling our point-of-sale business, including cross-selling to existing partners. We also see significant upside in using our core personal loan funding capabilities to fund larger, longer-term purpose-driven loans.
Finally, I want to touch on our funding this quarter. Our funding engine remains exceptionally strong.
That strength has become a competitive advantage, and it's attracting new bank partners. This quarter, we closed three deals that together add more than $2 billion of committed capital over the next 24 months.
We announced a $700 million auto forward flow with Neuberger Berman, our second such partnership. In personal loans, we launched our inaugural variable funding note, establishing $700 million in additional funding capacity.
We also closed our second revolving personal loan securitization, supporting $850 million of production over its life, which demonstrates demand from insurance capital for bespoke solutions. Within ABS, we raised $3 billion this quarter.
That was anchored by our largest ever auto ABS transaction, which was upsized as new investors joined our auto shelf. These funding sources provide both diversification and the capacity to support originations at scale through cycles.
I want to take a step back and look at what's ahead. Regardless of market cycles, our strategy remains focused on core fundamentals: onboarding high-quality new partners, and deepening relationships with existing ones with expanded product offerings.
We are doing this intentionally to diversify our partner base, secure our funding capacity, and maintain credit with strict discipline. We believe a short-term dip in volume growth is an acceptable trade-off to maintain our unit economics, as expanding the network provides far greater long-term value for the business and its shareholders.
Jon Dobres
Thank you, Sanjiv. This quarter delivered record net income of nearly $50 million, driven by the mission-critical nature of our infrastructure.
Before I walk through our successful quarter and outlook, let me talk about the impact from higher rates. As Gal mentioned earlier, rates increased in September, which we reacted to in regular course.
Let me explain. In the short term, higher rates lower FRLPC as a percentage of volume.
Q3 came in at 4.1%, the low end of our 4% to 5% target range. To bring us back to the midpoint, in September and October, we staged APR increases across our asset classes: 100 basis points in personal loans and 140 in auto.
By the end of Q4, we expect to trend upward, and in 2027, move toward the middle of the 4% to 5% range. Now to the quarter and strong outlook.
On the funding side, investor demand is very strong. We executed $1.8 billion of personal loan securitization and $1.2 billion of auto securitizations in Q3, and increased our investor network to over 180 unique investors.
Spreads are consistent with or have improved from earlier in the year. For example, spreads tightened more than 20 basis points on our most recent personal loan transaction.
Tighter spreads and more investors are the clearest signal of investor confidence in the network's credit performance and investor demand. Outside of our core ABS franchise, our long-term diversified committed capital strategy is delivering.
Forward flow, long-term revolving structures, and warehouses discussed last quarter have all come to fruition, and the pipeline for non-pre-funded ABS partnerships remains strong in Q4. Now the results.
Network volume grew 29% year-over-year to $3.6 billion, led by personal loans and auto. Application volume rose 42% year-over-year to $377 billion.
This follows Q2, which you'll remember was our first quarter over $300 billion in applications. Application growth is our leading indicator for future volume from new partners and products, $377 billion tells us our bank-led partner strategy is working.
Conversion remains around 1%. It came down slightly as we prudently onboard new partner- and product-driven volume.
As we prove out the quality of the new partner and product flow, conversion and volume follow. Revenue and other income grew 12% year-over-year to $390 million.
Collectively, FRLPC and other income, which is predominantly interest income, grew 17% year-over-year to $175 million, or 4.8% of network volume. The vast majority of this is received as cash when earned in the quarter.
Fee revenue grew 7% to $362 million, driven by volume and partly offset by the lower FRLPC rate. Interest and investment income more than doubled as our cash-yielding bond portfolio grew.
FRLPC grew 5% to $146 million. As a percentage of network volume, it was 4.1%, down 91 basis points year-over-year, reflecting the elevated 2-year Treasury.
As we pass along these costs, FRLPC as a percentage of volume will move upward toward the midpoint of our 4% to 5% range in 2027. Adjusted EBITDA rose 22%, or $23 million, to $130 million, a 33% margin, up 3 points.
Core operating expenses were $45 million, $2 million lower than a year ago, and 31% of FRLPC, down 3 percentage points. Operating income was $113 million, up 41%.
Finally, GAAP net income was $50 million, up 121% from Q3 2025, a 13% net income margin versus 6% a year ago. Let me double-click on one element of what I just spoke about.
Core operating expenses have been essentially flat for seven straight quarters. That's what lets incremental FRLPC and interest income flow through to the bottom line at such a high rate.
Our fixed cost base doesn't move with volume. Credit is in line with expectations across all verticals.
As 2025 vintages season for PL and auto, our most recent KBRA surveillance reports upgraded 63 tranches with zero downgrades. This gives us additional confidence in our future level of impairments, and that impairments will continue to come down as a percentage of production.
Now the balance sheet. We've continued to improve the quality and mix of our investment assets.
As of September 30th, we had $306 million in cash and cash equivalents, and $1.1 billion in loans and securities, with bonds making up 49% of the portfolio. The majority of the interest recognized from our investments in loans and securities is cash.
The fair value of the certificate portion was adjusted down $43 million in the quarter. Our balance sheet has become a strategic driver of value for Pagaya and a key strength as we are able to borrow on our bond portfolio at our choosing to lower our cost of capital on a non-recourse basis.
These secured borrowings are increasingly bank-led and priced very attractively. For example, our most recent agreement with a major bank funds at about a 6.5% cost of capital, supporting bonds that yield about 11% to Pagaya on an unlevered basis.
Overall, cost of secured borrowings is currently about 8.5%, versus about 11.5% in mid-2025. We expect this aggregate rate to continue to decline.
A further indicator of balance sheet strength is our shareholders' equity, which has increased by about 50% since the close of 2024. Finally, on to guidance.
We're raising net income guidance for the third time this year. Even in a higher-rate environment, application volume and investor demand remain extremely strong, which lets us exit the year with a projected 112% increase in net income.
Q4 volume will be seasonally lower than Q3. Excluding Klarna, Q3 volumes were $3.3 billion.
Q4 reflects the first full quarter without Klarna, plus Q4 seasonality. To be clear, Klarna contributed volume, but was not material to FRLPC or profit.
Ex-Klarna, the Q4 2026 seasonal decline is expected to be milder than what we saw in 2025: about 5% to 6% versus 9% in 2025. FRLPC as a percentage of volume is expected near the lower end of the 4% to 5% range.
It begins to rise toward the end of Q4 and continues into 2027, when we expect to get closer to the middle of the range. For full year 2026, we expect network volume of $12.725 to $13.025 billion, total revenue and other income of $1.45 to $1.5 billion, adjusted EBITDA of $465 to $485 million, and GAAP net income of $162 to $182 million.
With that, let me turn it over to the operator for Q&A.
Operator
Thank you. We will now be conducting a question-and-answer session.
If you would like to ask a question, please press *1 on your telephone keypad. A confirmation tone will indicate your line is in the question queue.
You may press *2 if you would like to remove your question from the queue. For participants using speaker equipment, it may be necessary to pick up your handset before pressing the star keys.
One moment, please, while we poll for questions. The first question is from John Hecht from Jefferies.
Please go ahead.
John Hecht
Morning, guys. Good results, congrats, and thanks for taking my questions.
First question is, two two new bank announcements, that's a pretty good development. Maybe you could tell us what drove those I guess negotiations across the line, and how the pipeline is generally related to that?
Gal Krubiner
Hi, John. It's Gal here.
Thank you for the question. Definitely, by far the thing that I and the team are most excited about, we definitely see a shift in the way banks are thinking about the Pagaya offering.
Let me start with Citizens and FNBO, we'll move a little bit to the main driver that we see in the market, and we'll close by a few remarks on the pipeline. From Citizens' perspective, I think the best way to think about it is when they looked into opening the personal loan business again that they had in the past, their best way or easiest way to do it was really to partner with Pagaya.
We can take a project that could take for a bank something like two to three years, and with our technology capabilities and with the capital market capabilities, really to bring it up to life in six to nine months. For a bank like Citizens that has mainly motivation is to provide solutions and products to their depositary base, that's the easiest, most straightforward way to do that.
The reason why Citizens and FNBO are so exciting for us, because we definitely feel this is marking the full shift of the understanding of the banks on the value proposition that we are providing, and making it something like more a category leader. Things that we spoke in the past on the theory level are now coming and becoming the real way to do business.
The same goes for FNBO, when they are actually doing the same for the point of sale on home improvement. They were looking for a partner to help them approve more, extend more, provide more value to their customers, and we were the selected partner.
We're very fortunate and in appreciative, both the managements of FNBO and Citizens. On the things behind and what's pushing these partners to come, you can think about the two major motivations as the first one is to maintain and increase the consumer's deposits.
The personal loan is really a product that is attached to deposits needs, and a lot of the situation where customers that have a big deposits are looking for personal loan, and the bank can't provide it, they will end up looking for the same thing in a fintech, and more likely than not, will be in a situation where they are moving part of their deposits elsewhere. Their ability to have the same solutions, the same capabilities inside the bank is really something that we are helping them provide, and think about it as the way to protect their deposits from fleeing away out of them.
The other side of the coin is really about growth. The bank is actually starting to realize that they need to grow, and they could do that through increasing their fee income that is not really correlated to the bank balance sheet.
When we are working with them and sharing with them a little bit of the upside that is being generated from the fees that the banks are being producing through these loans, but they don't need to attach any balance sheet to that, that's really materially increasing the return on the equity and showcasing the growth that they should and can now propose, but not through a heavy lifting of bank balance sheet or any tech big investments. All of that to say that we are really seeing the market moving to us, and we are expecting even more significant surge in the engagement from bank lenders.
We are actually today speaking with many more of the lenders, and even more than that, we are speaking with the bigger players than we expect before. That's what we feel about the motivation and discussion.
All of that is bringing us really to a super strong pipeline, as I mentioned, driven by big banks, not by medium or small banks, some of them are even megabanks. When we think about the pipeline number, it definitely grew over 50% year-over-year, making and marking the significant change in the understanding of the banks on the value proposition.
John Hecht
That's great context, thank you. Then second question is just the Q4 volume guide, maybe talk about what you're thinking in terms of approval rates and the mix, just to give us a little bit of more details on that.
It still shows good momentum, but also ongoing selectiveness.
Jon Dobres
When you think about Q4 volume, the mix will be pretty similar to what we've seen throughout the year. PL remains our largest asset class, but auto is growing faster.
You'll kind of continue to see that trend. As I mentioned in my remarks, Q4 is the first quarter where Klarna is fully out of the network.
Again, that reduces volume, it was about 300 or so, 330 million of volume last quarter. However, has really no effect on FRLPC, EBITDA, or anything below.
That's how you should think of it, sort of a continuation of the volume trend for the year, sort of ex-Klarna in the quarter.
John Hecht
Perfect. Thank you very much.
Operator
The next question is from Sanjay Sakhrani from KBW. Please go ahead.
Sanjay Sakhrani
Thank you. Good morning, and congrats on all the progress that's being made.
I guess, Gal, you mentioned how the mix of your originations or the potential is moving towards larger banks. I guess, what changes as that happens as we think about the mix of types of loans and the economic potential of those loans?
Gal Krubiner
Hi, Sanjay. Thanks for the question, definitely.
Just let me clarify, I spoke that the Q4 onboarding are moving into a bigger banks, etc. I think the big way to think about the change is actually the quality of the borrower that we are actually originating.
If you take a look on, for example, the personal loan and the actual income of what it used to be a year ago was much lower, and now we're talking about $120,000 for application. You can imagine that these borrowers are living much more in the big banks, and our ability to access them through the big banks is actual very meaningfully different.
If you will see on the shareholder letter, we actually spoke on the same thing, but just for the auto, and you will see that when we speak about the income, borrower income of the production that we have on the auto portfolio this quarter versus 2022, you're talking about average income of $88,000 versus 62. It's a 41% increase.
You talk about vehicle mileage that went down from 65,000 miles to a 24, which is a reduction of a 63%. That's definitely part of our strategy to increase the capability and to increase our ability to originate better and better collateral, and that is coming from being able to penetrate into a bigger, more robust, more well-known banks that, quite frankly, many of them do not have the PL offering, or even if they have the PL offering, they have it in a much more limited scale.
Therefore, our solution to them is much more full spectrum to the upwards and to the better borrowers, and that tie out to our long-term strategy of improving the collateral outcome.
Sanjay Sakhrani
Okay. I guess, as we think, obviously, significant operating leverage potential and what you guys demonstrated this quarter and what's expected for the remainder of the year, as we look ahead, should we expect this type of profile to persist, or are there investments that you might need to make as you move in to these different partnerships that you might have?
Thanks.
Sanjiv Das
Sanjay, this is Sanjiv. I'll take this.
I think, if you really think about what's happened in the last six last four quarters, we have onboarded seven new accounts, which is significant in terms of the scale of onboardings, with absolutely zero increase in our onboarding cost and zero increase in our ramp-up cost. In fact, we've shortened the operating onboarding time, and we've rapidly increased the ramp-up time.
All this has happened without any increase in operating expense. The short answer to your question on do we expect anything to happen in the next few quarters with the continued momentum, the short answer, in my opinion, is absolutely don't expect it to happen, because it's highly scalable.
That's what we've been talking about for quite some time. Continue to expect significant operating leverage with continued momentum in the rate of partner onboarding.
One other thing I'd just like to add is that in addition to the rate of partner onboarding is, if you notice what Gal mentioned, was not just the rate of network volume growth, but the change in the quality of network volume growth. We are shifting that also significantly as we move top of the funnel.
The growth is coming from both the growth in the new partners as well as the growth in volume from existing partners, neither of which requires additional operating expense.
Sanjay Sakhrani
Thank you very much.
Operator
The next question is from Moshe Orenbuch from TD Cowen. Please go ahead.
Moshe Orenbuch
Great. Thanks.
You guys talked about the tighter spreads in the more recent deals that you've done. It's particularly interesting given that I think investors had been concerned, in addition to the increase in base rates, that spreads broadly in the industry had widened towards the end of Q3.
Maybe, could you put that into context a little bit? Is it just kind of more consistent recent performance?
How does that kind of translate into your outlook for Q4 and beyond? Thanks.
Jon Dobres
Thanks for the question, and it's really something that has been tremendously exciting for us this quarter. Credit is performing very well within our expectations.
If you look at KBRA's last surveillance report, for example, we had 63 upgrades and zero downgrades in terms of our securitizations. Indicators, obviously, what we see internally and also externally, are very positive around credit.
When you take a step back, though, let's think about funding more holistically. We've set a strategy to have a long-term, diverse, committed capital base.
When you looked at us a year ago, about 75% of our funding was from pre-funded ABS. Now it's more like 50/50 in terms of other channels.
The ABS is performing very well, which we see from the spreads, we see from increase in our investor base from about 170 to over 180, a lot of indications around there which are very, very solid. What excites us even more are the wins we've had this quarter on the non-traditional ABS initiatives.
We set out last quarter on the earnings call, and we said we were going to execute a new revolving structure, forward flow, and VFN off-balance sheet warehouse. We achieved all of that this quarter, as Sanjiv talked about in his remarks.
We see a really diverse array of investor interest. It's on the securitization side, it's on the non-traditional securitization side, and we have a pipeline of additional interest.
You'll see another warehouse from us this quarter, for example, that will be bank-led, that will continue to drive down spreads and really make our cost of capital increasingly attractive and diversified.
Gal Krubiner
One more sentence to add, Moshe. As we think about 2027 and why we are excited and actually bullish about the year and bullish about Q4, etc., is that we see these two trends, right?
On the one hand side, we have a very strong adoption from the banks, so that side of the business is doing and doing well, and as Sanjiv mentioned, quicker and faster and more pronounced. Then on the other side, we have what we call the maturing of our funding channels and capabilities.
Part of the spread tightening is us moving flow to other channels, being able to bring more banks, more balance sheet, more insurance capital. All of that together is what you should think about the full Pagaya flywheel, which is lower cost of capital is driving more ability to compete and to convert into the partner side.
The partner side seeing more value into that and therefore more profit are being translated to us. We have the guidance of continue to increase the FRLPC, continue to drive more economics to Pagaya, and all of that is coming from the two sides: reducing the cost of capital and increasing the access to borrowers.
Moshe Orenbuch
Right. It seems like investors, with the comments we've gotten, seem to have focused a little bit on the FRLPC in this quarter.
I guess, is it you guys have already done the things from a pricing standpoint that are needed to get that towards your 4.5% target, right? There's nothing else that you would have to do in order to get there.
Is that a fair observation?
Jon Dobres
I think that's definitely the right way to think about it.
Moshe Orenbuch
Great. Thanks very much.
Operator
The next question is from Kyle Joseph from Stephens. Please go ahead.
Kyle Joseph
Hey, good morning, guys. Thanks for taking my questions.
Probably just add one on to what Moshe had. On FRLPC, like Moshe said, you've guys kind of laid out strategies to get it back towards the mid-4 range right in your zone.
Obviously, in '25, we got a little bit call it spoiled when it was towards that elevated level, closer to 5. Is that really just a function of just adding more new partners in '26 and a little bit of that's the cost of business, but over time, even those new partnerships will ramp back towards that kind of level we saw in '25?
Is that how we should be thinking about things in terms of both the impacts of rates and new partnerships on FRLPC?
Jon Dobres
Right. When you look at the two components, I think you're thinking about it correctly.
On the rate side, we've moved these APR increases through, and as we get into 2027, you'll begin to see kind of the restoration higher up in the 4% to 5% range from that. On new partners and products, we had an unbelievable year of onboarding, right?
That does have a lowering effect on the FRLPC rate early on, but as those partners and products mature, the combination of those products and partners maturing and the moves we took on rates will begin to push the aggregate rate forward. Just as a single point, all partners, over time, get to a similar FRLPC rate.
It's just as we onboard them, it's lower at first. Your earlier comment on a mature partner getting to the same rate is exactly right.
Sanjiv Das
Kyle, I'll just add, this is Sanjiv. I'll just add from the market perspective in terms of how we responded to the increase in rates, there are two things that you should consider.
One is, do we have the ability to transmit this in terms of the speed of transmission from an increase in our cost of funds to the consumer? The short answer is yes, and we did that.
That's point number one. Point number two is, when you did the increase in rates, did you guys see a drop in activation which impacted your volumes?
We watched this now over the last three weeks, and we have seen that our activation rates have stayed pretty much constant. The reason for that is because in this segment, we have pricing power, and consumers feel that the need for credit at a responsible rate, because if you take it too far up, it has its own consequences, but we find that it's been pretty steady.
From a market perspective, we have been able to not only transmit the rates, but also hold our activation rates relatively stable.
Kyle Joseph
Really helpful. Thanks, guys.
Then just a quick follow-up for me, talking about the reacceleration in network volume growth. Obviously, we know you've added a great deal of new partners this year, which is obviously a good thing.
Can you just kind of balance that out with what you're seeing in terms of penetration at existing partners and new products as well, and give us a sense for the balance of growth we've seen this year?
Sanjiv Das
As I mentioned to Sanjay before, we have definitely seen that the rate of network growth has been very, very strong. As I said earlier, the rate of network growth has pretty much offset the volume fluctuations because of the rates.
Number two, the rate of top-line growth because of our ability to scale with our existing partners has far exceeded the expense growth, and which has mostly been flat. Both the network as well as existing partner growth has been very, very strong and continues to be strong.
We've taken partners that used to operate at about 250 million a year at roughly $1 billion of volume production in our PL business as well as in our auto business, we have seen existing partners that have grown very, very substantially in the last 18 months as we continue to ramp up our potential with them, and pretty much replicate what we've done with one with the other partners. As I said, the most important thing, I know we focus on volume a lot, but I think it's important to also focus on quality of volume.
We have started moving very much top of the funnel, and are very much changing the quality of the mix of the consumers that we are getting now. As Gal mentioned, personal loans at a average income of $120,000, and FICO scores that are very close to 680 to 700-ish.
Quality of flow is also extremely important, and we continue to see that happen, and we expect that to happen as we move along.
Kyle Joseph
Great. Thanks for taking my questions.
Operator
The next question is from Peter Christiansen from Citi. Please go ahead.
Peter Christiansen
Good morning. Thanks for the question.
Nice execution, guys. Two questions here.
John, it was helpful to talk about how application growth versus the conversion rate on onboarding new bank partners, how that kind of goes through the paces. Can you just elaborate on that, and how we should think about when does conversion, I guess, eventually normalize when you're onboarding a new partner, like some of the banks that you have this quarter?
Jon Dobres
We see sort of normalization over kind of a 12-month period. You should think of it as sort of prudently onboarding, right?
We obviously, before we actually activate a new partner, are doing a ton of work modeling out exactly what we think the flow will look like, what the performance will look like, etc. However, you need to actually start funding loans to see this performance.
In the short term, we intentionally slowly ramp up, we can make any necessary tweaks or anything else to ensure that the credit performance from new partners will be good. That's why you'll see application growth before you see volume growth, right?
Because a lot of that is being evaluated, and over that sort of 12-ish-month period, we're then ramping that into steady-state volume.
Peter Christiansen
That's helpful. Then, I do want to chat about the pipeline here, which sounds really exciting.
You highlighted pipelines over 50% larger year-over-year, largest. Just trying to help size that opportunity, is the average expected volume contribution from the current pipelines materially larger than some of the cohorts that you signed in '24 or '25, or should we think of growth as primarily being driven by a higher count of opportunities?
Sanjiv Das
This is Sanjiv, Pete. Let me take a shot at it, and Gal, John, feel free to chime in.
A couple of things. One is, it's absolutely right, the pipeline is, in fact, 50% up, and the change in the pipeline towards banks is a material qualitative difference from 18 months ago.
The fact that we have now, as Gal mentioned earlier, both major money center banks as well as regional banks, after we proved that the model works with US Bank and Barclays Bank, which acquired Best Egg, we proved that we were regularly completely robust, and we proved the ability to grow fee income, that has demonstrably moved the pipeline towards banks. What do I expect as a result of banks coming in?
Because banks are significantly larger, and because banks have started thinking about personal loans through Pagaya as a mechanism to both defend their deposits as well as grow their fee income, the ability to materially grow is substantially larger in the big banks, as you would expect. I think that value proposition is very strong and makes us very bullish about the prospects of what we are doing in '27, '28.
Gal Krubiner
The only thing I will add, Pete, I think that's one of the things that it's a little missing because it's hard to see, takes some time. We are really becoming and shaping to be a company that is working with major players, big banks, and then you can think about it that we kind of have a line inside for each partner to eventually contribute $30 million of annual in contribution margin.
I'm not sure how many companies in the US financial ecosystem could have these numbers while they are working with banks in the ability to drive so much revenue and contribution margin from a specific partner. I think as much as the importance is the pace and the speed and the robustness of the process in the same time, the ability to actually have the power to generate from a single onboarding, even if it takes two years or three years, $30, $50, $80 million sometimes of contribution margin in a year, is really the powerful piece about Pagaya that is still underappreciated a bit.
That talks to the question that Sanjay asked about, wait, what's the operational leverage, and is it meant to stay like that? When you have these two pieces together, and you connect the dots about on the one hand side, cost of capital going down that we spoke in this call, and then you have the other piece of the constant ability to add partner, which we spoke on this call, and then you take all of that, and you ask the question of what it means for Pagaya to have, hopefully in the next two to three years, additional 10 to 20 partners that could contribute $10, $20, $30 million each, is a very meaningful, stable, with high-margin business that we are actually after, and the fact that we are becoming that category definer.
We definitely feel the market is going to us, and that we are I'm not saying inflection point, because it's a long journey, but definitely in the right way to achieve our strategic goals.
Sanjiv Das
One one more thing I would like to add, I know we've doubled down a lot on banks, particularly on the personal loan side, but I would say that on the auto side, the fact that we are now very, very significantly engaged with large OEMs is another major shift, which I think will have a similar impact to banks on the personal loan side. The auto boom should continue to happen with the new partners that we are seeing in the network.
Peter Christiansen
Thank you. If I could just squeeze in one more, a couple weeks ago, there was a really interesting article on The Wall Street Journal about banks looking to improve their conversion rates with second-look technology, very very similar describing kind of the business model you guys have built.
Just curious if that has brought more attention to Pagaya, conversations increasing, potential new partner deals, anything of that sort? Thanks.
Gal Krubiner
Pete, funny enough, I don't know if you had the time to read my shareholder letter, but I actually spoke about Jamie there. That's true.
I think The Wall Street Journal article, from our perspective, is what flagging a little bit that the so-called market is moving to us. People do recognize that banks in the US today, specifically consumer banks, could not provide everything that they need to their partners, let it be United Airlines or others, and we see that these type of co-brands and different parts are pushing them to find different solutions.
I think, though, the one thing that is a little bit lost is not a second look or other pieces, it's really about the technology that it has behind to do personal loan, auto loans at scale that we are actually, as part of the fintech so-called progression, have developed for many years the state-of-the-art technology capabilities and funding capabilities that to be able to embed it directly into a major bank without them need to do a lot of work together, it's just the right thing. Banks has a lot of the question of build, partner, or buy, that's the classic partner.
We are seeing that happening, it's being recognized across the United States. It's doubly important for consumer credit type of assets.
It is very technology-driven and integration to AI embedded into all of that, and that's really the thing we're playing on. That's the tailwind that we believe are going to carry this company for the next 10, 15 years to the size that should become.
Peter Christiansen
Appreciate it. Thanks again.
Operator
The next question is from Rayna Kumar from Oppenheimer. Please go ahead.
Guru Sidaarth
Hi, this is Guru on for Rayna, and thanks a lot for taking our question. This was slightly commented on earlier, but if you can maybe just comment on how much additional volume can the current expense base support before investments need to step up?
Where would you prioritize incremental spending, right? Can we continue to expect earnings to keep growing faster than FRLPC here?
Thanks.
Jon Dobres
As Sanjiv mentioned earlier, the operating leverage is a feature of our business model. We can continue to onboard our pipeline in our current asset classes without any acceleration of those costs.
We see that trend continuing.
Operator
The next question is from Hal Goetsch from B. Riley Securities.
Please go ahead.
Hal Goetsch
Hey, thank you. My question is looking at the change in the customer quality, the age of the cars, there was a nice table you have on your note.
Is that the key insight here is that these banks need to offer more loans, they've maybe exited the personal loan market or other markets, and need to get back into it because they need to have those depositor relationships that go with that, and they're worried about losing those? Is that a key insight that you're sharing with us this week?
Sanjiv Das
Yes, Hal, this is Sanjiv. Yes, it is, in fact, the key insight, particularly from the perspective of banks.
As you rightly mentioned, banks doubled down on credit cards and sort of paid less attention to personal loans, are now realizing that personal loans are a critical retention mechanism for their deposit customers, because deposit customers not only take a personal loan elsewhere if it's not available at a bank, they also take that deposit with them when they do that. It's a critical retention tool, and that's a fundamental point that we were trying to make in the table, as well as the fact that we enable banks to grow fee income while they're doing that, which banks who are very focused on growing, particularly growing fee income, find this a very attractive feature of what we offer.
Hal Goetsch
That makes a lot of sense. It seems your partners are doing quite well, your SoFis, your Sezzles, your Allies are doing quite well, and I guess their competitors are noticing.
My next question is, several years ago, you were going with just decline monetization, personal loans. Now you have multiple offerings for each lender, and the pace at which you're onboarding them is picking up.
Are these lenders starting out with the same maybe one offering? Are they able to launch more offers at the same time maybe versus a couple of years ago when new lending partner would only launch with maybe one offering, and now it's more?
Could you share with us this?
Sanjiv Das
The short answer is, sorry, Hal. The short answer is that they are starting with multiple capabilities on day one.
A year ago, we ramped one product at a time. Now when we when we onboarded a customer, we had one product a year a year or so ago.
Now we have all our products embedded in our API when we onboard a an institution. Multiple products are available from day zero, and pretty much that's part of part of the reason why the rate of growth is much faster for these new
Hal Goetsch
partners. Excellent.
Thanks for your time.
Sanjiv Das
Sure. Thank you.
Operator
The next question is from David Scharf from Citizens Capital Markets. Please go ahead.
David Scharf
Hi, good morning. Thanks for taking my questions here.
Hey, first, just quickly, just shifting to the consumer, just curious, have you seen any change in behavior, application flow, kind of basically price elasticity, since you kind of raised the rates, the 100 basis points to personal, 140 to auto? Has there been any change in uptake since those were instituted?
Gal Krubiner
The short answer is no. We think what's happening is two-fold.
One is, when you have that quickly of a move, the others are moving with you. The full market is pricing higher, or at least most of it.
The other piece, as Sanjiv mentioned, that even when you speak about a 100 more basis points, etc., still the US economy is very strong, very robust. Just this morning, the GDP was, in the last quarter, the highest it's been in the last years.
People do have the ability to observe another 100 basis points on a $10,000 loan, or a $20,000 on a car, if they want to have a new car, or have that vacation, or whatsoever. It's in that fact, and usually, I'm the opposite, I'm saying that the things that are being read in the newspaper are not what we actually see in reality, but this time, it's very much in line.
We don't see any higher delinquencies. You should remember that we're talking about very specific type of consumer, which is very strong, like personal loan, $120,000 of an income yearly.
It's a strong borrower that have a strong ability to pay. Even on the auto, we're talking about $88,000 of financial income per year.
In these cohorts, these segments, not at all.
David Scharf
Got it. No, good to hear.
Needed to be asked. Hey, maybe just one one follow-up.
Shifting to AI, on the affiliate optimizer, I don't believe you've provided what mix of revenue that product accounts for, but you have highlighted it as a significant growth driver lately. Do you have any thoughts about how channels might change as lenders have to start marketing to agents as opposed to consumers directly?
As we've talked to some lenders, they've noted that as there's more agentic marketing to agents, that it's possible that maybe the Credit Karmas or the NerdWallets start to get disintermediated. Have you or any of your partners kind of formulated any opinions on how this might play out over the next few years?
Gal Krubiner
That goes a little bit to our strategy. We don't tend to bet on one lender or one flow.
Our strategy is to be everywhere, to everyone. Let's assume we'll be an agent provider that is really rapidly growing, they will need to close loans, too, and we will know and learn how to work with them.
As for now, we don't see a major shift, because at the end of the day, in order to get a loan, you need to have a lender. Since we are on both the personal loan and the auto very well-embedded into these ecosystems, it's less important for us it will come from this channel or the other.
It's just a matter of building that capabilities, which we definitely have the capability and will do so. Actually, you're touching an interesting point of the business model of Pagaya, which is not to say we are better in this or that, and it's just the infrastructure behind lending that is so critical if you're coming through an agent, if you are coming through a Credit Karma, or you're coming through just the organic channels of the website.
David Scharf
Got it. Very helpful.
Thank you, Gal.
Operator
The next question is from Joseph Vafi from Canaccord Genuity. Please go ahead.
Hey,
Joseph Vafi
guys. Good morning.
Great results, great performance, nice to see. Just wondering here, maybe some puts and takes in the model if we do see some more Fed tightening on the interest rate side into early next year, some of the puts and takes there.
Then quickly, as a follow-up, a big onboarding year, should we expect the kind of guidance you've had on the number of partners to onboard for next year to be higher than we saw this year given how much you've done so far? Or is there so much to do on the '26 cohort that it may be harder to onboard more in '27?
Thank you.
Jon Dobres
On rates, and we've talked about this a bunch, but the 2-year Treasury is obviously our benchmark. I think the market's pretty widely expecting further tightening, so that's likely embedded in the rate today.
Again, the actions we've taken to date, moving those APRs higher, we feel provides us with the buffer that we need. Sanjiv, do you want to take the partner play?
Sanjiv Das
Sure. Look, we'd like to keep our guidance the same that we've always had, which is two to four partners a year.
We think that's the right and responsible thing for us to do. We have always, while we're getting very strong demand and we're in very late-stage discussions with a number of our partners, we are not always sort of in control of how long it takes, we'd like to keep it at two to four.
Operator
The next question is from Randy Binner from Texas Capital. Please go ahead.
Randy Binner
Hey, thanks for squeezing me in here. I think I heard this in a prior response, but my question is on credit and how pushing higher APRs through to your target borrowers affects their ability to pay, and have you analyzed how that's impacted borrowers in kind of past interest rate hiking cycles?
Gal Krubiner
We actually touched upon this. We don't see any impact as for now, both from performance, the ability to pay of a 1% more on a $10,000 loan per year is not something that is materially important for someone who earns $120,000.
The short answer, it doesn't and should not impact.
Randy Binner
I guess, just giving your past and your data set, is there a level we would think about where that would start to matter more for, again, assuming that you have the $125k, 662 FICO borrower? Is there a level where that gets more sensitive, or that's hard to analyze?
Gal Krubiner
Of course there is some level. I would just say that since we are already at elevated high interest rate, even now, we are at four point at 4%, it's not like we are at zero.
The really way you should think about it is when you're seeing 400, 500, 600 basis points movement, that's could materially impact the ability of consumers to pay. 100 basis points, 50 basis points, 150, these are things that, transmitted over time, are actually not impacting the ability of a borrower to pay.
Randy Binner
Thanks. Appreciate it.
Gal Krubiner
Thank you.
Operator
There are no further questions at this time. I'd like to turn the floor back over to Gal Krubiner for closing comments.
Gal Krubiner
Thank you very much, everyone, for joining us today. As you can see, we are continue to progress on our strategic initiatives of reducing cost of capital, onboarding more partners to our network, and driving towards a stable and long-term vision for our company.
We appreciate all the support throughout the year, and looking forward to see you in the first earnings in 2027. Thank you very much.
Operator
This concludes today's teleconference. You may disconnect your lines at this time.
Thank you for your participation.