Exzeo Group, Inc.
NNYSE:XZOQ4 FY2025 · Earnings Call TranscriptFebruary 25, 2026
Operator
Good afternoon, and welcome to Axio Group's fourth quarter 2025 earnings call. My name is Mark and I will be your conference operator.
At this time, all participants will be in listen-only mode. Before we begin today's call, I would like to remind everyone that this conference call is being broadcast live via webcast and is available for webcast replay approximately 4 hours after the call through February 25, 2027 on the Investor Relations section of Axio Group's website at www.axio.com.
I would now like to turn the call over to Bill Brummel, Vice President of Investor Relations. Bill, please proceed.
Bill Brummel
Thank you, and good afternoon. Welcome to Axio Group's fourth quarter 2025 earnings call.
To access today's webcast, please visit the investor information section of our corporate website at www.axio.com. Before we begin, I would like to take the opportunity to remind our listeners that today's presentation and responses to questions may contain forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995.
Words such as anticipate, estimate, expect, intend, plan, and project, and other similar words and expressions, are intended to signify forward-looking statements. Forward-looking statements are not guarantees of future results and conditions, but rather are subject to various risks and uncertainties.
Some of these risks and uncertainties are identified in the company's filings with the Securities and Exchange Commission. Should any risks or uncertainties develop into actual events, these developments could have material adverse effects on the company's business, financial condition, and results of operation.
Axio Group disclaims all the obligations to update any forward-looking statements. Now with that, I would like to turn the call over to Suela Bolku, Axio's Chief Financial Officer.
Suela Bolku
Thank you, Bill. Good evening, everyone, and thank you for joining us for Axio's fourth quarter earnings call.
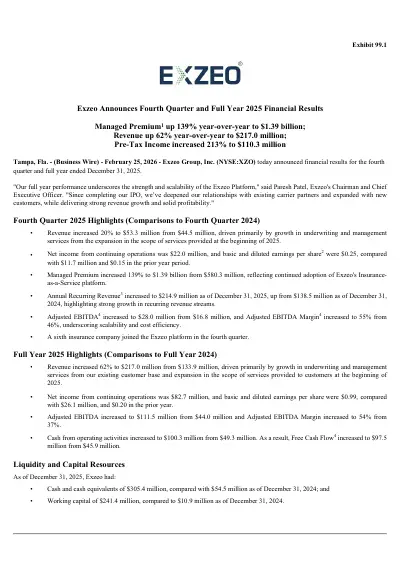
Axio delivered another strong financial performance for the fourth quarter. Pretax income in the quarter was approximately $29 million, and diluted earnings per share were 25 cents.
For the full year, pretax income was over $110 million, and diluted earnings per share were 99 cents. For the fourth quarter, revenue increased to $53 million, and for the full year, increased to $217 million.
We booked the first non-ACI revenue during the quarter, and while the contribution from our two new clients was modest, they are growing and are expected to have managed premium on our platform of approximately $100 million by the end of the first quarter. Our adjusted EBITDA margins increased to over 54% in the fourth quarter and for the full year.
There continues to be significant leverage in our operating model because we can add managed premium with very little incremental expense. I want to highlight a few other KPI metrics.
Managed premium at the end of the fourth quarter were approximately 1.39 billion, ahead of our expectations and up significantly from about $580 million last year. The other KPI metric that I wanted to highlight was our annual recurring revenue, which was $215 million in the fourth quarter, an increase from about $139 million in the prior year quarter.
For the full year 2025, we generated strong free cash flow of about $97 million. With net income of about $83 million, that represents a free cash flow conversion rate of 117%.
Moving to the balance sheet. We ended the year with $305 million cash and cash equivalents, and we continue to have no debt.
Stockholders' equity increased 16-fold to $254 million. Before turning the call over to Kevin, we would like to provide a quick update on guidance and what we're currently expecting for the first quarter and the full year 2026.
Starting with pretax income. We expect pretax income to be between 23 and $26 million for the first quarter.
For the full year 2026, we continue to expect pretax income to be between $115 million and $125 million. Next, managed premium.
We expect managed premium to be over 1.4 billion by the end of the first quarter. Based on current momentum, we are raising our outlook for 2026, and we now expect managed premium to reach 1.55 billion by year-end.
In closing, Axio delivered another strong quarter highlighted by continued growth in managed premium, expanding margins, and a solid debt-free balance sheet supported by a strong cash position. With that, I will hand it over to Kevin, President of Axio.
Kevin Mitchell
Thank you, Suela. As we previously communicated, we laid out goals for 2026.
Let me give you a progress update. First, we wanted to add non-ACI clients to our platform and grow them to a meaningful size.
As Suela highlighted, the two startups added to the platform in the fourth quarter should be approximately 100 million of premium by the end of the first quarter. Second, we issued a press release this evening announcing that Axio has added a new client and a new product to its platform.
The new product is flood, and the new client is Tokio Marine Highland, a wholly owned subsidiary of Tokio Marine Kiln and a member of Tokio Marine Group. They've selected the Axio platform to offer their flood insurance product, and we've already added our first policy.
Third, we are taking an important step to widen our sales funnel with prospective clients. This includes the recent hiring of a seasoned industry executive with a tremendous amount of experience in software sales.
Overall, Axio is heading in a positive direction. Next, I want to take a few minutes to give our view on the approaching inflection point of AI in the insurance industry and why we think it will be positive for Axio.
Much of the insurance industry still relies on human underwriters to manually review and touch nearly every policy. In an AI-driven world, that is going to change.
Friction will come out of the system. We saw years ago that the industry would eventually be moving towards a fully automated insurance platform where policies are bound in minutes and administered with little to no human intervention, which is what Axio currently does today.
What is clear is that the technology bar is being raised. We believe the rise of AI will drive a new upgrade supercycle that will be difficult to avoid.
The end result will be a modernized platform that reduces human touch per policy, lowers operating costs, and delivers better underwriting performance. The debates of how to navigate these upgrades will be a major topic.
It will cause a rethink of how insurance is done and what tools or platforms to use. The Axio platform was built to deliver the solution.
It is a modern, fully automated insurance platform that scales efficiently with our clients' growth. We offer our clients shorter implementation cycles, as demonstrated by the speed at which new clients are already operational on the platform, a consumption-based fee model eliminating large upfront costs and directly aligning Axio's economics with our clients' growth, and reduced execution risk, providing a streamlined on-ramp to the future.
In short, this industry inflection point has the potential to serve as a meaningful catalyst, accelerating our ability to achieve and potentially exceed the strategic objectives we outlined during our IPO process. Now I'll turn the call over to Paresh, Axio's Chief Executive Officer.
Paresh Patel
Thanks, Kevin. Now that we are a few months removed from our IPO, several things are evident.
As Suela highlighted, Axio is delivering strong operating margins, growing earnings, and generating meaningful positive cash flow. On the operational side, as Kevin discussed, we are growing managed premium, broadening our product offerings, signing new third-party clients, and investing in the team needed to capture additional market shares in the years ahead.
With all that said, what excites me the most is with AI, the future operating model of the insurance industry will be different, and Axio was designed specifically for that future. Our focus now is on execution, including adding more clients, products, and premium to the platform.
With that, I'll turn the call over for questions.
Operator
Thank you. Our first question will come from Terry Tillman with Truist Securities.
Terry, please go ahead.
Terry Tillman
Thanks. Hey Paresh, Kevin, Suela, and Bill.
Congratulations on the results in the quarter. I had a couple questions.
First one, and hopefully you can hear me okay, I wanted to ask about the entry into the flood market with Tokio Marine. It's a very large company.
Anything you can share at all though about the level of aggression in terms of how quickly that business could build and how important that is to their future, because just trying to figure out how that might ramp. Is this a signal that you could be doing more in flood near term or do you want to just start here?
Then I had a couple of follow-ups.
Paresh Patel
Terry, the biggest thing about this is that we have a previous relationship with them. How quickly this deal came together, and we've already issued our first policy, having said that, we've got here so fast, we haven't really had the time to think about what the future may bring and how many places we can go with this thing.
What we do know is Tokio Marine is licensed to sell the product in 42 states, right? This instantly expands the scope and reach of what we can do with the Axio platform, right?
Kevin Mitchell
Hey Terry, this is Kevin. What excites us with Tokio Marine is they have a long history in flood.
Very established, they know the business quite well, and being able to partner with someone that has that type of credibility, we think is a true positive. As Paresh mentioned, the speed at which our technology can partner with them is pretty impressive.
They were excited of how quickly we could get to market.
Terry Tillman
That's great to hear. I guess just two more quick questions.
The next one is, that sounds strong in terms of just the two two newer carriers to be $100 million of premium, if I got that right, in the first quarter. That's pretty sizable, pretty quick.
I want to ask a question beyond that, because it's like, well, what is the next kind of stacking up of customers, because people always want to see more. I think, Paresh, you said on the last call that the pipeline had tripled in 5 weeks post the IPO.
Sounds like you've got a seasoned sales leader. What could you share a little bit more about the go-to-market activity?
You've been a public company for even longer. Just some commentary about how you see the funnel developing.
Then I had a one last one for Suela. Thank you.
Paresh Patel
Yeah. Absolutely.
Look, Terry, the funnel is developing very well. Some relationships take a little bit longer to onboard and others happen very quickly.
Tokio Marine, obviously, was a very quick one, but others may take a little bit longer because various other things get in the way. What we see is that opportunity is sort of growing.
Why I say that is some of the prepared comments that we made about instead of having to try to win customers and convince them that Axio was the way to go, with the advent of AI, I think more people are looking to see what's the future and how quickly can we get there. Now think about what we just did in the last 4 months.
We've onboarded three new customers. They already have premium on the platform, right?
Imagine how fast that world is moving compared to an industry where typical software implementations are 12 to 14 months, and that's for only part of this stuff, right? What we sort of set out to do, it's now happening in real time, and ironically enough, more people are looking for it.
Lots of conversations going on. We are also trying to be respectful of how we do this so that we don't really take credit for any conversations until it actually turns into premium on the platform.
Terry Tillman
Yep. Makes sense.
Understood. Last question for Suela is the free cash flow conversion is impressive being well over 100%.
Could you share any perspective, I know we have the pretax income guideposts for '26, which you maintained. Any commentary around that outperformance in four 4Q or the strength in 4Q, and how you think about free cash flow conversion for all of '26?
Thanks.
Suela Bolku
We expect the free cash flow conversion to continue to be over 100%, and that's primarily driven by the growth that we expect. I know I've mentioned this before, but we have a positive working capital cycle where we actually get paid cash upfront from our customers and it takes us over 12 months to recognize revenue.
Since we're growing in 2026, we expect the free cash flow conversion to continue to be over 100%.
Terry Tillman
Thank you.
Suela Bolku
Sure.
Operator
Our next question will come from Dylan Becker with William Blair. Dylan, please go ahead.
Dylan Becker
Hey everyone. Really nice job here.
Maybe it's kind of been hinted at, but for Kevin or Paresh, would love your guys's perspectives on kind of what the evolution of the insurance model looks like, kind facilitated by AI. If you could kind of dive into the proprietary data set, kind of how that positions you guys to be that differentiated kind of provider here, and maybe the impetus having accelerated from an adoption perspective from an end consumer just due to the fact that the market's normalizing, rates are becoming a little bit more competitive, and they need to get a little bit more granular in what they're underwriting.
Thoughts there would be really appreciated. Thank you.
Kevin Mitchell
Sure. Hey Dylan, this is Kevin.
On the first part, when you talk about data sets, I think you're well-versed in this. We've been on a journey here at Axio.
This started back in 2012. In early days when we started building the platform, there weren't data sets to purchase, we built our own, and that gave us a distinct competitive advantage in the market, we knew how to source it, curate it, and make sure that it was accurate so we could make these key underwriting decisions for our clients.
I think that has been really key when you look at some of our clients' performance over the last few years, or outperformance. We think a major element of that is the tech and the curated data sets that Axio is able to provide.
Then on customers and where they live and what they expect, everyone is in a position these days where they're very used to kind of instant and making things simple and easy and reducing friction. I think one of the big things that Paresh has talked about in the past is we set up Axio so it's automated.
All steps of the process, whether it's quote to bind, to the underwriting, to the customer service, even to the claims element, it's critically important that you automate all those steps. There's not a kink in the hose, to speak.
If you can do all those key pieces, you're going to drive incredible efficiency for your insurance carrier client. It's a better customer experience, the agents love you, and it really allows our clients to level up and compete regardless of whatever market they might find themselves in.
Dylan Becker
Very helpful. Thanks, Kevin.
Maybe for Suela, could you kind of remind us as well, too, and great to see kind of the uplift to the expected premium outlook for 2026 here, but how that kind of flows through the seasonality of premiums coming online, how that converts to kind of revenue and ARR, and maybe how that also gives conviction in the sustainability of the profitability profile, as well too relative to kind of that margin expansion trajectory we've called out in the past as well. Thank you.
Suela Bolku
Very good question. Dylan, the timing of the ramp that we expect for 2026 will vary, but I would think of the ramp being a little bit more back-end loaded.
The timing will obviously matter, and as managed premium will be added to the platform, it will increase the annual recurring revenue based on the contractual fees or the take rate. Then from a revenue recognition standpoint, just a reminder that a portion of our revenue gets recognized upfront, is about a quarter of our revenue is recognized upfront, and the remainder earned over the 12 month premium period.
I would just say that it all depends on the timing of the ramp and the timing when the managed premium joins our platform.
Paresh Patel
Yeah. Dylan, I think part of the whole thing about the predictions of this is that you could appreciate Suela trying to assimilate the inputs from at this point seven different carriers
Suela Bolku
and
Paresh Patel
whatever their growth plans and expansion plans are and trying to use that to predict where Axio will be, right? That's why the answer is a little bit less defined than you would normally expect because, and that's going to be more the case.
Actually, we're in that weird situation where if you have seven people, it's difficult to predict things. If you had one, it's easy.
If you have seven, it's difficult. If you have 70, you can take an average and you'll get there.
We're in that in-between transition where the ramping and stuff is very difficult to tell because it's kind of lumpy, yeah?
Dylan Becker
No, that's perfect. Thank you, Suela.
Thank you, Paresh. Really appreciate it.
Operator
At this time, if you would like to ask a question, just press star followed by the number one on your telephone keypad. Our next question will come from Matt Carletti with Citizens.
Matt, please go ahead.
Matt Carletti
Hey, thanks. Good afternoon.
Couple of my questions were answered. I just have a couple numbers ones probably for Suela.
Can you help me with the 1.39 billion managed premiums for the year, I know it's a small number, but how about the starting point for third-party? I heard your guidance on Q1 where you expect Q1 to end, but just I know there was some put on the platform in Q4.
Can you help us with where that was at year-end?
Suela Bolku
I can just say that was pretty modest, and as both Kevin and I mentioned, we expect that to be material by the end of the first quarter. Percentage-wise will be increasing.
Paresh Patel
Matt, I think the biggest thing we would like to hope everybody to note is third-party revenue on the platform was zero at end of Q3. It was nominal at the end of Q4, and it's going to be 100 million approximately end of Q1.
Just illustrates because there were some concerns about adding third-party business. Those are numbers.
Matt Carletti
Perfect. That's helpful.
Then just one at Suela, I hate to ask you to repeat yourself, but I was in transit, I had to get through security, I think, when you said it. The pretax net income guide just for Q1, I got the year, was it 23 to 25 or did I mishear you?
Suela Bolku
23
Matt Carletti
to 26. 23, 26.
Wonderful. All right, thank you very much.
Appreciate it.
Operator
At this time, this includes our question and answer session. I would now like to turn the call back over to Paresh Patel, who has a few closing remarks.
Paresh Patel
I want to thank everyone who joined the call today, and I want to thank the Axio team for all their hard work. Before we wrap up, I want to quickly mention that the Rule 10b5-1 pre-arranged purchase plan that I highlighted last quarter for myself will be effective next month.
I want to thank everyone for their time today. Thank you.
Operator
This concludes today's call. You may now disconnect.